
 Aircraft Exterior Strip and Repaint Services Market | 2026-2036
Aircraft Exterior Strip and Repaint Services Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Exterior Strip and Repaint Services Market Insights
Chrome-based pretreatments are recalibrating product economics as stricter environmental limits push shops toward trivalent chromium and zirconium-based alternatives. Satys leverages its European MRO network to sustain high-throughput strip-and-repaint capacity for narrow-body fleets. Dean Baldwin Painting anchors its position through geographic dominance across multiple US service locations. Duncan Aviation differentiates by specializing in business aviation completions that integrate strip, repaint, and interior refurbishment workflows.
Aircraft exterior strip and repaint services encompass the complete removal of existing coatings through chemical or mechanical methods, followed by surface preparation, corrosion treatment, and reapplication of polyurethane or epoxy-based topcoat systems typically specified to 3-6 mil dry film thickness for optimal aerodynamic performance and UV protection. Commercial airliners command the largest project scale segment as deferred retirements extend heavy maintenance intervals, while private jets generate premium margin pools due to custom livery complexity and shorter turnaround requirements. Corrosion treatment within the service type dimension is gaining structural importance as aging aluminum airframes face intensified inspection mandates.
The FAA enforces VOC limits under 40 CFR Part 63 Subpart GG that directly shape coating selection and booth filtration investments, while EASA's REACH-aligned substance restrictions constrain hexavalent chromium use across European maintenance facilities. Military operators face additional compliance layers through MIL-PRF-85285 performance specifications that govern coating durability on tactical aircraft. Stakeholders must monitor evolving substance bans and certification reciprocity agreements between regulators to anticipate where compliance-driven strip-and-repaint demand will concentrate next.
Market Dynamics
Deferred new aircraft deliveries are compressing fleet replacement cycles, forcing operators to extend airframe service life through intensive strip-and-repaint maintenance. This structural pressure concentrates demand on MRO facilities capable of high-throughput coating removal and compliant reapplication.
Growth Catalysts
- FAA VOC limits under 40 CFR Part 63 Subpart GG:Aerospace coating shops face mandatory filtration and solvent recovery investments that accelerate compliant strip-and-repaint cycle frequency across US-based fleets.
- Aluminum airframe corrosion protocols:Aging commercial fleets intensify inspection mandates for fuselage skin integrity, routing more aircraft into scheduled heavy maintenance events.
- Polyurethane topcoat systems:Advanced UV-resistant formulations with 3-6 mil dry film thickness specifications extend coating durability while reducing turnaround intervals between full strip cycles.
Market Restraints
- Hexavalent chromium phase-out:EASA REACH-aligned substance restrictions constrain pretreatment chemistry options, forcing European facilities toward unproven zirconium-based alternatives with higher unit costs.
- Specialized booth infrastructure:VOC-compliant spray enclosures require seven-figure capital commitments that exclude smaller independent operators from contract eligibility.
- Skilled applicator scarcity:Certified coating technicians with MIL-PRF-85285 specification training command premium wages that compress shop margin structures.
Strategic Opportunities
- Trivalent chromium transition:First-mover shops capturing EPA and EASA-aligned pretreatment certifications secure preferred vendor status with sustainability-focused fleet operators.
- Business aviation completions integration:Bundled strip-repaint-interior workflows capture premium pricing from private jet owners demanding compressed single-point turnaround.
- Chemical-mechanical hybrid stripping:Automated coating removal systems paired with precision solvent application reduce labor hours and environmental exposure liability.
Industry Challenges
- Cross-regulatory certification reciprocity gaps:FAA-approved coating systems lack automatic EASA recognition, forcing dual qualification costs for shops serving international carriers.
- Legacy fleet documentation fragmentation:Incomplete maintenance histories for aging aircraft complicate corrosion assessment and warranty claim substantiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Exterior Strip and Repaint Services Market |
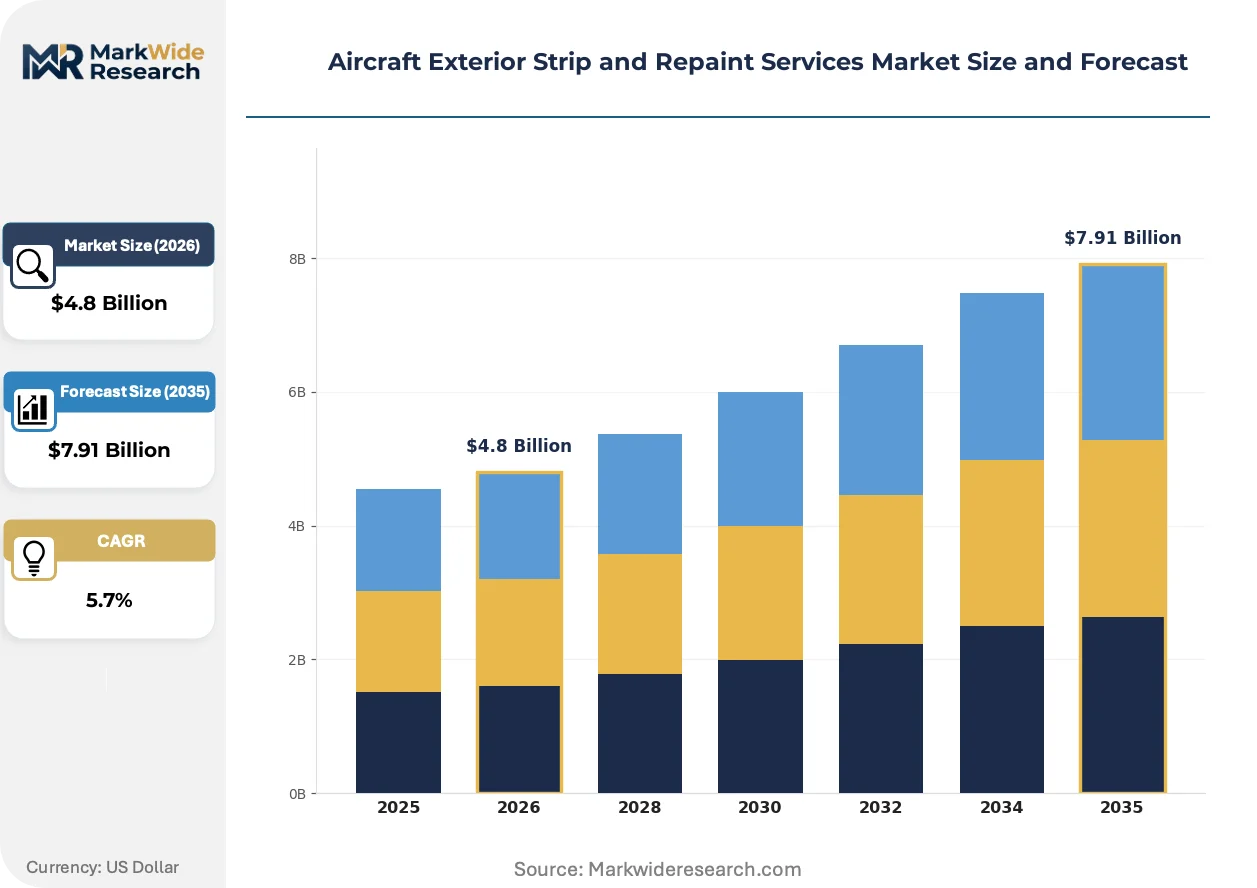
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
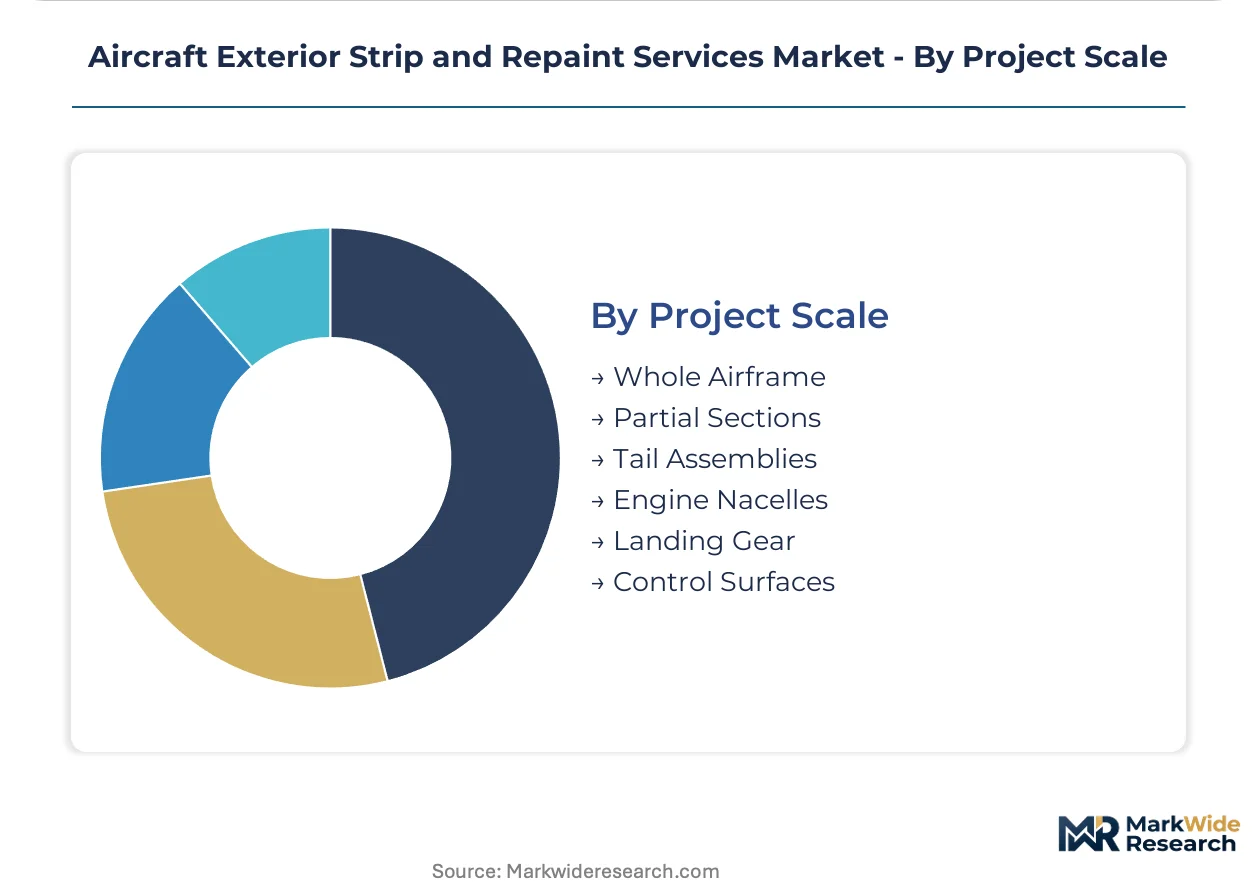
| Segmentation | Service Type: Paint Removal, Surface Preparation, Corrosion Treatment, Repainting, Finishing, Inspection Aircraft Type: Commercial Airliners, Private Jets, Cargo Aircraft, Helicopters, Military Planes, Amphibious Aircraft End User: Airlines, Charter Operators, Leasing Companies, Maintenance Repair Organizations, Military Operators, Aircraft Manufacturers Project Scale: Whole Airframe, Partial Sections, Tail Assemblies, Engine Nacelles, Landing Gear, Control Surfaces |
| Companies Covered | International Aerospace Coatings, Satys, MAAS Aviation, Duncan Aviation, Dean Baldwin Painting, General Atomics AeroTec Systems, Gameco, Air Works, New United Goderich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Exterior Strip and Repaint Services Market Trends and Innovations
Coating removal and reapplication workflows are converging with digital inspection and automated surface preparation technologies. These shifts compress project timelines while tightening compliance documentation.
Robotic abrasive blasting systems are integrating precision nozzle control with real-time substrate monitoring to eliminate manual sanding variability. Narrow-body fleet operators at high-volume US MRO facilities adopt these units to sustain 21-day turnaround commitments. The technology is integrating quality assurance directly into the stripping phase, reducing rework rates and booth occupancy time.
REACH substance restrictions are recalibrating European coating supply chains toward pre-registered zirconium and trivalent chromium pretreatments. Shops in Germany and France face reformulation costs that favor larger network operators with captive chemical engineering resources. Business aviation specialists respond by consolidating specification approvals across EASA and FAA jurisdictions.
Airline procurement teams are unbundling heavy maintenance contracts to separate strip-and-repaint scope from airframe checks. Low-cost carriers in the United States now solicit standalone painting bids through digital tender platforms that transparently benchmark booth rates and material surcharges. This transparency compresses incumbent vendor margins while rewarding shops with documented VOC compliance audit trails.
Aircraft Exterior Strip and Repaint Services Market Segmentation

Segmentation in aircraft exterior strip and repaint services reveals how certification requirements, turnaround constraints, and airframe complexity fragment demand across distinct service tiers. Each dimension carries unique regulatory burdens that shape vendor qualification and pricing power.
Service Type:
Paint removal and corrosion treatment demand FAA-certified booth operations under 40 CFR Part 63 Subpart GG, while surface preparation and finishing require MIL-PRF-85285 specification training for military contracts.
- Paint Removal:Chemical and mechanical stripping processes remove existing polyurethane or epoxy coatings down to bare substrate. Airlines operating narrow-body fleets in the United States drive volume through scheduled heavy maintenance intervals, with deferred retirements compressing cycle frequency.
- Corrosion Treatment:Aluminum airframe integrity protocols mandate intensive fuselage skin remediation for aging commercial fleets. Inspection findings from FAA-mandated checks route aircraft into unscheduled strip-and-repaint events, creating demand spikes outside normal maintenance calendars.
- Surface Preparation:Abrasive blasting and solvent cleaning ready substrates for pretreatment adhesion.
- Repainting:Polyurethane topcoat reapplication to 3-6 mil dry film thickness specifications.
- Finishing:Final gloss control and livery detail application for custom schemes.
- Inspection:Digital substrate monitoring and coating thickness verification.
Paint removal sits at the top of the volume ranking, with corrosion treatment climbing the fastest.
Aircraft Type:
Cost tier segmentation separates high-throughput narrow-body operations from premium-margin business aviation completions requiring compressed single-point turnaround.
- Commercial Airliners:Deferred new aircraft deliveries extend fleet life cycles across Boeing 737 and Airbus A320 family operators. Heavy maintenance intervals at US MRO facilities concentrate demand for 21-day strip-and-repaint turnarounds with full VOC compliance documentation.
- Private Jets:Custom livery complexity and shorter downtime windows generate premium pricing pools. Duncan Aviation and Satys capture this tier through bundled interior-exterior completion workflows that justify higher booth rates.
- Cargo Aircraft:Freighter conversions and continued operation of aging wide-body platforms sustain repaint demand.
- Helicopters:Rotorcraft blade and fuselage coatings require specialized fixture infrastructure.
- Military Planes:MIL-PRF-85285 durability specifications govern tactical aircraft coating systems.
- Amphibious Aircraft:Saltwater exposure accelerates corrosion treatment frequency for coastal operators.
Commercial airliners dominate absolute throughput, while private jets deliver the steepest margin expansion trajectory.
End User:
Customer type determines procurement structure, with airlines unbundling heavy maintenance contracts and leasing companies demanding standardized livery compliance across portfolio aircraft.
- Airlines:Low-cost carriers in the United States now solicit standalone painting bids through digital tender platforms. Transparent benchmarking of booth rates and material surcharges compresses incumbent margins while rewarding documented VOC compliance audit trails.
- Leasing Companies:Portfolio standardization requirements and end-of-lease remarketing obligations drive repaint volume. Return conditions mandate fresh coatings that satisfy multiple airline customer specifications, forcing shops to maintain broad approval portfolios.
- Charter Operators:Brand refresh cycles and owner preference changes generate recurring demand.
- Maintenance Repair Organizations:Third-party MROs bundle strip-and-repaint into airframe check packages.
- Military Operators:Defense procurement layers additional compliance through performance specifications.
- Aircraft Manufacturers:New production and delivery defect remediation require completion services.
Airlines command the largest contract values, with leasing companies expanding most quickly as portfolio remarketing intensifies.
Project Scale:
Application scope segments by labor intensity and booth occupancy, from full airframe strip cycles to targeted control surface repairs.
- Whole Airframe:Complete coating removal and reapplication across fuselage, wings, and empennage. Commercial operators deferring retirement decisions in the United States sustain this segment through intensive life-extension maintenance.
- Partial Sections:Fuselage skin panel replacement zones and repair areas requiring localized strip-and-repaint. Damage events and modification integration create demand outside scheduled maintenance calendars.
- Tail Assemblies:Vertical and horizontal stabilizer coating cycles.
- Engine Nacelles:Thrust reverser and cowling refinishing for thermal protection.
- Landing Gear:Strut and door coating restoration for corrosion protection.
- Control Surfaces:Aileron, rudder, and elevator leading edge remediation.
Whole airframe projects anchor facility utilization, with partial sections gaining share fastest as targeted repair protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Wichita MRO corridor anchors North American strip-and-repaint capacity, with legacy fleet density and FAA-certified booth infrastructure sustaining high-throughput operations for deferred retirement cycles across Boeing narrow-body operators.
United States
Commercial airlines operating aging 737 and A320 fleets drive repaint volume through intensive life-extension programs. The FAA enforces VOC limits under 40 CFR Part 63 Subpart GG that mandate filtration investments across coating shops. Dallas-Fort Worth and Miami maintenance clusters concentrate capacity for high-frequency narrow-body turnarounds.
France
Airbus manufacturing proximity and legacy carrier maintenance networks sustain demand for wide-body strip-and-repaint services. EASA REACH-aligned substance restrictions constrain hexavalent chromium pretreatments, forcing Toulouse and Bordeaux facilities toward trivalent chromium certifications.
Germany
Lufthansa Technik's integrated MRO footprint drives specification-setting for corrosion treatment protocols. The country's national environmental regulator enforces strict aerospace coating emissions standards that favor larger network operators with captive chemical engineering resources. Hamburg and Frankfurt clusters lead European adoption of zirconium-based pretreatment alternatives.
United Kingdom
London Gatwick and Manchester maintenance bases serve leasing company portfolio standardization requirements, with end-of-lease remarketing obligations generating fresh coating demand. The UK Civil Aviation Authority maintains reciprocal recognition agreements with FAA certification standards that facilitate cross-Atlantic contract mobility for specialized shops.
Singapore
Seletar Aerospace Park hosts Southeast Asia's highest concentration of business aviation completion centers, with private jet operators demanding compressed single-point turnaround for bundled exterior-interior workflows. The Civil Aviation Authority of Singapore enforces coating compliance standards aligned with EASA frameworks that position the city-state as a regional certification hub.
Aircraft Exterior Strip and Repaint Services Market Competitive Landscape
Capacity expansion dominates the current landscape as MRO networks add VOC-compliant spray enclosures to capture deferred retirement demand. The vendor base separates into three distinct tiers: integrated aviation service conglomerates with captive airline relationships, independent painting specialists operating multi-location US networks, and business aviation completion houses bundling strip-repaint with interior refurbishment. Geographic scale and certification breadth determine contract eligibility for airline procurement teams unbundling heavy maintenance scope.
Within the European network tier, Satys exemplifies high-throughput narrow-body capacity across its continental MRO footprint. Dean Baldwin Painting occupies a position among US-based multi-location specialists serving commercial airline tender platforms. Duncan Aviation anchors the business aviation completion archetype through integrated exterior-interior workflow bundling.
| Leading Market Players |
|---|
| International Aerospace Coatings |
| Satys |
| MAAS Aviation |
| Duncan Aviation |
| Dean Baldwin Painting |
| General Atomics AeroTec Systems |
| Gameco |
| Air Works |
| New United Goderich |
| Others |
Pricing and Supply Chain Analysis
Polyurethane resin feedstock costs cascade through three distinct pricing tiers as VOC-compliant coating formulations absorb reformulation premiums before reaching airline procurement teams. Trivalent chromium pretreatment chemistry spreads the cost burden unevenly across European shops facing REACH-aligned substance restrictions and US facilities adapting to EPA enforcement patterns.
Pricing Analysis
Input-cost pass-through from zirconium-based pretreatment chemistry and MIL-PRF-85285 certified labor pools stratifies project quotes across premium, standard, and economy certification tiers. Price differentiation hinges on EASA-FAA dual qualification status and compressed turnaround guarantees for narrow-body fleets. Pricing pressure stems from digital tender platforms transparently benchmarking booth rates among low-cost carriers. Airlines with unbundled heavy maintenance contracts exhibit highest price sensitivity, while business aviation completion houses serving private jet owners demonstrate lowest sensitivity due to bundled interior-exterior workflows.
Supply Chain Analysis
Certification gating through FAA Part 63 Subpart GG booth approvals and EASA REACH-aligned substance registrations concentrates compliant coating supply in the United States, France, and Germany. Raw material dependencies center on aerospace-grade polyurethane resins, trivalent chromium conversion coatings, and zirconium-based pretreatment alternatives. Single-source vulnerability persists for REACH-registered chemical intermediates facing periodic substance review. Distribution runs through MRO network procurement hubs serving airline heavy maintenance clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft exterior strip and repaint market compounds regulatory compliance obligations into sustained demand as FAA VOC limits under 40 CFR Part 63 Subpart GG force fleet-wide coating cycle acceleration.
For Market Incumbents: To counter margin compression from digital tender transparency, deploy automated chemical-mechanical hybrid stripping systems that reduce labor hours per narrow-body project. Secure trivalent chromium pretreatment certifications ahead of EPA enforcement waves to capture preferred vendor status with sustainability-focused carriers. Expand booth capacity in Dallas-Fort Worth and Miami maintenance clusters where deferred 737 retirements concentrate demand. For New Entrants and Emerging Players: Launch via standalone corrosion treatment specialization targeting aging aluminum airframe protocols outside scheduled maintenance calendars. Penetrate the partial sections segment where targeted repair protocols proliferate faster than whole airframe competition. Pursue EASA-FAA dual qualification as the primary go-to-market credential for leasing company portfolio standardization contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where seven-figure VOC-compliant spray enclosure investments exclude smaller independent operators from airline contract eligibility. Long-term viability favors network operators with captive chemical engineering resources capable of navigating REACH substance review cycles. Acquisition targets include mid-cap specialists with documented compliance audit trails and established relationships with narrow-body fleet operators. Monitor EASA-FAA certification reciprocity negotiations as the signal for cross-Atlantic contract mobility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Trivalent Chromium Certification Investment | EPA-aligned pretreatment approvals secure preferred positioning with sustainability-focused US fleet operators. |
| Automated Stripping System Deployment | Robotic abrasive blasting integration compresses 21-day turnaround commitments for high-volume narrow-body contracts. |
| Dual Jurisdiction Qualification | EASA-FAA reciprocal recognition reduces dual certification costs for shops serving international carrier portfolios. |
| Business Aviation Completion Bundling | Integrated exterior-interior workflows capture premium pricing from private jet owners demanding single-point accountability. |
| Corrosion Treatment Specialization | Aging aluminum airframe protocols generate unscheduled demand spikes outside normal heavy maintenance calendars. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MRO operations directors, airline fleet engineering managers, coating chemists at pretreatment suppliers, and procurement leads at leasing companies with secondary validation. FAA enforcement records under 40 CFR Part 63 Subpart GG, EASA REACH substance registration databases, airline heavy maintenance contract disclosures, and customs data on aerospace coating imports anchored the dataset. Bottom-up project volume estimates triangulated against top-down fleet size and cycle frequency assumptions.
Comparable-period anchoring across historical strip-and-repaint cycle data established baseline utilization rates before modeling forward across the projection horizon. Segmentation dimensions included service type, aircraft category, end-user procurement structure, and project scale tier. CAGRs derived from fleet age distribution shifts and regulatory compliance-driven cycle compression. Forecast inputs incorporated deferred new aircraft delivery schedules and REACH substance restriction phase-out timelines.
Several conditions sit outside the modeled scope, including military coating system specifications governed by MIL-PRF-85285 durability requirements and new production aircraft delivery defect remediation volumes. Forecasts reflect documented assumptions about regulatory enforcement intensity and fleet retirement deferral persistence. A model refresh is warranted upon material change in EASA-FAA certification reciprocity agreements or EPA VOC limit enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market