
 North America Aerosol Cans Market | 2026-2036
North America Aerosol Cans Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aerosol Cans Market Analytics
Asset-light leasing models for can-making equipment is tilting competitive dynamics toward mid-tier brands that previously faced capital barriers. Crown Holdings Inc. leverages its integrated metal supply chain to sustain cost advantages across aluminum aerosol production. Ball Corporation anchors North American capacity through large-scale manufacturing plants in Colorado and Ohio. Trivium Packaging competes via specialized shaping and decoration capabilities that serve premium personal care clients.
Aerosol cans are sealed pressurized containers typically fabricated from aluminum or steel, designed to dispense products through a valve system using liquefied or compressed gas propellants. These containers must withstand internal pressures ranging from 90 to 180 psi while maintaining chemical compatibility with diverse formulations, serving industries from cosmetics to automotive maintenance. Aluminum dominates product type demand due to its lightweight properties and infinite recyclability, though steel persists in industrial paints where puncture resistance matters. Personal care applications command the largest volume share, while cleaning products represent the fastest-growing application segment as household disinfectant formats proliferate.
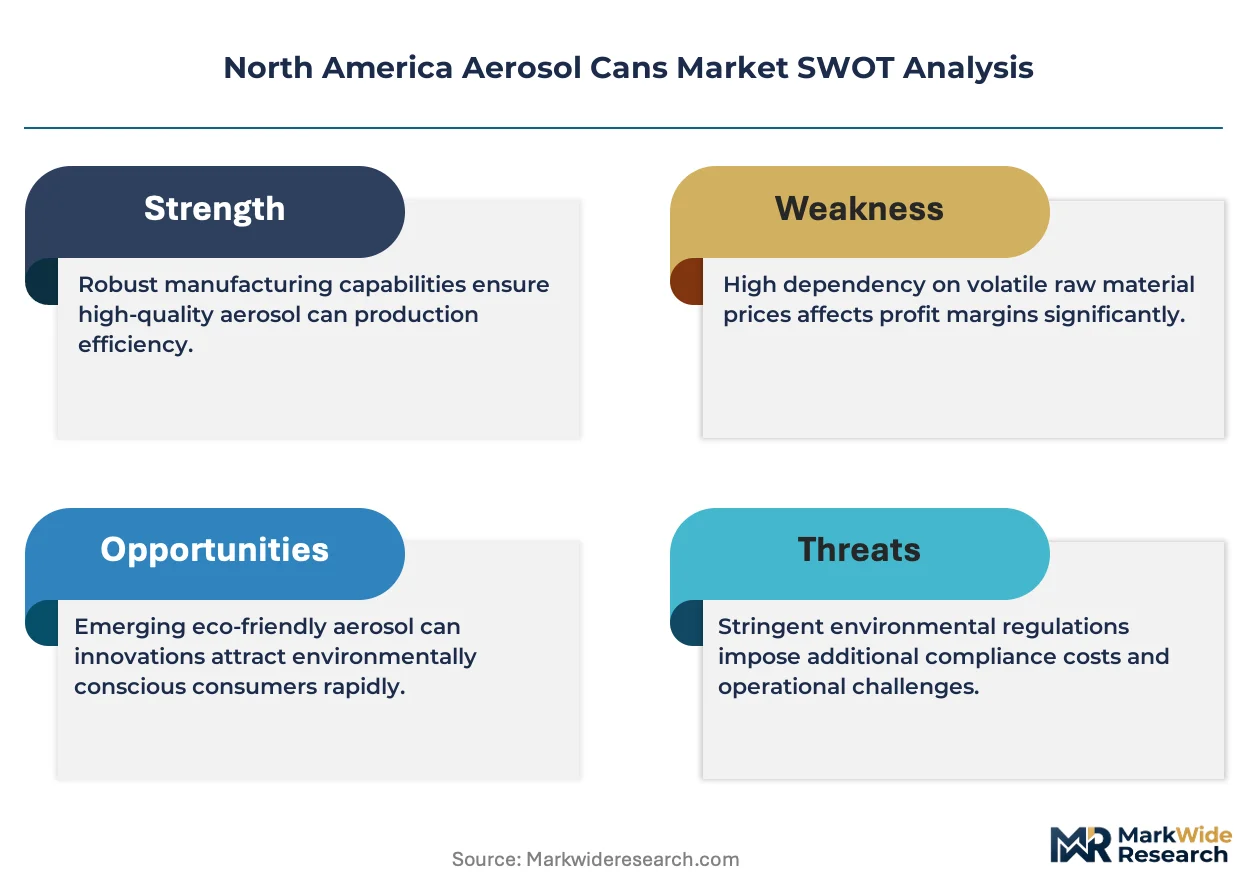
EPA regulations under the Clean Air Act limit volatile organic compound content in consumer aerosols, directly constraining propellant selection and reformulation cycles across US manufacturing. California Air Resources Board rules extend these constraints with state-specific lower thresholds, forcing multi-jurisdictional compliance strategies. Health Canada and PMRA oversee parallel standards for aerosolized pesticides and sanitizers in the Canadian market. Stakeholders must monitor evolving state-level preemption debates and propellant transition timelines to align capacity investments with regulatory trajectories.
Market Dynamics
EPA volatile organic compound rules under the Clean Air Act are forcing propellant reformulation across US manufacturing, compressing product development cycles while creating compliance-driven procurement advantages for integrated suppliers.
Growth Catalysts
- California Air Resources Board thresholds:State-level VOC limits stricter than federal baselines accelerate demand for low-emission propellant technologies and premium compliant formulations.
- Household disinfectant formats:Cleaning product aerosolization is expanding can volumes faster than personal care, driven by institutional sanitation protocols and residential hygiene habits.
- Refillable aluminum systems:Personal care brands are piloting reusable can platforms that reduce per-use material intensity and align with extended producer responsibility frameworks.
Market Restraints
- Aluminum ingot price volatility:Primary metal input costs fluctuate with LME pricing and energy surcharges, squeezing converter margins during contract renegotiations.
- Gulf Coast manufacturing corridor concentration:Overreliance on Texas-Louisiana chemical and packaging infrastructure exposes supply chains to hurricane disruption and regional logistics bottlenecks.
- Steel can substitution ceiling:Industrial paint applications resist aluminum conversion due to puncture resistance requirements and legacy filling equipment compatibility.
Strategic Opportunities
- Quebec and Ontario packaging hub expansion:Canadian provincial incentives for green manufacturing are attracting secondary can-making capacity to serve US-Canada cross-border distribution.
- Compressed gas propellant convergence:Nitrogen and compressed air systems combined with bag-on-valve technology open food-grade and sensitive-formulation applications previously closed to hydrocarbon propellants.
- Direct-to-brand ecommerce channels:Specialty aerosol startups are bypassing traditional distributor networks through subscription refill models and DTC personal care platforms.
Industry Challenges
- Propellant chemistry talent scarcity:Formulation chemists with expertise in low-GWP and non-flammable propellant blends command premium compensation and limited geographic mobility.
- Multi-jurisdictional compliance timelines:Simultaneous EPA, CARB, and Health Canada PMRA registration processes extend product launch cycles by 18-24 months for sanitizers and pesticides.
- Legacy steel can line conversion:Retooling Midwest industrial paint facilities for aluminum handling requires capital outlays that mid-tier contract fillers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aerosol Cans Market |
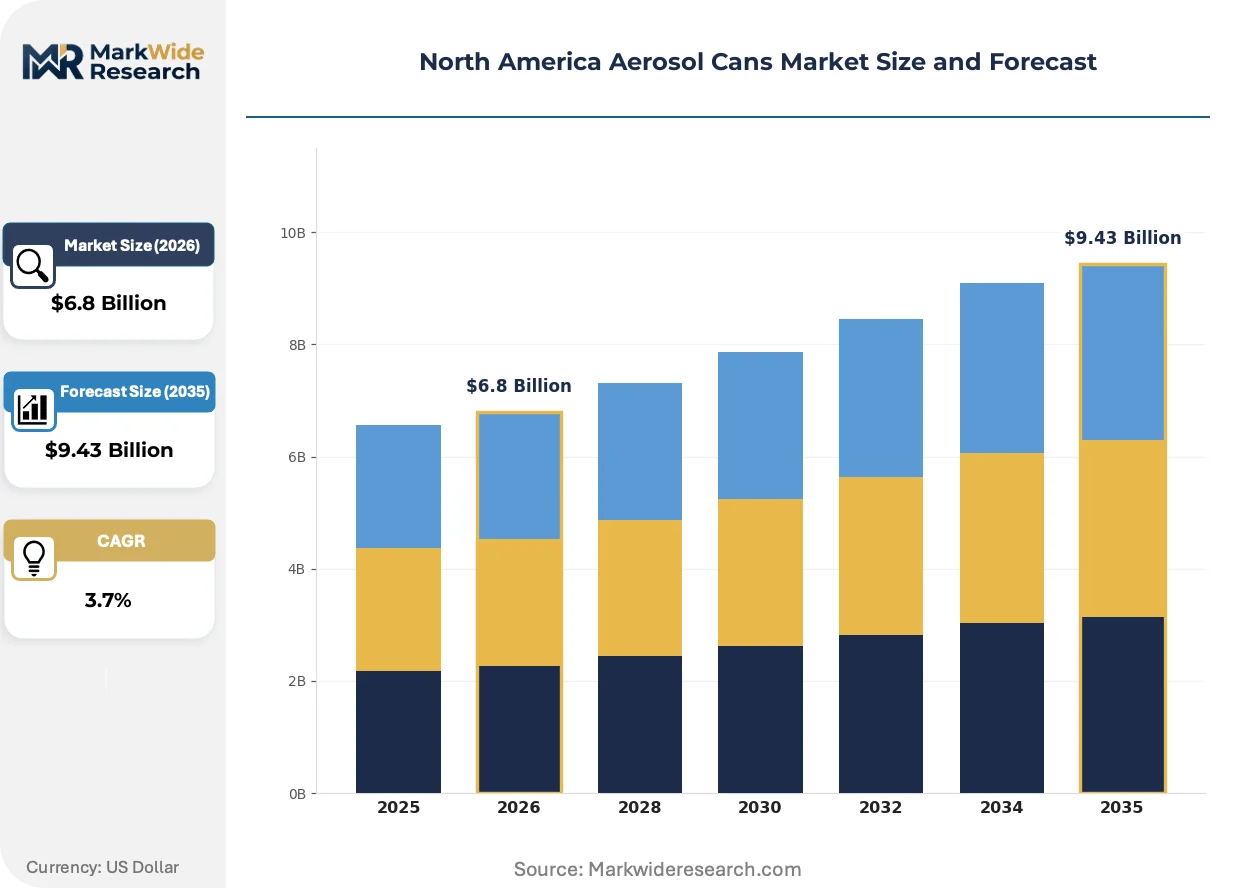
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Plastic, Glass End User: Household, Automotive, Healthcare, Industrial Application: Personal Care, Cleaning Products, Food & Beverage, Paints Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Ball Corporation, Crown Holdings Inc., Ardagh Packaging, CCL Container, Trivium Packaging, Mauser Packaging Solutions, Nampak, Exal Corporation, Silgan Dispensing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aerosol Cans Market Evolving Landscape
Propellant chemistry and container design are converging to address regulatory pressure while opening application categories previously blocked by compatibility constraints. Material science advances and compliance-driven specification changes are reshaping supplier selection criteria.
Bag-on-valve technology separates product from propellant using a laminated film pouch welded to the valve, enabling water-based and sensitive formulations in personal care. Premium skincare and pharmaceutical brands are adopting this format for preservative-free and natural-positioned products. The technology is migrating from niche dermatological applications toward mass-market sun care and hair treatment segments, compressing the addressable market for traditional dip-tube designs.
EPA Significant New Alternatives Policy evaluations are accelerating hydrofluorocarbon phase-down timelines for specific aerosol categories. Industrial solvent and precision cleaner manufacturers face compressed reformulation windows as SNAP rules designate specific substitutes unacceptable. Metalworking and electronics cleaning applications in Michigan and Ohio manufacturing clusters are most affected, with facilities stockpiling legacy formulations while qualifying hydrocarbon and siloxane replacements.
Brand procurement teams are consolidating supplier relationships around vertically integrated converters capable of delivering regulatory documentation, decoration, and logistics from single sources. Mid-tier personal care labels are reducing their qualified vendor lists from six to three partners, prioritizing those with in-house aluminum extrusion and low-VOC propellant blending. This concentration is most visible among California-based clean beauty brands subject to Proposition 65 litigation risk and demanding full material transparency.
North America Aerosol Cans Market Segmentation
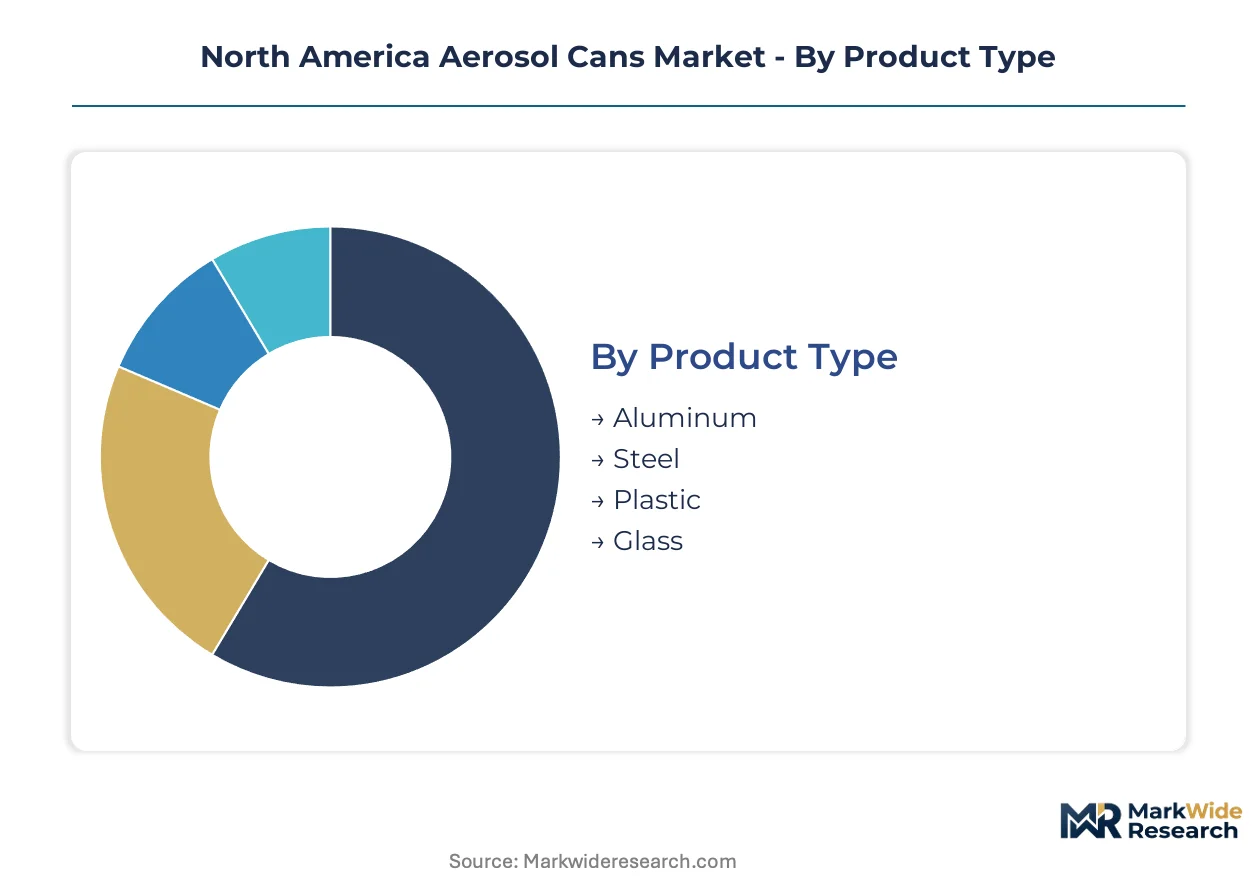
Segmentation reveals how material selection, end-use concentration, and channel strategy fragment competitive positioning across the North American aerosol cans market. Each dimension exposes distinct margin structures and regulatory exposure profiles that shape supplier prioritization.
Product Type:
Material composition spans lightweight consumer formats to puncture-resistant industrial containers, with recyclability mandates and propellant compatibility driving specification divergence.
- Aluminum:Extruded and drawn aluminum dominates personal care and household applications due to infinite recyclability and compatibility with low-VOC propellant systems. Demand concentrates in US Gulf Coast manufacturing corridors serving Texas and Louisiana chemical processing clusters, where integrated converters capture EPA compliance documentation advantages.
- Steel:Tinplate and tin-free steel persist in industrial paints and automotive maintenance products requiring puncture resistance under workshop conditions. Midwest manufacturing clusters in Michigan and Ohio anchor legacy filling infrastructure that resists aluminum conversion due to capital replacement costs and equipment compatibility constraints.
- Plastic:Polymer aerosol systems serve niche pharmaceutical and food-grade applications where metal propellant interaction poses formulation risks.
- Glass:Borosilicate and soda-lime containers address premium fragrance and cosmetic segments demanding visual transparency and chemical inertness.
The dominant share belongs to Aluminum, while Steel is closing the gap fastest through specialized industrial coatings applications.
End User:
Customer-type concentration determines volume scale versus margin intensity, with institutional procurement protocols diverging sharply from retail-driven household demand.
- Household:Residential consumers purchase through retail channels with high frequency and low per-transaction values, driving demand for standardized diameters and mass-market decoration. California Air Resources Board compliance requirements shape propellant selection for this segment more than any other end-use category.
- Automotive:Aftermarket maintenance products require corrosion-resistant interiors and compatibility with hydrocarbon-based brake cleaners and lubricants. Ontario's packaging hub serves cross-border distribution to Michigan and Ohio assembly corridor customers.
- Healthcare:Pharmaceutical aerosols demand FDA-validated manufacturing environments with batch-level traceability and sterilization protocols.
- Industrial:Metalworking and electronics cleaning applications face compressed EPA SNAP reformulation timelines for hydrofluorocarbon phase-down.
Household commands volume leadership, though Healthcare is expanding most quickly through dermatological and respiratory therapeutic launches.
Application:
Use-case diversity stretches from daily-consumption personal care to intermittent industrial maintenance, with formulation sensitivity dictating container specification.
- Personal Care:Deodorants, hair sprays, and shaving foams represent the established volume base, with refillable aluminum platforms piloting among California clean beauty brands seeking extended producer responsibility alignment.
- Cleaning Products:Household disinfectants and institutional sanitizers are expanding can volumes faster than personal care, driven by residential hygiene habits and EPA-registered formulation requirements.
- Food & Beverage:Whipped cream and cooking spray applications require nitrogen propellant systems and FDA-compliant interior coatings.
- Paints:Spray coatings for automotive touch-up and architectural applications favor steel containers with solvent-resistant interior linings.
Personal Care retains the largest installed base, yet Cleaning Products is gaining share fastest through post-pandemic sanitation protocol permanence.
Distribution Channel:
Channel configuration determines packaging lot sizes, decoration complexity, and inventory velocity requirements across the value chain.
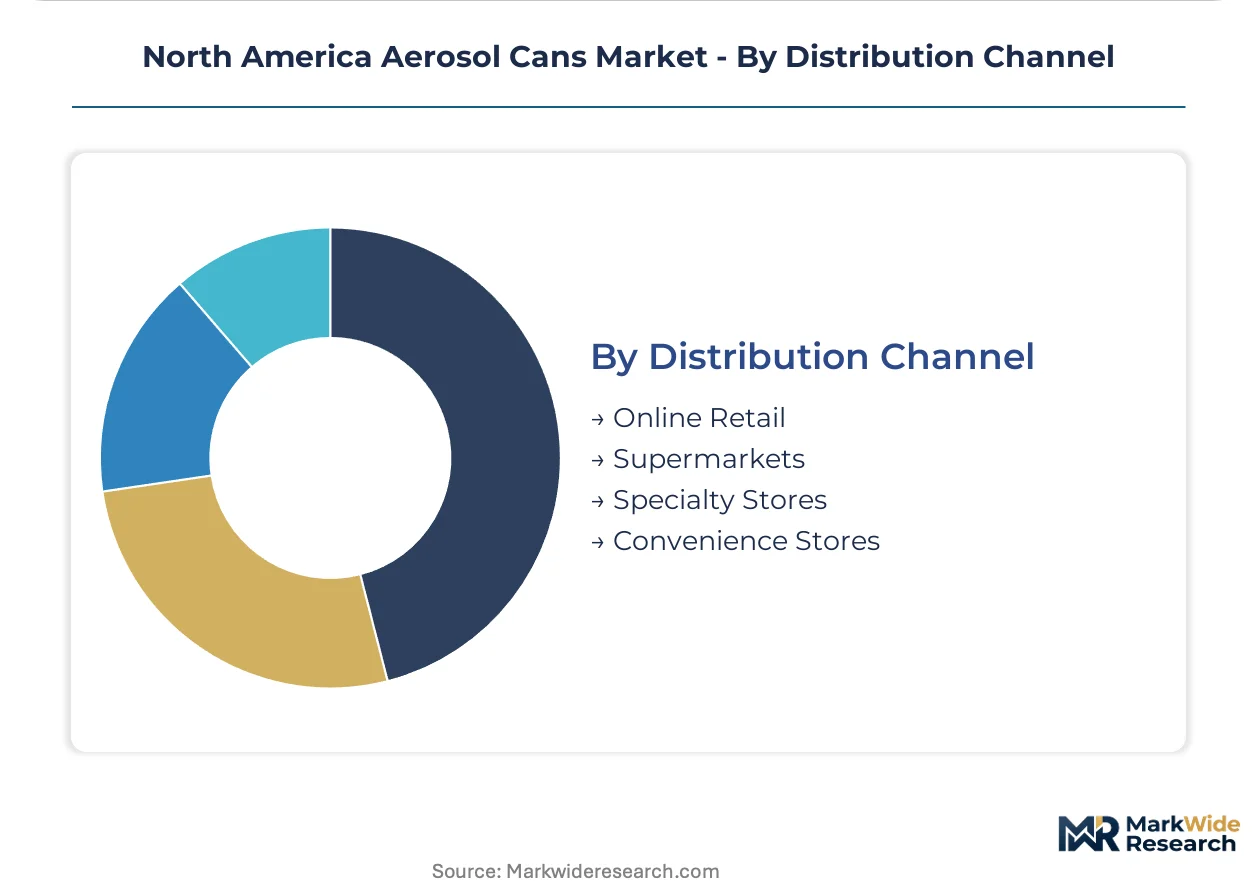
- Online Retail:Direct-to-consumer and third-party marketplace sales require damage-resistant secondary packaging and compact dimensional optimization for parcel logistics. Specialty aerosol startups leverage subscription refill models to bypass traditional distributor networks.
- Supermarkets:Mass merchandisers demand high-velocity SKUs with promotional display compatibility and standardized pallet configurations.
- Specialty Stores:Beauty and automotive retailers specify premium decoration and limited-edition finishes supporting brand positioning.
- Convenience Stores:Impulse-oriented channels prioritize compact can sizes and high-margin travel formats.
Supermarkets maintain the deepest volume penetration, while Online Retail is climbing the fastest through DTC personal care platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the US Gulf Coast manufacturing corridor, while Canadian provincial incentives are eroding traditional cost advantages through cross-border capacity expansion.
United States
Personal care brands pilot refillable aluminum platforms alongside household disinfectant volume expansion. EPA volatile organic compound rules under the Clean Air Act compress propellant reformulation cycles. Texas and Louisiana chemical processing clusters anchor integrated converter operations serving downstream filling facilities.
Canada
Ontario's packaging hub attracts secondary can-making investment through green manufacturing tax credits. Health Canada and PMRA oversee parallel aerosolized pesticide and sanitizer registration processes. Quebec provincial programs support aluminum extrusion capacity serving US-Canada cross-border distribution networks.
Mexico
Maquiladora operations near the US border capture contract filling demand from California clean beauty brands seeking tariff-advantaged production. Mexican environmental regulations align with US EPA frameworks through USMCA coordination mechanisms. Nuevo León industrial parks host packaging converters supplying Texas retail distribution centers.
North America Aerosol Cans Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in propellant chemistry and valve engineering. The North American aerosol cans market structures around three to five vertically integrated converters controlling aluminum extrusion and decoration capacity, while mid-tier contract fillers compete on formulation flexibility. Two strategic archetypes dominate: integrated metal suppliers with captive aluminum supply chains, and specialized decorators serving premium personal care positioning. Capacity expansion and regulatory compliance documentation consolidation represent the dominant competitive moves.
Within the integrated converter tier, Crown Holdings Inc. and Ball Corporation exemplify scale-driven platform control, while Trivium Packaging occupies a position emphasizing specialized shaping capabilities. Crown Holdings Inc. represents the vertically integrated archetype through metal supply chain control. Ball Corporation anchors large-scale manufacturing presence across Colorado and Ohio production nodes. Trivium Packaging exemplifies the premium-specialist positioning through decoration and forming expertise serving clean beauty brand procurement consolidation.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings Inc. |
| Ardagh Packaging |
| CCL Container |
| Trivium Packaging |
| Mauser Packaging Solutions |
| Nampak |
| Exal Corporation |
| Silgan Dispensing Systems |
| Others |
Value Network & Pricing Analysis
Undercapacity in Ontario's aluminum extrusion sector is tightening converter margins while amplifying pricing leverage for integrated suppliers with captive metal supply. This utilization dynamic rewards Crown Holdings and Ball Corporation with cost pass-through advantages, while mid-tier contract fillers absorb compressed spreads between standardized commodity cans and configured-to-order premium formats.
Pricing Analysis
The customization-premium spread separates standard aluminum aerosol cans from configured-to-order formats with specialized shaping, decoration, and low-VOC propellant compatibility documentation. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by EPA compliance tier, volume scale, and decoration complexity. Pricing pressure stems from aluminum ingot cost volatility transmitted through LME pricing mechanisms, squeezing converter margins during contract renegotiations. Private-label household brands exhibit highest price sensitivity, while California clean beauty labels prioritize full material transparency over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration in the US Gulf Coast corridor and Ontario's packaging hub anchors North American can-making capacity. Supply draws from primary aluminum smelters in Quebec, steel tinplate producers in Ohio, and propellant chemical processors in Texas and Louisiana. Single-source vulnerability concentrates around hurricane exposure to Texas-Louisiana chemical infrastructure. Distribution runs through mass merchandiser DC networks, cross-border Canadian-US logistics channels, and emerging direct-to-consumer parcel fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions. EPA and CARB compliance documentation requirements create switching costs that lock brand relationships and deter new converter entry.
For Market Incumbents: Entrench market position through backward integration into aluminum extrusion capacity in Quebec and low-VOC propellant blending capabilities. Add secondary can-making lines in Ontario to capture green manufacturing tax credits and serve cross-border distribution. Counter the threat of refillable aluminum platform disruption by piloting reusable can systems with California clean beauty brands.
For New Entrants and Emerging Players: Pursue white-space opportunities in compressed gas propellant systems for food-grade and pharmaceutical applications previously closed to hydrocarbon formats. Target the bag-on-valve technology segment serving preservative-free skincare and natural-positioned personal care. Establish go-to-market presence through direct-to-consumer subscription refill models that bypass traditional distributor networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract filling services as asset-light leasing models for can-making equipment reduce entry barriers. Long-term viability favors vertically integrated converters with regulatory documentation capabilities and decoration expertise. Watch for EPA SNAP rule acceleration on hydrofluorocarbon phase-downs as the signal indicating reformulation-driven procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Crown Holdings captures Quebec smelter proximity to secure ingot cost advantages. |
| Low-VOC Propellant Blending Capacity | Integrated converters align with EPA Clean Air Act compliance timelines. |
| Ontario Packaging Hub Expansion | Secondary can-making investment serves US-Canada cross-border distribution networks. |
| Bag-on-Valve Technology Migration | Laminated film pouch systems open preservative-free formulation categories. |
| Direct-to-Consumer Refill Platforms | Subscription models bypass traditional distributor networks for specialty aerosol startups. |
Research Methodology
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings across the North American aerosol cans market. Conversations with plant managers at Gulf Coast converters, procurement leads at California personal care brands, EPA regulatory affairs specialists, and channel sales heads at mass merchandisers combined with bottom-up and top-down triangulation. Secondary validation draws from EPA SNAP program filings, CARB rulemaking dockets, SEC 10-K disclosures from Crown Holdings and Ball Corporation, and Health Canada PMRA registration databases.
Calibration against historical aluminum price cycles and propellant reformulation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, end-use category, application segment, and distribution channel complexity. CAGRs were derived through demand elasticity analysis, capacity utilization trends, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs incorporate LME aluminum pricing volatility bands and EPA enforcement intensity scenarios.
Sensitivities concentrate around aluminum ingot price spikes, hurricane disruption to Gulf Coast chemical infrastructure, and accelerated EPA SNAP phase-down timelines. Forecasts reflect assumptions about regulatory stability and propellant chemistry talent availability. Quarterly review of LME pricing spreads, CARB threshold announcements, and converter capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Global Optical Brighteners Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
Demethylase Inhibitor Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Silver Iodide Market