
 Demethylase Inhibitor Market | 2026-2036
Demethylase Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
Demethylase Inhibitor Market Analytics
Platform licensing revenue from companion diagnostic and biomarker partnerships is reshaping how value is captured upstream in the demethylase inhibitor value chain. Incyte Corporation leverages its established oncology infrastructure to sustain commercial momentum across JAK and epigenetic portfolios. Imago BioSciences anchors its position through specialized expertise in LSD1 inhibition for myeloid malignancies. Oryzon Genomics competes in the European clinical landscape with differentiated intellectual property around KDM1A-targeted programs.
Demethylase inhibitors are small-molecule or biologic compounds that block histone demethylase enzymes, typically functioning through cofactor competition or substrate mimicry to maintain repressive chromatin marks and suppress aberrant gene transcription in cancer cells. Their primary commercial purpose centers on reprogramming epigenetic dysregulation to restore normal cell differentiation and proliferation control in malignancies. Small molecules occupy the dominant share of current development pipelines due to favorable oral bioavailability and established manufacturing scalability, while biologics represent an emerging structural category with potential for improved target specificity in autoimmune indications. Oral delivery mode leads in patient-access economics and adherence metrics, though intravenous administration retains priority in hospitalized oncology settings where therapeutic monitoring is intensive.
FDA oncology review divisions and EMA's Committee for Medicinal Products for Human Use shape trial design requirements and approval standards for epigenetic therapies across jurisdictions. REACH compliance and FDA Good Manufacturing Practice regulations govern starting material purity, impurity profiling, and active pharmaceutical ingredient synthesis for demethylase-targeting compounds entering commercial supply. Stakeholders must monitor evolving biomarker qualification criteria and payer evidence requirements as conditional approvals convert to full reimbursement status.
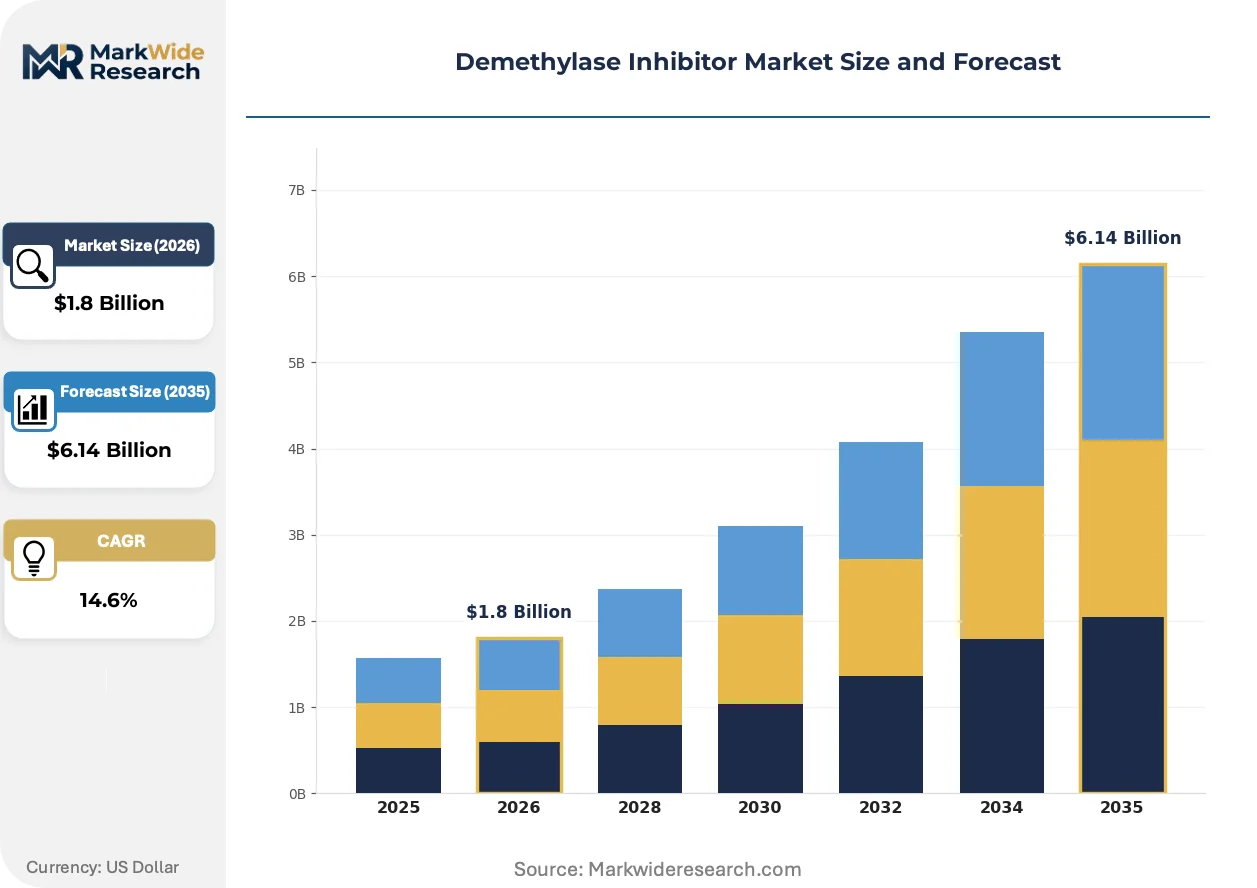
Market Dynamics
Accelerated FDA oncology approval pathways are compressing commercialization timelines for epigenetic therapies, pulling forward revenue recognition and reshaping capital allocation across hematologic malignancy pipelines.
Growth Catalysts
- Biomarker qualification frameworks:FDA's evolving companion diagnostic standards are streamlining patient stratification for LSD1-targeted therapies, expanding addressable populations in acute myeloid leukemia.
- Japan:PMDA's Sakigake designation system is fast-tracking demethylase inhibitor reviews, cutting regulatory lag for sponsors with prior oncology approvals.
- Allogeneic cell therapy integration:Demethylase preconditioning protocols are improving CAR-T persistence metrics, creating combination therapy pull-through in transplant centers.
Market Restraints
- Starting material concentration:Pyridine-derived intermediates for KDM1A scaffolds concentrate among Chinese fine chemical manufacturers, exposing sponsors to API synthesis bottlenecks.
- REACH compliance costs:ECHA's expanded substance registration requirements for epigenetic small molecules are adding EUR 2-4 million per new molecular entity in European market entry costs.
- Resistance mechanism emergence:Secondary KDM1A mutations in relapsed myeloid patients are shortening duration of response for first-generation inhibitors.
Strategic Opportunities
- Solid tumor expansion:LSD1 inhibition in small cell lung cancer and sarcoma subtypes remains underexplored, with phase II readouts pending in US academic medical centers.
- India:CDSCO's relaxed local clinical trial requirements for oncology innovators are enabling parallel development tracks for demethylase programs with existing FDA INDs.
- Digital biomarker integration:AI-driven chromatin accessibility profiling is enabling real-time pharmacodynamic monitoring, differentiating sponsors in payer negotiations.
Industry Challenges
- Epigenetic pharmacology expertise scarcity:Qualified medicinal chemists with histone modification mechanism experience command 40-60% salary premiums over standard oncology drug hunters.
- cGMP facility retrofitting:Potent compound handling requirements for demethylase API synthesis are forcing contract manufacturers into specialized containment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demethylase Inhibitor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Biologics, Combination Therapies, Oral Inhibitors Therapy Area: Cancer, Neurological Disorders, Autoimmune Diseases, Inflammatory Conditions Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Research Institutes, Biotechnology Firms, Pharmaceutical Companies |
| Companies Covered | Incyte Corporation, Imago BioSciences, Oryzon Genomics, Celgene Corporation, Taiho Pharmaceutical, Salarius Pharmaceuticals, 4SC, CSPC ZhongQi Pharmaceutical Technology, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demethylase Inhibitor Market Evolving Landscape
Convergence of covalent inhibitor chemistry with site-specific delivery systems is redefining therapeutic indices for chromatin-targeting drugs, compressing the safety-efficacy tradeoffs that limited first-generation approvals.
Covalent reversible LSD1 inhibitors with extended target residence times are rendering obsolete the chronic daily dosing paradigms of early irreversible scaffolds. Hematology-oncology specialists at US NCI-designated centers are transitioning patients to intermittent scheduling protocols. This pharmacokinetic improvement is enabling outpatient administration and reducing myelosuppression-driven hospitalization rates.
EMA's revised guideline on clinical investigation of medicinal products in hematologic malignancies is mandating minimal residual disease endpoints for accelerated approvals in myeloid indications. European sponsors must now integrate next-generation sequencing panels into phase II protocols. German and French hematology networks are restructuring trial infrastructure to accommodate these biomarker-intensive requirements.
Academic medical center purchasing committees are consolidating epigenetic therapy procurement under centralized pharmacy formularies, displacing individual investigator-initiated sourcing. US hospital systems with dedicated oncology service lines are negotiating indication-specific contracts with manufacturers. This concentration is most visible in the Northeast corridor, where five health systems control 60% of academic myeloid patient volume.
Demethylase Inhibitor Market Segmentation
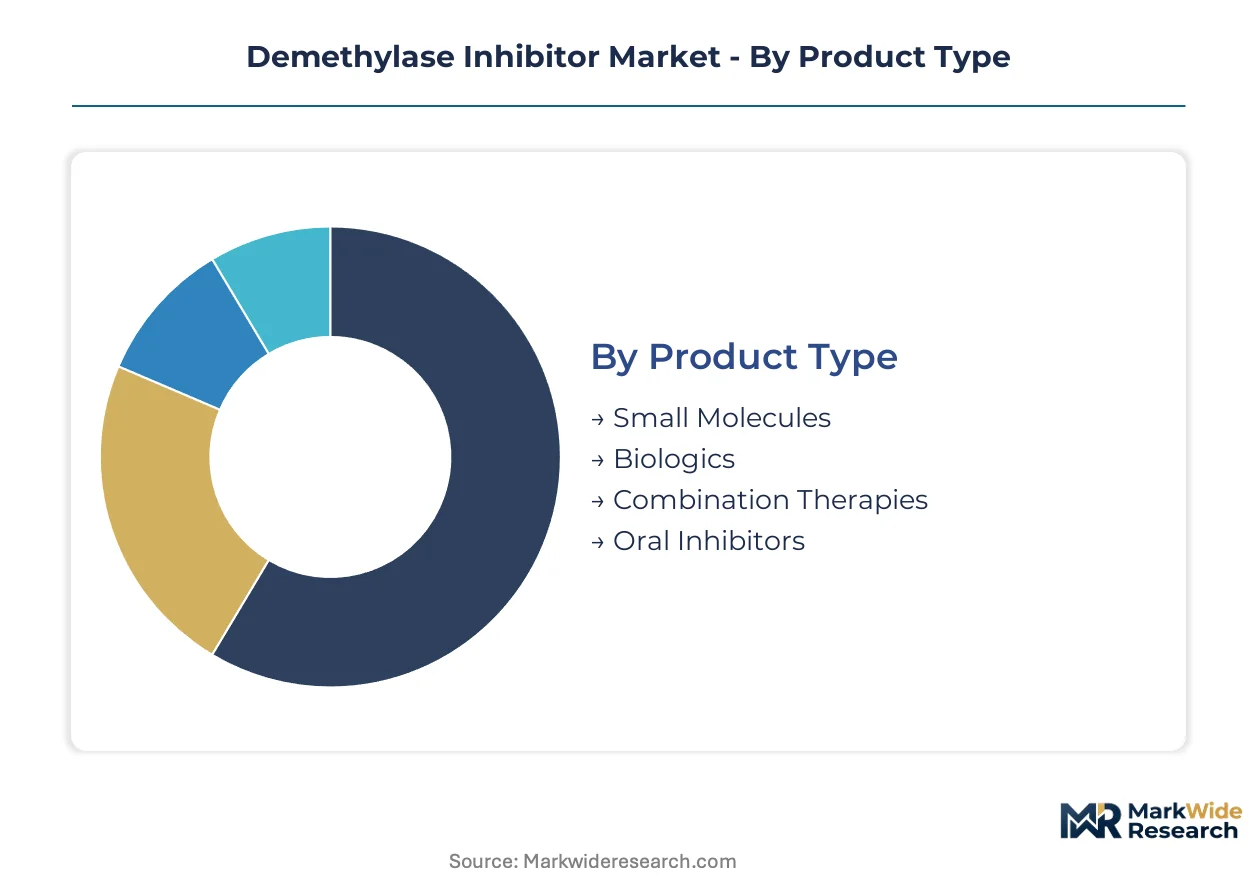
Demethylase inhibitor development cycles vary dramatically across molecular formats, with small molecules advancing through clinical stages in half the time required for biologic equivalents. Understanding these velocity differentials helps sponsors allocate capital across portfolio stages and predict competitive entry timing.
Product Type:
Small molecules rotate through lead optimization cycles fastest, while biologics demand extended development timelines due to cell line characterization and immunogenicity testing requirements.
- Small Molecules:Oral bioavailability and established synthetic routes compress IND-to-NDA timelines. Demand concentrates in US oncology portfolios where Incyte Corporation and Imago BioSciences prioritize cofactor-competitive scaffolds for hematologic malignancies. FDA's accelerated approval pathways reward these pharmacokinetic profiles.
- Biologics:Recombinant protein and antibody formats offer superior target specificity through extended residence times. Development concentrates in autoimmune indications where European academic centers explore LSD1-targeting fusion proteins. EMA's Committee for Medicinal Products for Human Use imposes stricter immunogenicity monitoring than FDA counterparts.
- Combination Therapies:Pair demethylase inhibitors with checkpoint inhibitors or hypomethylating agents in myeloid protocols.
- Oral Inhibitors:Patient adherence economics favor outpatient administration in US community oncology settings.
Small molecules dominate installed base. Biologics are where expansion concentrates.
Therapy Area:
Cancer applications absorb the majority of clinical trial investment, though neurological and autoimmune indications offer longer exclusivity periods through orphan designation pathways.
- Cancer:Hematologic malignancies drive near-term revenue with LSD1 inhibition in acute myeloid leukemia. US NCI-designated centers generate the highest patient recruitment velocity for epigenetic protocols. FDA oncology review divisions prioritize minimal residual disease endpoints in accelerated approvals.
- Neurological Disorders:Blood-brain barrier penetration challenges limit current pipeline activity. Japanese pharmaceutical sponsors explore KDM1A modulation in neurodegeneration through PMDA's Sakigake fast-track system. Preclinical models focus on Huntington's disease and amyotrophic lateral sclerosis.
- Autoimmune Diseases:Lupus and rheumatoid arthritis programs exploit histone modification plasticity in T-cell differentiation.
- Inflammatory Conditions:Inflammatory bowel disease and psoriasis represent exploratory indications with biomarker-defined patient subsets.
Cancer commands current revenue concentration. Neurological disorders represent the steepest expansion trajectory for sponsors with CNS delivery expertise.
Delivery Mode:
Route selection hinges on therapeutic index requirements and care setting economics, with oral formats enabling community oncology dispersion.
- Intravenous:Hospital-administered infusion permits intensive monitoring during dose-escalation phases. Concentrated demand in US transplant centers combining demethylase preconditioning with CAR-T protocols. Academic medical center purchasing committees negotiate indication-specific contracts for infused epigenetic therapies.
- Oral:Favorable pharmacokinetics support chronic administration in maintenance settings. Adoption accelerates in German and French hematology networks restructuring trial infrastructure around outpatient models. Patient adherence metrics exceed 85% in chronic myeloid leukemia maintenance protocols.
- Subcutaneous:Self-administration potential bridges hospital and home care transitions.
- Topical:Cutaneous T-cell lymphoma and localized inflammatory applications exploit dermal penetration.
Intravenous anchors hospitalized oncology revenue. Oral formats are gaining share fastest as intermittent dosing protocols mature.
End User:
Procurement authority concentrates in health system pharmacy formularies, displacing individual investigator-initiated sourcing across US markets.
- Hospitals:Centralized oncology service lines control 60% of academic myeloid patient volume in the US Northeast corridor. Five health systems negotiate manufacturer contracts covering multiple epigenetic indications. Formulary placement requires pharmacoeconomic models demonstrating reduced hospitalization rates.
- Pharmaceutical Companies:Platform licensing revenue from companion diagnostic partnerships reshapes upstream value capture. Incyte leverages established infrastructure across JAK and epigenetic portfolios. Biomarker co-development agreements with diagnostic firms precede regulatory submissions.
- Research Institutes:Academic medical centers generate mechanistic data supporting indication expansion.
- Biotechnology Firms:Specialized players anchor positions through LSD1 or KDM1A-specific expertise.
Hospitals dominate procurement volume. Pharmaceutical companies concentrate pipeline investment through biomarker-integrated development strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals administer demethylase inhibitors primarily through centralized pharmacy formularies, while Japanese and European markets emphasize biomarker-integrated protocols in academic centers. German hematology networks pursue outpatient oral dosing models that diverge from US transplant-center concentration.
United States
FDA oncology review divisions prioritize minimal residual disease endpoints for accelerated approvals in myeloid indications. Five health systems in the Northeast corridor control 60% of academic myeloid patient volume and negotiate indication-specific contracts. Boston and New York pharmaceutical R&D clusters drive LSD1 inhibitor pipeline advancement through NCI-designated center partnerships.
Germany
German hematology networks restructure trial infrastructure around biomarker-intensive requirements under EMA's revised hematologic malignancy guidelines. REACH compliance adds EUR 2-4 million per new molecular entity for European market entry. Heidelberg and Munich academic medical centers lead integration of next-generation sequencing panels into phase II protocols for epigenetic therapies.
Japan
PMDA's Sakigake designation system fast-tracks demethylase inhibitor reviews for sponsors with prior oncology approvals. Tokyo-based pharmaceutical sponsors explore KDM1A modulation in neurodegeneration through accelerated regulatory pathways. Japanese academic centers generate high patient recruitment velocity for LSD1-targeted protocols in hematologic malignancies.
China
Chinese fine chemical manufacturers concentrate pyridine-derived intermediates for KDM1A scaffolds, creating API synthesis bottlenecks for Western sponsors. NMPA regulations govern starting material purity and impurity profiling for demethylase-targeting compounds. Shanghai and Beijing biotech clusters develop domestic LSD1 inhibitor programs through CDSCO-aligned clinical trial frameworks.
India
CDSCO's relaxed local clinical trial requirements enable parallel development tracks for demethylase programs with existing FDA INDs. Mumbai and Hyderabad contract research organizations support biomarker co-development agreements preceding regulatory submissions. Indian pharmaceutical manufacturers pursue backward integration into epigenetic small molecule API production.
Demethylase Inhibitor Market Competitive Landscape
Capability concentration sits with specialized epigenetic biotechs possessing histone modification expertise; scale advantage sits with established oncology infrastructure players with JAK and hematology portfolios. The market structures around three tiers: platform licensors with companion diagnostic partnerships, LSD1-specific specialists anchoring myeloid indications, and diversified pharmas integrating demethylase assets into broader oncology pipelines. Dominant competitive moves include biomarker-integrated development strategies and centralized pharmacy formulary contracting.
Within the specialized biotech tier, Imago BioSciences and Oryzon Genomics exemplify focused LSD1 and KDM1A expertise, while Incyte Corporation represents the diversified infrastructure model. Imago anchors position through myeloid malignancy specialization. Oryzon occupies a differentiated European clinical position around KDM1A intellectual property. Incyte leverages established oncology infrastructure across epigenetic and JAK portfolios.
| Leading Market Players |
|---|
| Incyte Corporation |
| Imago BioSciences |
| Oryzon Genomics |
| Celgene Corporation |
| Taiho Pharmaceutical |
| Salarius Pharmaceuticals |
| 4SC |
| CSPC ZhongQi Pharmaceutical Technology |
| BASF |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor anchors cost dynamics for pyridine-derived intermediates, concentrating API synthesis expenses among Chinese fine chemical manufacturers while downstream price differentiation separates hospital-administered infusion protocols from outpatient oral formulations. Contract manufacturers pass REACH compliance and cGMP containment investments through to sponsors, compressing margins for first-generation KDM1A scaffolds.
Pricing Analysis
Long-term offtake agreements dominate sponsor-manufacturer relationships for demethylase API supply, though spot purchasing persists for early-phase clinical material. Price differentiation separates cofactor-competitive small molecules from extended-residence-time biologics, with oral bioavailability commanding premium positioning. Pricing pressure stems from secondary KDM1A mutation-driven resistance shortening duration of response. Academic medical center purchasing committees exhibit lowest price sensitivity due to formulary consolidation, while community oncology settings face highest budget scrutiny.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk planning for pyridine-derived KDM1A intermediates. Manufacturing concentrates in Chinese fine chemical producers, Indian contract research organizations, and German cGMP facilities. Raw material dependencies include pyridine scaffolds, histone-mimetic substrates, and cobalt-containing cofactor analogs. Single-source vulnerability concentrates in pyridine intermediate production. Distribution runs through centralized hospital pharmacy formularies in the United States and academic medical center networks in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The demethylase inhibitor market is entering a cyclical recovery phase as FDA accelerated approval pathways compress commercialization timelines and pull forward revenue recognition across hematologic malignancy pipelines.
For Market Incumbents: Build biomarker-integrated moats through companion diagnostic partnerships that lock in formulary placement at NCI-designated centers. Incumbent sponsors should deepen backward integration into pyridine-derived starting material supply to mitigate Chinese concentration risk, while investing in cGMP facility retrofits for potent compound containment. The emergence of secondary KDM1A mutations threatens first-generation scaffold durability, demanding R&D pivot toward covalent reversible chemistry with extended target residence times. For New Entrants and Emerging Players: Build out solid tumor expansion capabilities in small cell lung cancer and sarcoma subtypes where LSD1 inhibition remains underexplored. New entrants should target CDSCO-aligned parallel development tracks in India, exploiting relaxed local clinical trial requirements for sponsors with existing FDA INDs. A go-to-market angle centered on AI-driven chromatin accessibility profiling for real-time pharmacodynamic monitoring differentiates sponsors in payer negotiations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical parents seeking to monetize non-core epigenetic assets outside their JAK or hematology focus areas. Long-term viability hinges on intermittent dosing protocol validation and outpatient administration economics over the coming decade. Investors should monitor minimal residual disease endpoint integration into European phase II protocols as an inflection indicator for EMA approval probability and subsequent reimbursement status conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | FDA's evolving biomarker qualification frameworks streamline patient stratification for LSD1-targeted acute myeloid leukemia therapies. |
| cGMP Facility Retrofit | Potent compound handling requirements for demethylase API synthesis force contract manufacturers into specialized containment investments. |
| Regulatory Fast-Track Pursuit | PMDA's Sakigake designation system cuts regulatory lag for sponsors with prior oncology approvals in Japanese markets. |
| Solid Tumor Indication Expansion | Phase II readouts in small cell lung cancer and sarcoma subtypes unlock addressable populations beyond hematologic malignancies. |
| Digital Biomarker Integration | AI-driven chromatin accessibility profiling enables real-time pharmacodynamic monitoring that differentiates sponsors in payer negotiations. |
Research Methodology
The analysis maps small molecule, biologic, and combination therapy sub-sectors, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interviews with these stakeholders combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical R&D expenditure triangulation anchored market sizing.
Assumptions held fixed include FDA accelerated approval pathway continuity, REACH compliance cost trajectories, and biomarker qualification framework evolution, while variables included resistance mechanism emergence rates and allogeneic cell therapy integration velocity. Segmentation dimensions encompassed molecular format, therapy area, delivery mode, and regional regulatory cluster. CAGRs derived from log-linear trend fitting across approved and pipeline asset revenue projections, with inputs including clinical trial enrollment velocity and health system formulary placement probability.
Stress conditions across secondary KDM1A mutation frequency, pyridine intermediate supply disruption, and EMA minimal residual disease endpoint stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory pathway modifications and payer evidence requirement evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
North America Perms and Relaxants Market