
 Monomethyl Acetoacetamide Market | 2026-2036
Monomethyl Acetoacetamide Market Size, Share, and Industry Trends Forecast 2026-2036
Monomethyl Acetoacetamide Market Outlook
China is fragmenting its monomethyl acetoacetamide capacity across multiple provincial chemical parks, with new reactor lines coming online in Jiangsu and Shandong. BASF leverages its integrated acetyl chemistry platform to supply pharmaceutical-grade material with tight impurity profiles. Eastman Chemical Company anchors North American availability through its Kingsport, Tennessee manufacturing complex. Laxmi Organic Industries specializes in batch-scale custom synthesis for Indian agrochemical exporters.
Monomethyl acetoacetamide is a methyl-substituted beta-keto amide synthesized via acetoacetic ester aminolysis, typically supplied as a crystalline solid with melting points near 80-85 degrees Celsius. The compound functions primarily as a reactive intermediate in heterocyclic ring closure for pharmaceutical synthesis and as a chelating ligand precursor in agricultural formulations. Solvent-grade product lines dominate volume throughput, though intermediate-grade material captures disproportionate margin pools due to pharmaceutical certification requirements. Agrochemical applications represent the fastest-expanding demand segment as post-patent herbicide manufacturers seek cost-effective acetoacetamide building blocks. Direct sales channels control the majority of pharmaceutical offtake, while distributor networks handle fragmented agricultural demand across smaller compounders.
EPA industrial chemical reporting under TSCA Section 8(a) shapes import volumes and purity documentation requirements for US-bound shipments. REACH registration dossiers filed with ECHA mandate extensive toxicological data for European market access, elevating compliance costs for non-integrated suppliers. China's MEE enforces emission caps on acetoacetic ester production, constraining upstream feedstock availability during environmental inspection cycles. Stakeholders must monitor regulatory divergence between jurisdictions as divergent purity standards threaten to bifurcate product specifications and fragment tradable volumes.
Market Dynamics
Pharmaceutical formulators are consolidating their supplier base around REACH-compliant and EPA-certified producers, creating a bifurcation between certified pharmaceutical-grade supply and commodity solvent-grade volumes. This certification-driven consolidation is compressing margins for non-integrated intermediates suppliers while elevating pricing power for integrated acetyl chemistry platforms.
Growth Catalysts
- REACH Registration Dossiers:European ECHA compliance mandates are filtering out non-compliant suppliers, concentrating volume with registered producers who can document toxicological data. Pharmaceutical offtake is migrating toward these verified supply lines.
- Acetoacetic Ester Aminolysis:Continuous reactor improvements are reducing batch-to-batch variability in melting point and impurity profiles. Agrochemical compounders are absorbing expanded output for post-patent herbicide synthesis.
- Jiangsu and Shandong Clusters:China's provincial chemical parks are adding dedicated monomethyl acetoacetamide reactor lines. Domestic agrochemical derivative production is absorbing this incremental capacity.
Market Restraints
- Upstream Feedstock Concentration:China's MEE emission caps on acetoacetic ester production create cyclical supply squeezes during environmental inspection periods. Non-integrated formulators face input volatility.
- Substitution Threat from Alternative Beta-Keto Amides:Ethyl acetoacetate derivatives and diketene-based routes compete in cost-sensitive agrochemical applications. Price-sensitive compounders switch when specification thresholds permit.
- REACH Compliance Cost Burden:ECHA registration fees and toxicological testing requirements exceed six figures for new entrants. This structural barrier protects incumbents but blocks supply diversification.
Strategic Opportunities
- Indian Agrochemical Export Channel:Custom synthesis specialists can capture margin from Indian formulators supplying Latin American and African herbicide markets. Batch-scale flexibility matches fragmented order patterns.
- EPA TSCA Section 8(a) Alignment:US-bound suppliers who pre-position purity documentation and reporting infrastructure can displace importers struggling with compliance timelines. Direct pharmaceutical relationships reward readiness.
- Chelation Ligand Convergence:Agricultural micronutrient formulations are integrating acetoacetamide-derived metal chelators alongside traditional EDTA complexes. This application expansion opens specialty pricing tiers.
Industry Challenges
- Pharmaceutical Certification Timelines:FDA drug master file coordination and EMA CEP applications extend qualification cycles to 18-24 months. Suppliers must carry inventory and validation costs before revenue recognition.
- Analytical Method Transfer:Customer-specific impurity profiling requirements create bespoke quality control protocols. Each pharmaceutical formulator demands distinct HPLC method validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monomethyl Acetoacetamide Market |
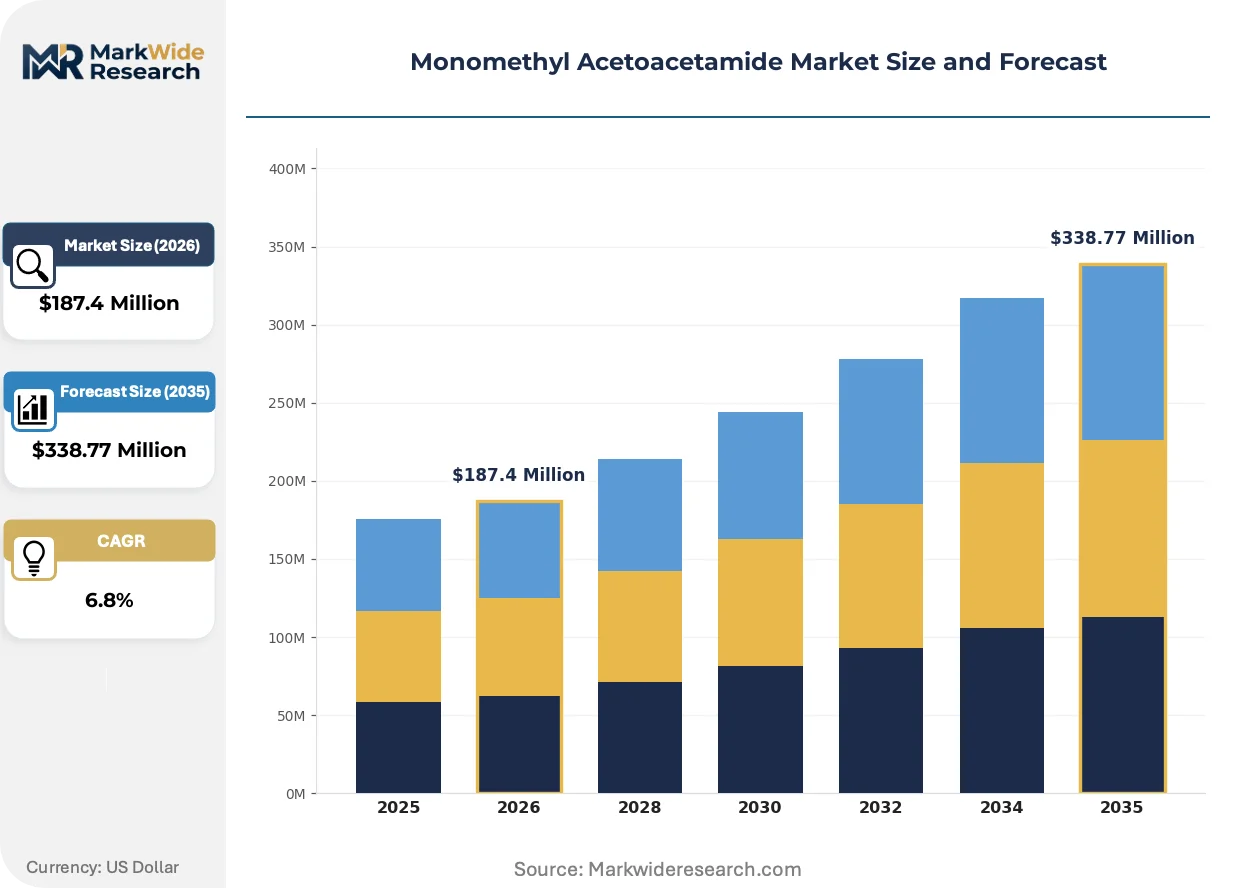
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Reagent, Chemical Compound Application: Pharmaceuticals, Agrochemicals, Dyes, Food Additives End User: Chemical Manufacturers, Research Institutions, Healthcare Providers, Agricultural Firms Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | CONIER Chem & Pharma Ltd., Hubei Jusheng Technology Co. Ltd., Xiamen AmoyChem Co. Ltd., Ria International, SP Chemical Industries, Laxmi Organic Industries, Career in Han Chemicals, BASF, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monomethyl Acetoacetamide Market Strategic Shifts
Digital process control and regulatory data management are converging to reshape how intermediate suppliers demonstrate compliance and capture pharmaceutical-grade premiums. These shifts favor capitalized incumbents over fragmented commodity producers.
Continuous flow reactor technology is virtualizing batch-scale production economics for monomethyl acetoacetamide. BASF and Eastman are deploying modular flow chemistry skids that compress residence times and tighten impurity distributions. Pharmaceutical formulators are qualifying this output for active pharmaceutical ingredient synthesis, enabling just-in-time inventory models that reduce working capital requirements across the value chain.
REACH authorization timelines are compressing the window for non-registered suppliers to serve European pharmaceutical markets. ECHA's 2023 updated guidance on intermediate registration is forcing re-evaluation of toll manufacturing arrangements. Indian and Chinese exporters are redirecting volumes toward domestic agrochemical absorption or US pharmaceutical channels where TSCA reporting offers clearer pathways.
Buyer concentration among top-tier pharmaceutical formulators is consolidating procurement decisions around dual-source strategies with certified primary and qualified secondary suppliers. Direct sales teams are displacing distributor networks for pharmaceutical-grade volumes, while agricultural compounders remain fragmented across regional distributors. This bifurcation is most visible in North America, where Kingsport-based supply anchors pharmaceutical relationships while distributor networks handle smaller agrochemical blenders.
Monomethyl Acetoacetamide Market Segmentation
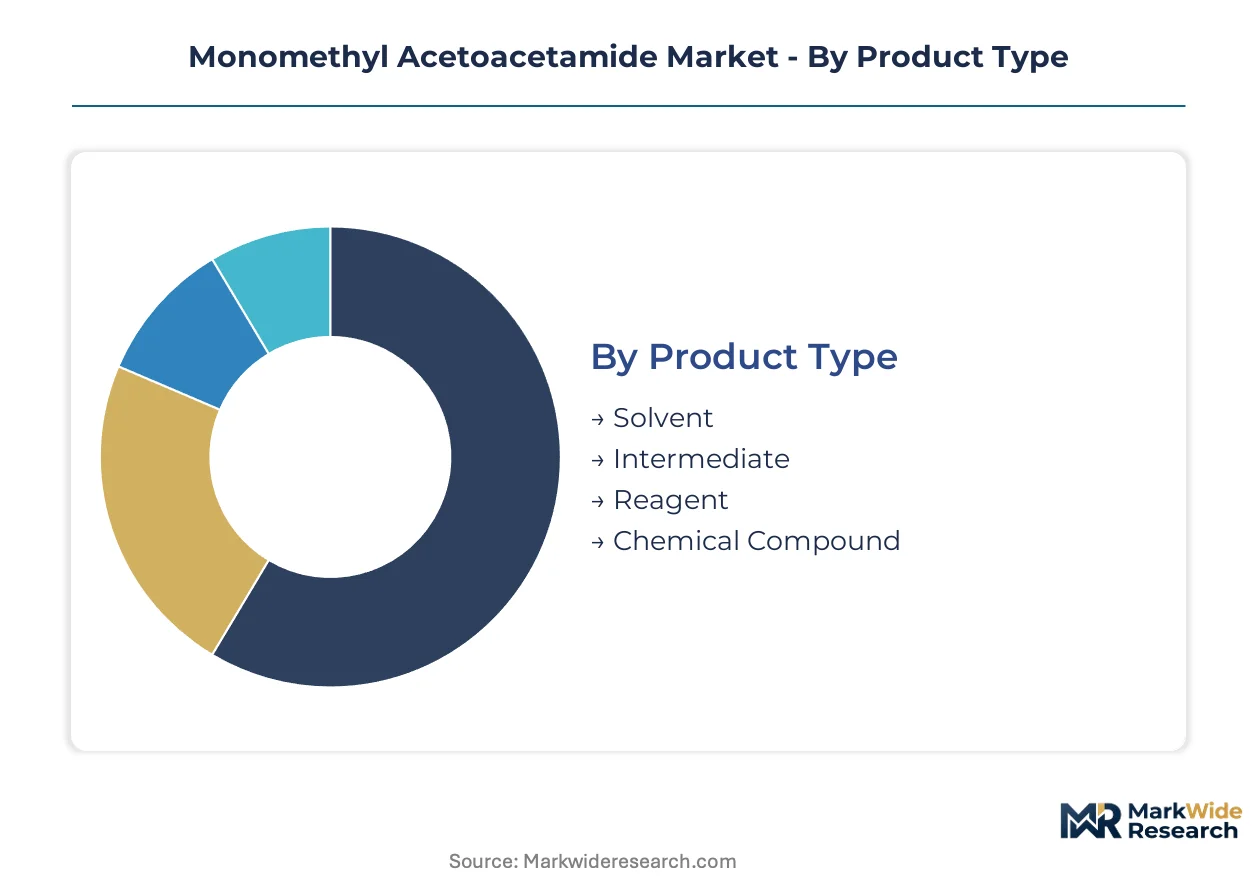
Monomethyl acetoacetamide procurement cycles vary dramatically across use cases, from multi-year pharmaceutical qualification timelines to spot-market agrochemical purchases. Segment-level inventory velocity directly shapes supplier working capital requirements and margin capture potential.
Product Type:
Solvent-grade material turns over fastest on quarterly contracts, while pharmaceutical intermediate lots sit in validation queues for 18-24 months before revenue recognition.
- Solvent:Supplied in bulk tankers or drums for industrial extraction and cleaning applications. Agrochemical blenders in Jiangsu and Shandong absorb volume through distributor networks with 30-60 day payment terms. Price volatility tracks acetoacetic ester feedstock fluctuations.
- Intermediate:Crystalline solid meeting tight melting point specifications (80-85°C) for active pharmaceutical ingredient synthesis. FDA drug master file coordination and EMA CEP applications create extended qualification cycles. REACH-registered producers capture pricing premiums through certified supply lines.
- Reagent:Laboratory-scale packaging for analytical chemistry and method development. Research institutions procure through specialized chemical catalogs with small-batch flexibility.
- Chemical Compound:Generic industrial grade for non-specified manufacturing processes. Price-sensitive buyers switch to ethyl acetoacetate derivatives when specification thresholds permit.
Intermediate dominates installed base value. Solvent is where expansion concentrates.
Application:
Cost tier stratification separates pharmaceutical formulators paying certification premiums from commodity agrochemical buyers optimizing unit economics.
- Pharmaceuticals:Heterocyclic ring closure for beta-lactam and pyrimidine derivative synthesis. Dual-source procurement strategies concentrate volume with REACH-compliant and EPA-certified primary suppliers. Continuous flow reactor output is qualifying for just-in-time inventory models.
- Agrochemicals:Post-patent herbicide manufacturers seek cost-effective acetoacetamide building blocks for chelating ligand precursors. Indian exporters supply Latin American and African markets through batch-scale custom synthesis arrangements. This segment is climbing the fastest as domestic Chinese producers scale derivative output.
- Dyes:Pigment intermediate for azo and anthraquinone colorant synthesis. Textile belt manufacturers in Gujarat and Jiangsu drive regional demand concentration.
- Food Additives:Limited food-grade certification requirements constrain supplier participation. FSSAI compliance in India and FDA food additive petitions shape addressable market scope.
Pharmaceuticals anchor margin pools. Agrochemicals is where volume growth concentrates.
End User:
Customer type determines contract structure, with integrated chemical manufacturers locking in multi-year supply agreements versus fragmented agricultural firms purchasing through distributor networks.
- Chemical Manufacturers:Integrated acetyl chemistry platforms like BASF and Eastman leverage captive feedstock for pharmaceutical-grade output. Direct sales teams manage relationships with tier-one pharmaceutical formulators.
- Research Institutions:University and corporate R&D labs procure gram-to-kilogram quantities for method development. Catalog distributors handle fragmented order patterns with premium pricing.
- Healthcare Providers:Hospital pharmacy compounding and diagnostic reagent preparation drive small-volume demand. Regulatory documentation requirements parallel pharmaceutical standards.
- Agricultural Firms:Post-patent herbicide compounders and micronutrient formulators absorb expanded Chinese capacity. Regional distributor networks manage credit risk across fragmented customer bases.
Chemical Manufacturers dominate supply concentration. Agricultural Firms is where demand fragmentation creates distributor opportunity.
Distribution Channel:
Channel selection bifurcates between certified pharmaceutical supply requiring direct manufacturer relationships and commodity agricultural volumes flowing through intermediaries.
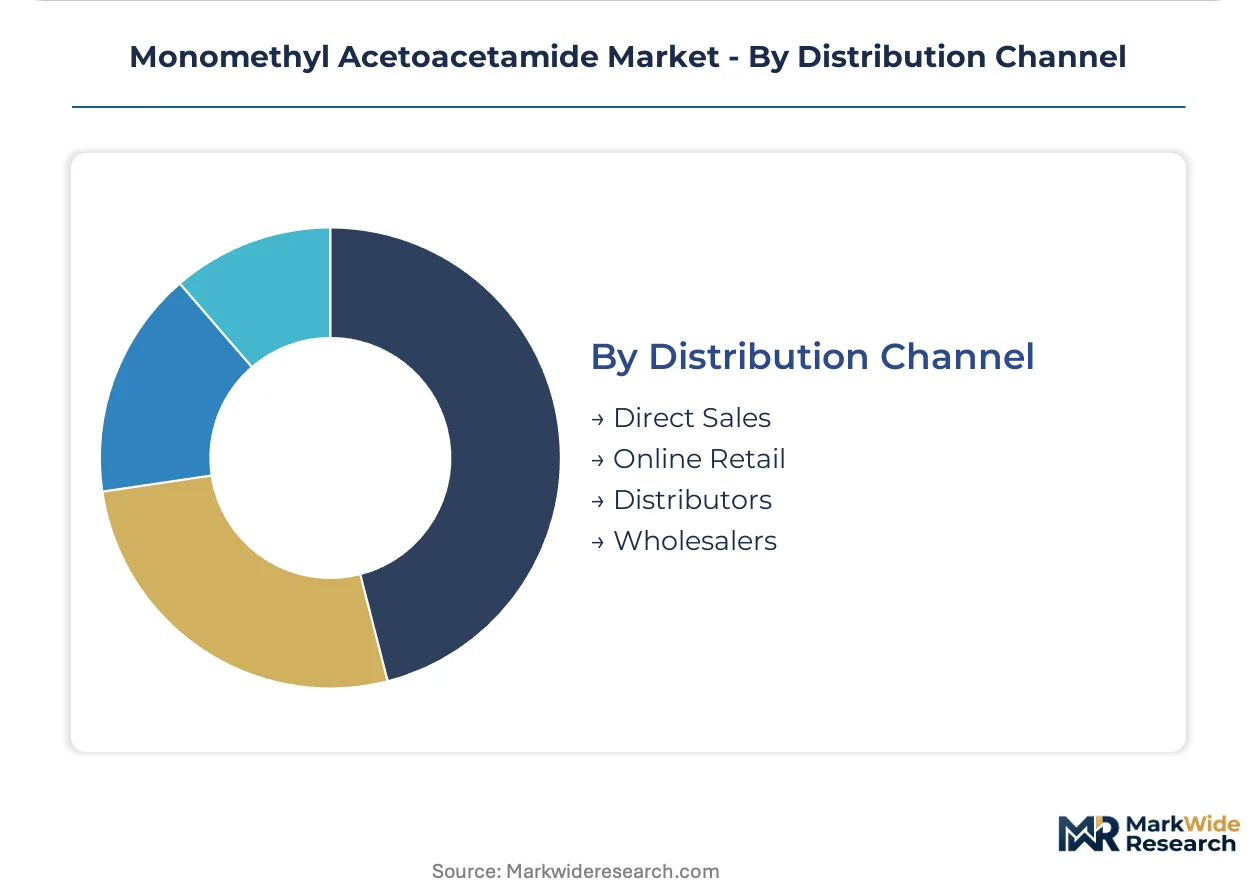
- Direct Sales:Manufacturer-to-formulator relationships for pharmaceutical-grade intermediate with full regulatory documentation. Technical service teams coordinate analytical method transfer and impurity profiling validation.
- Distributors:Regional chemical distributors manage inventory and credit for agrochemical compounders and smaller industrial users. Margin compression intensifies with online retail competition.
- Online Retail:Laboratory supply platforms capture research institution and small-batch industrial demand. Digital process control data is becoming a competitive differentiator for qualified suppliers.
- Wholesalers:Bulk commodity handlers for solvent-grade material in industrial manufacturing belts. Price transparency limits margin capture potential.
Direct Sales dominates pharmaceutical value capture. Distributors is where agricultural volume flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the dominant geography through emission caps on acetoacetic ester production that constrain upstream feedstock availability. Pharmaceutical formulators in Europe and North America face divergent regulatory timelines for market access. Agrochemical demand concentrates in East Asian manufacturing clusters.
China
Jiangsu and Shandong provincial chemical parks are adding dedicated reactor lines for domestic agrochemical derivative production. MEE emission caps on acetoacetic ester create cyclical supply squeezes during environmental inspection periods. Shandong Peninsula manufacturers absorb expanded capacity for post-patent herbicide synthesis.
United States
Pharmaceutical formulators consolidate procurement around EPA TSCA Section 8(a) certified suppliers with pre-positioned purity documentation. FDA drug master file coordination extends qualification cycles to 18-24 months. Kingsport, Tennessee anchors North American pharmaceutical-grade supply through integrated acetyl chemistry infrastructure.
Germany
REACH-registered producers capture pricing premiums through ECHA-compliant supply lines with documented toxicological data. EMA CEP applications filter pharmaceutical offtake toward verified European suppliers. BASF leverages its Ludwigshafen integrated platform for tight impurity profile certification.
India
Custom synthesis specialists supply Latin American and African herbicide markets through batch-scale flexible arrangements. FSSAI food-grade certification requirements constrain supplier participation in limited additive applications. Gujarat textile belt manufacturers drive regional dye intermediate demand concentration.
Monomethyl Acetoacetamide Market Competitive Environment
Integrated acetyl chemistry platforms and regional custom synthesis specialists split the market into certification-driven tiers. Pharmaceutical-grade supply concentrates around REACH-registered and EPA-certified producers with documented toxicological data. Batch-scale operators serve fragmented agrochemical demand through distributor networks. Capacity expansion in Chinese provincial chemical parks and continuous flow reactor technology deployment represent dominant competitive moves.
Within the integrated platform tier, BASF and Eastman Chemical Company exemplify archetypes with captive feedstock control and pharmaceutical certification infrastructure. Laxmi Organic Industries occupies a position among custom synthesis specialists serving export-oriented agrochemical formulators. Chinese manufacturers including Hubei Jusheng Technology Co. Ltd. and Xiamen AmoyChem Co. Ltd. represent the scale-driven regional supply base expanding through provincial chemical park clusters.
| Leading Market Players |
|---|
| CONIER Chem & Pharma Ltd. |
| Hubei Jusheng Technology Co. Ltd. |
| Xiamen AmoyChem Co. Ltd. |
| Ria International |
| SP Chemical Industries |
| Laxmi Organic Industries |
| Career in Han Chemicals |
| BASF |
| Eastman Chemical Company |
| Others |
Value Chain & Pricing Dynamics
China's acetoacetic ester production clusters concentrate upstream feedstock control, directing margin pools toward REACH-registered pharmaceutical-grade suppliers who command certification premiums while solvent-grade volumes compete on cyclical feedstock arbitrage.
Pricing Analysis
Geographic price spreads separate European pharmaceutical-grade material from Asian solvent-grade volumes by certification burden and purity documentation depth. Three-tier pricing structure across pharmaceutical intermediate, solvent-grade, and commodity chemical levels stratifies margin capture, with FDA drug master file coordination and EMA CEP applications as primary price differentiation drivers. Pricing pressure stems from ethyl acetoacetate substitution in cost-sensitive agrochemical applications. Agrochemical compounders exhibit highest price sensitivity, while pharmaceutical formulators prioritize supply security over unit cost.
Supply Chain Analysis
Export-control regimes on dual-use chemical processing equipment constrain technology transfer to non-integrated producers, reinforcing supply concentration. China, Germany, and the United States anchor production capacity, with Jiangsu and Shandong provincial parks feeding domestic derivative output. Acetoacetic ester, methylamine, and aminolysis catalysts constitute critical input dependencies. Single-source vulnerability concentrates in China's MEE emission-capped feedstock base during environmental inspection cycles. Distribution runs through direct manufacturer relationships for pharmaceutical-grade material and regional distributor networks for agricultural volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow reactor technology and REACH authorization timelines are disrupting competitive positioning, compressing the window for non-certified suppliers to serve European pharmaceutical markets.
For Market Incumbents: Pre-empt substitution threats from diketene-based routes by deepening captive acetoacetic ester supply and accelerating FDA drug master file coordination for just-in-time inventory qualification. BASF and Eastman should extend pharmaceutical certification infrastructure to modular flow chemistry output, locking in dual-source procurement relationships before ECHA intermediate registration guidance hardens. For New Entrants and Emerging Players: Build out batch-scale custom synthesis capability for Indian agrochemical exporters supplying Latin American and African herbicide markets, where fragmented order patterns reward operational flexibility. Target chelation ligand convergence in agricultural micronutrient formulations as the most penetrable application expansion, positioning through FSSAI compliance for limited food-grade additive opportunities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian custom synthesis specialists and Chinese provincial chemical park operators facing REACH compliance cost barriers. Five-to-ten year viability hinges on regulatory certification moats rather than commodity scale. Watch EMA CEP application timelines as the signal for pharmaceutical-grade supply scarcity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Deployment | BASF and Eastman compress residence times while tightening impurity distributions for pharmaceutical qualification. |
| REACH Registration Dossier Completion | ECHA-compliant producers filter European pharmaceutical offtake toward verified supply lines with toxicological documentation. |
| Backward Integration into Acetoacetic Ester | Integrated acetyl chemistry platforms mitigate MEE emission cap volatility during Chinese environmental inspection cycles. |
| Indian Agrochemical Export Channel Development | Custom synthesis specialists capture margin from Latin American and African herbicide markets through batch-scale flexibility. |
| Chelation Ligand Application Expansion | Agricultural micronutrient formulations integrate acetoacetamide-derived metal chelators alongside traditional EDTA complexes. |
Study Parameters
Desk research of customs trade databases, ECHA registration dossiers, and SEC chemical industry filings preceded structured interviews with plant managers at acetoacetic ester production facilities, procurement leads at pharmaceutical formulators, distribution channel partners in Indian agrochemical export markets, and technical R&D directors at integrated acetyl chemistry platforms. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis validated volume estimates across the analysis window.
Assumptions held regulatory timelines and feedstock emission cap enforcement patterns within observed historical ranges while varying pharmaceutical qualification cycle lengths and agrochemical derivative demand growth rates. Segmentation modeling incorporated product grade tier, end-use industry application, packaging format, and regional production hub dimensions. CAGRs derived from regression analysis against acetoacetic ester price indices and pharmaceutical intermediate certification premiums, with continuous flow reactor adoption curves and REACH authorization compression as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese provincial chemical park operators or accelerated EMA CEP application approvals by integrated platforms would shift outcomes. Material shifts in MEE emission cap enforcement stringency or EPA TSCA Section 8(a) reporting requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market