
 Colloidal Gold Suspension Market | 2026-2036
Colloidal Gold Suspension Market Size, Share, and Industry Trends Forecast 2026-2036
Colloidal Gold Suspension Market Insights
Multi-source procurement for high-purity gold precursors is recalibrating supply economics across the value chain. BBI Solutions leverages its in-house nanoparticle synthesis capabilities to control batch consistency for diagnostic clients. Sigma Aldrich sustains broad catalog distribution that reaches smaller research institutions without direct manufacturer relationships. NanoComposix differentiates through custom surface chemistry modifications that serve specialized imaging applications.
Colloidal gold suspension comprises nanoscale gold particles, typically 2-150 nm in diameter, dispersed in aqueous or organic media via citrate reduction or similar stabilization protocols; the particle surface charge and coating chemistry determine aggregation stability and biological targeting. Diagnostic tests represent the dominant application segment, with lateral flow immunoassays consuming standardized particle sizes in high-throughput manufacturing. Drug delivery applications occupy a faster-growing but smaller position, as pharmaceutical companies evaluate gold nanoparticle vectors for targeted therapeutics against oncology indications.
FDA device regulations and EPA nanomaterial reporting requirements shape product development timelines and safety documentation burdens for manufacturers selling into United States markets. ISO 10993 biocompatibility standards and REACH substance registration in Europe add parallel compliance layers that influence formulation choices and market access strategies. Stakeholders must monitor how evolving regulatory clarity on nanomaterial classification affects capital allocation between diagnostic and therapeutic application development.
Market Dynamics
Multi-source procurement for high-purity gold precursors is recalibrating supply economics across the value chain, while FDA nanomaterial guidance and REACH substance registration create parallel compliance burdens that reshape formulation priorities and capital allocation between diagnostic and therapeutic applications.
Growth Catalysts
- Point-of-care testing infrastructure:Lateral flow immunoassays expand into veterinary diagnostics and environmental monitoring, absorbing standardized colloidal gold particle volumes from high-throughput manufacturers in the United States.
- REACH substance registration:European regulatory clarity on nanomaterial classification accelerates documented safety profiles that unlock institutional procurement channels for research-grade suspensions.
- Targeted oncology therapeutics:Pharmaceutical companies evaluate gold nanoparticle vectors for drug delivery, creating pull-through demand for custom surface chemistry modifications in preclinical development pipelines.
Market Restraints
- Gold precursor cost volatility:Spot price fluctuations for high-purity chloroauric acid and sodium citrate reagents compress margin stability for batch-scale synthesis operations.
- Supply concentration in United States:NIH-funded research clusters in Boston and San Diego absorb disproportionate volumes, creating geographic demand asymmetry that strains distributor inventory allocation.
- ISO 10993 biocompatibility certification timelines:Extended safety documentation periods for device-grade formulations delay product commercialization and tie up working capital.
Strategic Opportunities
- Environmental monitoring applications:Heavy metal detection and water quality testing represent underpenetrated end-uses where lateral flow adaptability meets regulatory sampling mandates.
- EU Green Deal nanomaterial incentives:Sustainable synthesis protocol funding creates competitive advantage for manufacturers adopting citrate reduction alternatives with lower environmental footprint.
- Convergence with quantum dot imaging:Multiplexed diagnostic platforms combining gold nanoparticle stability with fluorescent signal amplification enable next-generation assay sensitivity thresholds.
Industry Challenges
- Specialized nanomaterial synthesis talent:Scarcity of chemists trained in controlled nucleation and surface functionalization protocols constrains batch consistency at scale.
- Legacy quality management system integration:Diagnostic manufacturers face friction embedding nanoparticle supplier qualification into existing ISO 13485 device frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colloidal Gold Suspension Market |
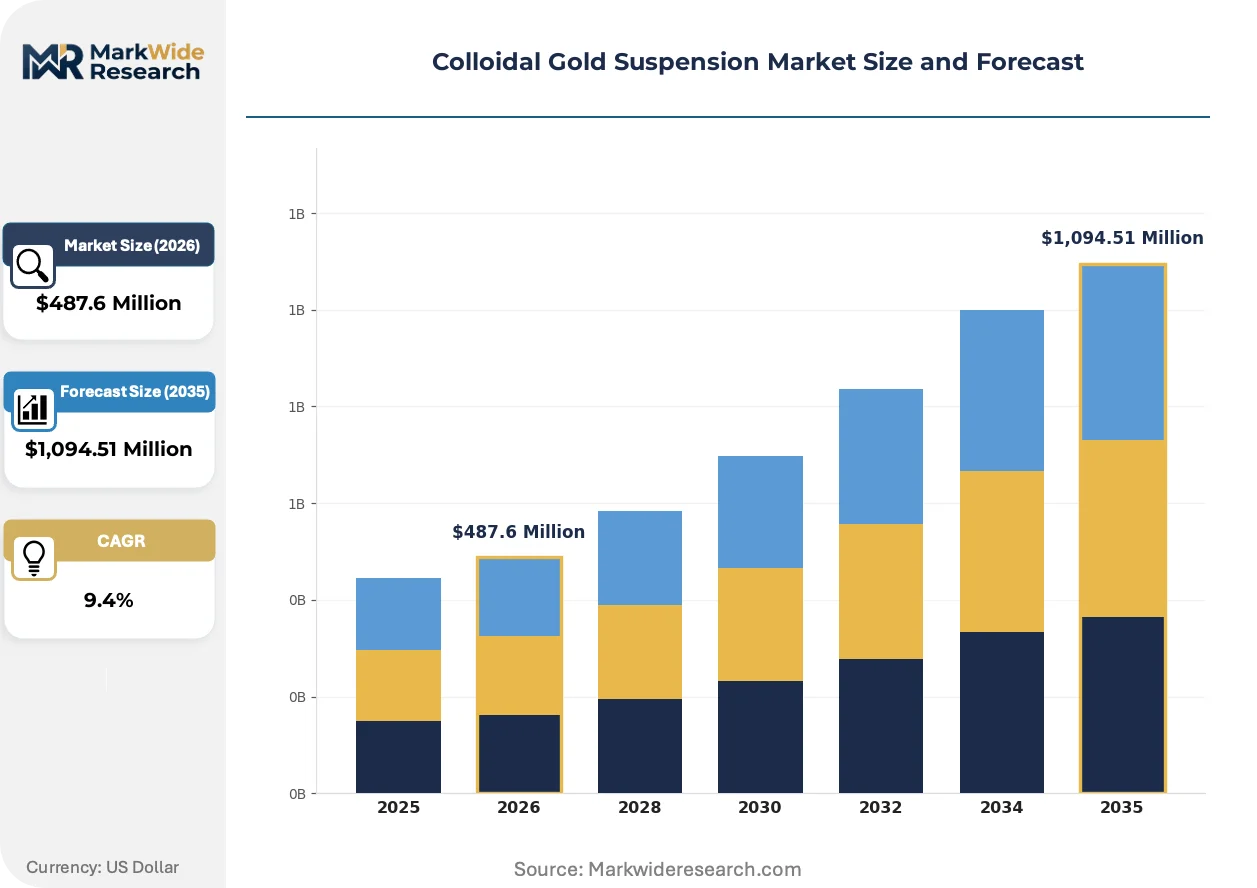
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Colloidal Solutions, Gold Powders, Coated Particles Application: Biomedical Research, Diagnostic Tests, Drug Delivery, Imaging Agents End User: Hospitals, Laboratories, Research Institutions, Pharmaceutical Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale Suppliers |
| Companies Covered | Innova Biosciences, Sigma Aldrich, BBI Solutions, Meliorum Technologies, Metalor, Cytodiagnostics, Tripod Technology, NanoBio Chemicals India, nanoComposix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colloidal Gold Suspension Market Trends and Innovations
Surface chemistry engineering is actively reshaping competitive differentiation, as manufacturers move beyond commodity particle supply toward functionalized architectures that command premium positioning in specialized imaging and therapeutic applications.
PEGylated and antibody-conjugated gold nanoparticles enable targeted cellular binding with reduced non-specific adsorption. Academic medical centers and contract research organizations are adopting these modified suspensions for preclinical imaging studies. The structural consequence is absorbing research budgets that previously allocated to organic fluorophores and radioactive tracers.
EMA's evolving guidance on nanomaterial-containing medicinal products is compressing development timelines for pharmaceutical-grade formulations. Device manufacturers must now submit enhanced characterization data on particle size distribution and surface charge stability. European diagnostic firms are responding by vertically integrating synthesis capabilities to control documentation traceability.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for standardized diagnostic-grade particles. Hospital systems and reference laboratories now negotiate volume contracts through medtech distributors. This concentration is most visible in the United States, where integrated delivery networks leverage purchasing scale to compress per-test reagent costs.
Colloidal Gold Suspension Market Segmentation
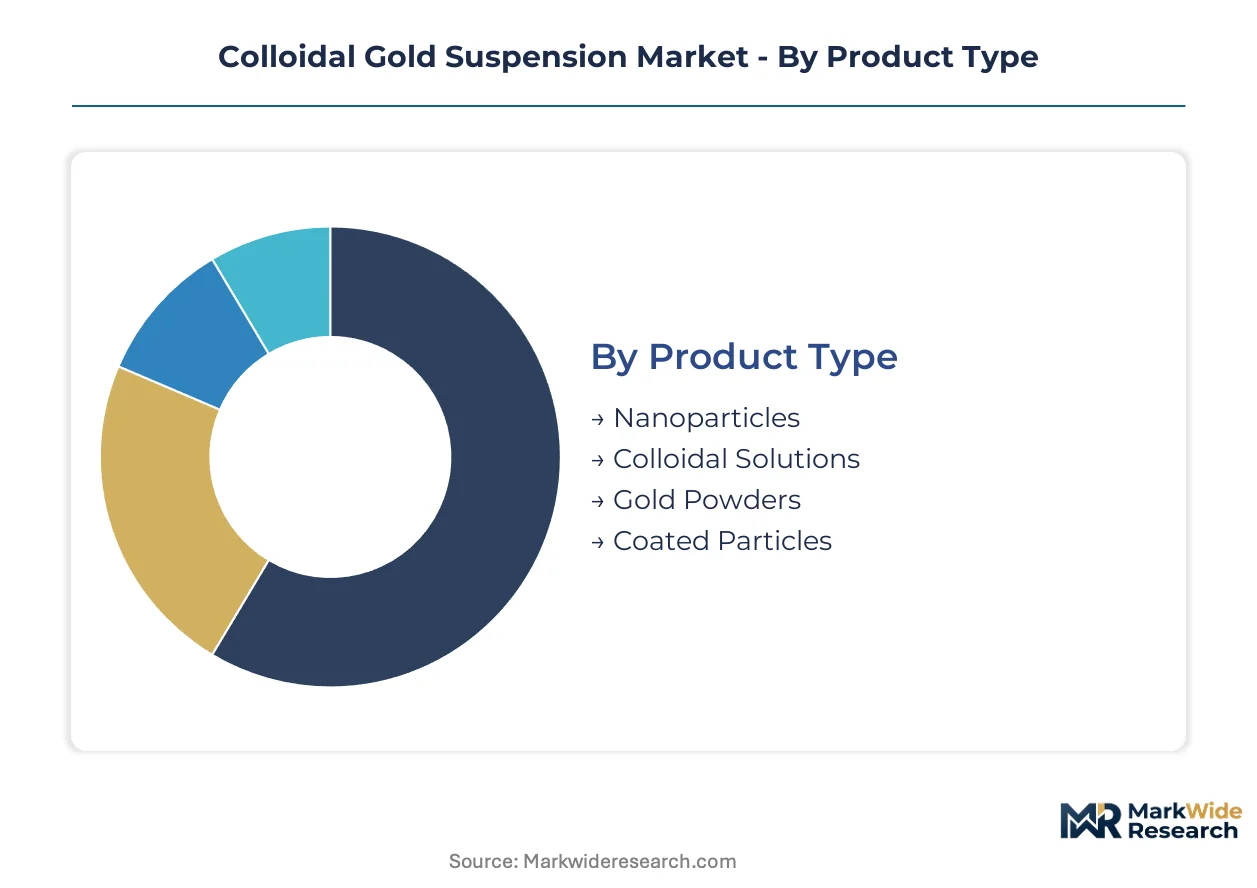
Segmentation in colloidal gold suspensions reveals distinct procurement patterns between standardized diagnostic-grade materials and specialized functionalized variants. Integration depth varies sharply: some segments serve as standalone consumables while others embed into complex device ecosystems requiring extensive regulatory documentation.
Product Type:
Standalone nanoparticle suspensions command premium positioning in research markets, whereas coated and powder formulations embed into manufacturing supply chains with tighter integration requirements.
- Nanoparticles:Citrate-stabilized aqueous dispersions with defined size distributions (2-150 nm) serve as the foundational input for lateral flow assay manufacturers. Demand concentrates in United States point-of-care testing infrastructure where FDA device regulations mandate batch-to-batch consistency documentation.
- Colloidal Solutions:Ready-to-use buffered suspensions with optimized pH and ionic strength reduce downstream processing steps for diagnostic kit producers. Pharmaceutical companies in Boston and San Diego research clusters absorb significant volumes for preclinical drug delivery evaluation.
- Gold Powders:Lyophilized or spray-dried particulate formats enable long-haul shipping to remote manufacturing sites without cold chain dependency.
- Coated Particles:PEGylated, antibody-conjugated, or streptavidin-functionalized surfaces command specialized positioning in imaging and therapeutic applications.
Volume placements concentrate in Nanoparticles; the faster expansion belongs to Coated Particles.
Application:
Application segments stratify by regulatory burden intensity, with diagnostic tests facing compressed commercialization timelines compared to drug delivery's extended safety validation cycles.
- Diagnostic Tests:Lateral flow immunoassays for infectious disease, pregnancy, and cardiac markers consume standardized particle sizes in high-throughput manufacturing. Veterinary diagnostics and environmental monitoring applications are absorbing additional volumes as assay platforms expand beyond human clinical settings.
- Drug Delivery:Gold nanoparticle vectors for targeted oncology therapeutics occupy a smaller but steeply climbing position. EMA guidance on nanomaterial-containing medicinal products is compressing development timelines and pulling through demand for custom surface chemistry modifications.
- Biomedical Research:Academic laboratories utilize unconjugated particles for fundamental colloidal behavior studies and assay development prototyping.
- Imaging Agents:CT and photoacoustic contrast applications leverage gold's high atomic number and tunable optical properties for preclinical imaging studies.
Diagnostic Tests anchor current procurement volumes; Drug Delivery is climbing the fastest as pharmaceutical pipelines mature.
End User:
End user segments diverge by purchasing authority structure, with consolidated hospital procurement contrasting against fragmented research institution buying patterns.
- Pharmaceutical Companies:Integrated drug development operations source custom-functionalized particles through direct manufacturer relationships, bypassing distributor markups for high-volume therapeutic programs. ISO 10993 biocompatibility certification requirements extend supplier qualification timelines.
- Research Institutions:NIH-funded clusters in Boston and San Diego absorb disproportionate volumes of research-grade suspensions, though individual laboratory purchasing limits contract leverage.
- Hospitals:Integrated delivery networks in the United States negotiate consolidated procurement contracts through group purchasing organizations, compressing per-test reagent costs for standardized diagnostic particles.
- Laboratories:Reference and clinical testing facilities balance cost sensitivity against turnaround time requirements in sourcing decisions.
Volume placements concentrate in Pharmaceutical Companies; the steepest expansion trajectory belongs to Hospitals as point-of-care infrastructure proliferates.
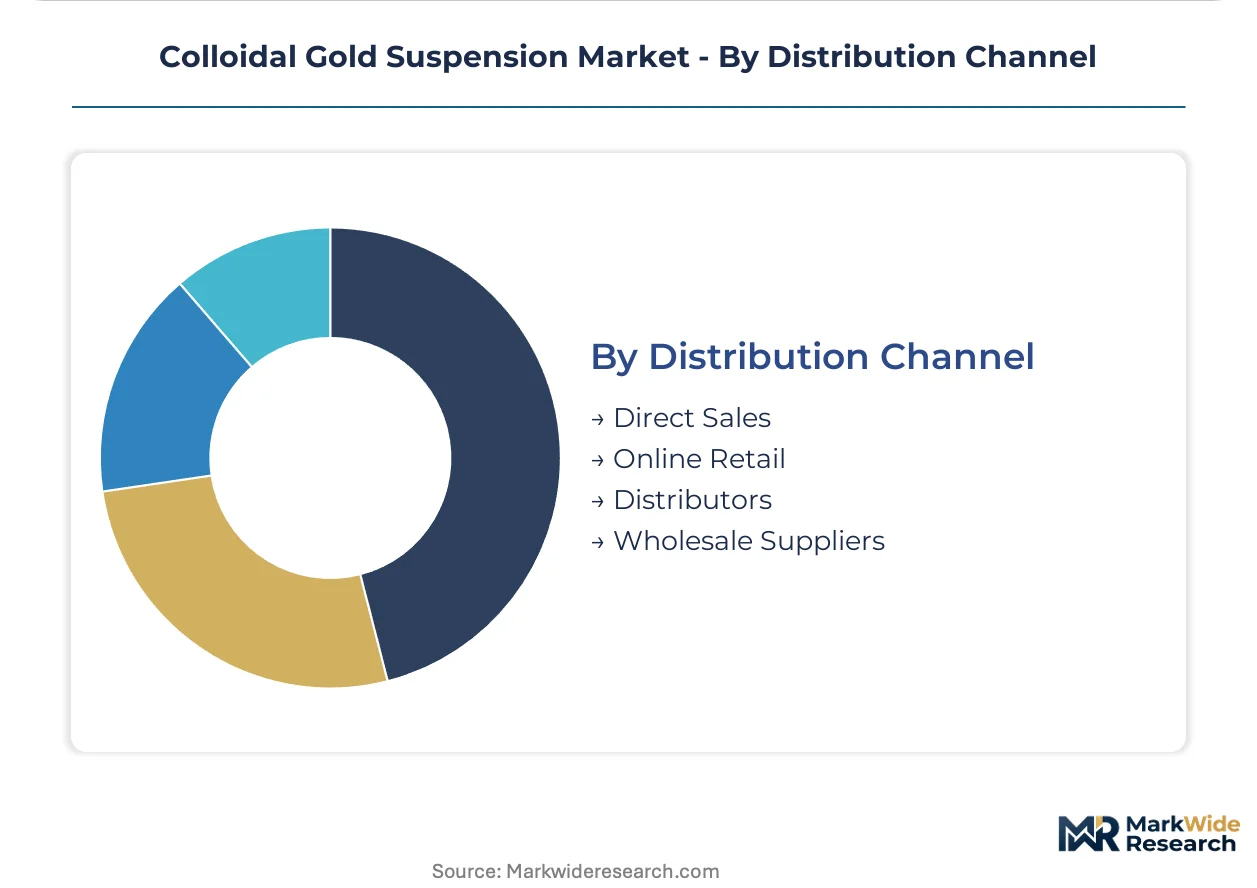
Distribution Channel:
Channel selection reflects order fragmentation patterns, with large-volume diagnostic manufacturers bypassing intermediaries while smaller research buyers rely on catalog distributors.
- Direct Sales:Diagnostic test manufacturers with predictable high-volume demand establish captive supply relationships with synthesis specialists, securing batch priority and documentation traceability. BBI Solutions and similar producers leverage in-house capabilities to lock in device-grade contracts.
- Distributors:Medtech and laboratory supply intermediaries serve fragmented research and clinical laboratory demand, aggregating smaller orders across multiple end users. Sigma Aldrich sustains broad catalog reach to institutions lacking direct manufacturer relationships.
- Online Retail:E-commerce platforms capture emergency replenishment and small-scale research orders with expedited fulfillment.
- Wholesale Suppliers:Bulk chemical distributors handle commodity-grade gold precursor and reagent logistics for synthesis operations.
Direct Sales dominates volume placements; Distributors are gaining share fastest as consolidated procurement concentrates buying power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity gold precursor supply chains anchor manufacturing economics in the United States, Germany, and China, where diagnostic test production and nanomaterial research clusters concentrate procurement volumes and shape regional competitive dynamics.
United States
Point-of-care testing infrastructure and NIH-funded research clusters in Boston and San Diego absorb disproportionate volumes of diagnostic-grade suspensions. FDA device regulations mandate batch-to-batch consistency documentation that extends supplier qualification timelines. Integrated delivery networks leverage group purchasing organization contracts to compress per-test reagent costs across hospital systems.
Germany
Precision diagnostic manufacturers and academic medical centers drive demand for functionalized nanoparticles in preclinical imaging applications. REACH substance registration requirements and ECHA nanomaterial classification protocols accelerate documented safety profiles for institutional procurement. The Rhine-Ruhr industrial corridor hosts synthesis operations serving device-grade contracts across European markets.
China
Domestic lateral flow assay production for infectious disease testing consumes standardized particle volumes from local synthesis operations. NMPA medical device regulations and GB standards for nanomaterial characterization shape product registration pathways. The Yangtze River Delta concentration of diagnostic manufacturers pulls through precursor volumes from regional chemical suppliers.
United Kingdom
Veterinary diagnostics and environmental monitoring applications expand assay platform demand beyond human clinical settings. MHRA guidance on nanomaterial-containing devices aligns with evolving EMA medicinal product frameworks. The Cambridge-Oxford-London biotech triangle absorbs research-grade suspensions for fundamental colloidal behavior studies.
India
Contract research organizations and pharmaceutical development pipelines evaluate gold nanoparticle vectors for targeted therapeutics. CDSCO medical device rules and BIS standards for nanomaterial quality create parallel compliance documentation requirements. The Hyderabad-Bengaluru pharmaceutical corridor sources custom surface chemistry modifications for preclinical programs.
Colloidal Gold Suspension Market Competitive Landscape
Capacity expansion dominates the current landscape as synthesis specialists scale batch operations to secure device-grade contracts from diagnostic manufacturers. The vendor base stratifies between integrated producers controlling precursor-to-particle workflows and catalog distributors aggregating fragmented research demand. Three archetypes anchor positioning: in-house synthesis specialists, broad-reach chemical distributors, and custom surface chemistry modifiers. Competitive moves concentrate on backward integration into gold precursor supply and geographic expansion into Asia-Pacific diagnostic manufacturing zones.
Among synthesis-integrated specialists, BBI Solutions and nanoComposix occupy positions shaped by nanoparticle production capabilities, while Sigma Aldrich exemplifies the catalog distribution archetype reaching institutions without direct manufacturer relationships. These three anchors represent distinct competitive vectors: captive supply control, functionalized architecture development, and broad institutional access. Their positioning reflects how procurement concentration in United States research clusters and European diagnostic manufacturing favors players with documented quality management systems and regulatory pathway experience.
| Leading Market Players |
|---|
| Innova Biosciences |
| Sigma Aldrich |
| BBI Solutions |
| Meliorum Technologies |
| Metalor |
| Cytodiagnostics |
| Tripod Technology |
| NanoBio Chemicals India |
| nanoComposix |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up diagnostic reagent specialists have consolidated batch-scale synthesis operations across the United States and Germany, tightening pricing discipline through captive supply relationships while compressing margin buffers for independent distributors serving fragmented research demand.
Pricing Analysis
Warranty-backed batch consistency documentation and ISO 10993 biocompatibility certification are bundled into premium diagnostic-grade contracts, whereas research-grade suspensions ship unbundled with limited traceability support. Three-tier pricing structure across premium, standard, and economy levels separates FDA-device-grade formulations from research-grade and commodity precursor tiers. Price differentiation hinges on certification burden and volume scale, with hospital systems through group purchasing organizations extracting steepest discounts. Cost compression in the standard tier is intensifying because consolidated procurement concentrates buyer leverage. Contract research organizations exhibit highest price sensitivity; pharmaceutical companies developing oncology therapeutics show least sensitivity due to custom surface chemistry requirements.
Supply Chain Analysis
Single-source vulnerability sits with high-purity chloroauric acid precursor supply concentrated in Germany, the United States, and China. Batch-scale synthesis draws from sodium citrate stabilizers, specialized filtration membranes, and analytical-grade solvents. Commodity price volatility for gold feedstock creates margin instability that propagates through value chain tiers. Distribution runs through direct manufacturer relationships for diagnostic OEMs and medtech distributors for fragmented research accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface chemistry engineering is displacing legacy unconjugated particle supply as PEGylated and antibody-functionalized architectures capture premium positioning in imaging and therapeutic pipelines.
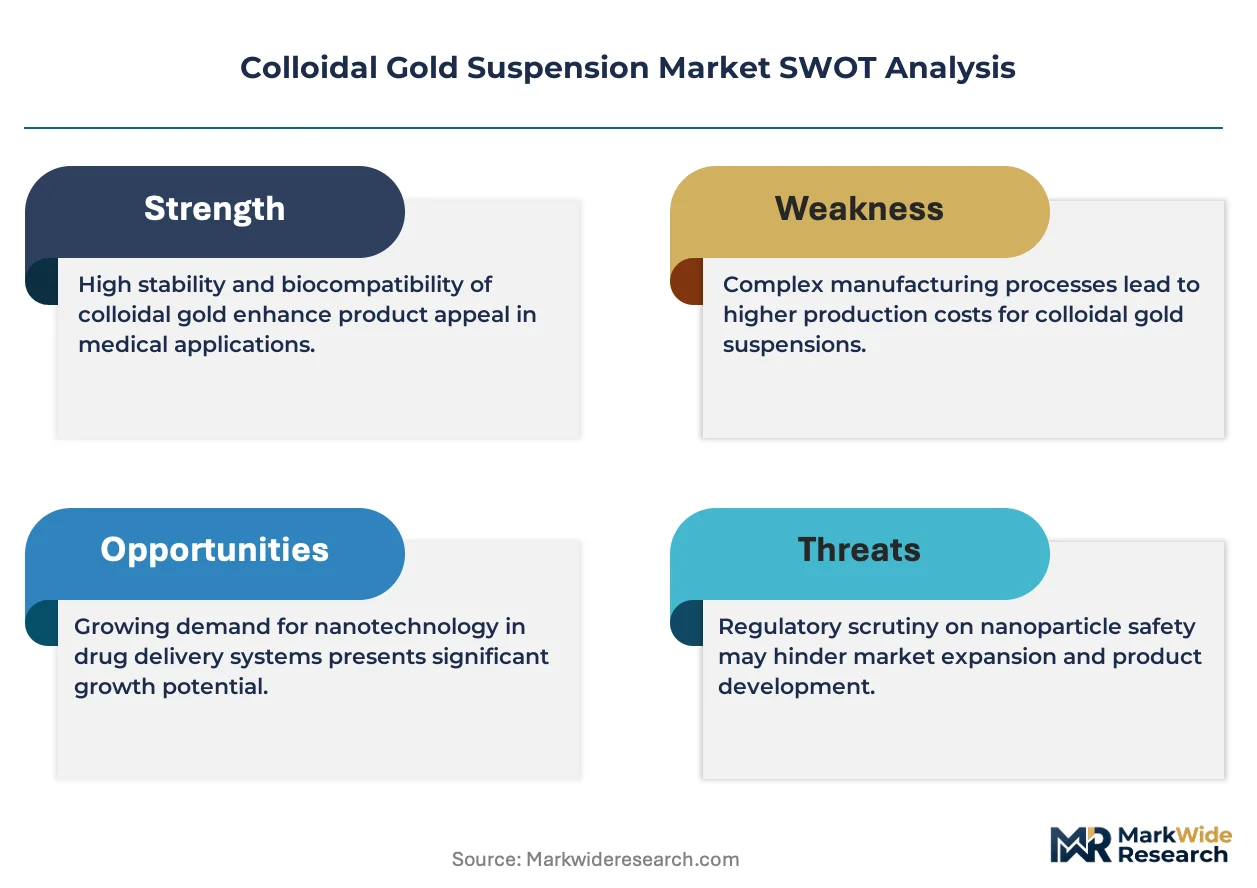
For Market Incumbents: Deploy backward integration into gold precursor refining to lock in margin control against spot price volatility. Incumbent synthesis specialists must secure ISO 13485 certification extensions to maintain device-grade contract eligibility as FDA nanomaterial guidance tightens documentation requirements. Capacity addition in the Yangtze River Delta diagnostic manufacturing zone defends geographic share against regional Chinese competitors. For New Entrants and Emerging Players: Begin with environmental monitoring applications for heavy metal detection, an underpenetrated lateral flow segment with lower regulatory barriers than human diagnostics. Veterinary diagnostics in India offers penetrable white-space with CDSCO device rules still evolving. A go-to-market angle anchored on sustainable citrate reduction protocols aligns with EU Green Deal nanomaterial incentives. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap synthesis specialists with captive nanoparticle production capabilities in the Boston-San Diego research corridor. Long-term viability rests on therapeutic pipeline maturation stretching across a multi-year pharmaceutical development window. Watch EMA guidance finalization on nanomaterial-containing medicinal products as the inflection signal pulling through custom functionalization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gold Precursor Supply | BBI Solutions and nanoComposix secure margin control against chloroauric acid spot volatility. |
| ISO 13485 Quality Management Extension | Diagnostic-grade suppliers embed nanoparticle qualification into existing device frameworks. |
| Custom Surface Chemistry Development | PEGylated and antibody-conjugated architectures command premium in oncology therapeutic pipelines. |
| Geographic Expansion into Asia-Pacific Manufacturing | Yangtze River Delta diagnostic producers pull through localized synthesis capacity. |
| Sustainable Synthesis Protocol Adoption | Citrate reduction alternatives unlock EU Green Deal nanomaterial incentive funding. |
Research Methodology
Independent corroboration across synthesis specialists, diagnostic test manufacturers, and pharmaceutical development executives underwrites the qualitative findings. Primary interviews with nanoparticle chemists, regulatory affairs leads at device firms, GPO contracts managers, and preclinical imaging directors combined with secondary validation from FDA device filings, EMA nanomaterial guidance documents, NIH grant databases, and REACH substance registration records. Bottom-up demand modeling across end-use segments triangulates against top-down value chain analysis.
Comparable-period anchoring to historical lateral flow assay deployment and gold nanoparticle therapeutic pipeline progression shaped the projection horizon. Segmentation dimensions modeled include product type tier, application regulatory burden intensity, end-user purchasing authority structure, and distribution channel concentration pattern. CAGRs derive from segment-level demand build-ups calibrated to documented procurement volumes at NIH-funded research clusters. Forecast inputs incorporate evolving FDA nanomaterial classification timelines and EMA medicinal product guidance compression effects.
Underlying measurement precision varies by segment; diagnostic test applications carry tighter precision than emerging therapeutic vectors. Forecasts reflect documented assumptions on regulatory pathway clarity and precursor supply stability. Gold price volatility, nanomaterial classification delays, and synthesis talent scarcity constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Zinc Methionine Chelates Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Europe Optical Brighteners Market