
 Global Optical Brighteners Market | 2026-2036
Global Optical Brighteners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Brighteners Market Foresight
REACH compliance is broadening the cost-of-entry calculus for optical brightener suppliers seeking European market access. BASF leverages its integrated precursor supply chain to sustain cost advantages across benzoxazole derivative production. Huntsman International LLC anchors its position through specialized textile brightening formulations that dominate premium apparel segments. Archroma differentiates by navigating complex regulatory environments with certified low-impact product lines.
Optical brighteners are synthetic organic compounds, typically stilbene or coumarin derivatives, that absorb ultraviolet light and re-emit visible blue wavelengths to counteract yellowing in substrates. These agents function through fluorescence mechanisms with absorption maxima near 340-400 nanometers, primarily serving to enhance perceived whiteness in paper, textiles, detergents, and plastics. Styryl derivatives occupy the largest volume share due to their cost-performance balance in paper and detergent applications, while benzoxazole derivatives represent the fastest-expanding category driven by thermal stability demands in plastics processing. Coumarin derivatives concentrate in high-end coatings where UV resistance and optical clarity command premium positioning.
EPA oversight in the United States, REACH in Europe, and GB standards in China collectively shape permissible chemistries, labeling requirements, and discharge limits for optical brightener manufacturing. ECHA substance evaluations and MEE environmental compliance mandates in China are forcing reformulation investments and supply chain requalification across the industry. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which chemistries will retain market access versus face phased restriction.
Market Dynamics
REACH substance evaluations and China's MEE discharge mandates are forcing simultaneous reformulation across three continents, compressing the viable chemistry set while paper mills and textile finishers accelerate qualification of compliant alternatives.
Growth Catalysts
- Packaging sector expansion:E-commerce fulfillment centers in China and India are specifying optical brighteners for corrugated board and folding cartons to enhance shelf appeal. This specification pull is converting previously unbrightened grades.
- REACH authorization timelines:The phased restriction of legacy stilbene derivatives under ECHA evaluation is accelerating substitution demand for benzoxazole and coumarin chemistries that retain market access.
- Thermal stability requirements:Plastics processors in Germany and Japan are adopting benzoxazole derivatives for high-temperature engineering polymers used in automotive interior components.
Market Restraints
- Precursor supply concentration:Diaminostilbene disulfonic acid (DASDA) production clusters in China and India, creating single-source vulnerability for stilbene derivative manufacturers elsewhere.
- Substitute whitening technologies:Titanium dioxide loading in paper coatings and fluorescent-free visual brightening through process control are capturing share in premium packaging segments.
- Input cost volatility:Ortho-toluidine and cyanuric chloride prices fluctuate with agrochemical and pool chemical demand cycles, compressing formulation margins unpredictably.
Strategic Opportunities
- Bio-based feedstock integration:Coumarin derivative producers are exploring lignin-derived precursors to meet EU Green Deal circular economy procurement criteria in cosmetics and food-contact applications.
- India textile hub expansion:Surat and Tiruppur processing clusters are upgrading finishing capabilities, creating first-time specification opportunities for textile-grade brighteners in previously commodity-oriented operations.
- Dual-channel distribution:Direct technical service relationships with mid-size paper mills are bypassing traditional merchant chemical distributors, capturing margin and accelerating formulation co-development.
Industry Challenges
- Cross-jurisdictional registration expertise:The divergence between EPA TSCA inventory requirements, REACH dossier standards, and China's MEE new chemical notification creates compliance timeline fragmentation that few suppliers navigate efficiently.
- Application-specific qualification cycles:Each paper machine or textile finishing line requires 12-18 month validation of optical brightener performance against yellowness indices and lightfastness specifications, locking working capital in field trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Brighteners Market |
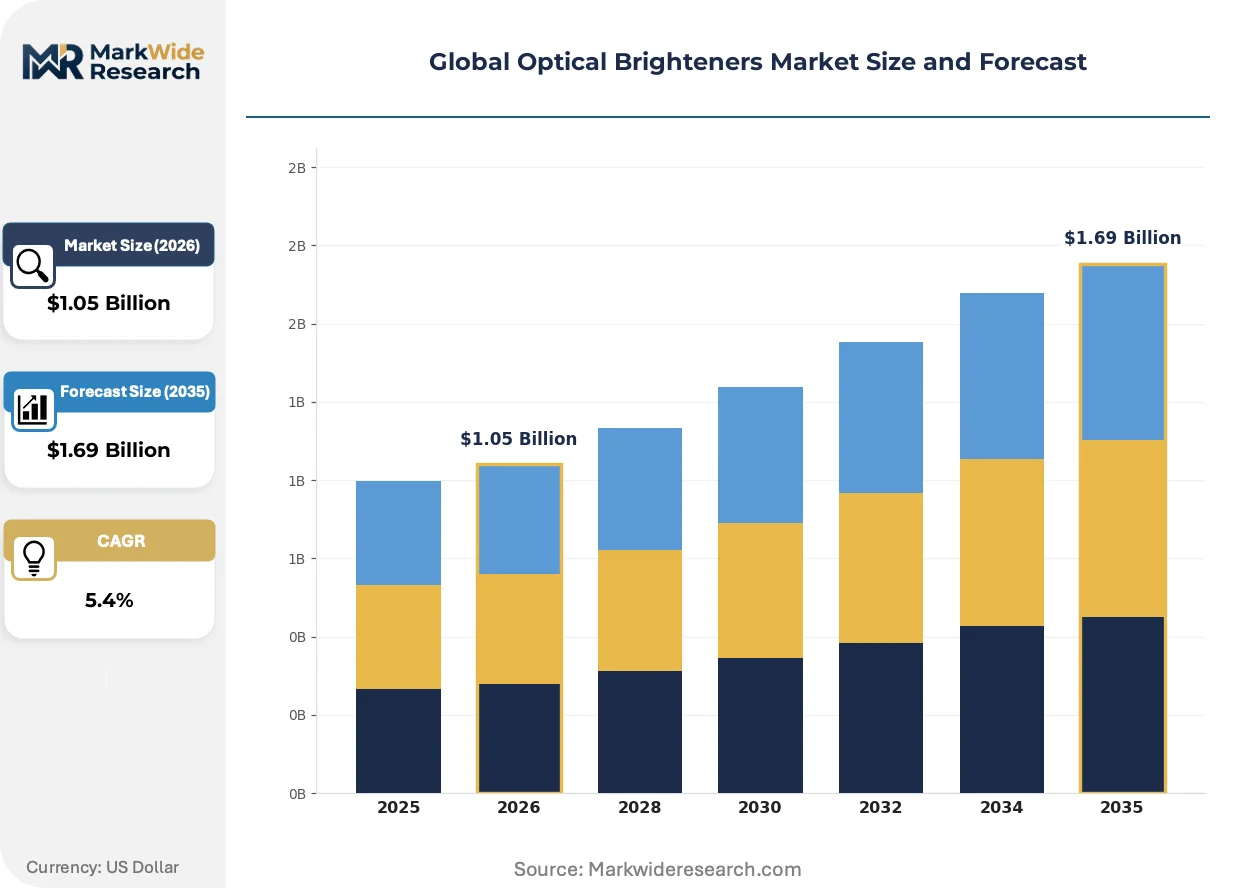
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styryl Derivatives, Coumarin Derivatives, Benzoxazole Derivatives, Pyrazoline Derivatives, Others Application: Paper Whitening, Textile Brightening, Detergents, Plastics, Coatings End User Industry: Manufacturing Plants, Textile Producers, Chemical Processors, Packaging Facilities Distribution Channel: Direct Sales, Online Platforms, Distributors, Industrial Suppliers, Retail Outlets |
| Companies Covered | BASF, Huntsman International LLC, Archroma, Milliken & Company, Clariant, 3V Sigma S.p.A., Eastman Chemical Company, Day-Glo Color Corp., Kolorjet Chemicals Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Brighteners Market Shifts & Advancements
Fluorescence engineering is converging with sustainability certification requirements, as formulators balance optical performance against biodegradability mandates and restricted substance lists that vary by end-use jurisdiction.
Microencapsulation technology for controlled-release optical brighteners is electrifying technical textile applications. Military uniform suppliers and high-performance sportswear manufacturers in Germany and South Korea are adopting these systems to maintain brightness through repeated industrial laundering. The technology is compressing replacement frequency and enabling premium pricing for durability-certified formulations.
REACH Annex XIV authorization requirements for certain stilbene derivatives are eliminating legacy chemistries from EU market access. Paper producers in Finland and textile finishers in Italy are accelerating qualification of benzoxazole alternatives ahead of sunset dates. The regulatory compression is favoring suppliers with pre-registered substitution portfolios over those dependent on soon-to-be-restricted molecules.
Brand-owner sustainability scorecards are reshaping chemical procurement in consumer-facing packaging. Unilever, Procter & Gamble, and Nestlé supplier requirements are displacing traditional specification-by-price models with certified low-impact brightener mandates. This behavioral shift is most visible in Western European detergent and personal care packaging, where Cradle to Cradle and ZDHC MRSL compliance now gate commercial relationships.
Global Optical Brighteners Market Segmentation
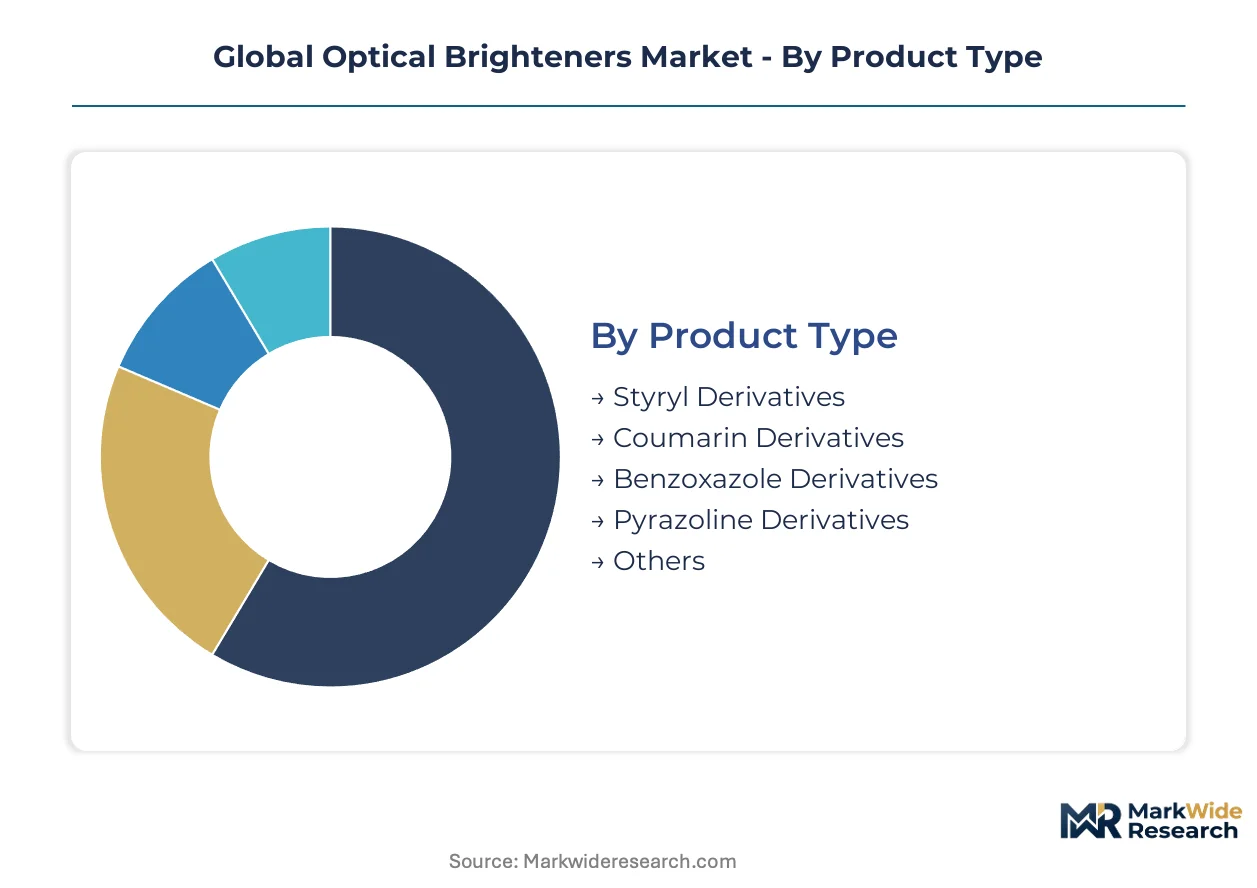
Optical brightener procurement splits sharply between high-volume commodity grades and premium-certified formulations. Specification divergence across paper, textile, and plastics end-uses forces suppliers to maintain parallel product architectures with distinct regulatory dossiers.
Product Type:
Volume leadership belongs to styryl derivatives, while premium positioning and regulatory resilience concentrate in benzoxazole and coumarin chemistries.
- Styryl Derivatives:These stilbene-based compounds dominate paper and detergent applications through cost-efficient synthesis from DASDA precursors. Demand concentrates in Chinese and Indian packaging facilities serving e-commerce fulfillment networks, though REACH authorization timelines are compressing European market access for legacy grades.
- Benzoxazole Derivatives:Superior thermal stability above 300°C enables specification in automotive interior plastics and high-temperature engineering polymers. German and Japanese processors are converting to these chemistries ahead of regulatory sunset dates for less stable alternatives.
- Coumarin Derivatives:UV resistance and optical clarity command premium positioning in high-end coatings and cosmetics packaging. Lignin-derived bio-based precursors are under evaluation for EU Green Deal compliance.
- Pyrazoline Derivatives:Niche fluorescence properties serve specialized security printing and anti-counterfeiting applications with limited volume but high margin retention.
- Others:Naphthotriazole and carbostyril variants address specific wavelength requirements in photographic papers and medical diagnostic substrates.
Mature deployment sits with styryl derivatives. Newer deployment is concentrated in benzoxazole derivatives.
Application:
End-use fragmentation reflects divergent performance requirements across substrate types and processing conditions.
- Paper Whitening:Corrugated board and folding carton specifications from Chinese and Indian e-commerce fulfillment centers are converting previously unbrightened grades. Yellowness index targets and lightfastness requirements vary by paper machine configuration.
- Textile Brightening:Premium apparel segments in Italy and Germany specify benzoxazole and coumarin chemistries for industrial laundering durability. Microencapsulation technology is penetrating military and sportswear applications.
- Detergents:Consumer-facing brands including Unilever and Procter & Gamble mandate Cradle to Cradle and ZDHC MRSL compliance, displacing price-driven procurement models.
- Plastics:Thermal stability requirements in automotive interior components favor benzoxazole derivatives over stilbene alternatives.
- Coatings:UV resistance specifications in high-end architectural and automotive finishes command coumarin-derived premium formulations.
Volume concentration centers on paper whitening. Value expansion is climbing fastest in textile brightening.
End User Industry:
Customer technical capabilities determine specification complexity and service intensity requirements.
- Manufacturing Plants:Integrated paper and plastics producers with in-house laboratories drive co-development relationships and direct technical service engagement.
- Textile Producers:Surat and Tiruppur processing clusters in India are upgrading finishing capabilities, creating first-time specification opportunities in previously commodity-oriented operations.
- Chemical Processors:Toll manufacturers and formulation houses require certified low-impact product lines for EU and North American re-export markets.
- Packaging Facilities:E-commerce fulfillment specifications are pulling brightener demand into corrugated board grades previously shipped unbrightened.
Established relationships sit with manufacturing plants. Emerging relationships are concentrating in packaging facilities.
Distribution Channel:
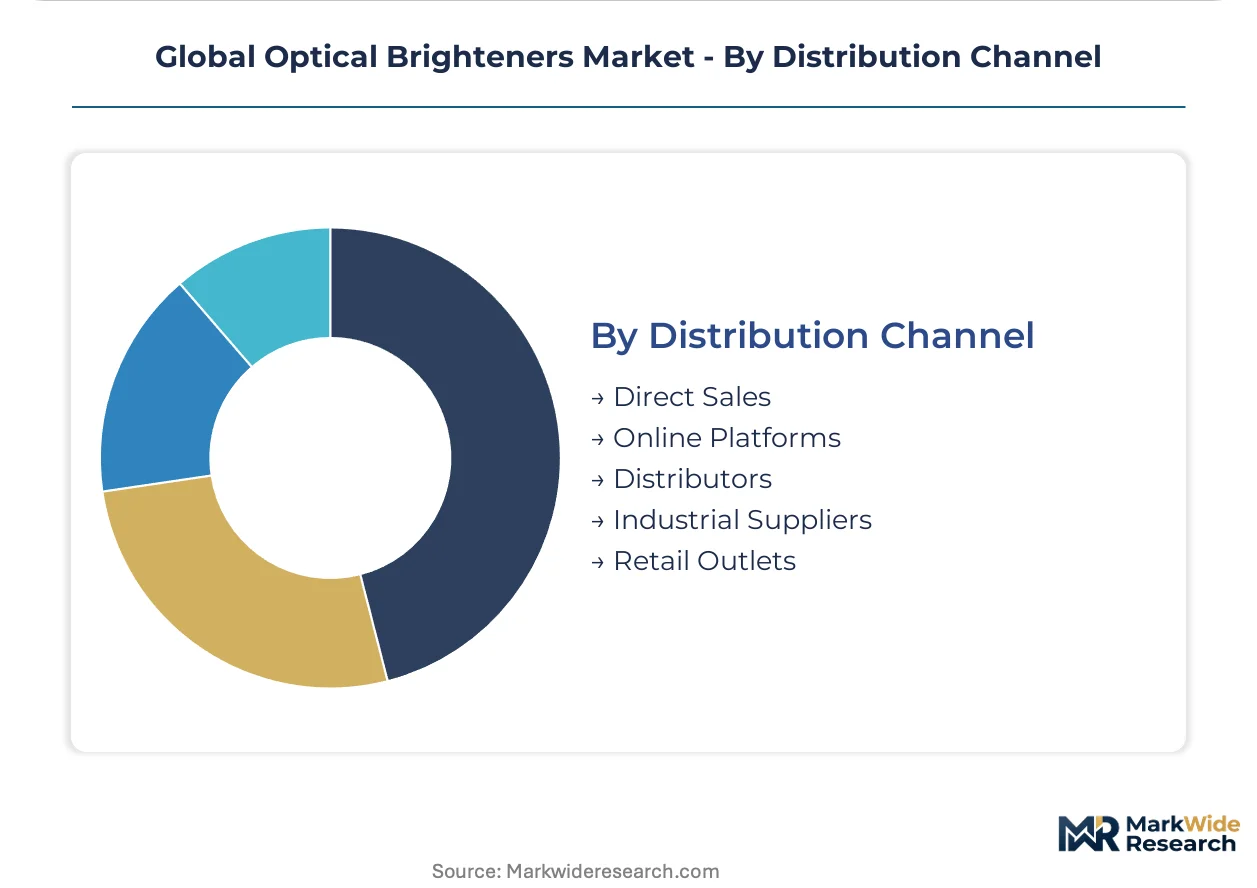
Channel selection reflects customer scale, technical sophistication, and geographic concentration.
- Direct Sales:Mid-size paper mills and textile finishers are bypassing traditional merchant distributors to capture margin and accelerate 12-18 month qualification cycles through technical co-development.
- Online Platforms:Standardized grades for small-batch detergent and coatings formulators enable procurement efficiency with limited technical support.
- Distributors:Regional chemical merchants retain position in fragmented textile and plastics processing markets lacking in-house formulation expertise.
- Industrial Suppliers:Integrated supply contracts with multinational packaging and consumer goods manufacturers bundle brighteners with adjacent process chemicals.
- Retail Outlets:Minimal penetration limited to DIY coatings and small-scale textile operations.
Traditional concentration sits with distributors. Structural shift is gaining share fastest in direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese and Indian packaging facilities are driving volume concentration through e-commerce fulfillment specifications, while German and Japanese processors lead premium-grade adoption for automotive and textile applications.
China
Corrugated board producers in the Yangtze River Delta and Pearl River Delta are converting previously unbrightened grades to meet e-commerce fulfillment specifications from Alibaba and JD.com logistics networks. MEE discharge mandates under the 14th Five-Year Plan are forcing reformulation investments at Zhejiang and Jiangsu chemical parks. The Shandong Peninsula hosts expanding DASDA precursor capacity serving domestic stilbene derivative manufacturers.
Germany
Automotive interior plastics processors in Bavaria and Baden-Württemberg are specifying benzoxazole derivatives for thermal stability above 300°C in dashboard and trim components. REACH Annex XIV authorization timelines for legacy stilbene derivatives are accelerating substitution demand ahead of sunset dates. The North Rhine-Westphalia chemical cluster anchors technical service relationships with mid-size paper mills across Northwestern Europe.
India
Textile finishers in Surat and Tiruppur are upgrading from commodity operations to specification-grade brightening capabilities for export-oriented apparel. BIS certification requirements and DGFT export incentive schemes are reshaping procurement criteria for Tiruppur dyeing units. Maharashtra-based packaging converters are capturing first-time brightener specifications from Amazon India and Flipkart fulfillment networks.
United States
EPA TSCA inventory requirements and state-level discharge permits are compressing the viable chemistry set for Great Lakes paper producers. The Southeast packaging corridor from Georgia to the Carolinas is pulling brightener demand into corrugated board grades previously shipped unbrightened. Texas Gulf Coast chemical processors are requalifying supply chains to serve Unilever and Procter & Gamble sustainability scorecard requirements.
Japan
High-performance sportswear manufacturers in Osaka and Nagoya are adopting microencapsulated brighteners for industrial laundering durability. METI chemical substance management frameworks align with REACH-equivalent restrictions on legacy chemistries. The Kyushu plastics processing belt is converting to benzoxazole derivatives for automotive interior components exported to German OEMs.
Global Optical Brighteners Market Competitive Landscape
German and Swiss producers anchor the premium formulation tier; Chinese and Indian specialists hold volume positions in commodity stilbene derivatives. The vendor base stratifies across three archetypes: integrated multinational chemical conglomerates with captive precursor supply, regional specialists focused on single chemistry families, and toll manufacturers serving brand-owner sustainability mandates. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct technical service relationships displacing traditional distribution channels.
Among integrated chemical conglomerates, BASF and Clariant exemplify the precursor-integrated archetype that sustains cost advantages across benzoxazole derivative production. Huntsman International LLC occupies a position within the specialized textile formulation tier, while Archroma sits within the certified low-impact product segment navigating complex regulatory environments. These three companies represent distinct strategic postures: backward integration into raw materials, application-specific technical service depth, and regulatory compliance certification.
| Leading Market Players |
|---|
| BASF |
| Huntsman International LLC |
| Archroma |
| Milliken & Company |
| Clariant |
| 3V Sigma S.p.A. |
| Eastman Chemical Company |
| Day-Glo Color Corp. |
| Kolorjet Chemicals Pvt Ltd |
| Others |
Supply & Pricing Matrix
Microencapsulation technology adoption in military and sportswear applications is simultaneously elevating formulation premiums and concentrating production capabilities among German and South Korean specialists with proprietary coating expertise. This technology transition compresses replacement frequency for end-users while locking in higher-margin supply relationships that resist commodity pricing pressure.
Pricing Analysis
Volume-margin split separates commodity stilbene derivatives from premium benzoxazole and coumarin chemistries. Three-tier pricing structure across REACH-certified, standard industrial, and unregistered economy grades reflects divergent regulatory compliance investments. Pricing pressure stems from titanium dioxide substitution in paper coatings and fluorescent-free process alternatives capturing premium packaging share. Small-batch detergent formulators exhibit highest price sensitivity; automotive plastics processors demonstrate lowest sensitivity due to thermal stability specifications.
Supply Chain Analysis
China's MEE discharge mandates and India's BIS certification requirements are reshaping raw material sourcing toward domestic-content-compliant facilities. DASDA precursor production clusters in Shandong and Zhejiang provinces; benzoxazole derivative synthesis concentrates in German and Japanese chemical parks. Ortho-toluidine and cyanuric chloride input costs fluctuate with agrochemical demand cycles, creating margin volatility. Single-source vulnerability runs through Chinese DASDA capacity. Distribution runs through direct technical service relationships with mid-size paper mills, bypassing traditional merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Benzoxazole derivative substitution for legacy stilbene chemistries constitutes the dominant technology-transition phase, as REACH sunset dates and thermal stability requirements displace incumbent molecules across European and automotive applications.
For Market Incumbents: Hedge regulatory exposure by accelerating benzoxazole and coumarin substitution portfolios ahead of ECHA authorization timelines. Secure captive DASDA supply through backward integration into Chinese or Indian precursor capacity. Defend margin position by embedding microencapsulation technical service capabilities with military and sportswear manufacturers in Germany and South Korea. For New Entrants and Emerging Players: Enter via Surat and Tiruppur textile upgrading clusters, where first-time specification opportunities exist in previously commodity-oriented finishing operations. Target bio-based coumarin derivatives for EU Green Deal compliance in cosmetics and food-contact applications. Lead with Cradle to Cradle certification to bypass established supplier relationships with Unilever and Procter & Gamble procurement teams. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of regional specialists with REACH-registered substitution portfolios and established automotive qualification relationships. Long-term viability favors suppliers with integrated precursor supply and multi-jurisdictional registration expertise. Watch ECHA substance evaluation acceleration as the inflection signal for chemistry obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DASDA Precursors | Shandong and Zhejiang capacity investments reduce single-source vulnerability for stilbene derivative manufacturers. |
| REACH-Compliant Substitution Portfolio | Benzoxazole and coumarin registration dossiers secure European market access ahead of legacy stilbene sunset dates. |
| Microencapsulation Technical Service Capability | German and South Korean military uniform suppliers pay premiums for industrial laundering durability certification. |
| Direct Mill Relationships | Mid-size paper producers in Finland and Italy bypass distributors to accelerate 12-18 month qualification cycles. |
| Bio-Based Coumarin Development | Lignin-derived precursors meet EU Green Deal circular economy procurement criteria for sustainable formulations. |
Research Methodology
Multi-period observation of ECHA substance evaluation timelines, MEE discharge mandate implementation, and e-commerce fulfillment specification shifts anchored the trend analysis, supplemented by interviews with paper mill technical directors, textile finishing plant managers, automotive plastics procurement leads, and detergent formulator R&D heads. Secondary validation drew from REACH registration databases, customs trade flows, SEC chemical company filings, and GB standards compliance records. Bottom-up volume modeling triangulated against top-down industry association estimates.
Input-output matrix analysis mapped benzoxazole derivative thermal stability specifications, stilbene derivative cost curves, and coumarin premium positioning across paper, textile, detergent, plastics, and coatings end-uses. Segmentation dimensions included chemistry family, application substrate, certification tier, and regional regulatory cluster. CAGRs derived from production capacity expansion announcements, brand-owner procurement scorecard disclosures, and substitution elasticity estimates across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH restriction timelines or breakthrough fluorescent-free whitening technologies. Forecasts reflect documented assumptions on regulatory implementation pace and precursor supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
India Prussian Blue Market