
 North America Advanced Drug Delivery Systems Market | 2026-2036
North America Advanced Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Advanced Drug Delivery Systems Market Analytics
Biologics formulation talent is bifurcating the competitive landscape, with scarce protein-stabilization expertise concentrating at established hubs and leaving mid-tier developers capacity-constrained. Pfizer Inc leverages captive manufacturing networks to sustain fill-finish dominance across parenteral formats. West Pharmaceutical Services Inc anchors its position through elastomer and containment technology leadership. BD competes aggressively in prefillable syringe and autoinjector systems, extending its reach into homecare channels.
Advanced drug delivery systems integrate engineered carriers, controlled-release matrices, and targeted transport mechanisms to modulate pharmacokinetic profiles and improve therapeutic indices. Liposomal encapsulation and biodegradable polymer depots achieve sustained plasma concentrations over weeks to months, reducing dosing frequency for chronic indications. Injectable systems command the largest revenue pool given biologics compatibility and hospital reliance, while nanoparticle platforms represent the fastest-expanding technology segment driven by oncology and mRNA applications. Homecare settings are gaining share as parenteral self-administration devices mature, shifting volume from institutional sites.
FDA Center for Drug Evaluation and Research and Health Canada jointly shape approval pathways for complex generics and novel excipients, with divergence in biosimilar interchangeability standards creating compliance overhead for cross-border launches. The EPA regulates residual solvent thresholds in polymer synthesis, directly affecting biodegradable polymer sourcing costs. Stakeholders must monitor pending FDA guidance on long-acting injectable bioequivalence, as this will determine which platform technologies qualify for abbreviated approval and subsequent market access.
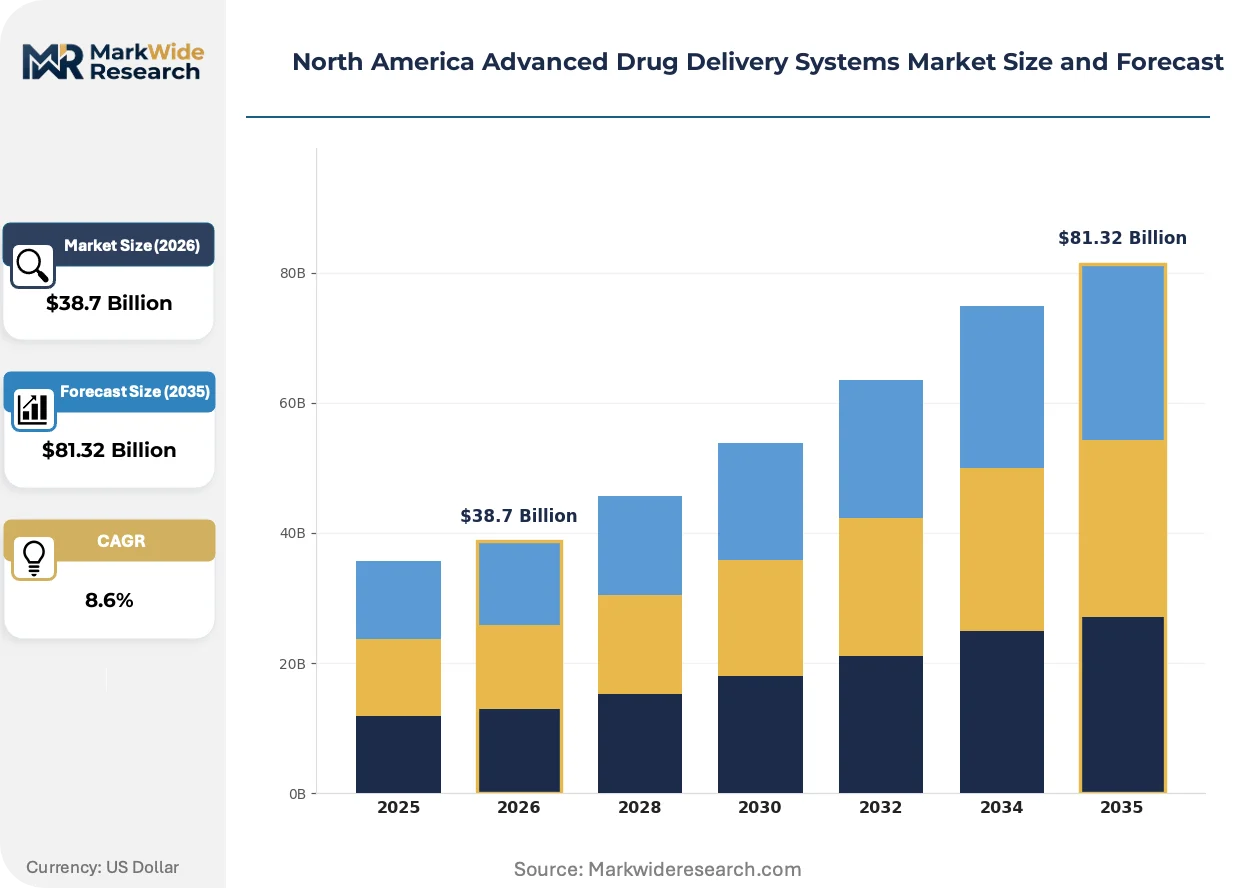
Market Dynamics
FDA guidance on complex generic bioequivalence is fragmenting platform technology strategies across parenteral delivery developers, forcing asset-specific validation investments that concentrate capabilities at established manufacturing hubs.
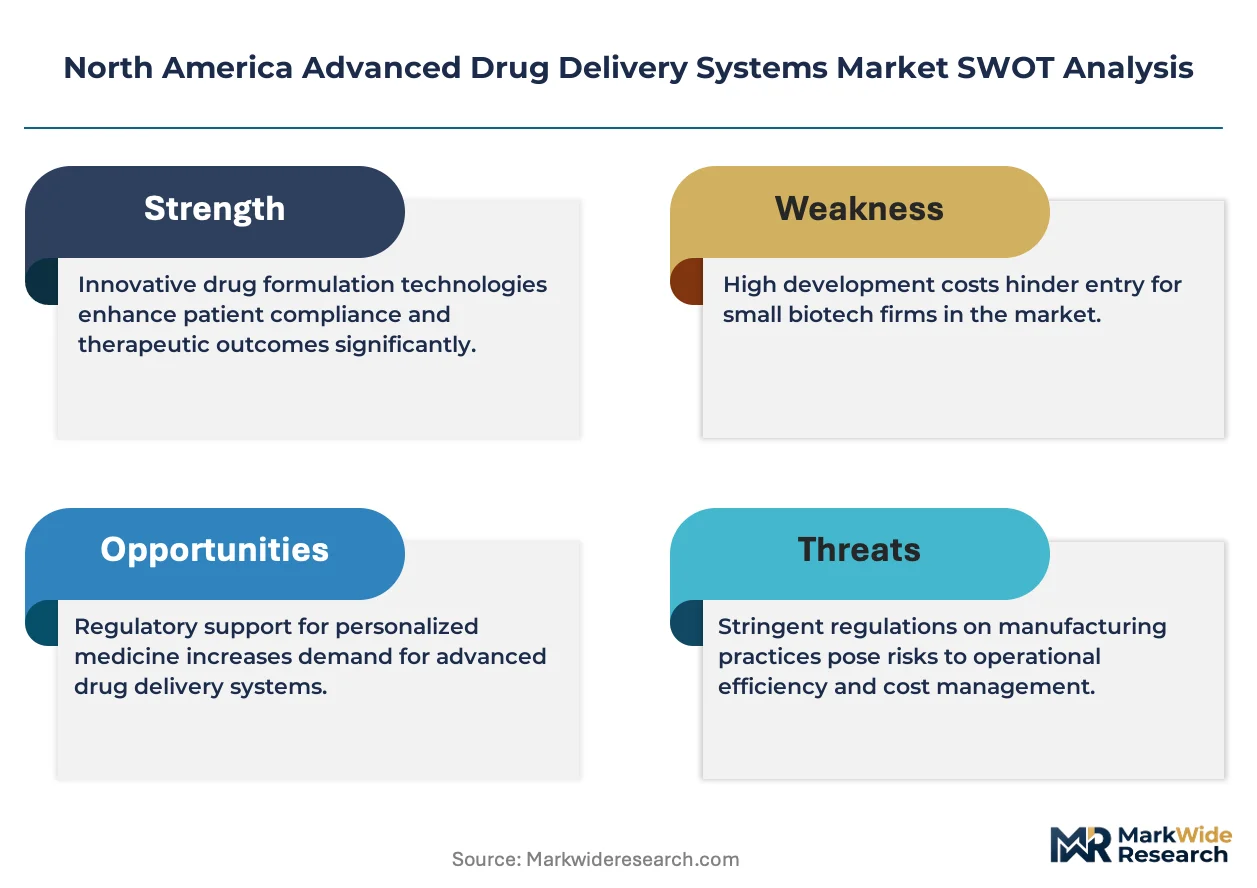
Growth Catalysts
- Biologics pipeline expansion:Monoclonal antibody and mRNA therapeutic candidates are multiplying clinical-stage demand for compatible injectable and nanoparticle carriers.
- Health Canada interchangeability standards:Accelerated biosimilar approval pathways are expanding addressable patient populations for follow-on biologics requiring advanced delivery infrastructure.
- Midwest pharmaceutical corridor concentration:Illinois, Indiana, and Ohio manufacturing clusters are attracting formulation talent and contract development investment.
Market Restraints
- Specialty polymer supply concentration:Biodegradable PLGA and PEG sourcing depends on limited European and Asian chemical suppliers, exposing fill-finish operations to input volatility.
- EPA residual solvent thresholds:Polymer synthesis compliance costs are compressing margins for biodegradable depot formulations.
- Protein stabilization technical ceiling:Aggregation and denaturation risks in long-acting injectables constrain shelf-life extensions and cold-chain simplification.
Strategic Opportunities
- Homecare self-administration channels:Autoinjector and prefillable syringe formats are capturing volume from institutional infusion centers.
- IRA Medicare price negotiation carve-outs:Orphan and pediatric indications retain pricing flexibility, incentivizing rare-disease delivery platform development.
- Lipid nanoparticle-mRNA convergence:Oncology vaccine and gene editing applications are opening new therapeutic categories beyond infectious disease.
Industry Challenges
- Fill-finish aseptic processing talent scarcity:Qualified operators and validation specialists are concentrating at top-tier contract manufacturers, constraining mid-tier capacity expansion.
- Combination product quality system integration:Device-drug submissions require synchronized FDA Center for Devices and Radiological Health and Center for Drug Evaluation and Research compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Advanced Drug Delivery Systems Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Systems, Implants, Inhalers, Transdermal Patches Delivery Mode: Oral, Parenteral, Topical, Pulmonary End User: Hospitals, Homecare Settings, Clinics, Research Institutes Technology: Microencapsulation, Nanoparticles, Liposomes, Biodegradable Polymers |
| Companies Covered | 3M, West Pharmaceutical Services Inc, Pfizer Inc, AstraZeneca, Amgen Inc, Bayer AG, AbbVie Inc, Merck & Co Inc, BD, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Advanced Drug Delivery Systems Market Evolving Landscape
Platform technology diversification is fragmenting established delivery categories as developers pursue indication-specific pharmacokinetic profiles and differentiated intellectual property positions.
Microsphere and in-situ depot technologies are fragmenting sustained-release formulation approaches previously dominated by simple ester prodrugs. Biologics developers in Massachusetts and California are piloting these platforms for quarterly dosing regimens in chronic immunology and endocrinology. The shift is compressing competitive moats around legacy extended-release injectables while opening formulation partnerships between device specialists and polymer suppliers.
FDA pending guidance on long-acting injectable bioequivalence is reshaping abbreviated approval strategies for complex generics. Developers are front-loading pharmacokinetic modeling investments to preempt demonstration requirements. Parenteral platform technologies with established bioequivalence pathways command valuation premiums in licensing discussions.
Hospital procurement consortia are consolidating purchasing authority for standard parenteral formats while fragmenting sourcing for specialty combination products. Integrated delivery networks in Texas and Florida are unbundling device selection from drug procurement, creating direct contracting opportunities for autoinjector manufacturers. This bifurcation is visible in request-for-proposal structures separating commodity syringes from patient-centric delivery systems.
North America Advanced Drug Delivery Systems Market Segmentation
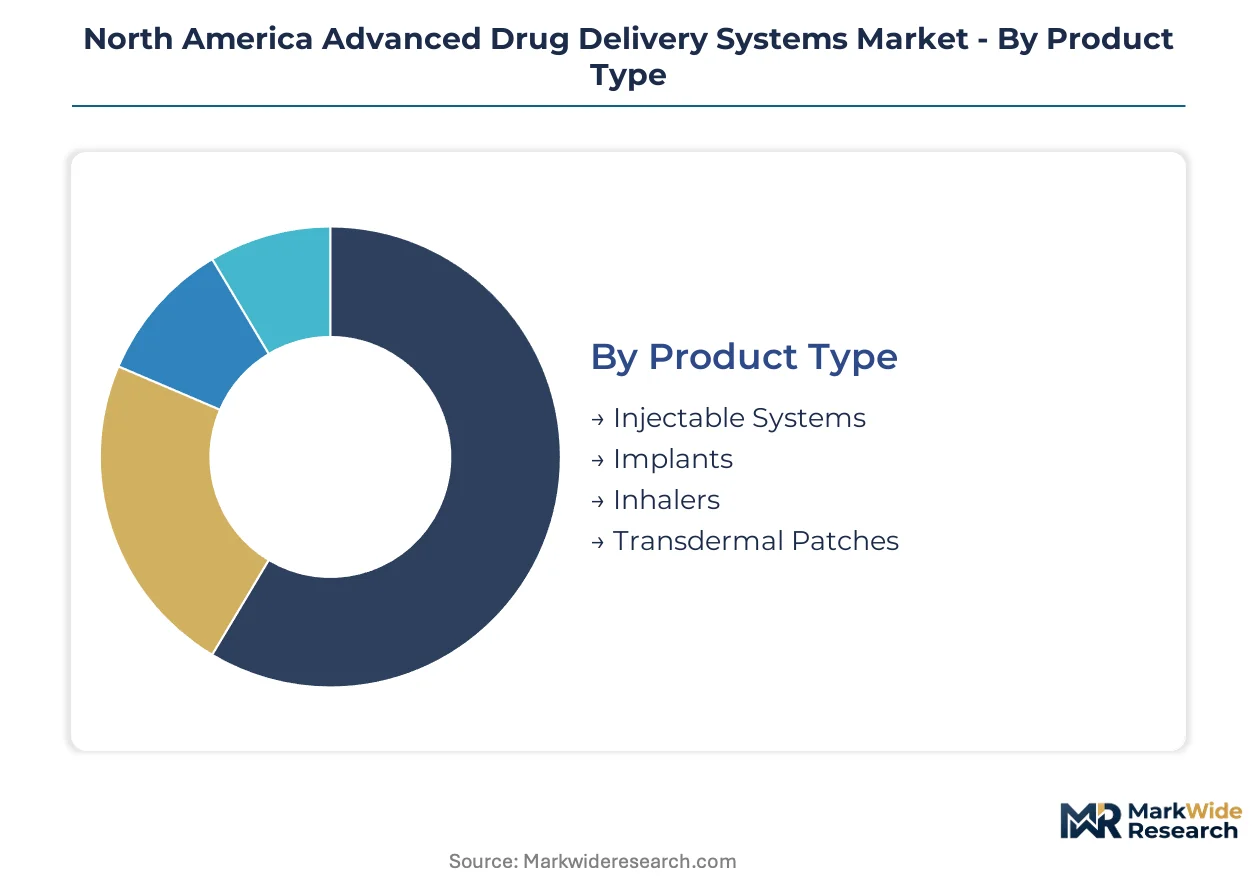
Segmentation in advanced drug delivery systems reveals how formulation technologies, administration routes, and care settings intersect to determine commercial viability. Channel dynamics vary sharply across these dimensions, with institutional procurement dominating high-volume injectables while direct-to-patient models reshape device-intensive categories.
Product Type:
Injectable systems flow primarily through hospital consortia and specialty pharmacy networks, while implant and transdermal formats increasingly bypass institutional procurement through direct physician dispensing and mail-order channels.
- Injectable Systems:Prefilled syringes, autoinjectors, and infusion devices constitute the revenue core, with biologics compatibility driving specification requirements. Massachusetts and New Jersey biotech clusters concentrate demand for high-viscosity protein formulations requiring specialized needle technologies.
- Implants:Biodegradable polymer rods and osmotic pumps achieve zero-order release kinetics for chronic endocrine and psychiatric indications. The Midwest pharmaceutical corridor anchors manufacturing capacity for long-acting depot formulations serving Medicaid and Medicare populations.
- Inhalers:Pressurized metered-dose and dry-powder devices deliver pulmonary therapies across asthma and COPD indications. FDA combination product regulations govern device-drug pairing approvals.
- Transdermal Patches:Matrix and reservoir designs enable passive diffusion of small-molecule hormones and analgesics. Homecare channels capture growing volume as pain management shifts from institutional infusion to patient-controlled delivery.
Injectable systems dominate installed base. Implants represent where expansion concentrates.
Delivery Mode:
Cost tier stratification separates high-complexity parenteral formats from commodity oral and topical alternatives, with reimbursement intensity tracking invasiveness and monitoring requirements.
- Oral:Modified-release tablets and capsules leverage osmotic pump and multiparticulate technologies for chronopharmacology applications. Generic erosion has compressed margins, though complex modified-release platforms retain pricing power through FDA bioequivalence barriers.
- Parenteral:Intravenous, subcutaneous, and intramuscular routes command premium reimbursement given bioavailability assurance and therapeutic monitoring infrastructure. The Northeast corridor concentrates fill-finish capacity for monoclonal antibody and mRNA candidates.
- Topical:Semisolids, foams, and advanced penetration enhancers serve dermatology and localized pain indications. Compounding pharmacy networks fragment distribution compared to centralized hospital procurement.
- Pulmonary:Nebulized and inhaled delivery achieves systemic absorption for biologics and local deposition for respiratory disease. Device development costs and FDA human factors requirements elevate competitive barriers.
Parenteral formats capture the highest reimbursement tiers. Pulmonary delivery is climbing the fastest as inhaled biologics advance through clinical pipelines.
End User:
Volume concentration varies by care setting sophistication, with high-acuity hospitals driving complex infusion demand and homecare settings fragmenting procurement through patient-specific device selection.
- Hospitals:Integrated delivery networks in Texas and Florida consolidate purchasing for standard parenteral formats while maintaining specialty pharmacy carve-outs for oncology and immunology biologics. Aseptic processing requirements and USP 797 compliance elevate supplier qualification barriers.
- Homecare Settings:Self-administration devices and remote monitoring integration are displacing institutional infusion for maintenance therapies. Autoinjector training programs and telehealth reimbursement policies determine adoption velocity.
- Clinics:Ambulatory infusion centers and physician offices handle intermediate-complexity therapies requiring supervision but not overnight admission. Medicare site-of-service payment differentials influence volume migration between settings.
- Research Institutes:Academic medical centers and contract research organizations drive early-phase formulation development and pharmacokinetic characterization. NIH funding concentration in Maryland and California shapes regional demand patterns.
Hospitals retain the largest volume share. Homecare settings are gaining share fastest as device usability and payer incentives align.
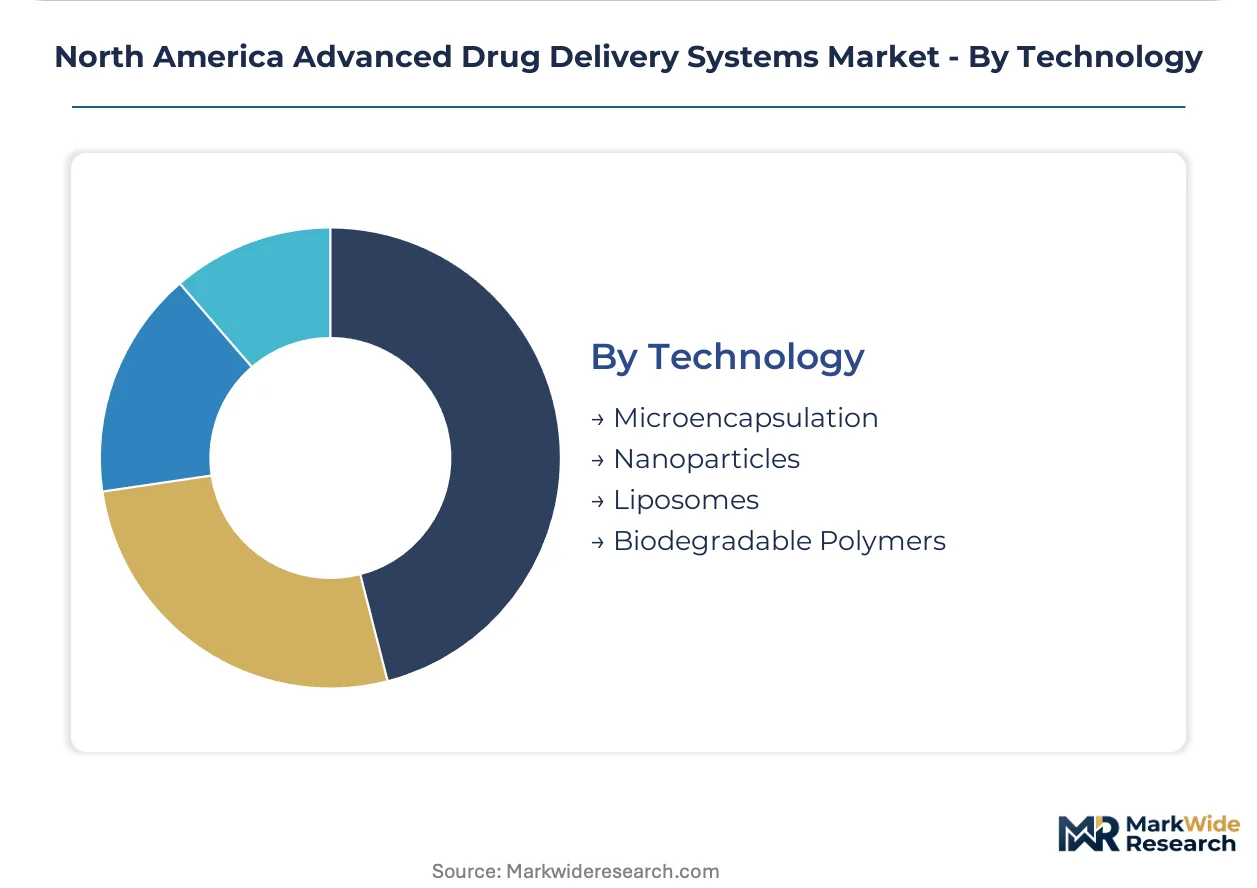
Technology:
Supply concentration for specialty excipients and manufacturing equipment creates tiered access, with established developers controlling platform IP and mid-tier players facing polymer sourcing constraints.
- Microencapsulation:Spray-drying and coacervation techniques enable taste masking, moisture protection, and modified release for oral dosage forms. The technology serves pediatric and geriatric compliance applications where palatability drives adherence.
- Nanoparticles:Polymeric and lipid-based carriers below 200nm achieve enhanced permeability and retention in tumor tissue, plus intracellular delivery for gene therapies. FDA guidance on nanomaterial characterization creates regulatory precedent risk for novel platforms.
- Liposomes:Phospholipid bilayer vesicles encapsulate hydrophilic and hydrophobic payloads for targeted oncology and antifungal applications. Manufacturing complexity and sterile filtration requirements concentrate production at specialized contract manufacturers.
- Biodegradable Polymers:PLGA, PLA, and PEG-PLA copolymers form implantable depots and injectable microspheres for sustained release over weeks to months. EPA residual solvent regulations and limited European chemical supplier concentration expose formulations to input cost volatility.
Biodegradable polymers anchor the largest installed base. Nanoparticles represent the steepest expansion trajectory driven by oncology and mRNA therapeutic pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on complex generics and combination products anchors strategic positioning across the United States, while Health Canada accelerates biosimilar pathways north of the border. Both regulators shape cross-border technology transitions and manufacturing investment flows.
United States
Monoclonal antibody and mRNA therapeutic pipelines multiply demand for compatible parenteral carriers across Massachusetts and New Jersey biotech clusters. FDA Center for Drug Evaluation and Research pending guidance on long-acting injectable bioequivalence is reshaping abbreviated approval strategies. Northeast pharmaceutical corridors concentrate fill-finish capacity for high-viscosity protein formulations requiring specialized needle technologies.
Canada
Health Canada interchangeability standards accelerate biosimilar approval pathways and expand addressable populations for follow-on biologics. Ontario and Quebec manufacturing hubs attract contract development investment from U.S. developers seeking dual-market registration efficiency. Toronto-based formulation specialists concentrate protein-stabilization expertise serving cross-border clinical trials.
Northeast Corridor
Integrated delivery networks in New York and Pennsylvania consolidate purchasing for standard parenteral formats while maintaining specialty pharmacy carve-outs for oncology biologics. USP 797 compliance requirements and aseptic processing standards elevate supplier qualification barriers. Boston-Cambridge biotech density drives early-phase formulation partnerships between device specialists and polymer suppliers.
Midwest Pharmaceutical Belt
Illinois, Indiana, and Ohio manufacturing clusters attract formulation talent and contract development investment for long-acting depot formulations. Medicaid and Medicare population concentration sustains demand for biodegradable polymer implants in chronic endocrine and psychiatric indications. Indianapolis and Cleveland anchor production capacity for quarterly dosing regimens in immunology.
Southwest and Gulf Coast
Texas and Florida hospital procurement consortia unbundle device selection from drug procurement, creating direct contracting opportunities for autoinjector manufacturers. Medicare site-of-service payment differentials influence volume migration from institutional infusion to ambulatory settings. Houston and Miami medical centers pilot homecare self-administration programs with remote monitoring integration.
North America Advanced Drug Delivery Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fill-finish dominance and elastomer technology anchoring premium positions. The competitive landscape bifurcates between captive manufacturing networks and contract development organizations. Three archetypes define the field: integrated pharmaceutical manufacturers with captive delivery capabilities, specialized device and containment technology providers, and diversified healthcare conglomerates with cross-segment synergies. Strategic moves concentrate on capacity expansion in Midwest pharmaceutical corridors and technology licensing partnerships for nanoparticle platform access.
Among integrated pharmaceutical manufacturers, Pfizer Inc and AbbVie Inc exemplify the captive manufacturing archetype, leveraging in-house networks to sustain parenteral format dominance. West Pharmaceutical Services Inc occupies a position within the specialized containment tier, anchoring elastomer and device technology leadership. BD sits within the diversified medical technology segment, competing across prefillable syringe and autoinjector systems with extension into homecare channels.
| Leading Market Players |
|---|
| 3M |
| West Pharmaceutical Services Inc |
| Pfizer Inc |
| AstraZeneca |
| Amgen Inc |
| Bayer AG |
| AbbVie Inc |
| Merck & Co Inc |
| BD |
| Others |
Value Network & Pricing Analysis
Fill-finish capacity utilization above 85% at Northeast pharmaceutical corridors creates pricing power for qualified aseptic operators while compressing margins for mid-tier developers lacking scale. This concentration dynamic elevates price floors for parenteral combination products and forces smaller players toward contract manufacturing partnerships.
Pricing Analysis
Long-term offtake agreements dominate high-volume injectable procurement, with hospital consortia locking multi-year supply contracts for standard syringes and infusion devices. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated combination products from commodity fill-finish services and unvalidated imports. Cost compression in standard parenteral formats is intensifying because integrated delivery networks are unbundling device selection from drug procurement. Specialty pharmacy networks show highest price sensitivity for autoinjector systems, while oncology biologics purchasers prioritize supply assurance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail for standard elastomer components and glass syringes, while strategic stockpiling of specialty PLGA and PEG polymers buffers against European chemical supplier concentration. Biodegradable polymer supply draws from Germany, Netherlands, and China, with residual solvent-grade specifications varying by EPA compliance tier. Raw material dependencies center on pharmaceutical-grade elastomers, borosilicate glass tubing, and lipid excipients for nanoparticle formulations. Single-source vulnerability from limited qualified polymer suppliers exposes fill-finish operations to input volatility. Distribution runs through specialized cold-chain logistics providers serving hospital consortia and direct-to-pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement consortia in Texas and Florida, fragmenting supplier access for mid-tier developers while elevating qualification barriers for new market participants.
For Market Incumbents: Shield formulation partnerships with Midwest manufacturing clusters from erosion by locking exclusive supply agreements for biodegradable polymer inputs. Captive aseptic processing capacity in Illinois and Ohio anchors margin defense against contract manufacturing price wars. Prioritize Health Canada dual-registration pathways to capture biosimilar interchangeability premiums before guidance divergence widens compliance overhead. For New Entrants and Emerging Players: Lead with orphan indication delivery platforms exploiting IRA Medicare price negotiation carve-outs for pricing flexibility. Homecare self-administration channels in Southwest hospital systems offer the most penetrable entry vector given unbundled procurement structures. Target direct contracting relationships with integrated delivery networks separating device selection from pharmaceutical procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized elastomer and containment technology providers serving multi-product biologics pipelines. Long-term viability over the analysis window favors platform-technology developers with established FDA bioequivalence pathways for long-acting injectables. Acquisition targets should demonstrate protein-stabilization expertise and captive Midwest manufacturing presence. Watch pending FDA guidance on complex generic bioequivalence as the critical inflection signal for platform technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Combination Product | CDRH and CDER synchronized review timelines determine market access velocity for device-drug pairings. |
| Manufacturing Scale-Up in Midwest Corridor | Illinois and Ohio capacity expansion captures formulation talent concentration for long-acting depot production. |
| Licensing Agreement for Nanoparticle Platform | Lipid nanoparticle-mRNA convergence opens oncology vaccine categories beyond infectious disease applications. |
| Hospital System Partnership for Autoinjector Distribution | Texas and Florida IDN direct contracting bypasses traditional pharmaceutical procurement bundling. |
| Reimbursement Strategy for Homecare Self-Administration | Medicare site-of-service payment differentials accelerate volume migration from institutional infusion settings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Secondary validation drew from FDA 510(k) filings, Health Canada approval databases, ClinicalTrials.gov protocol registries, and hospital GPO contract repositories. Bottom-up demand modeling across patient population segments triangulated with top-down pharmaceutical expenditure tracking.
Across the projection horizon, the analytical framework modeled segmentation by administration route, technology platform, care setting, and regional regulatory cluster. CAGRs were derived from therapeutic pipeline velocity, biosimilar approval trajectories, and device adoption curves in homecare channels. Forecast inputs incorporated FDA guidance timelines on long-acting injectable bioequivalence and Health Canada interchangeability standard evolution.
The analysis sits within stated boundaries; outcomes outside sustained biologics pipeline expansion and stable EPA residual solvent thresholds would require recalibration. Forecasts reflect assumptions regarding regulatory pathway efficiency and polymer supply continuity. Revision becomes warranted when FDA guidance divergence from Health Canada crosses interoperability thresholds or when specialty polymer input costs spike above historical volatility bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Facial Implant Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Global Optical Biometry Devices Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
US Biomedical Sensors Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Face Mask Device Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Global Positive Airway Pressure Devices Market