
 North America Analgesics Market | 2026-2036
North America Analgesics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Analgesics Market Intelligence
Asset-light contract manufacturing and royalty-based licensing is tilting competitive dynamics toward firms that outsource production while retaining formulation IP. Pfizer Inc. leverages its biologics manufacturing network to sustain supply chain flexibility across multiple dosage forms. Johnson & Johnson anchors its position through consumer-facing brand equity and retail pharmacy channel control. Teva Pharmaceutical Industries Ltd competes on generic portfolio breadth, occupying cost-sensitive segments with high-volume manufacturing scale.
Analgesics comprise pharmacologically active compounds designed to relieve pain through peripheral or central nervous system modulation, including non-steroidal anti-inflammatory agents, opioid receptor agonists, and local anesthetic formulations delivered via oral tablets, transdermal patches, or intravenous solutions. Their primary commercial purpose spans acute post-operative pain, chronic musculoskeletal conditions, cancer-related pain, and neuropathic disorders across institutional and outpatient settings. Non-opioid formulations lead in prescription volume due to favorable safety profiles, while topical analgesics represent the fastest-expanding margin pool as patients and payers seek alternatives to systemic exposure. The oral administration route dominates dispensing patterns, though transdermal delivery is gaining structural traction for chronic pain populations requiring steady plasma levels.
The FDA's REMS framework for extended-release and long-acting opioids shapes product development pipelines, while Health Canada's opioid labeling requirements influence cross-border formulation strategies. State-level prescription drug monitoring programs across the United States add compliance layers that filter market access. Stakeholders must monitor evolving pharmacovigilance mandates and payer formularies to anticipate which analgesic modalities retain reimbursement advantage.
Market Dynamics
The FDA's REMS framework for extended-release opioids is compressing prescribing volumes while simultaneously redirecting R&D investment toward non-opioid mechanisms and abuse-deterrent formulations. This regulatory pressure is the dominant structural force reshaping competitive positioning across the North American analgesics landscape.
Growth Catalysts
- Ambulatory surgical expansion:Same-day discharge protocols in United States outpatient centers are accelerating multimodal analgesia adoption. Post-operative pain management regimens now integrate NSAIDs, local anesthetics, and adjunctive agents to reduce opioid exposure.
- Transdermal delivery advances:Steady-state plasma concentration technologies are enabling chronic pain patients to bypass first-pass hepatic metabolism. Polymer matrix innovations are extending patch wear time from 72 to 96 hours in neuropathic indications.
- State-level PDMP integration:Prescription Drug Monitoring Programs across 49 United States jurisdictions are creating data infrastructure that supports legitimate medical use while flagging diversion patterns. This compliance architecture is building prescriber confidence in non-opioid alternatives.
Market Restraints
- Active pharmaceutical ingredient concentration:Bulk opioid alkaloid production concentrates in limited overseas manufacturing zones. Supply chain vulnerability for codeine, morphine, and oxycodone intermediates creates procurement risk for domestic formulators.
- REMS compliance overhead:The FDA's Risk Evaluation and Mitigation Strategy imposes prescriber certification, patient counseling documentation, and pharmacy verification requirements. These procedural burdens limit product launches and sustain generic incumbency.
- Acetaminophen hepatotoxicity ceiling:Dose capping at 3,000-4,000 mg daily restricts formulation flexibility for combination products. This pharmacological limitation constrains single-pill efficacy in severe acute pain segments.
Strategic Opportunities
- Topical NSAID penetration:Diclofenac sodium gel and lidocaine patch formulations are capturing musculoskeletal pain volume previously managed with oral agents. Pharmacy benefit designs in United States commercial plans are expanding prior authorization flexibility for local administration.
- Canada's opioid labeling harmonization:Health Canada's standardized warning requirements are creating cross-border formulation efficiency. Manufacturers can deploy unified packaging and patient education materials across North American markets.
- Neuropathic pain underdiagnosis:Diabetic peripheral neuropathy and post-herpetic neuralgia remain undertreated relative to prevalence estimates. Specialized pain clinics in United States metropolitan markets are expanding referral pathways for gabapentinoid and SNRI-based regimens.
Industry Challenges
- Formulation chemist scarcity:Expertise in abuse-deterrent polymer matrices and extended-release kinetics concentrates among limited specialist cohorts. Recruitment competition with biologics and oncology sectors is elevating compensation costs.
- Legacy ERP integration:Track-and-trace compliance for opioid distribution requires serialization systems that interface with aging warehouse management platforms. Pharmaceutical wholesalers are absorbing implementation delays and validation expenses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Analgesics Market |
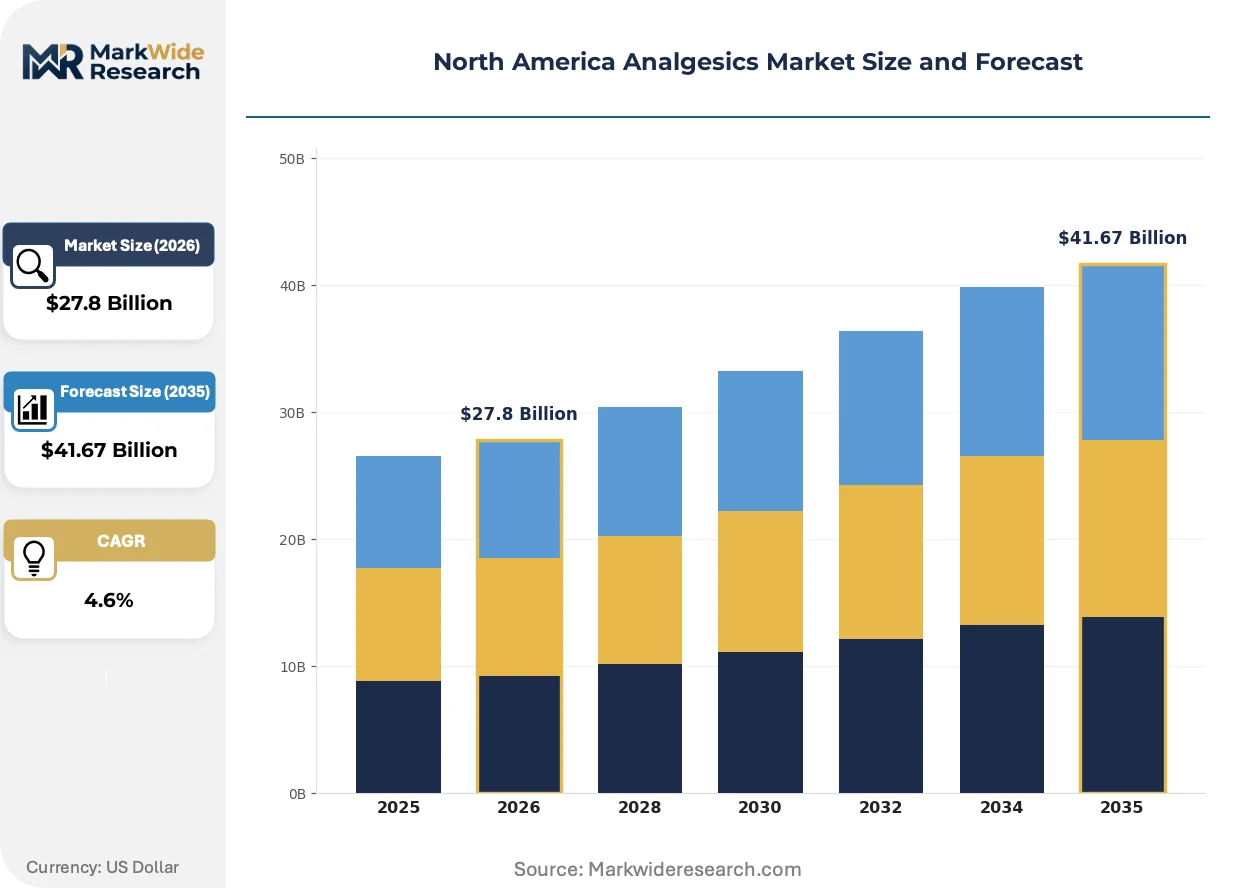
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $41.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Opioid, Opioid, Combination Products, Topical Analgesics End User: Hospitals, Clinics, Home Care, Pharmacies Administration Route: Oral, Intravenous, Transdermal, Rectal Formulation: Tablets, Capsules, Gels, Creams |
| Companies Covered | Johnson & Johnson, Pfizer Inc., Bayer AG, Novartis AG, Sanofi, GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd, AbbVie Inc., Assertio Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Analgesics Market Strategic Shifts & Innovations
Formulation science is collapsing traditional boundaries between systemic and local analgesia, while regulatory architecture and procurement logic are simultaneously rewiring how products reach patients. Three interconnected developments are redefining competitive advantage.
Liposomal bupivacaine formulations are collapsing the efficacy gap between single-injection local anesthetics and continuous catheter techniques. Orthopedic surgical centers in the United States are adopting these extended-release depot technologies for joint replacement protocols. The technology is collapsing inpatient length-of-stay economics and shifting revenue capture toward ambulatory settings.
The FDA's 2023 updated REMS blueprint for extended-release opioids is mandating real-time pharmacy benefit verification and prescriber training recertification. Generic manufacturers face disproportionate compliance burdens relative to branded portfolio breadth. United States extended-release opioid prescriptions are contracting as prescribers migrate toward immediate-release alternatives with lighter documentation requirements.
Integrated delivery networks are consolidating pharmaceutical procurement under centralized pharmacy and therapeutics committees. Hospital systems spanning multiple United States states are negotiating sole-source contracts for perioperative analgesia protocols. This concentration is displacing individual physician preference in favor of formulary-driven standardization across affiliated surgical sites.
North America Analgesics Market Segmentation
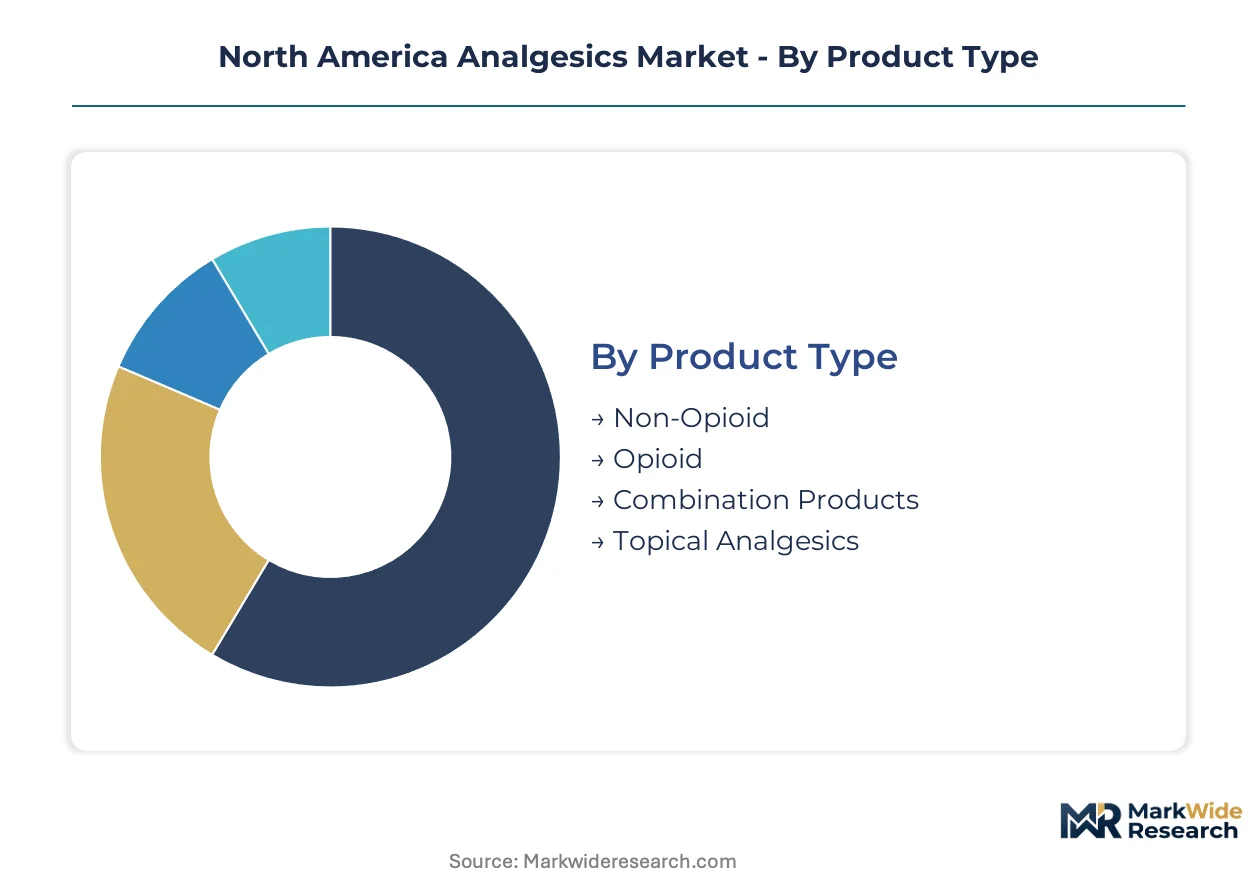
Pain management protocols vary sharply across care settings, from perioperative suites to home-based chronic care. Segmentation reveals how formulation science and regulatory pressure are reallocating volume across administration routes and product categories.
Product Type:
Use cases span acute post-surgical rescue dosing through maintenance therapy for degenerative conditions.
- Non-Opioid:NSAIDs and acetaminophen formulations dominate prescription volume through favorable hepatic and renal safety margins relative to opioid alternatives. United States ambulatory surgical centers are embedding these agents in multimodal protocols to reduce discharge opioid burden.
- Opioid:Morphine, oxycodone, and fentanyl derivatives retain institutional preference for breakthrough cancer pain and major orthopedic recovery. FDA REMS certification requirements are compressing community prescribing while concentrating volume in academic medical centers with compliance infrastructure.
- Combination Products:Fixed-ratio opioid-acetaminophen blends balance efficacy against hepatotoxicity ceilings. Dose capping at 3,000 mg daily restricts formulation flexibility.
- Topical Analgesics:Diclofenac gels and lidocaine patches bypass first-pass metabolism for osteoarthritis and neuropathic indications. Pharmacy benefit managers are expanding prior authorization flexibility for local administration.
Established volume favors Non-Opioid; emerging adoption favors Topical Analgesics.
End User:
Procurement authority concentrates differently across institutional hierarchies and retail channels.
- Hospitals:Integrated delivery networks negotiate sole-source contracts for perioperative analgesia. Pharmacy and therapeutics committees displace individual physician preference with formulary-driven standardization.
- Clinics:Pain management and orthopedic specialty practices drive gabapentinoid and SNRI prescribing for neuropathic conditions. Referral pathways from primary care are expanding in United States metropolitan markets.
- Home Care:Transdermal patches and oral extended-release formulations enable discharge continuity. Medicare reimbursement structures influence product selection for chronic pain populations.
- Pharmacies:Retail chains capture over-the-counter NSAID volume and prescription fulfillment. Direct-to-consumer advertising drives brand preference in United States commercial plans.
Margin concentration tilts toward Hospitals; patient volume expansion centers on Home Care.
Administration Route:
Delivery technology determines pharmacokinetic profiles and regulatory classification.
- Oral:Tablets and capsules dominate dispensing patterns through manufacturing scale and patient familiarity. Immediate-release formulations face lighter documentation burdens than extended-release alternatives.
- Intravenous:Perioperative and emergency department use concentrates in morphine, hydromorphone, and ketorolac. Liposomal bupivacaine depot formulations are collapsing length-of-stay economics in joint replacement protocols.
- Transdermal:Polymer matrix innovations extend patch wear time from 72 to 96 hours. Steady-state plasma technologies serve chronic pain populations requiring consistent exposure.
- Rectal:Alternative for patients with compromised oral absorption or vomiting. Limited formulation availability constrains adoption.
Oral retains volume dominance; Transdermal climbs the fastest on chronic pain demographics.
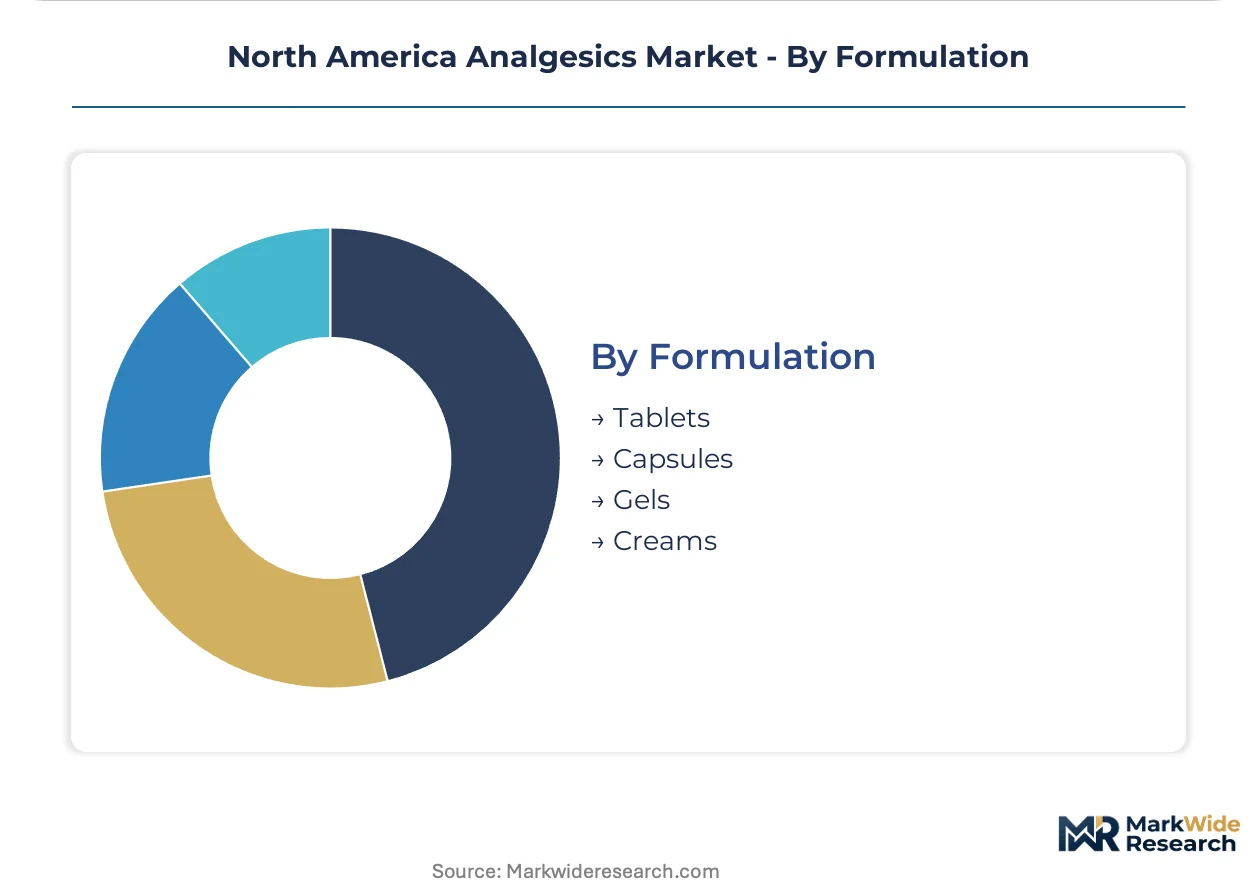
Formulation:
Physical presentation shapes manufacturing complexity and patient compliance.
- Tablets:Immediate-release and extended-release compressed solids anchor generic manufacturing scale. Abuse-deterrent polymer matrices require specialized formulation chemistry expertise.
- Capsules:Gelatin shells enable combination granules and modified-release beads. Content uniformity specifications add validation overhead.
- Gels:Hydrophilic carriers deliver diclofenac and other NSAIDs through dermal penetration. Manufacturing requires homogenization equipment for viscosity control.
- Creams:Oil-in-water emulsions serve localized musculoskeletal applications. Preservative selection affects stability profiles.
Tablets command manufacturing scale; Gels gain share fastest on musculoskeletal volume migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's REMS framework and Health Canada's opioid labeling harmonization are redirecting procurement patterns across North American markets. These regulatory architectures favor non-opioid formulations and abuse-deterrent technologies while compressing legacy opioid volumes.
United States
Integrated delivery networks in Texas and Florida are consolidating perioperative analgesia procurement under sole-source contracts. State-level prescription drug monitoring programs now cover 49 jurisdictions, building prescriber confidence in multimodal protocols. The Philadelphia-Camden corridor anchors generic manufacturing scale for immediate-release tablets.
Canada
Health Canada's standardized opioid warning requirements enable cross-border packaging efficiency for manufacturers serving both markets. Ontario's hospital procurement alliances are driving formulary standardization across acute care networks. The Toronto-Waterloo corridor concentrates pharmaceutical distribution infrastructure serving prairie provinces.
Mexico
Federal Commission for Protection against Health Risks (COFEPRIS) registration pathways are streamlining for imported analgesic formulations. Mexico City metropolitan hospitals are expanding ambulatory surgical capacity with multimodal pain protocols. The Guadalajara pharmaceutical cluster houses contract manufacturing operations serving North American markets.
North America Analgesics Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented prescribing authority. The market structure tilts toward scale-driven incumbents with pharmacy benefit manager relationships and retail distribution depth. Three archetypes dominate: diversified pharmaceutical conglomerates with consumer health divisions, pure-play generic manufacturers with high-volume manufacturing assets, and biologics-focused firms leveraging formulation IP through royalty structures. Competitive moves concentrate on portfolio diversification into abuse-deterrent technologies and strategic partnerships with integrated delivery networks for formulary placement.
Among diversified healthcare conglomerates, Johnson & Johnson and Pfizer Inc. exemplify channel-control strategies that span prescription and over-the-counter segments. Teva Pharmaceutical Industries Ltd. occupies the generic manufacturing archetype with cost-sensitive positioning. These three anchors represent distinct competitive vectors: brand equity and retail penetration, biologics manufacturing flexibility, and high-volume commoditized supply.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc. |
| Bayer AG |
| Novartis AG |
| Sanofi |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd |
| AbbVie Inc. |
| Assertio Holdings Inc |
| Others |
Cost & Logistics Intelligence
Undercapacity in FDA-certified abuse-deterrent formulation capacity across the United States Midwest is elevating spot pricing for contract manufacturing slots while compressing margins for generic tablet producers. This utilization asymmetry rewards manufacturers with captive polymer matrix expertise and penalizes pure-play commoditized suppliers.
Pricing Analysis
Certification level creates the primary spread, with FDA REMS-compliant extended-release formulations commanding premium positioning against standard immediate-release tablets. Three-tier pricing structure across REMS-certified, standard prescription, and economy generic levels reflects compliance overhead and liability exposure. Cost compression in immediate-release opioids is intensifying because prescriber certification requirements favor lighter-documentation alternatives. Hospital procurement committees exhibit lowest price sensitivity due to formulary standardization mandates, while retail pharmacy chains face highest sensitivity from reimbursement rate compression.
Supply Chain Analysis
Upstream alkaloid feedstock draws from concentrated poppy cultivation zones in India, Turkey, and Australia, with morphine and codeine base processing anchored in limited overseas manufacturing corridors. Active pharmaceutical ingredient production hinges on specialized fermentation and extraction capabilities for opioid intermediates. Single-source vulnerability for bulk narcotic raw materials creates procurement risk exposure for domestic formulators facing import licensing delays. Distribution runs through pharmaceutical wholesalers with serialized track-and-trace infrastructure connecting to hospital and retail pharmacy endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated delivery network consolidation across United States metropolitan markets is concentrating procurement authority under pharmacy and therapeutics committees, shifting supplier power toward buyers with sole-source contracting leverage.
For Market Incumbents: Insulate formulation IP through backward integration into specialized polymer matrix production and captive supply of abuse-deterrent excipients. Secure capacity expansion in FDA-inspected facilities to capture contract manufacturing demand from competitors lacking certification infrastructure. Defensive positioning against generic erosion requires deepening relationships with integrated delivery networks through multi-year formulary commitments. For New Entrants and Emerging Players: Build out topical analgesic manufacturing capabilities targeting musculoskeletal pain volume migrating from oral NSAIDs. Prioritize pharmacy benefit manager prior authorization flexibility as the go-to-market angle. White-space concentration sits in neuropathic pain formulations for diabetic peripheral neuropathy, where gabapentinoid alternatives face reimbursement headwinds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers with dedicated REMS-compliant capacity and long-term offtake agreements with branded portfolio companies. Acquisition target archetype: mid-scale formulators with polymer matrix expertise and existing FDA establishment registrations. Signal to monitor: Health Canada opioid labeling harmonization progress as cross-border packaging efficiency catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Development | FDA REMS compliance creates defensible positioning against generic substitution pressure. |
| Integrated Delivery Network Partnership | Hospital system sole-source contracts displace physician preference with formulary standardization. |
| Transdermal Delivery Platform Expansion | Polymer matrix innovations extend patch wear time for chronic pain patient retention. |
| Topical NSAID Manufacturing Scale-Up | Diclofenac gel capacity captures musculoskeletal volume shifting from systemic exposure. |
| Cross-Border Regulatory Harmonization | Unified packaging for Health Canada and FDA requirements reduces compliance overhead. |
Research Approach
Operator-level perspectives from formulary directors, hospital procurement managers, regulatory affairs leads, and pharmacy benefit access specialists anchored the qualitative base. Primary fieldwork combined with secondary validation against FDA REMS documentation, CMS Medicare reimbursement databases, ClinicalTrials.gov protocol registrations, and integrated delivery network contract disclosures. Bottom-up prescription volume modeling and top-down pharmaceutical spending triangulation ensured cross-verification of market sizing assumptions.
Scenario-bracketing across regulatory enforcement intensity, opioid prescribing volume elasticity, and transdermal adoption curves framed the analytical envelope. Segmentation dimensions included product type, administration route, end-user setting, and regional regulatory cluster across the projection horizon. CAGRs derived from patient population epidemiology, procedure volume forecasts, and historical pricing trajectory analysis informed value expansion estimates.
Stress conditions across FDA REMS expansion scope, DEA production quota adjustments, and pharmacy benefit manager formulary exclusion severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding prescriber certification compliance rates and generic erosion timelines. Cross-checking against IQVIA prescription audit data and hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Adapalene Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Pancrelipase Market