
 Pocket Ventilation Systems Market | 2026-2036
Pocket Ventilation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pocket Ventilation Systems Market Analytics
Underground mining contractors are reorganizing procurement priorities around wearable respiratory protection as shaft depths exceed conventional airflow limits. Pentair leverages its filtration engineering heritage to dominate portable system specifications for confined-space entry. Trox GmbH anchors European supply through its climate-control manufacturing scale, while Yokogawa Electric competes on sensor-integrated monitoring architectures that track real-time air quality metrics.
Pocket ventilation systems are compact, self-contained breathing air devices designed to deliver filtered or supplied air to individual users in oxygen-deficient or contaminated environments, typically incorporating battery-driven blowers, HEPA or activated carbon filtration stages, and adjustable facepiece interfaces rated for particulate, gas, or vapor hazards. Their primary industrial purpose is to sustain worker respiratory safety where ambient ventilation proves inadequate or impossible. Stationary systems still occupy the largest installed base in permanent mining infrastructure, yet portable and battery-operated configurations represent the fastest-expanding margin pools as mobile workforce models displace fixed installations. The technology dimension shows mechanical blower systems retaining dominance in heavy industrial settings while hybrid and solar-powered variants penetrate remote construction and disaster relief deployments where grid access remains absent.
OSHA's confined-space standards and EPA particulate exposure limits directly shape product certification requirements and procurement compliance timelines across North American industrial buyers. The EU's PPE Regulation and CE marking protocols govern market access for any system sold into European mining or construction channels, forcing design adaptations around interoperability testing. Stakeholders must monitor how battery chemistry regulations from transport safety agencies and emerging carbon footprint disclosure rules reshape supply chain sourcing for lithium-ion dependent portable units.
Market Dynamics
Deepening shaft operations in underground mining are compressing conventional ventilation economics, forcing contractors toward personal respiratory units as primary rather than supplementary protection. Battery chemistry advances and OSHA enforcement convergence are accelerating this equipment transition.
Growth Catalysts
- OSHA Confined-Space Enforcement:Tighter inspections at US mining operations are mandating redundant breathing air systems where natural airflow falls below 19.5 percent oxygen. Procurement timelines for compliant equipment have shortened from 18 months to 6 months.
- Lithium-Ion Energy Density Gains:New cell chemistries are extending blower runtime to 8-hour shifts without weight penalties. Australian and Canadian remote sites are electrifying fleets faster than grid extension permits.
- Tunneling Depth Records:South African platinum operations now exceed 4,000 meters vertical depth where ambient ventilation fails entirely. Personal systems have become the only viable respiratory solution at these extremes.
Market Restraints
- Cobalt Supply Concentration:Democratic Republic of Congo dominates battery-grade cobalt refining, exposing portable unit manufacturers to price volatility and ethical sourcing audits that delay certification.
- Filtration Media Cost Structure:Activated carbon and HEPA substrate prices track petrochemical feedstock indices, compressing margins on replacement cartridge business lines.
- Technical Limitation — Heat Dissipation:Compact blower motors in sealed housings face thermal runaway risks above 45°C ambient, excluding deployment in certain deep-earth geothermal zones.
Strategic Opportunities
- Disaster Response Procurement Channels:FEMA and UN humanitarian stockpiling programs represent untapped volume for solar-rechargeable variants. These buyers prioritize interoperability over feature depth.
- EU Green Deal Carbon Border Adjustments:Battery carbon footprint disclosure requirements will favor European-assembled units with verified supply chains. Early compliance creates preference lock-in.
- Sensor-Filtration Convergence:Integrating real-time particulate and gas detection with automatic blower speed modulation addresses both safety and battery conservation. Yokogawa Electric and similar automation specialists are entering this white space.
Industry Challenges
- Respiratory Protection Specialist Shortage:Fit-testing and maintenance certification programs lack sufficient instructors to match equipment deployment rates. Training backlogs extend commissioning timelines.
- Legacy Mine Infrastructure Integration:Charging station installation in century-old shaft systems requires electrical retrofitting that conflicts with heritage preservation codes in certain jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pocket Ventilation Systems Market |
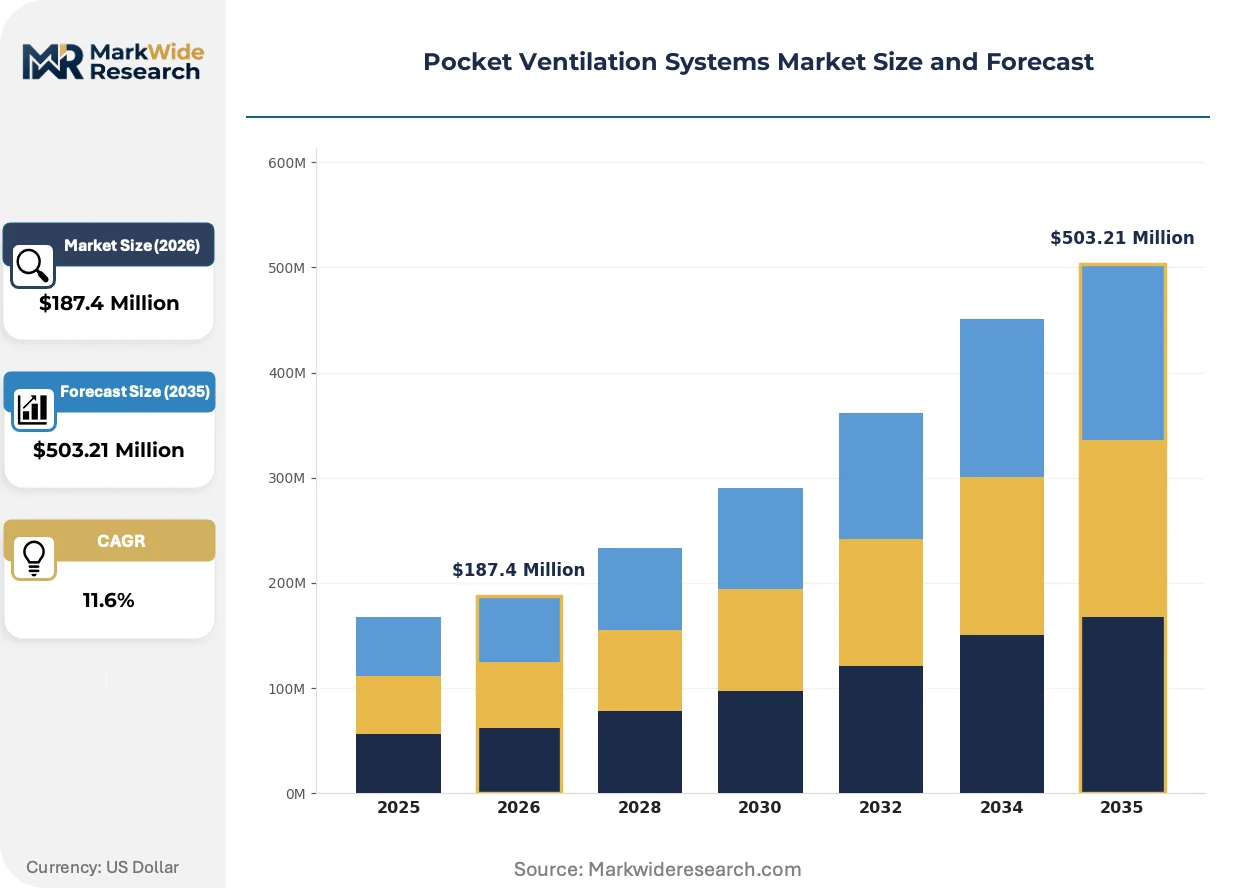
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Rechargeable, Battery-Operated Application: Construction, Mining, Indoor Farming, Disaster Relief Technology: Mechanical, Natural, Hybrid, Solar-Powered End User: Industrial Workers, Agricultural Employees, Emergency Responders, Recreational Users |
| Companies Covered | Pentair, Yokogawa Electric, RLE Technologies, Thermocoax, Airtherm Corporation, Vershwal Engineering Pvt Ltd, Forbes Marshall, Langbein and Engelbracht, Trox GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pocket Ventilation Systems Market Evolving Landscape
Solid-state battery architectures and MEMS sensor integration are compressing device footprints while expanding functional scope. The competitive frontier has shifted from airflow capacity to intelligent power management and predictive maintenance.
Solid-state lithium-metal cells are miniaturizing energy storage without sacrificing safety margins against thermal runaway. Underground contractors in Chile and Finland are piloting these configurations for 12-hour extended shifts. The technology is miniaturizing what was previously belt-worn battery packs into shoulder-integrated modules that distribute load ergonomically.
REACH authorization requirements for nickel compounds are forcing filtration media suppliers to reformulate activated carbon substrates. European manufacturers face 18-month retesting cycles for CE marking renewal. Mining procurement officers in Germany and Poland are prioritizing suppliers with pre-validated alternative chemistries to avoid supply interruption.
Rental and lease-to-own models are displacing capital purchase for seasonal tunneling contractors. Equipment-as-a-service providers in Western Australia now bundle maintenance, certification, and battery swap logistics into per-shift pricing. This shift is most visible in fly-in-fly-out operations where asset ownership creates stranded equipment risk between project cycles.
Pocket Ventilation Systems Market Segmentation
Pocket ventilation systems fragment across four critical dimensions that determine procurement economics and technology selection. Product configuration dictates capital intensity and mobility constraints, while end-use applications impose divergent certification and runtime requirements that reshape supplier priorities.
Product Type:
Stationary systems face the strongest substitution pressure as mining contractors pivot toward workforce mobility and shaft electrification programs accelerate.
- Portable:Self-contained units with shoulder-integrated blowers and replaceable filtration cartridges designed for confined-space entry. Australian fly-in-fly-out contractors in Western Australia and Queensland are standardizing these for 8-hour shift coverage as lithium-ion energy density eliminates weight penalties.
- Stationary:Fixed-installation breathing air stations with centralized compressor-fed manifold systems and multiple user drop points. South African platinum operations below 4,000 meters vertical depth still deploy these where shaft infrastructure permits permanent electrical installation.
- Rechargeable:Units with swappable battery modules enabling continuous operation through hot-swap protocols during extended shifts. Finnish underground contractors pilot solid-state architectures for 12-hour runtime without thermal runaway risks.
- Battery-Operated:Compact blower systems with integrated lithium-ion cells optimized for rapid deployment without external power infrastructure. Canadian remote mining sites in Ontario and British Columbia prioritize these where grid extension timelines exceed project schedules.
Stationary configurations anchor the volume base in permanent mining infrastructure while battery-operated units gain share at the steepest rate across electrifying remote sites.
Application:
Cost tier differentiation separates capital-intensive mining procurement from price-sensitive seasonal deployment in construction and agriculture.
- Construction:Short-duration respiratory protection for tunneling, demolition, and concrete cutting operations with emphasis on rapid deployment and rental economics. German infrastructure contractors favor lease-to-own models for seasonal project cycles.
- Mining:Heavy-duty specifications demanding redundant breathing air systems, continuous particulate monitoring, and OSHA-compliant fit-testing documentation. Chilean copper operations drive specifications for sensor-integrated architectures.
- Indoor Farming:Ammonia and particulate filtration for controlled-environment agriculture with lower airflow requirements and extended cartridge life. Dutch greenhouse operators in Westland cluster prioritize activated carbon formulations for nitrogen compound capture.
- Disaster Relief:Solar-rechargeable configurations for humanitarian deployment with interoperability standards overriding feature depth. FEMA stockpiling programs and UN humanitarian logistics channels represent emerging volume pools.
Mining applications dominate current procurement value while disaster relief channels expand most quickly as institutional stockpiling programs mature.
Technology:
Maturity gradients separate proven mechanical systems from emerging hybrid architectures still navigating certification timelines.
- Mechanical:Motor-driven blower systems with fixed-speed airflow delivery and established HEPA filtration stages. Heavy industrial settings in Poland and Germany specify these for reliability in high-particulate environments.
- Natural:Passive airflow designs relying on pressure differentials without powered components, limited to shallow-depth applications with favorable ventilation geometry. Rarely specified for new procurement.
- Hybrid:Configurations combining grid power, battery backup, and solar trickle-charging for operational flexibility across variable infrastructure. Remote construction sites in Western Australia deploy these where diesel generator access is intermittent.
- Solar-Powered:Photovoltaic-integrated units with direct panel-to-blower coupling for off-grid deployment. Disaster relief operators in Pacific Island nations prioritize these for logistical independence.
Mechanical technology retains the largest installed base while hybrid systems climb the fastest as electrification programs bridge grid and off-grid operations.
End User:
Customer type fragmentation creates divergent purchasing authority patterns between enterprise procurement and individual acquisition.
- Industrial Workers:Enterprise-provisioned respiratory protection with centralized maintenance, fit-testing, and certification programs. Mining contractors in Canada and Australia drive specifications through consolidated procurement offices.
- Agricultural Employees:Smaller-scale deployment with price sensitivity and seasonal usage patterns favoring rental or entry-tier purchase. Dutch and Belgian greenhouse cooperatives aggregate demand for volume discounts.
- Emergency Responders:Institutional procurement through civil defense and humanitarian agencies with interoperability requirements and stockpile rotation protocols. FEMA and UN channels standardize specifications for cross-border deployment compatibility.
- Recreational Users:Individual consumers seeking respiratory protection for hobbyist metalworking, home renovation, or preparedness applications. Limited market presence with minimal regulatory oversight.
Industrial workers anchor procurement volume while emergency responder channels show the steepest specification advancement as institutional stockpiling scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian manufacturers export battery-operated pocket ventilation systems to Canadian mining contractors facing electrification deadlines at remote Ontario and British Columbia sites.
United States
Deep-shaft copper operations in Arizona and Utah drive procurement of redundant breathing air systems. OSHA confined-space enforcement compresses equipment certification timelines from eighteen months to six. Pittsburgh-based mining contractors standardize specifications for sensor-integrated architectures tracking real-time particulate exposure.
Australia
Fly-in-fly-out contractors in Western Australia and Queensland prioritize portable units with 8-hour lithium-ion runtime. The country's national mining safety regulator mandates fit-testing documentation for all respiratory protection deployed below 1,000 meters vertical depth. Pilbara iron ore clusters pilot solid-state battery configurations for extended shift coverage.
Germany
REACH authorization requirements for nickel compounds force filtration media suppliers into 18-month retesting cycles for CE marking renewal. The EU's PPE Regulation governs market access for systems sold into European mining channels. Ruhr Valley underground operations specify mechanical blower systems for reliability in high-particulate environments.
Canada
Remote site electrification programs in Ontario and British Columbia accelerate faster than grid extension permits. Health Canada and the national transportation safety agency regulate battery chemistry standards for underground deployment. Sudbury nickel belt contractors standardize battery-operated units where permanent electrical infrastructure remains uneconomical.
Chile
Copper operations exceeding 3,000 meters vertical depth deploy personal respiratory systems as primary protection where ambient ventilation fails. The national mining regulator enforces redundant breathing air mandates for confined-space entry. Antofagasta and Calama mining clusters drive specifications for sensor-integrated monitoring architectures.
Pocket Ventilation Systems Market Competitive Landscape
Listed leaders compete with private specialists across filtration engineering and climate-control manufacturing dimensions. The vendor base separates into three tiers: diversified industrial conglomerates with respiratory protection divisions, dedicated ventilation equipment fabricators, and automation specialists integrating sensor architectures. Consolidation pressure concentrates among mid-scale European manufacturers facing REACH compliance cost escalation. Dominant competitive moves include strategic partnerships for battery supply security and geographic expansion into Australian and Canadian electrification programs.
Within the diversified industrial tier, Pentair exemplifies filtration engineering heritage applied to portable system specifications. Trox GmbH anchors European supply through climate-control manufacturing scale. Yokogawa Electric occupies a position among automation specialists converging sensor integration with blower speed modulation for battery conservation.
| Leading Market Players |
|---|
| Pentair |
| Yokogawa Electric |
| RLE Technologies |
| Thermocoax |
| Airtherm Corporation |
| Vershwal Engineering Pvt Ltd |
| Forbes Marshall |
| Langbein and Engelbracht |
| Trox GmbH |
| Others |
Value Network & Pricing Analysis
Filtration media manufacturing scale in Germany and Poland anchors European price floors for activated carbon and HEPA substrates, concentrating procurement leverage among vertically integrated suppliers while compressing margins for cartridge-only assemblers dependent on spot-market feedstock purchases.
Pricing Analysis
Mechanical blower systems command legacy-generation premiums against battery-operated configurations, while solid-state architectures launch at next-generation price points reflecting lithium-metal cell costs. Three-tier pricing structure across premium sensor-integrated, standard battery-operated, and economy mechanical levels separates OEM procurement from rental fleet operators and individual agricultural buyers. Pricing pressure stems from cobalt price volatility in Democratic Republic of Congo refining, squeezing portable unit margins most acutely among mid-scale manufacturers lacking long-term offtake agreements. Seasonal tunneling contractors exhibit highest price sensitivity, favoring per-shift rental models, whereas Chilean copper operators prioritize runtime reliability over unit economics.
Supply Chain Analysis
Inventory cycles for lithium-ion cells extend to 16-20 weeks from cell manufacturers in South Korea and Japan, constraining rapid scaling for Australian and Canadian electrification deadlines. Activated carbon substrates draw from coconut shell processors in Sri Lanka and Indonesia, while HEPA media production concentrates in Germany and the United States. Single-source vulnerability in cobalt sulfate refining exposes portable unit assemblers to ethical sourcing audit delays. Distribution runs through mining equipment OEMs and specialized respiratory protection distributors with certified service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
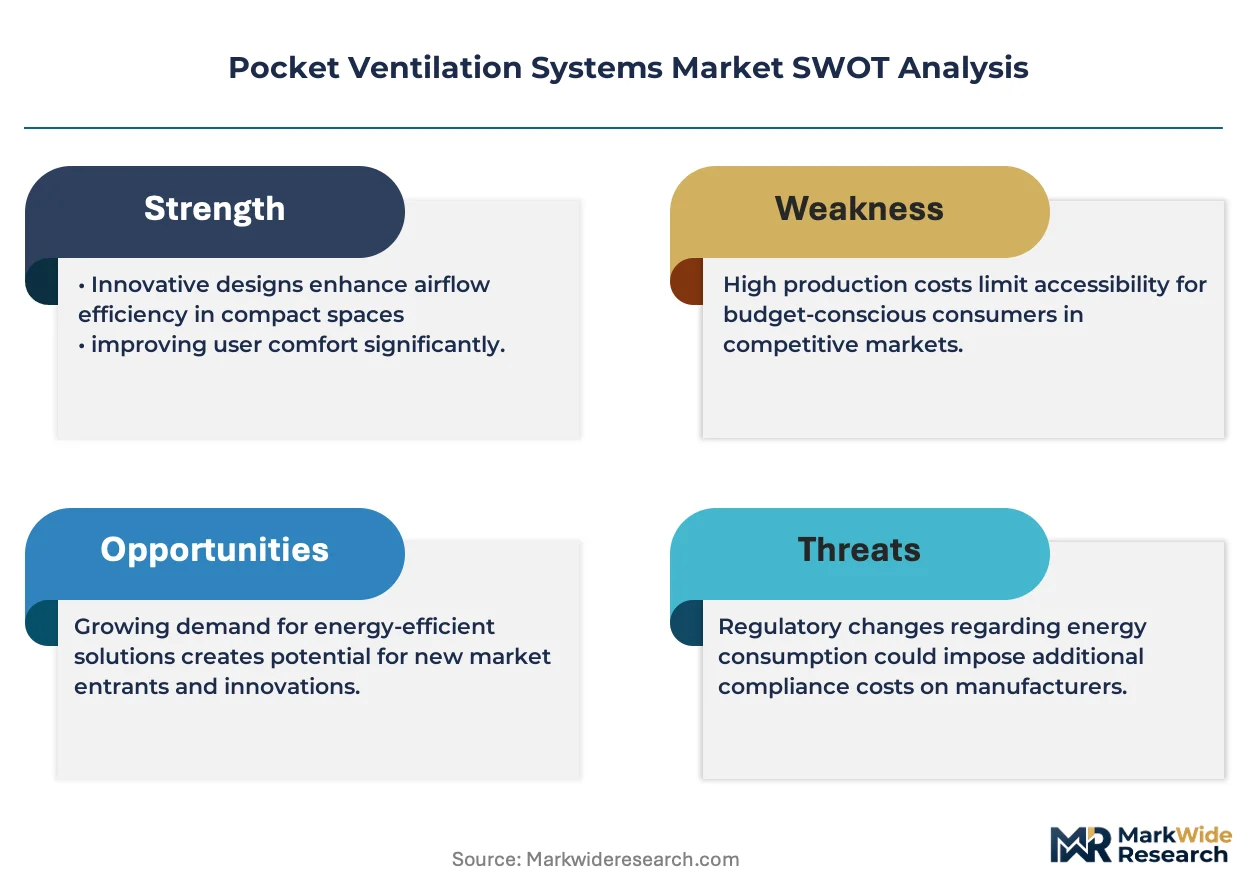
OSHA confined-space enforcement convergence with solid-state battery commercialization creates a high-growth disruption window, compressing procurement timelines while extending operational runtime specifications.
For Market Incumbents: Secure cobalt supply through long-term offtake agreements with Australian or Indonesian nickel-cobalt processors to insulate against Democratic Republic of Congo concentration risk. Secure sensor-integrated architecture patents ahead of Yokogawa Electric and automation specialist entrants, locking specification control at Chilean and Australian mining clusters where real-time monitoring mandates tighten.
For New Entrants and Emerging Players: Differentiate on solar-rechargeable configurations for FEMA and UN humanitarian stockpiling channels where interoperability standards override feature depth and incumbent presence remains minimal. Target disaster relief procurement officers with modular platform designs enabling rapid battery chemistry swaps as regulations shift, bypassing the certification backlog that slows established players.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-as-a-service providers bundling maintenance, certification, and battery swap logistics into per-shift pricing for Western Australian fly-in-fly-out contractors. Acquisition candidates with pre-validated REACH-compliant filtration media formulations offer 5-10 year regulatory insulation as European retesting cycles lengthen. Watch solid-state battery pilot outcomes in Finnish and Chilean underground operations as inflection indicators for technology-generation transitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive lithium-ion supply secures Australian and Canadian electrification program participation against cobalt volatility. |
| Sensor-Filtration Platform Integration | Real-time particulate modulation addresses OSHA compliance while conserving battery runtime at extreme depths. |
| REACH-Compliant Media Certification | Pre-validated activated carbon substrates avoid 18-month European retesting delays that interrupt German procurement. |
| Equipment-as-a-Service Model Launch | Per-shift pricing with bundled maintenance converts capital-averse seasonal contractors to recurring revenue. |
| Humanitarian Channel Specification Capture | FEMA and UN interoperability standards create preference lock-in for solar-rechargeable modular platforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mine safety officers, respiratory protection procurement managers, filtration media R&D directors, and equipment-as-a-service fleet operators. Secondary validation drew from OSHA enforcement bulletins, EPA particulate exposure databases, EU PPE Regulation compliance registries, and lithium-ion transport safety agency filings. Bottom-up unit deployment estimates from Australian and Canadian mining clusters were triangulated against top-down market sizing from filtration media production volumes.
Across the analysis window, the forecasting framework modeled product type segmentation by runtime specification, application tier by certification intensity, technology generation by energy storage architecture, and end-user category by procurement centralization. CAGRs were derived from shift-coverage demand curves and electrification program timelines. Key inputs included lithium-ion energy density improvement trajectories, shaft depth extension records from South African platinum operations, and OSHA inspection frequency adjustments.
The analysis sits within stated boundaries; outcomes outside sustained lithium-metal cell cost reduction or accelerated REACH authorization timelines would require recalibration. Forecasts reflect documented assumptions around battery chemistry regulatory stability and mining electrification funding continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Deaver Retractor Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Bariatric Beds Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
Global Microcatheter Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Face Mask Device Market
Medical Devices
Polysomnography Devices Market