
 Global Optical Biometry Devices Market | 2026-2036
Global Optical Biometry Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Biometry Devices Market Foresight
Aftermarket service revenue is fragmenting across installed bases as manufacturers compete for recurring calibration and software upgrade contracts. Carl Zeiss AG leverages its dense European service network to lock in multi-year maintenance agreements. Haag-Streit Group anchors its position through specialized training programs tied to device placements. Nidek Co. Ltd. competes by extending remote diagnostic capabilities that reduce field engineer dispatch costs.
Optical biometry devices employ low-coherence interferometry or swept-source optical coherence tomography to measure axial length, anterior chamber depth, and corneal curvature with sub-micron precision for intraocular lens power calculation. Swept-source OCT devices now command premium positioning due to their ability to penetrate dense cataracts and capture posterior segment detail through segmented wavelength scanning. Among applications, cataract surgery pre-op represents the mature revenue base while anterior segment analysis emerges as the fastest-expanding use case driven by corneal refractive procedure volumes.
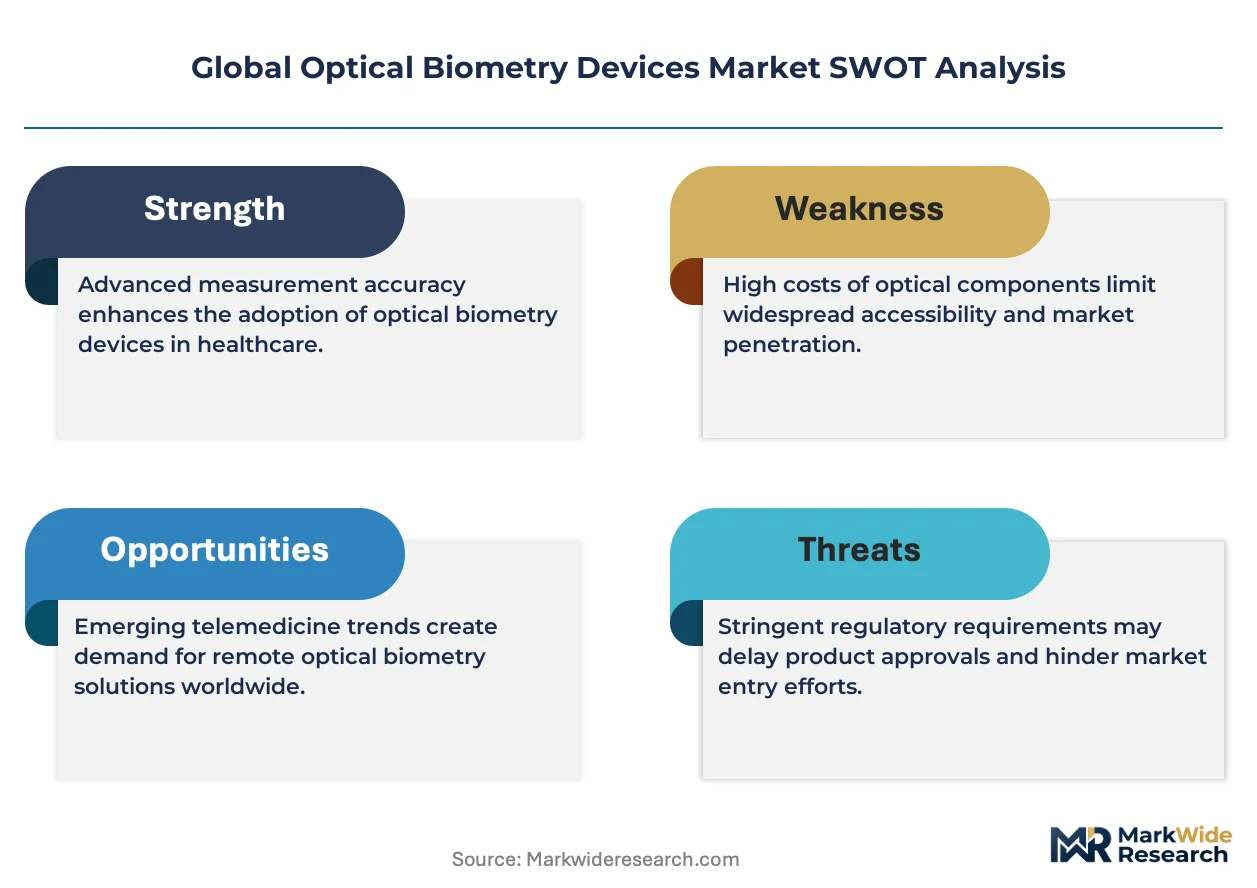
FDA 510(k) clearance pathways and EU MDR conformity assessments impose substantial clinical validation burdens on new device introductions, effectively filtering market access to well-capitalized manufacturers. ISO 10993 biocompatibility testing and IEC 60601 electrical safety standards further shape component sourcing and design architecture. Stakeholders must monitor how FDA guidance on artificial intelligence-enabled diagnostic outputs and EMA harmonization efforts around software-as-a-medical-device classifications reshape competitive barriers and partnership requirements.
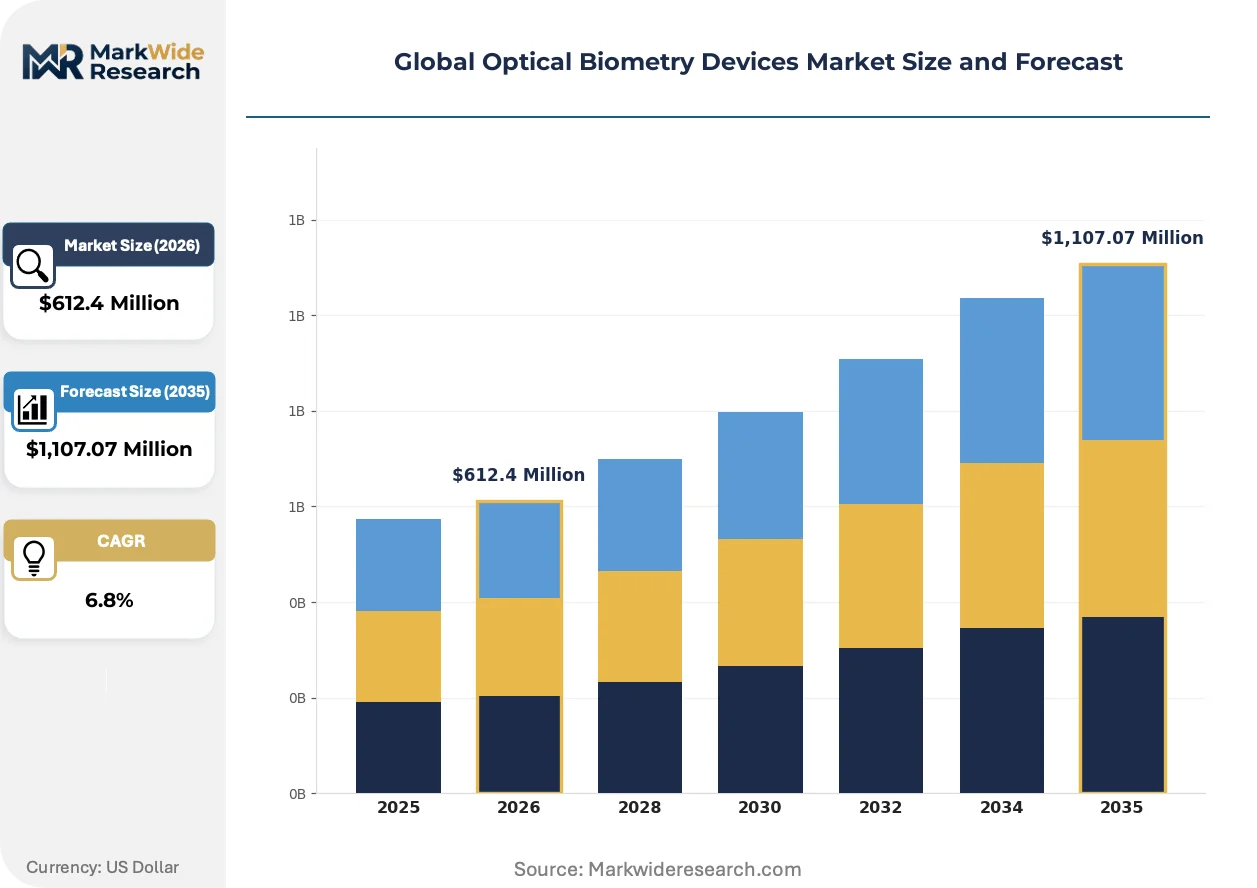
Market Dynamics
Swept-source optical coherence tomography is compressing the performance premium once commanded by partial coherence interferometry platforms, forcing incumbent manufacturers to accelerate software differentiation and service bundling to defend margin structures.
Growth Catalysts
- EU MDR Conformity Requirements:Stricter clinical validation standards for Class IIa medical devices are filtering out undercapitalized competitors and consolidating procurement toward established manufacturers with notified body relationships.
- Aging Demographics in Germany and Japan:Expanding patient pools requiring cataract intervention are driving replacement cycles in hospital ophthalmology departments and high-volume ambulatory surgery centers.
- AI-Enabled IOL Power Calculation:Machine learning algorithms integrated into biometry software are reducing post-operative refractive surprises and accelerating adoption among refractive surgeons.
Market Restraints
- Precision Optics Supply Concentration:Superluminescent diode and swept-source laser component manufacturing concentrates in specialized Japanese and German suppliers, exposing device assemblers to single-source risk.
- FDA 510(k) Clinical Validation Burden:Substantial equivalence demonstrations for new optical biometry platforms require extensive patient cohort studies, extending time-to-market by 18-36 months.
- Optical Coherence Tomography Substitution:Integrated anterior segment OCT systems in premium phacoemulsification platforms are absorbing standalone biometry functions in consolidated surgical suites.
Strategic Opportunities
- India's Tier-2 City Penetration:Underpenetrated ophthalmology infrastructure in secondary metropolitan areas creates whitespace for mobile biometry screening units and equipment leasing models.
- Corneal Refractive Surgery Workflow Integration:Anterior segment analysis applications for SMILE and LASIK pre-operative planning represent the fastest-expanding use case beyond traditional cataract workflows.
- Software-as-a-Medical-Device Harmonization:EMA and FDA convergence on SaMD classification frameworks enables synchronized regulatory strategies for algorithm-driven diagnostic outputs.
Industry Challenges
- Interferometry Specialist Talent Scarcity:Shortage of optical engineers with low-coherence interferometry system design expertise constrains R&D velocity for next-generation platform development.
- Legacy Device Interoperability:Integration of new swept-source platforms with existing electronic medical record systems and surgical planning software requires costly custom interface development.
- Extended IEC 60601-1 Certification Timelines:Electrical safety and electromagnetic compatibility testing for laser-based biometry systems faces bottlenecks at accredited testing laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Biometry Devices Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Biometers, Partial Coherence Interferometry, Optical Low Coherence Reflectometry, Swept Source OCT Devices Technology: Laser Interferometry, Optical Coherence Tomography, Reflection Biometry, A-scan Ultrasound Application: Cataract Surgery Pre-op, Intraocular Lens Calculation, Refractive Surgery, Glaucoma Assessment, Anterior Segment Analysis End User: Ophthalmology Clinics, Eye Research Institutes, Hospitals, Specialty Eye Centers |
| Companies Covered | Carl Zeiss AG, Topcon Corp., Haag-Streit Group, Nidek Co. Ltd., Bausch Lomb Corp., Tomey Corp., Ziemer Group, Alcon Inc., Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Biometry Devices Market Shifts & Advancements
Device architectures are converging around modular platforms that separate hardware measurement engines from software analytics layers, enabling faster algorithm deployment without hardware recertification cycles.
Swept-source optical coherence tomography is migrating from premium tertiary hospital installations into mid-tier ophthalmology clinics as component costs decline and manufacturing scales. Community-based surgical centers in the United States and Germany are adopting SS-OCT biometers at replacement rates exceeding legacy PCI platforms. This technology is migrating from high-end positioning toward standard-of-care status, compressing average selling prices and forcing manufacturers to differentiate through proprietary IOL calculation formulas rather than hardware performance alone.
The FDA's evolving guidance on artificial intelligence-enabled diagnostic outputs is reshaping software development cycles for biometry platforms incorporating machine learning-based IOL power prediction. Manufacturers must now demonstrate algorithm robustness across diverse demographic cohorts and device acquisition conditions, extending validation timelines. US-based ophthalmology device developers are responding by establishing prospective clinical registries to generate real-world performance evidence supporting 510(k) submissions.
Aftermarket service contracts are unbundling from initial device sales as procurement teams in hospital systems demand transparent pricing for calibration, software licensing, and remote diagnostic support. German university hospitals and Japanese national health service providers are leading this shift toward itemized service procurement. This behavioral change is most visible in Western Europe, where public tender regulations increasingly mandate separation of capital equipment and maintenance expenditure lines.
Global Optical Biometry Devices Market Segmentation
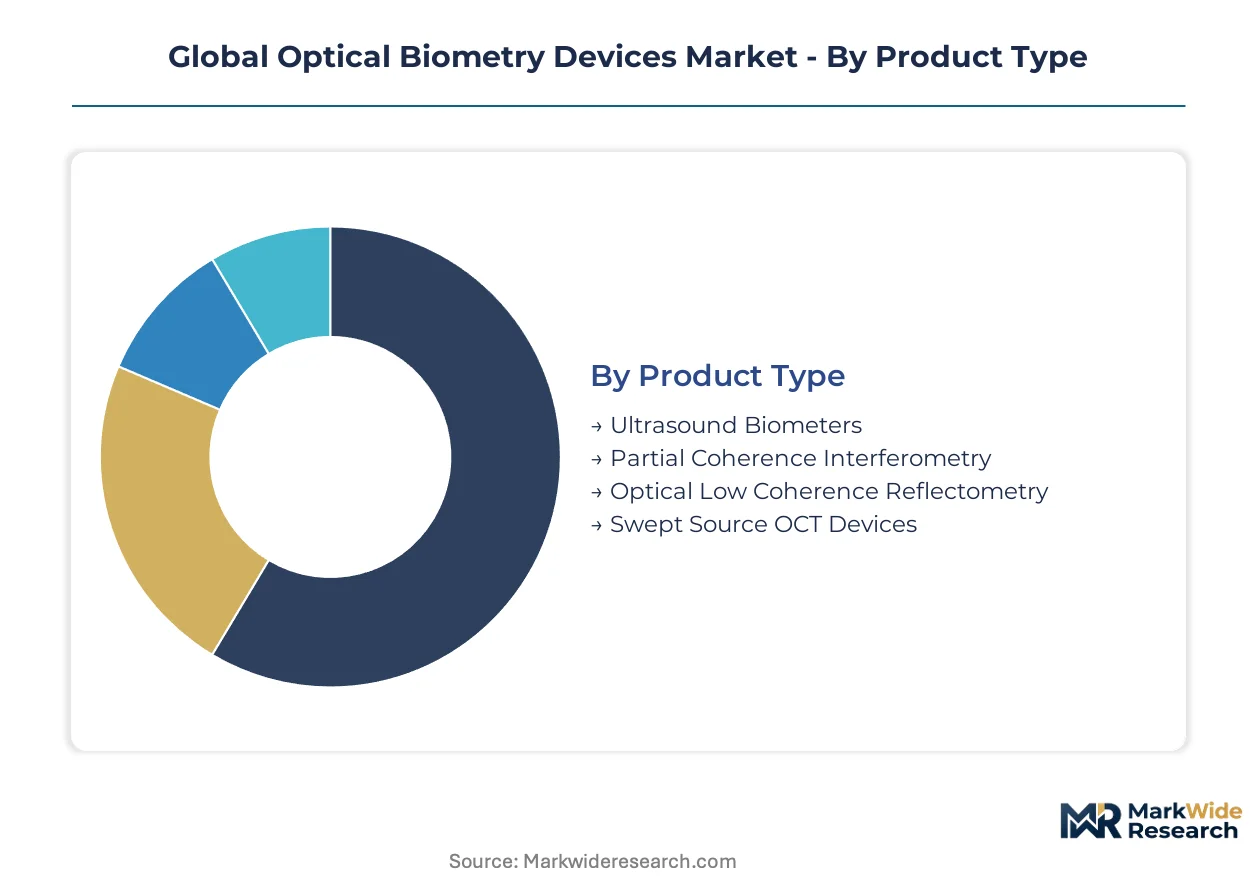
Segmentation in optical biometry reveals how technology tiers, clinical workflows, and procurement channels fragment purchasing decisions across ophthalmology settings. Understanding these splits helps manufacturers align R&D investment with where clinical value concentrates and where pricing power persists.
Product Type:
Mature interferometry platforms coexist with emerging swept-source architectures as facilities balance capital constraints against clinical capability requirements.
- Swept Source OCT Devices:These platforms deploy tunable laser sources sweeping across near-infrared wavelengths to capture full anterior segment and posterior segment anatomy through dense cataract media. Demand concentrates in German university hospitals and Japanese national health centers where complex cases justify premium acquisition costs and where reimbursement structures favor diagnostic thoroughness.
- Partial Coherence Interferometry:Established dual-beam interferometers using superluminescent diodes measure axial length through corneal contact-free alignment, dominating installed bases in US ambulatory surgery centers where throughput efficiency matters more than posterior segment visualization. PCI devices face replacement pressure as SS-OCT prices decline but retain loyalty in high-volume cataract factories prioritizing speed.
- Optical Low Coherence Reflectometry:Single-scan devices combining corneal topography with axial length measurement serve mid-tier ophthalmology clinics seeking consolidated diagnostic footprints without swept-source investment.
- Ultrasound Biometers:A-scan and immersion ultrasound systems persist for eyes with dense media opacity blocking optical penetration, maintaining niche demand in developing markets and trauma referral centers.
Swept Source OCT Devices handles the majority of new capital deployment; Partial Coherence Interferometry is the fastest mover on share as replacement cycles accelerate.
Technology:
Technology selection tracks the trade-off between measurement precision, tissue penetration depth, and capital intensity across different clinical scenarios.
- Optical Coherence Tomography:Cross-sectional imaging using low-coherence interferometry enables tomographic reconstruction of anterior chamber architecture, commanding preference in corneal refractive surgery planning where pachymetry and keratometry precision directly affect ablation outcomes. OCT-based biometry expands fastest in South Korean and Chinese urban markets where myopia correction volumes drive instrumentation upgrades.
- Laser Interferometry:Coherent light interference patterns deliver sub-micron axial length repeatability, anchoring IOL power calculation confidence in premium cataract practices across Switzerland and the United Kingdom where post-operative emmetropia rates determine reputation.
- Reflection Biometry:Slit-lamp integrated systems using Purkinje image analysis support routine screening workflows in community eye hospitals with constrained capital budgets.
- A-scan Ultrasound:Acoustic pulse-echo ranging retains utility in vitreoretinal practices managing silicone oil-filled eyes where optical methods fail.
Laser Interferometry carries the heaviest clinical validation burden; Optical Coherence Tomography is expanding most quickly into anterior segment applications beyond traditional biometry.
Application:
Application segmentation separates mature cataract workflows from emerging corneal and glaucoma diagnostics where biometry hardware repurposes for multi-modal use.
- Cataract Surgery Pre-op:Axial length, keratometry, and anterior chamber depth measurement for IOL power selection represents the foundational revenue pool, with demand tethered to age-related lens opacity prevalence in Germany, Japan, and the United States where surgical volumes per capita lead globally.
- Anterior Segment Analysis:Corneal topography, angle assessment, and pachymetry for refractive surgery candidacy evaluation climbs fastest as SMILE and LASIK procedure rates rise in India, Brazil, and Turkey where myopia epidemics meet expanding middle-class surgical access.
- Intraocular Lens Calculation:Formula-specific biometry parameter acquisition for toric, multifocal, and extended depth-of-focus IOL selection concentrates in private refractive cataract practices.
- Refractive Surgery:Pre-operative screening and post-operative monitoring for laser vision correction overlaps with anterior segment analysis but emphasizes different measurement protocols and software workflows.
- Glaucoma Assessment:Angle evaluation and anterior chamber morphometry for angle-closure risk stratification represents a secondary use case leveraging existing biometer hardware.
Cataract Surgery Pre-op absorbs the largest equipment allocation; Anterior Segment Analysis is gaining share fastest as corneal refractive volumes outpace cataract growth in emerging markets.
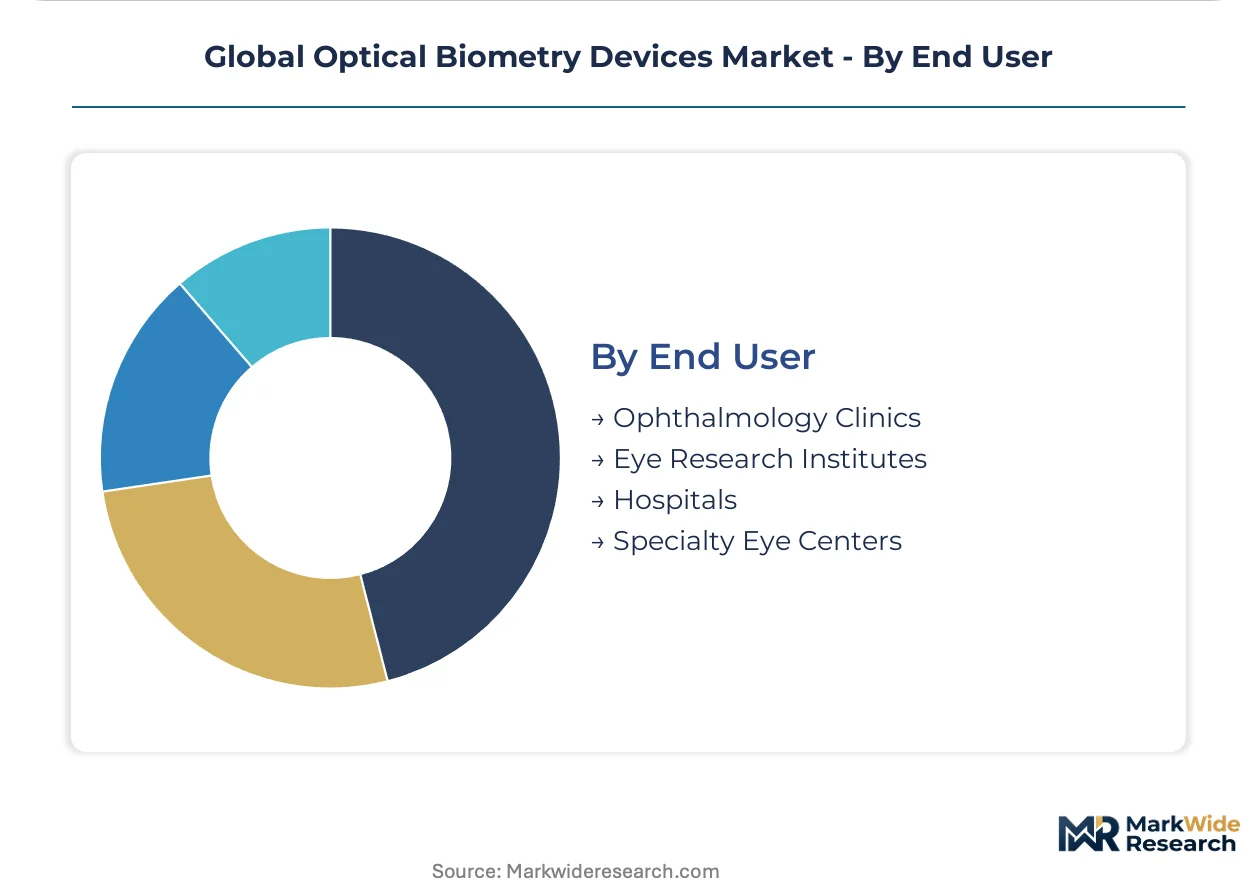
End User:
End user segmentation reflects how procurement autonomy, reimbursement structures, and patient flow patterns shape device specification requirements.
- Ophthalmology Clinics:Independent and group practice settings prioritize compact footprints, intuitive workflows, and financing flexibility over absolute measurement sophistication, dominating volume in US metropolitan suburbs and German Mittelstand cities where physician-owners control capital decisions.
- Hospitals:Integrated health systems and public hospitals emphasize interoperability with electronic medical records, multi-user credentialing, and service contract reliability, with purchasing concentrated in Japanese prefectural medical centers and UK National Health Service trusts.
- Specialty Eye Centers:Dedicated refractive and cataract surgery facilities demand highest measurement precision and fastest throughput, justifying premium SS-OCT platforms in Dubai, Singapore, and São Paulo where medical tourism and cash-pay procedures concentrate.
- Eye Research Institutes:Academic and clinical research organizations drive early adoption of experimental measurement protocols and algorithm validation, purchasing in smaller quantities but influencing subsequent mainstream specification standards.
Hospitals command the largest aggregate installed base; Specialty Eye Centers are climbing the fastest on capital expenditure per facility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized component manufacturing for swept-source lasers and superluminescent diodes clusters in Japanese and German precision optics hubs, concentrating supply risk for device assemblers worldwide.
United States
FDA 510(k) clearance pathways and aging demographic expansion drive procurement among ambulatory surgery centers and hospital ophthalmology departments. Medicare reimbursement structures favor diagnostic thoroughness in cataract pre-operative workflows. The Cleveland Clinic and Mayo Clinic anchor adoption of AI-integrated biometry platforms in the Midwest.
Germany
EU MDR conformity assessments and university hospital procurement standards filter market access toward established manufacturers with notified body relationships. The country's national pharmaceutical regulator enforces Class IIa medical device validation rigor. Bavarian medical technology clusters around Munich and Erlangen concentrate R&D activity for next-generation interferometry systems.
Japan
PMDA regulatory harmonization with international standards and super-aging population demographics sustain replacement cycles in prefectural medical centers. METI industrial policy supports domestic precision optics supply chains for laser component manufacturing. Tokyo and Osaka metropolitan areas concentrate specialty eye center demand for premium SS-OCT platforms.
India
CDSCO medical device registration requirements and expanding private ophthalmology infrastructure create whitespace for equipment leasing models. The country's national pharmaceutical regulator streamlines import licensing for diagnostic devices. Tier-2 cities including Pune, Ahmedabad, and Kochi drive mobile screening unit deployment for cataract outreach programs.
China
NMPA Class II medical device approval pathways and myopia epidemic prevalence accelerate anterior segment analysis adoption. The national medical products administration prioritizes domestic innovation in optical diagnostic equipment. Yangtze River Delta clusters around Shanghai and Suzhou concentrate manufacturing scale for cost-competitive biometry platforms.
Global Optical Biometry Devices Market Competitive Landscape
Precision optics conglomerates and specialized ophthalmology equipment manufacturers split the market between integrated platform ecosystems and focused diagnostic workflows. The vendor base concentrates around three strategic archetypes: diversified medical technology holding companies with broad surgical portfolios, dedicated ophthalmology diagnostic specialists with deep interferometry expertise, and precision optics groups leveraging component manufacturing advantages. Dominant competitive moves include software differentiation through proprietary IOL calculation algorithms and multi-year service contract bundling to lock in recurring revenue streams.
Among diversified medical technology groups, Carl Zeiss AG and Alcon Inc. occupy positions spanning diagnostic and surgical equipment portfolios, while Haag-Streit Group exemplifies the specialist archetype with concentrated ophthalmology focus. These three companies anchor the competitive structure, each representing distinct strategic approaches to device-platform integration and aftermarket service capture.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Topcon Corp. |
| Haag-Streit Group |
| Nidek Co. Ltd. |
| Bausch Lomb Corp. |
| Tomey Corp. |
| Ziemer Group |
| Alcon Inc. |
| Canon Inc. |
| Others |
Supply & Pricing Matrix
Japanese and German precision optics suppliers dominate swept-source laser and superluminescent diode manufacturing, concentrating upstream margin capture in the hands of specialized component vendors while device assemblers face margin compression downstream.
Pricing Analysis
FDA 510(k) and EU MDR conformity requirements dictate the pricing tier structure across optical biometry platforms, with three-tier pricing stratification separating premium SS-OCT systems from standard PCI devices and economy-grade ultrasound alternatives. Price differentiation rests on clinical validation depth and notified body certification status rather than hardware performance alone. Pricing pressure stems from SS-OCT component cost declines enabling mid-tier clinic access. Ambulatory surgery centers exhibit highest price sensitivity; German university hospitals show least.
Supply Chain Analysis
Contract manufacturing for optical subassemblies concentrates in Japanese precision electronics specialists and German optical engineering houses with captive interferometry module production. Swept-source laser engines, superluminescent diodes, and precision motion stages draw from Japanese, German, and Swiss suppliers. Single-source vulnerability pervades tunable laser component sourcing. Distribution runs through authorized ophthalmology equipment distributors with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers must defend against substitution from integrated anterior segment OCT systems in premium phacoemulsification platforms that absorb standalone biometry functions in consolidated surgical suites.
For Market Incumbents: Entrench installed base loyalty through multi-year calibration and software upgrade contracts that lock in recurring revenue streams. Accelerate proprietary IOL calculation algorithm development to differentiate beyond hardware performance as SS-OCT commoditizes. Prioritize backward integration into precision optics component supply to reduce single-source exposure from Japanese and German laser suppliers.
For New Entrants and Emerging Players: India's Tier-2 city ophthalmology infrastructure represents the most penetrable entry point, where mobile biometry screening units and equipment leasing models address capital-constrained clinic expansion. Corneal refractive surgery workflow integration for SMILE and LASIK pre-operative planning offers fastest-expanding application whitespace beyond mature cataract segments. Pursue CDSCO registration pathway alignment with hospital system procurement cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward precision optics specialists with swept-source laser design capabilities and established notified body relationships under EU MDR. Long-term viability hinges on software-as-a-medical-device regulatory convergence enabling synchronized FDA-EMA algorithm deployment strategies. Monitor FDA guidance evolution on AI-enabled diagnostic outputs as inflection signal for valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Class IIa conformity assessment filters market access toward established manufacturers with BSI or TÜV relationships. |
| Proprietary IOL Formula Development | Machine learning-based power calculation algorithms reduce post-operative refractive surprises and drive surgeon preference. |
| Multi-Year Service Contract Bundling | Calibration and remote diagnostic agreements lock in recurring revenue across German and Japanese hospital installed bases. |
| SS-OCT Platform Modularization | Separating hardware engines from software analytics enables faster algorithm deployment without hardware recertification cycles. |
| Tier-2 City Leasing Models | Equipment financing structures address capital constraints in Indian secondary metropolitan ophthalmology expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ophthalmology clinic directors, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and precision optics manufacturing executives. Secondary validation drew from FDA 510(k) filings, EU MDR notified body certificates, PMDA approvals, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up installed base modeling and top-down market sizing triangulated volume and value estimates.
Calibration against historical replacement cycle data and technology migration patterns shaped analytical framework development across the projection horizon. Segmentation dimensions modeled include product architecture, technology platform, clinical application, and end-user procurement channel. CAGRs were derived from regression analysis against demographic cataract prevalence and refractive surgery volume trajectories. Forecast inputs incorporated regulatory approval timeline assumptions and component cost elasticity parameters.
Practitioners should monitor FDA guidance evolution on AI-enabled diagnostic outputs, EU MDR notified body capacity constraints, and swept-source laser component supply disruptions for early signals of forecast revision. Quarterly review of hospital capital expenditure commitments and ambulatory surgery center technology refresh cycles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Antimicrobial Coated Medical Devices Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Directed Energy Based Surgical Systems Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Middle East and Africa Surgical Equipment Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Vascular Closure Device (VCD) Market