
 Global Positive Airway Pressure Devices Market | 2026-2036
Global Positive Airway Pressure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Positive Airway Pressure Devices Market Foresight
ISO 80601-2-70 certification for sleep apnea breathing equipment is redrawing competitive boundaries in the Global Positive Airway Pressure Devices Market. ResMed leverages integrated cloud connectivity and remote patient monitoring platforms to sustain technology leadership across North America and Europe. BMC Medical anchors its position through manufacturing scale and cost-efficient production networks serving Asia-Pacific and emerging markets. Fisher & Paykel Healthcare Limited differentiates via humidification systems bundled with PAP platforms.
Positive airway pressure devices are mechanical ventilatory support systems that deliver pressurized air through a sealed mask interface to maintain pharyngeal patency, typically operating at pressure ranges of 4–20 cm H₂O with algorithms adjusting to respiratory flow patterns. These systems serve primarily to treat sleep-disordered breathing and prevent nocturnal airway collapse in obstructive sleep apnea patients. Continuous Positive Airway Pressure products dominate installed base volumes due to established clinical protocols and payer familiarity, while Automatic Positive Airway Pressure systems capture faster growth as algorithmic titration reduces manual intervention needs. Homecare Settings command the largest end-user revenue pool as reimbursement shifts favor decentralized chronic disease management over facility-based sleep studies.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product development timelines and software validation requirements for connected PAP systems. Japan's PMDA enforces stringent post-market surveillance for software-as-a-medical-device components, adding compliance layers for algorithm-driven pressure adjustment features. Stakeholders must monitor evolving cybersecurity guidance from FDA and harmonization efforts between ISO 27001 and medical device quality management systems as connectivity becomes standard.
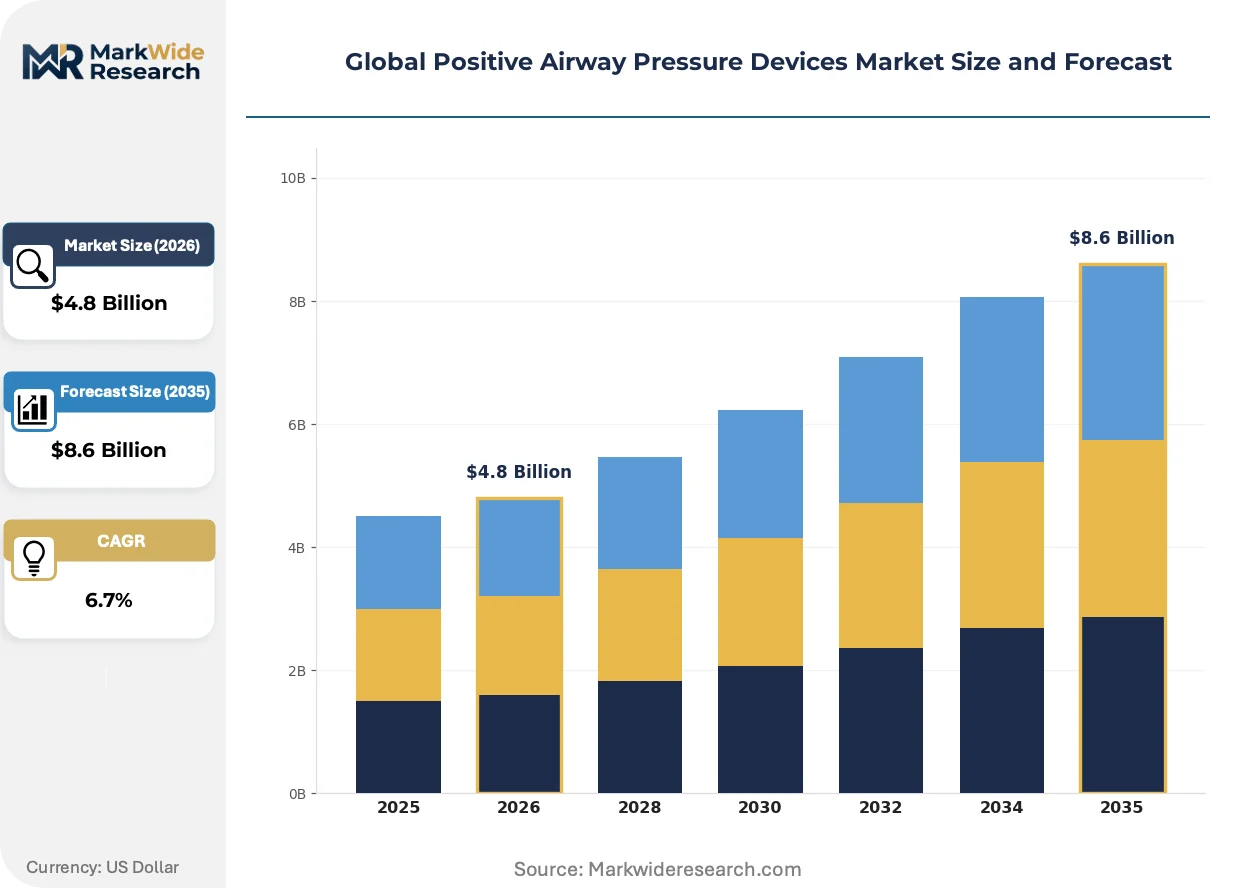
Market Dynamics
Algorithmic pressure titration and cloud-connected remote monitoring are compressing the traditional sleep-lab diagnosis pathway, shifting clinical authority toward home-based diagnostic ecosystems and software-validated therapy management platforms.
Growth Catalysts
- Homecare reimbursement expansion:CMS and private payers in the United States now cover unattended home sleep testing, eliminating facility-based polysomnography bottlenecks and accelerating device prescription velocity.
- ISO 80601-2-70 harmonization:Unified electrical safety and performance standards for sleep apnea breathing equipment streamline multi-market registration, reducing duplicate testing burdens for manufacturers targeting Europe and Asia-Pacific simultaneously.
- Aging demographic concentration:Germany and Japan exhibit elevated obstructive sleep apnea prevalence among populations over 65, where comorbid cardiovascular conditions amplify clinical urgency for pressure therapy intervention.
Market Restraints
- Silicone and polymer input volatility:Mask cushion and tubing production depends on medical-grade silicone supply chains concentrated in Guangdong province, exposing manufacturers to petrochemical price swings and export licensing delays.
- Software validation timeline extension:FDA 510(k) clearance for algorithm-driven APAP systems now requires cybersecurity documentation and interoperability testing, stretching development cycles by 8-14 months for connected device submissions.
- Oral appliance substitution:Mandibular advancement devices prescribed by dental sleep medicine practitioners capture mild-to-moderate OSA cases, eroding addressable patient pools for pressure-based first-line therapy.
Strategic Opportunities
- India diagnostic infrastructure gaps:Under 500 accredited sleep laboratories serve a population exceeding 1.4 billion, creating white space for telemedicine-integrated home diagnostic platforms and direct-to-patient device distribution.
- EU AI Act compliance premium:Manufacturers achieving conformity with risk-classification frameworks for machine-learning pressure adjustment algorithms can command pricing premiums in German, French, and Dutch procurement tenders.
- Humidification-therapy convergence:Integration of heated humidification with miniaturized blower systems addresses nasal congestion adherence barriers, opening pediatric and geriatric segments previously excluded from pressure therapy protocols.
Industry Challenges
- Cybersecurity engineering talent scarcity:Connected PAP platforms require firmware security architects and cloud infrastructure specialists, functions where medical device manufacturers compete directly with technology sector compensation benchmarks.
- Legacy device interoperability:Health system procurement of cloud-native platforms demands backward compatibility with 10-15 year installed bases of non-connected devices, complicating data architecture and remote monitoring rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Positive Airway Pressure Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Positive Airway Pressure, Bi-level Positive Airway Pressure, Automatic Positive Airway Pressure, Adaptive Servo-Ventilation Application: Obstructive Sleep Apnea, Central Sleep Apnea, Respiratory Distress Syndrome, Chronic Obstructive Pulmonary Disease End User: Sleep Disorder Clinics, Pulmonary Centers, Homecare Settings, Ambulatory Surgical Centers Deployment: Stationary Devices, Portable Units, Wearable Devices, Integrated Monitoring Systems |
| Companies Covered | React Health, BMC Medical, ResMed, Löwenstein Medical, Wellell, Koninklijke Philips N.V., Drive DeVilbiss Healthcare, Somnetics International, Fisher & Paykel Healthcare Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Positive Airway Pressure Devices Market Shifts & Advancements
Machine-learning respiratory event detection and consumer-grade sensor integration are dissolving boundaries between clinical-grade therapeutic devices and wellness-tracked sleep optimization tools, forcing regulatory reclassification debates and channel strategy recalibration across the value chain.
Adaptive pressure algorithms incorporating real-time flow limitation and snoring pattern analysis are bifurcating the product landscape into physician-titrated fixed-pressure systems and patient-self-optimizing automatic platforms. Sleep disorder clinics in the United States and Germany increasingly prescribe APAP as first-line therapy, reducing manual pressure adjustment appointments and compressing total cost-of-care metrics that influence payer formulary positioning.
EU Medical Device Regulation cybersecurity annexes and FDA premarket guidance for interconnected devices are mandating software bill-of-materials disclosure and vulnerability management protocols across the development lifecycle. Manufacturers must now embed security-by-design principles into pressure delivery firmware, with German notified bodies and US third-party reviewers scrutinizing encryption standards and over-the-air update mechanisms before granting market authorization.
Patient acquisition channels are fragmenting as direct-to-consumer advertising and telehealth prescription models displace traditional sleep-lab referral pathways. United States-based digital health platforms now bundle home sleep testing with automated CPAP provisioning, bypassing durable medical equipment distributors and capturing margin previously allocated to regional supply intermediaries, a pattern now emerging in Australian and Canadian markets with comparable reimbursement flexibility.
Global Positive Airway Pressure Devices Market Segmentation
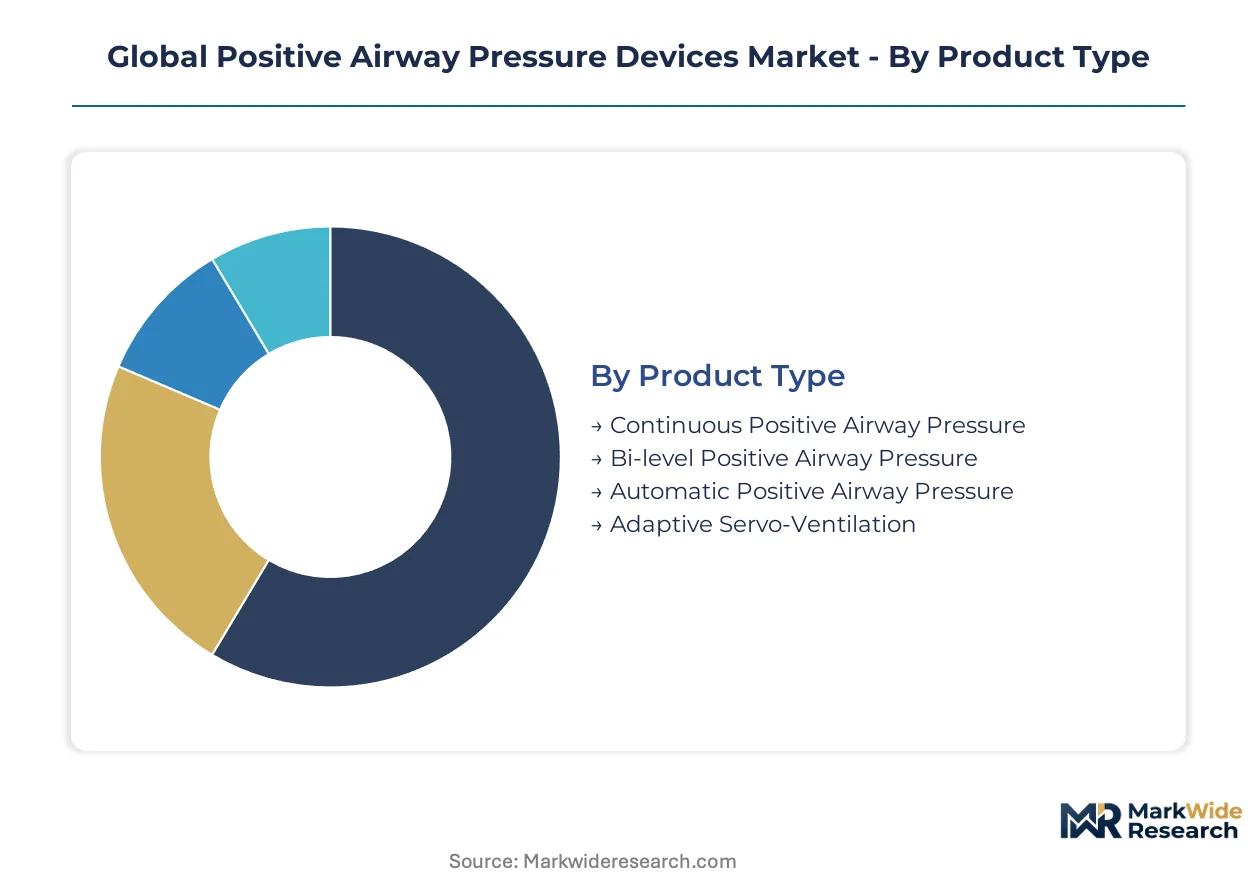
Segmentation in the PAP devices market determines reimbursement pathways, regulatory classification, and channel economics. Product type dictates pressure delivery algorithms and software validation requirements. End-user concentration shapes service bundling strategies and remote monitoring platform design.
Product Type:
Continuous Positive Airway Pressure systems dominate domestic prescription volumes in the United States and Germany, while Automatic Positive Airway Pressure variants drive export growth into Asia-Pacific markets seeking algorithmic titration capabilities.
- Continuous Positive Airway Pressure:Fixed-pressure delivery at physician-prescribed settings between 4–20 cm H₂O. Demand concentrates in United States Medicare populations where established clinical protocols and durable medical equipment reimbursement codes simplify prescription workflows.
- Automatic Positive Airway Pressure:Real-time pressure adjustment responding to flow limitation, snoring, and apnea-hypopnea indices. Japanese sleep clinics and Australian telehealth platforms favor APAP for home diagnostic pathways that reduce polysomnography bottlenecks.
- Bi-level Positive Airway Pressure:Separate inspiratory and expiratory pressure settings for patients requiring ventilatory assistance beyond standard obstruction management.
- Adaptive Servo-Ventilation:Specialized systems targeting central sleep apnea with periodic breathing patterns, deployed primarily in cardiology-integrated sleep programs.
Continuous Positive Airway Pressure holds the largest share; momentum sits with Automatic Positive Airway Pressure.
Application:
Cost tier stratification separates high-acuity hospital-integrated therapy from decentralized home management, with reimbursement intensity varying across diagnostic categories.
- Obstructive Sleep Apnea:Pharyngeal collapse during sleep drives the primary indication for PAP therapy. German statutory health insurance and Japanese employee health funds cover device costs for moderate-to-severe cases, concentrating volume in aging populations with cardiovascular comorbidities.
- Central Sleep Apnea:Neurological failure of respiratory drive requires adaptive servo-ventilation or specialized bi-level systems. United States academic medical centers and French hospital-at-home programs represent concentrated demand for complex titration protocols.
- Respiratory Distress Syndrome:Neonatal and acute applications in hospital settings.
- Chronic Obstructive Pulmonary Disease:Overlap syndrome management combining nocturnal hypoventilation with daytime respiratory insufficiency.
Obstructive Sleep Apnea generates the dominant prescription volume; Central Sleep Apnea commands premium pricing tiers.
End User:
Customer type fragmentation is accelerating as direct-to-consumer channels bypass traditional sleep-lab referral networks in reimbursement-flexible markets.
- Homecare Settings:Decentralized therapy management with cloud-connected remote monitoring. United States digital health platforms and Australian telemedicine providers now bundle diagnostic testing with automated device provisioning, displacing durable medical equipment intermediaries.
- Sleep Disorder Clinics:Physician-directed diagnosis and titration services. German multidisciplinary sleep centers and Japanese polysomnography facilities maintain clinical authority through APAP-first prescription protocols and adherence monitoring programs.
- Pulmonary Centers:Hospital-integrated respiratory therapy for complex cases.
- Ambulatory Surgical Centers:Perioperative screening and short-term device trials.
Homecare Settings capture expanding share; Sleep Disorder Clinics retain clinical influence over prescription authority.
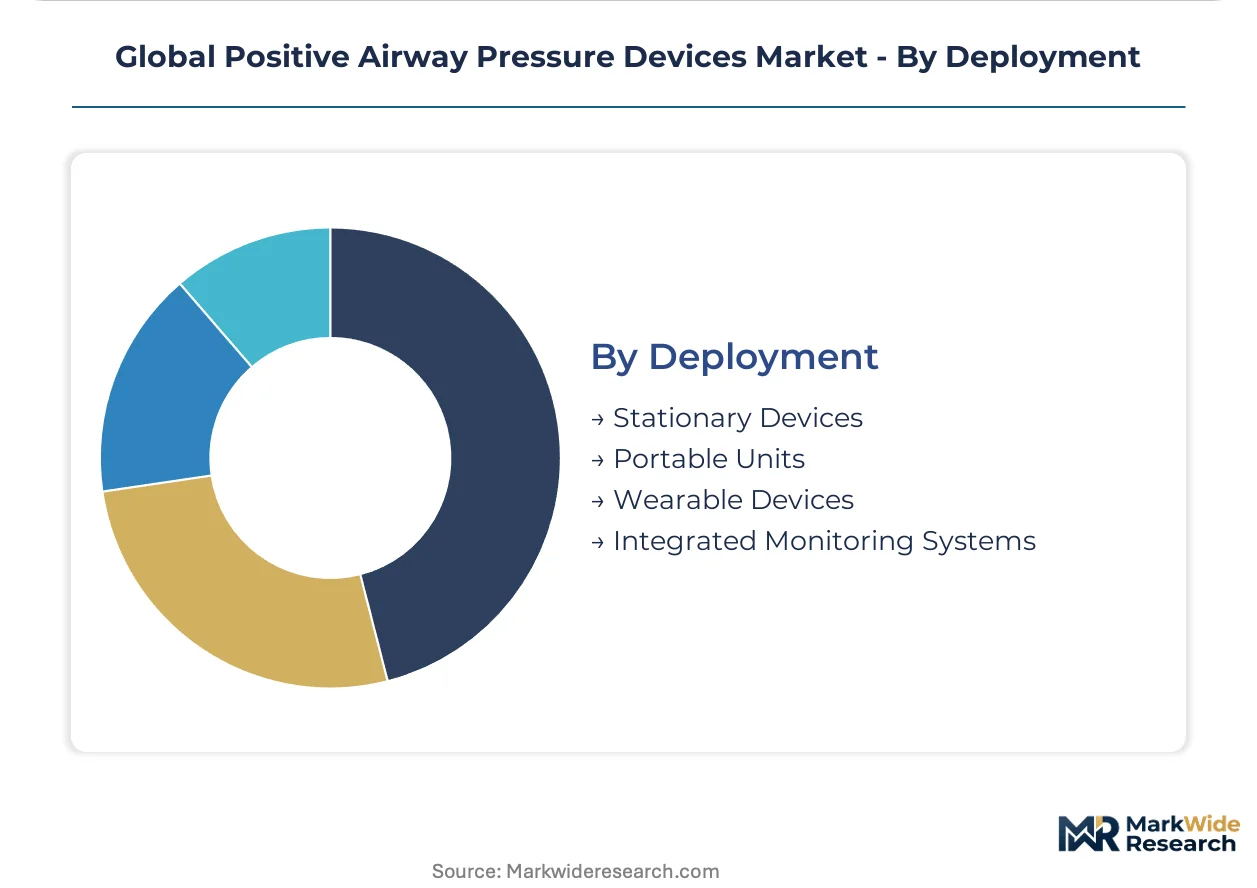
Deployment:
Supply concentration in miniaturized blower manufacturing favors integrated monitoring systems with embedded connectivity, while portable units compete on travel convenience and battery autonomy.
- Integrated Monitoring Systems:Cloud-native platforms with embedded cellular connectivity, over-the-air firmware updates, and automated adherence reporting. FDA 510(k) and CE marking under EU MDR cybersecurity annexes mandate software bill-of-materials disclosure, extending development timelines for manufacturers targeting United States and German procurement channels.
- Portable Units:Compact blowers with battery operation for travel and secondary residence use. Japanese business travelers and United States seasonal residents drive replacement-cycle demand for lightweight systems under 2 kg.
- Stationary Devices:Bedside systems with integrated humidification for fixed home installation.
- Wearable Devices:Experimental form factors including nasal pillow alternatives and mask-integrated sensors.
Integrated Monitoring Systems are climbing the fastest; Portable Units address adherence barriers in mobile patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex underwrites North American distribution capacity for pressure therapy systems, while the Rhine-Alpine freight corridor connects German manufacturing clusters to continental sleep clinics. These infrastructure assets shape how device flows concentrate in aging populations with reimbursement-backed diagnostic pathways.
United States
Medicare Advantage expansion and CMS home sleep testing coverage drive prescription velocity for cloud-connected APAP systems. FDA 510(k) clearance timelines now incorporate cybersecurity documentation requirements under 2018 premarket guidance updates. The Minneapolis-Saint Paul corridor hosts durable medical equipment distributors consolidating telehealth-integrated provisioning platforms.
Germany
Statutory health insurance reimbursement for moderate-to-severe OSA cases sustains device penetration among populations over 65 with cardiovascular comorbidities. EU MDR cybersecurity annexes and ISO 80601-2-70 harmonization streamline multi-market registration for notified bodies in Berlin and Munich. The Baden-Württemberg medical technology cluster concentrates humidification system manufacturing for bundled PAP platforms.
Japan
Employee health fund coverage and PMDA post-market surveillance for software-as-a-medical-device components elevate compliance thresholds for algorithm-driven pressure adjustment. METI industrial standards coordination accelerates local manufacturing scale for miniaturized blower systems. The Osaka-Kobe corridor anchors production networks serving domestic polysomnography facilities and export markets across Southeast Asia.
India
Under 500 accredited sleep laboratories serve a population exceeding 1.4 billion, creating infrastructure gaps for telemedicine-integrated home diagnostic platforms. CDSCO medical device registration pathways under the 2017 Rules framework are harmonizing with ISO standards for electrical safety. The Bengaluru medical device cluster is incubating direct-to-patient distribution models bypassing traditional sleep-lab referral networks.
Australia
Telehealth reimbursement flexibility and Medicare coverage for unattended home sleep testing accelerate digital health platform adoption. TGA conformity assessment for software-enabled devices aligns with FDA and EU MDR cybersecurity guidance. The Sydney-Melbourne corridor concentrates telemedicine providers bundling diagnostic testing with automated CPAP provisioning.
Global Positive Airway Pressure Devices Market Competitive Landscape
Listed leaders compete with private specialists across cloud connectivity and manufacturing scale dimensions. The vendor base exhibits moderate concentration, with integrated technology platforms commanding premium positioning against cost-optimized volume producers. Two strategic archetypes dominate: algorithm-driven remote monitoring specialists and manufacturing-scale suppliers serving price-sensitive emerging markets. Competitive moves center on M&A for software validation capabilities and strategic partnerships for regional distribution access.
Within the remote monitoring tier, ResMed and Fisher & Paykel Healthcare Limited exemplify platform-integrated positioning, while BMC Medical represents manufacturing-scale archetypes serving Asia-Pacific markets. React Health occupies a position bridging clinical-grade therapeutic systems and decentralized homecare provisioning. These three companies anchor the competitive spectrum from premium connected platforms to volume-optimized production networks.
| Leading Market Players |
|---|
| React Health |
| BMC Medical |
| ResMed |
| Löwenstein Medical |
| Wellell |
| Koninklijke Philips N.V. |
| Drive DeVilbiss Healthcare |
| Somnetics International |
| Fisher & Paykel Healthcare Limited |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day component lead times for medical-grade silicone and miniaturized blowers concentrate procurement leverage among manufacturers with multi-year supplier contracts, directly amplifying pricing power for integrated platform vendors against spot-market dependent assemblers in the Global Positive Airway Pressure Devices Market.
Pricing Analysis
Volume-discount tiering structures separate enterprise health system contracts from individual durable medical equipment prescriptions, with three-tier pricing stratification across premium cloud-connected platforms, standard APAP systems, and economy CPAP devices. Price differentiation hinges on FDA 510(k) clearance tier and remote monitoring software bundling. Cost compression in economy segments is intensifying because Asian manufacturers are scaling automated assembly lines. Hospital purchasing committees exhibit lowest price sensitivity due to bundled service contracts, while direct-to-consumer channels face acute pressure from telehealth platform aggregators.
Supply Chain Analysis
Inventory buffers for semiconductor motor controllers and pressure sensors now stretch beyond historical ninety-day baselines, exposing just-in-time architectures to disruption. Component sourcing draws from China for medical-grade silicone, Germany for precision blower assemblies, and Japan for pressure sensor modules. Single-source vulnerability concentrates in Guangdong province mask cushion production. Distribution runs through Minneapolis-Saint Paul corridor distributors for United States coverage and Rhine-Alpine freight networks for European sleep clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as home diagnostic pathways splinter prescription authority across telehealth platforms, sleep disorder clinics, and direct-to-consumer channels, creating niche positioning for specialized software-validated and manufacturing-scale archetypes alike.
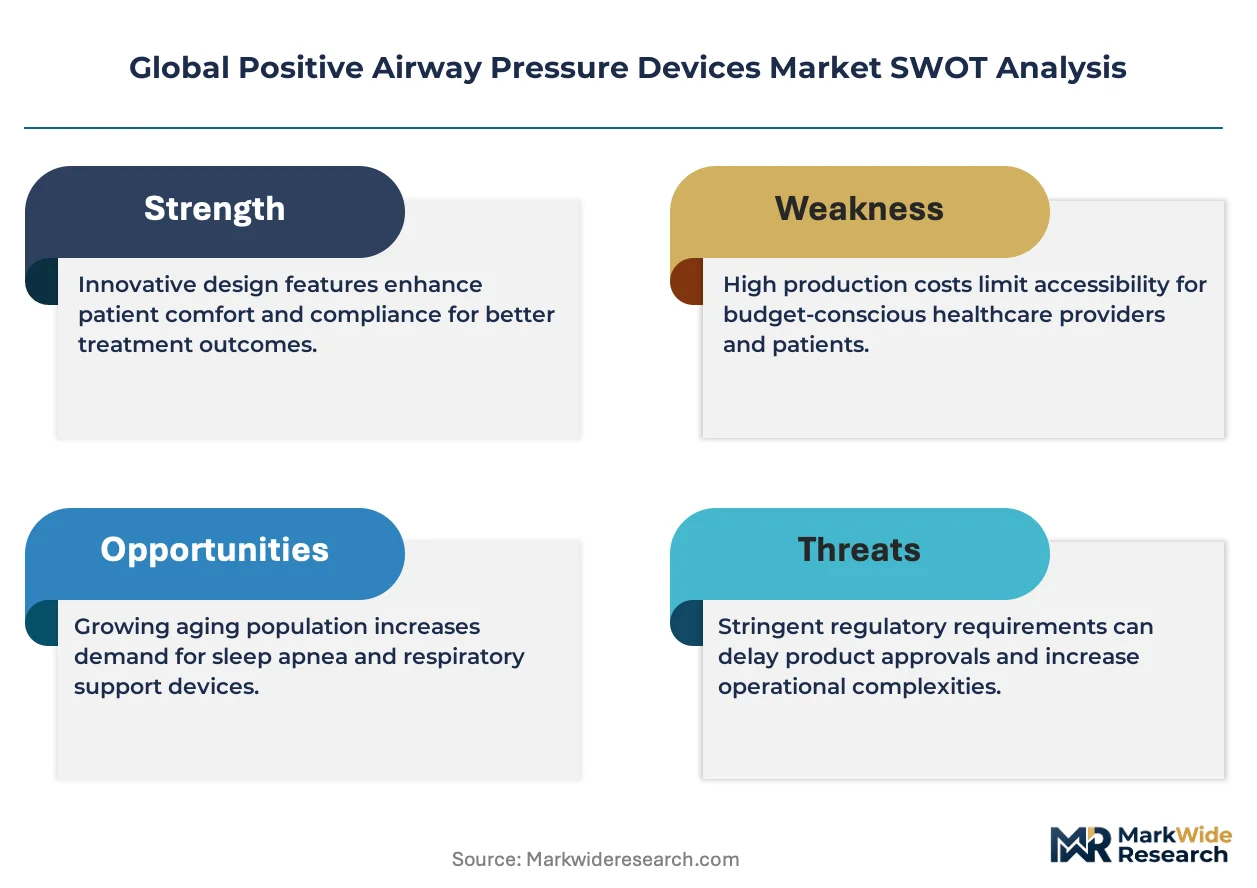
For Market Incumbents: Shield installed base retention through backward integration into humidification system manufacturing and exclusive cloud platform interoperability. Oral appliance substitution from dental sleep medicine practitioners threatens first-line therapy positioning. Certification investment in ISO 80601-2-70 harmonization secures multi-market registration barriers.
For New Entrants and Emerging Players: FDA 510(k) cybersecurity fast-track pathways offer regulatory arbitrage against legacy device clearance backlogs. India's diagnostic infrastructure gaps present the most penetrable geography, with under 500 accredited sleep laboratories serving 1.4 billion population. Direct-to-patient distribution through telemedicine-integrated platforms bypasses traditional sleep-lab referral bottlenecks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across software-as-a-medical-device development functions, favoring asset-light platform specialists over manufacturing-heavy assemblers. Long-term viability over the next decade rests on algorithmic pressure titration IP and remote monitoring data network effects. Acquisition target archetype: mid-scale APAP manufacturers with ISO 27001-compliant cloud infrastructure. Signal to monitor: EU AI Act conformity assessment timelines for machine-learning pressure adjustment algorithms.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR cybersecurity annexes now mandate software bill-of-materials disclosure for connected PAP systems. |
| Hospital System Partnership | German statutory health insurance reimbursement frameworks favor integrated adherence monitoring programs. |
| Software Companion Development | FDA 510(k) clearance timelines stretch 8-14 months for algorithm-driven APAP with cybersecurity documentation. |
| Reimbursement Strategy | CMS home sleep testing coverage eliminates polysomnography bottlenecks and accelerates prescription velocity. |
| Backward Integration | Captive supply of medical-grade silicone cushions insulates against Guangdong province export licensing delays. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR notified body documentation, and CMS reimbursement coding updates. Primary interviews engaged biomedical engineers at sleep disorder clinics, GPO contracts managers at United States hospital systems, and regulatory affairs leads at connected device manufacturers. Secondary validation incorporated PMDA post-market surveillance reports, CDSCO medical device registration filings under 2017 Rules, and TGA conformity assessment guidance. Bottom-up prescription volume modeling triangulated against top-down reimbursement expenditure analysis.
Segmentation dimensions modeled span product type, application indication, end-user channel, and deployment architecture across the projection horizon. Analytical framework derived CAGRs through algorithmic pressure titration adoption curves and homecare reimbursement expansion trajectories. Forecast inputs incorporated aging demographic prevalence projections for obstructive sleep apnea and software validation timeline extensions for cybersecurity-compliant submissions.
The analysis sits within stated boundaries; outcomes outside sustained Medicare Advantage expansion and EU MDR harmonization stability would require recalibration. Forecasts reflect documented assumptions regarding telehealth platform penetration rates and silicone supply chain normalization. Cybersecurity engineering talent scarcity and oral appliance substitution represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
General Surgery Devices Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Gracey Curette Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Corneal Implants Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Concentrator O2 Devices Market