
 US Biomedical Sensors Market | 2026-2036
US Biomedical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
US Biomedical Sensors Market Outlook
Modular sensor packaging is broadening buyer choice across acute and ambulatory settings. Medtronic leverages its integrated care ecosystem to sustain hospital loyalty for implantable monitoring platforms. Abbott Laboratories anchors home-based glucose tracking through continuous biosensor architectures that bypass traditional lab workflows. Honeywell International Inc. competes in industrial-grade sensor manufacturing, extending its process control expertise into FDA-regulated medical device supply chains.
Biomedical sensors are electromechanical or biochemical transducers that convert physiological signals into quantifiable electrical outputs, typically operating within precision ranges of microvolts to millivolts and requiring biocompatible encapsulation for tissue contact. These devices serve continuous physiological surveillance, diagnostic quantification, and closed-loop therapeutic feedback across clinical and consumer environments. Wearable sensors occupy the largest revenue pool as fitness monitoring and chronic disease management applications merge into single-device platforms. Electrochemical sensors lead technology-based demand due to their dominance in blood glucose and metabolite detection, while biosensors represent the fastest-expanding category as enzymatic and affinity-based detection methods penetrate infectious disease and oncology screening.
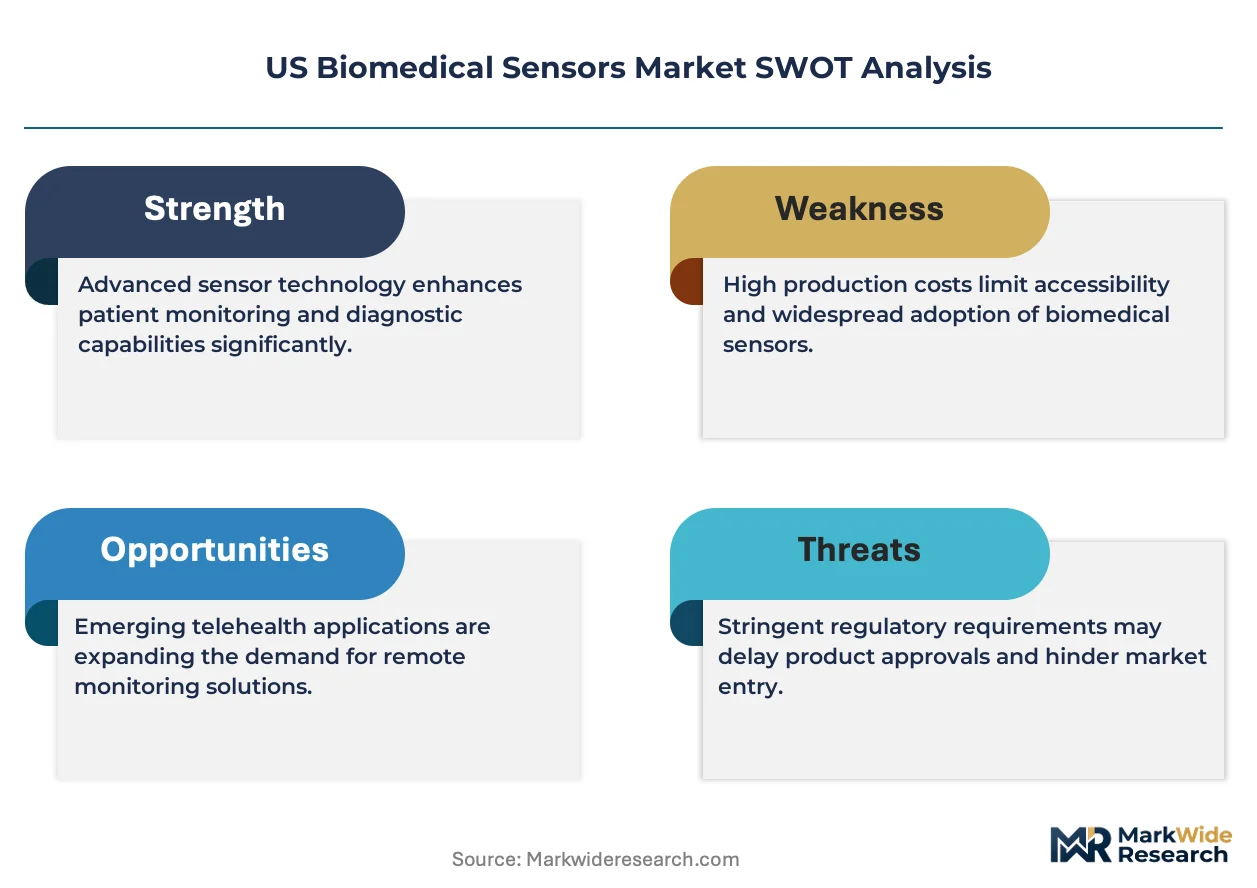
FDA premarket notification requirements and CMS national coverage determinations for remote therapeutic monitoring shape product development timelines and reimbursement-driven demand curves. OSHA workplace exposure standards and state-level clinical laboratory improvement amendments further constrain sensor deployment protocols in occupational and point-of-care settings. Stakeholders must monitor evolving FDA software-as-a-medical-device guidance and state Medicaid expansion of remote monitoring benefits to anticipate access and pricing inflection points.
Market Dynamics
FDA breakthrough device designations and CMS reimbursement pathways for remote patient monitoring are compressing commercialization timelines and redirecting R&D investment toward continuous physiological surveillance platforms.
Growth Catalysts
- CMS National Coverage Determinations:Reimbursement codes for remote therapeutic monitoring incentivize hospital systems to deploy ambulatory biosensor networks, accelerating patient discharge workflows.
- Chronic Disease Management Programs:Major hospital networks in California's medtech corridor integrate continuous glucose and cardiac monitoring into standardized care protocols.
- Enzymatic Detection Methods:Affinity-based biosensor architectures penetrate infectious disease screening applications, expanding addressable clinical testing volumes.
Market Restraints
- Biocompatible Encapsulation Costs:Precision microfabrication of tissue-contacting sensor housings requires specialized polymer substrates subject to supply volatility.
- FDA Premarket Notification Burden:Software-as-a-medical-device guidance creates documentation friction for algorithm-enabled diagnostic platforms.
- Electrochemical Sensor Substitution:Optical transduction methods for metabolite detection threaten incumbent glucose monitoring architectures in research settings.
Strategic Opportunities
- State Medicaid Expansion:Remote monitoring benefit extensions in Texas and Florida create reimbursement tailwinds for home-based chronic disease platforms.
- Wearable-Fitness Convergence:Single-device platforms merge consumer fitness tracking with clinical-grade arrhythmia detection, capturing dual-revenue streams.
- Closed-Loop Therapeutic Feedback:Integration of biosensor outputs with automated insulin delivery systems creates new device ecosystem control points.
Industry Challenges
- ISO 13485 Certification Timelines:Quality management system audits for FDA-regulated medical devices extend product launch schedules by 12-18 months.
- Legacy Hospital IT Integration:Proprietary data formats from next-generation biosensor platforms require costly middleware development for EHR compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Biomedical Sensors Market |
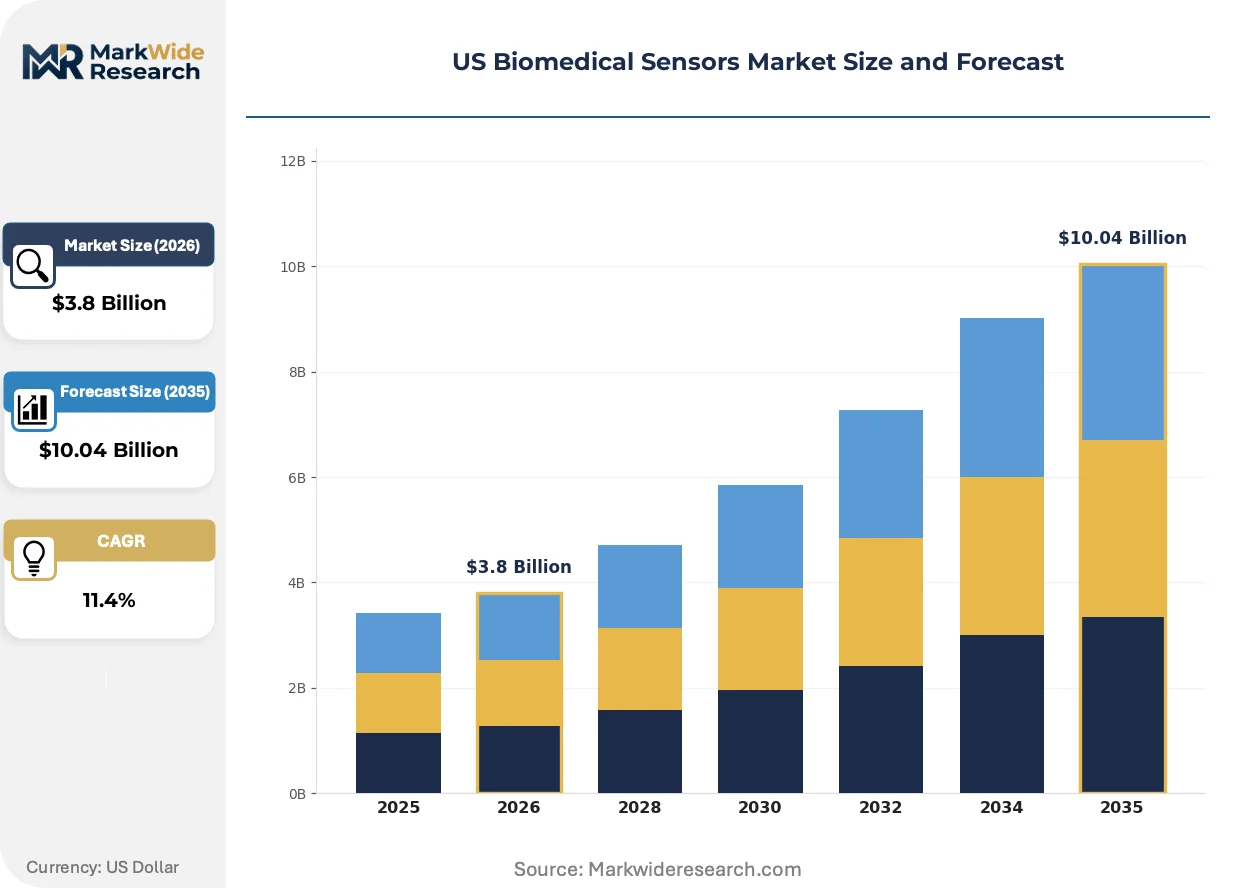
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Implantable Sensors, Invasive Sensors, Non-invasive Sensors End User: Hospitals, Home Care, Diagnostics Labs, Research Institutions Technology: Optical Sensors, Electrochemical Sensors, Biosensors, Thermal Sensors Application: Fitness Monitoring, Chronic Disease Management, Vital Signs Monitoring, Blood Glucose Monitoring |
| Companies Covered | Analog Devices, Inc., Medtronic, General Electric Company, Honeywell International Inc., NXP Semiconductors, STMicroelectronics, TE Connectivity, Sensirion AG, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Biomedical Sensors Market Strategic Shifts
Modular sensor packaging architectures are fragmenting buyer procurement patterns across acute and ambulatory settings, while electrochemical detection methods face displacement from multi-analyte biosensor platforms.
Continuous biosensor architectures are overtaking traditional fingerstick glucose monitoring in home-based diabetes management. Endocrinology practices at Stanford and UCSF health systems now prescribe factory-calibrated systems as first-line therapy. The shift is compressing clinical laboratory workflow revenues while elevating sensor subscription economics.
CMS reimbursement pathways for remote therapeutic monitoring are redirecting manufacturer commercialization resources toward ambulatory care settings. The policy framework rewards continuous physiological data transmission over episodic clinical encounters. Hospital networks in California and Massachusetts are restructuring chronic disease contracts around sensor-derived outcome metrics.
Subscription-based sensor provisioning is displacing capital equipment purchases in hospital procurement departments. Procurement departments now prioritize per-patient-per-month pricing models that align vendor incentives with clinical utilization. The behavioral shift is most visible in integrated delivery networks consolidating sensor deployment across multi-state footprints.
US Biomedical Sensors Market Segmentation
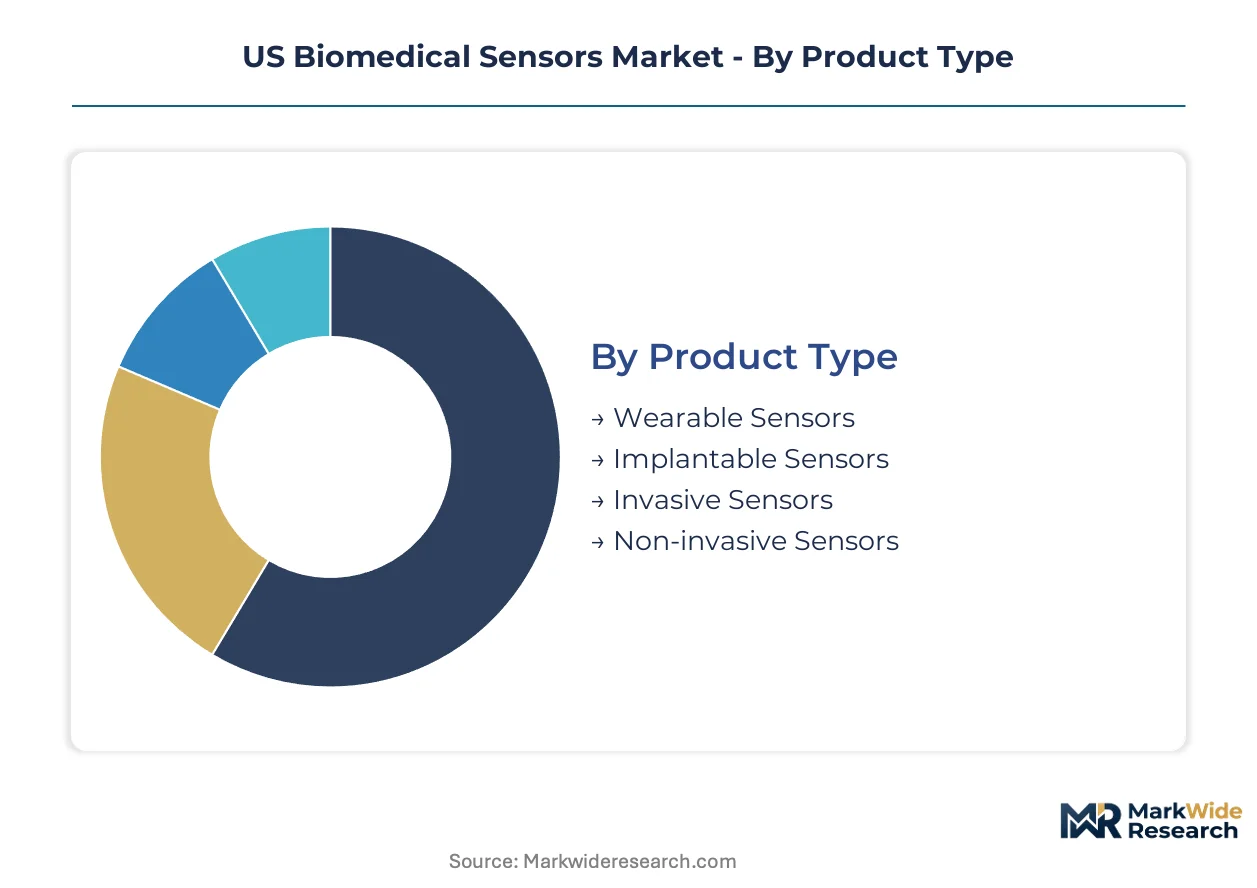
Biomedical sensor procurement patterns diverge sharply across clinical versus consumer environments, with FDA clearance tiers and CMS reimbursement codes determining viable addressable markets for each segment. Manufacturers must align product architectures with specific certification pathways to capture volume in acute care settings versus direct-to-consumer channels.
Product Type:
Wearable sensors carry Class II 510(k) pathways for non-invasive physiological monitoring, while implantable platforms trigger PMA requirements and extended clinical trial obligations. FDA breakthrough device designations compress timelines for select continuous monitoring applications.
- Wearable Sensors:Flexible substrate designs integrate photoplethysmography and accelerometry for wrist-worn cardiac and metabolic surveillance. Stanford Health System and UCSF Medical Center now prescribe these for post-discharge arrhythmia monitoring, with CMS remote therapeutic monitoring codes covering device provisioning.
- Implantable Sensors:Hermetically sealed biocompatible housings enable long-term intracardiac or intracranial pressure measurement. Medtronic leverages its integrated care ecosystem to sustain hospital loyalty for these platforms, though PMA submission costs exceed $10 million per indication.
- Invasive Sensors:Catheter-mounted transducers for intravascular pressure and flow measurement require sterilization validation and single-use economics.
- Non-invasive Sensors:Surface electrode and optical configurations bypass tissue contact regulations, accelerating deployment in ambulatory settings.
Wearable sensors sit at the top of the volume ranking, with implantable sensors climbing the fastest as breakthrough device pathways expand cardiovascular and neurological indications.
End User:
Procurement authority concentrates in integrated delivery networks consolidating sensor deployment across multi-state footprints, with home care emerging as the highest-margin channel due to recurring subscription economics.
- Hospitals:Acute care systems in California's medtech corridor drive early adoption of next-generation biosensor platforms. These institutions prioritize middleware-compatible devices that feed directly into Epic and Cerner EHR architectures.
- Home Care:Continuous glucose monitoring and cardiac event recorders bypass clinical laboratory workflows entirely. Abbott Laboratories anchors this segment through factory-calibrated systems prescribed as first-line diabetes therapy.
- Diagnostics Labs:Centralized testing facilities retain demand for high-throughput electrochemical analyzers, though point-of-care displacement threatens volume.
- Research Institutions:NIH-funded consortia drive demand for experimental multi-analyte biosensor prototypes not yet cleared for clinical use.
Hospitals retain the largest procurement budgets, with home care gaining share fastest as CMS reimbursement pathways mature.
Technology:
Electrochemical methods dominate metabolite detection, while enzymatic biosensor architectures penetrate infectious disease and oncology screening with higher specificity thresholds.
- Electrochemical Sensors:Amperometric glucose oxidase electrodes remain the reference standard for blood glucose quantification. These devices operate within microampere current ranges and require factory calibration to eliminate end-user variability.
- Biosensors:Affinity-based detection using antibodies or aptamers enables pathogen identification and biomarker quantification at picomolar sensitivity. Enzymatic architectures are penetrating COVID-19 and influenza screening applications.
- Optical Sensors:Photoplethysmography and near-infrared spectroscopy enable non-invasive oxygen saturation and hydration monitoring.
- Thermal Sensors:Thermopile and thermistor configurations track core body temperature for infection and ovulation monitoring.
Electrochemical sensors command the highest shipment volumes, with biosensors expanding most quickly as affinity-based methods diversify beyond glucose.
Application:
Fitness and chronic disease segments are converging into single-device platforms, with blood glucose monitoring representing the most reimbursement-mature vertical.
- Blood Glucose Monitoring:Continuous biosensor architectures now dominate prescription patterns over traditional fingerstick methods. Endocrinology practices at major academic medical centers have shifted first-line therapy to factory-calibrated systems.
- Chronic Disease Management:Integrated platforms combine cardiac, respiratory, and metabolic surveillance for heart failure and COPD populations. Hospital networks in Massachusetts and California structure value-based contracts around sensor-derived outcome metrics.
- Fitness Monitoring:Consumer-grade step counting and sleep staging face margin compression as clinical features migrate downstream.
- Vital Signs Monitoring:Continuous temperature, pulse, and respiratory rate tracking supports early warning score systems in general ward settings.
Blood glucose monitoring leads absolute revenue, with chronic disease management showing the steepest expansion trajectory as integrated care contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US biomedical sensors industry traces its commercial roots to California's semiconductor corridors, where Fairchild and Intel alumni seeded precision instrumentation expertise that migrated into medical device manufacturing during the 1970s.
California
Stanford and UCSF health systems prescribe factory-calibrated continuous glucose monitors as first-line diabetes therapy. FDA breakthrough device designations flow through the San Francisco Bay Area at higher rates than any other metro. Medtech clusters in San Jose and San Diego concentrate electrochemical sensor fabrication for blood glucose and cardiac monitoring platforms.
Massachusetts
Mass General Brigham and Partners HealthCare structure value-based chronic disease contracts around sensor-derived outcome metrics. CMS national coverage determinations for remote therapeutic monitoring accelerate procurement in Boston's integrated delivery networks. The Route 128 corridor hosts FDA-regulated cleanroom facilities for implantable biosensor packaging.
Texas
State Medicaid expansion of remote monitoring benefits creates reimbursement tailwinds for home-based chronic disease platforms in Houston and Dallas-Fort Worth. Texas Medical Center hospitals pilot closed-loop insulin delivery systems integrating biosensor outputs with automated pumps. Austin's semiconductor foundries supply precision analog front-ends for wearable physiological monitors.
Minnesota
Medtronic's integrated care ecosystem sustains hospital loyalty for implantable monitoring platforms from its Minneapolis headquarters. The state's medical device quality management infrastructure supports ISO 13485 certification pipelines that feed FDA premarket notification pathways. Rochester's Mayo Clinic drives early adoption of next-generation intracardiac pressure sensors.
Illinois
Abbott Laboratories anchors North American glucose monitoring supply chains from its Lake County base, shipping factory-calibrated systems to endocrinology practices nationwide. Chicago-area diagnostics labs retain demand for high-throughput electrochemical analyzers despite point-of-care displacement pressures. The state's central logistics position supports distribution to hospital networks across the Midwest and Southeast.
US Biomedical Sensors Market Competitive Environment
Premium-margin players sit above commodity-margin players across FDA clearance tier and reimbursement code access. The vendor base organizes into three strata: diversified medtech conglomerates with integrated care ecosystems, specialized sensor component suppliers with semiconductor process expertise, and emerging platform developers betting on software-as-a-medical-device pathways. Consolidation pressure runs through the middle tier as hospital procurement departments consolidate vendor lists around middleware-compatible architectures.
Within the diversified medtech tier, Medtronic and Abbott Laboratories represent contrasting strategic anchors. Medtronic exemplifies the hospital-loyalty model built on implantable platforms and PMA-level regulatory expertise. Abbott occupies a position bridging clinical prescription channels with consumer-accessible form factors. Honeywell International Inc. sits within the industrial-to-medical crossover archetype, extending process control manufacturing capabilities into FDA-regulated supply chains. Analog Devices, Inc. and NXP Semiconductors anchor the sensor component layer, supplying precision signal conditioning and low-power wireless connectivity to downstream device integrators.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| Medtronic |
| General Electric Company |
| Honeywell International Inc. |
| NXP Semiconductors |
| STMicroelectronics |
| TE Connectivity |
| Sensirion AG |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Biocompatible polymer substrates for sensor housings flow from specialized chemical suppliers through three distinct pricing tiers before reaching hospital procurement departments and home care distributors. FDA Class II versus Class III clearance requirements create step-function cost differentials that manufacturers pass downstream based on reimbursement code access rather than raw material input costs.
Pricing Analysis
Subscription-based per-patient-per-month models now dominate hospital procurement, displacing capital equipment purchases across integrated delivery networks. Price differentiation rests on FDA clearance tier and CMS reimbursement eligibility, with breakthrough device designations commanding premium positioning. Cost compression in wearable sensor tiers is intensifying as consumer-grade components migrate into clinical-grade platforms. Home care channels show the highest price sensitivity due to direct patient cost-sharing, while implantable platforms face inelastic demand from cardiac and neurological indications.
Supply Chain Analysis
Reverse-logistics flows for factory-calibrated glucose sensors and wearable cardiac monitors create closed-loop refurbishment channels that recover precious metal electrodes and specialized polymer substrates. Precision analog front-end manufacturing concentrates in Taiwan, South Korea, and the United States. Biocompatible encapsulation materials draw from German and Japanese specialty chemical suppliers. Single-source vulnerability runs through semiconductor foundry capacity for low-power wireless connectivity chips. Distribution runs through GPO contracts at integrated delivery networks and direct-to-patient pharmacy channels for home-based chronic disease platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US biomedical sensors market compounds steadily as chronic disease prevalence and CMS reimbursement expansion create durable demand tailwinds. Hospital network consolidation and software-as-a-medical-device pathways reinforce structural growth.
For Market Incumbents: Anchor hospital loyalty through middleware-compatible architectures that integrate directly into Epic and Cerner EHR systems. Deepen ISO 13485 certification pipelines to compress FDA premarket notification timelines against emerging software-enabled diagnostic platforms. Defend implantable sensor margins by leveraging PMA-level regulatory expertise as a competitive moat. For New Entrants and Emerging Players: Multi-analyte enzymatic detection architectures offer a technology-first wedge into infectious disease screening applications where incumbent electrochemical methods lack specificity. Target state Medicaid expansion markets in Texas and Florida for home-based chronic disease platforms. Pursue direct-to-patient pharmacy partnerships to bypass consolidated hospital procurement committees. For Investors and Strategic Acquirers: Consolidation pressure builds where middleware compatibility requirements and ISO 13485 certification timelines disadvantage sub-scale component suppliers. The market supports long-term compounder positioning through recurring sensor subscription economics and expanding CMS remote therapeutic monitoring codes. Acquisition targets include specialized sensor component suppliers with semiconductor process expertise and FDA-regulated cleanroom infrastructure. Monitor FDA software-as-a-medical-device guidance evolution for inflection signals in algorithm-enabled diagnostic valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercialization timelines for continuous cardiac monitoring platforms at Stanford and UCSF. |
| Hospital System Partnership | Secures middleware integration commitments that lock out competing biosensor vendors from EHR workflows. |
| Software Companion Development | Enables closed-loop therapeutic feedback integration with automated insulin delivery systems. |
| Reimbursement Strategy | Aligns CMS remote therapeutic monitoring codes with factory-calibrated glucose sensor prescription patterns. |
| Backward Integration into Biocompatible Polymers | Reduces supply volatility exposure for tissue-contacting sensor housings in implantable platforms. |
Study Parameters
Direct dialogue with hospital purchasing committees, biomedical engineers, GPO contracts managers, and endocrinology practice administrators grounded the qualitative assessment of procurement behavior and clinical adoption patterns. Secondary validation drew from FDA 510(k) and PMA filings, CMS national coverage determinations, hospital procurement databases, and SEC 10-K disclosures from diversified medtech conglomerates. Bottom-up sensor shipment estimates triangulated against top-down reimbursement code utilization data.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, end user channel, detection technology, and clinical application. Electrochemical versus biosensor technology trajectories, wearable-implantable form factor shifts, and acute-to-home care setting migration informed the analytical framework. CAGRs emerged from regression against CMS reimbursement expansion timelines and chronic disease prevalence projections.
The model holds under stable FDA premarket review timelines and continued CMS remote monitoring reimbursement; deviation in software-as-a-medical-device regulatory interpretation or state Medicaid contraction would shift volume trajectories. Practitioners should monitor FDA guidance evolution and state-level telehealth policy for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Sinus Implants Market
Medical Devices
Cervical Disc Prosthesis Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Asia-Pacific Manual Resuscitators Market