
 Face Mask Device Market | 2026-2036
Face Mask Device Market Size, Share, and Industry Trends Forecast 2026-2036
Face Mask Device Market Foresight
Medical-grade filtration certification is reorganizing competitive tiers across the face mask device landscape. Philips leverages its respiratory-therapy heritage to anchor hospital procurement channels in North America and Europe. Panasonic Corporation competes through manufacturing scale and semiconductor-cleanroom expertise that extends into precision-filter production. NuFACE differentiates by occupying the premium consumer-wearables intersection, where LED-therapy and skincare convergence commands higher price realization.
Face mask devices encompass respiratory-protection and skincare-treatment apparatus engineered to specific filtration efficiency, material porosity, or light-wavelength parameters, with primary purpose spanning infection control in clinical settings, particulate blocking in industrial environments, and dermatological therapy in consumer applications. N95 respirators and antimicrobial-filter technology dominate margin pools where healthcare procurement mandates enforce sustained replacement schedules. Reusable segments navigate sustainability pressures while disposable units sustain volume leadership in emergency-preparedness stockpiling and high-turnover hospital wards.
FDA 510(k) clearance pathways and OSHA respiratory-protection standards govern United States market access, while CE marking under the EU Medical Device Regulation shapes European product-qualification timelines. Japan's PMDA and METI coordinate domestic standards alignment with international ISO filtration benchmarks, creating multi-jurisdictional compliance burdens for scaled suppliers. Stakeholders must monitor evolving harmonization between national emergency-stockpile specifications and routine healthcare procurement frameworks to anticipate demand-step changes.
Market Dynamics
Healthcare procurement mandates are compressing supplier qualification timelines while simultaneously elevating filtration-performance thresholds, forcing manufacturers to recalibrate R&D-to-certification pipelines against emergency-stockpile specifications and routine hospital procurement frameworks.
Growth Catalysts
- OSHA respiratory-protection standards:United States industrial-safety mandates enforce sustained replacement schedules for N95-grade units in manufacturing and construction sectors.
- Antimicrobial-filter technology:Hospital systems are expanding procurement of advanced filtration units to meet infection-control protocols in high-turnover wards.
- Germany:Aging-population healthcare spending sustains above-average replacement cycles for medical-grade respiratory protection in acute-care settings.
Market Restraints
- Polypropylene supply concentration:Melt-blown nonwoven feedstock dependence on specialized petrochemical suppliers creates input cost volatility.
- CE marking timelines:EU Medical Device Regulation qualification periods extend product-launch windows for European market entry.
- Reusable segment competition:Sustainability pressures in institutional procurement are fragmenting volume leadership away from disposable units.
Strategic Opportunities
- Japan PMDA alignment:Domestic standards harmonization with ISO filtration benchmarks creates pathways for suppliers meeting multi-jurisdictional requirements.
- LED-therapy convergence:Skincare-treatment apparatus incorporating precision light-wavelength parameters command premium price realization in consumer channels.
- Emergency-preparedness stockpiling:National reserve specifications are generating demand-step changes independent of routine healthcare procurement cycles.
Industry Challenges
- FDA 510(k) pathway complexity:Respiratory-device clearance timelines require substantial documentation of filtration-efficiency equivalence.
- Multi-jurisdictional compliance burdens:Suppliers must simultaneously navigate OSHA, CE marking, and PMDA standards without standardized test-protocol reciprocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Mask Device Market |
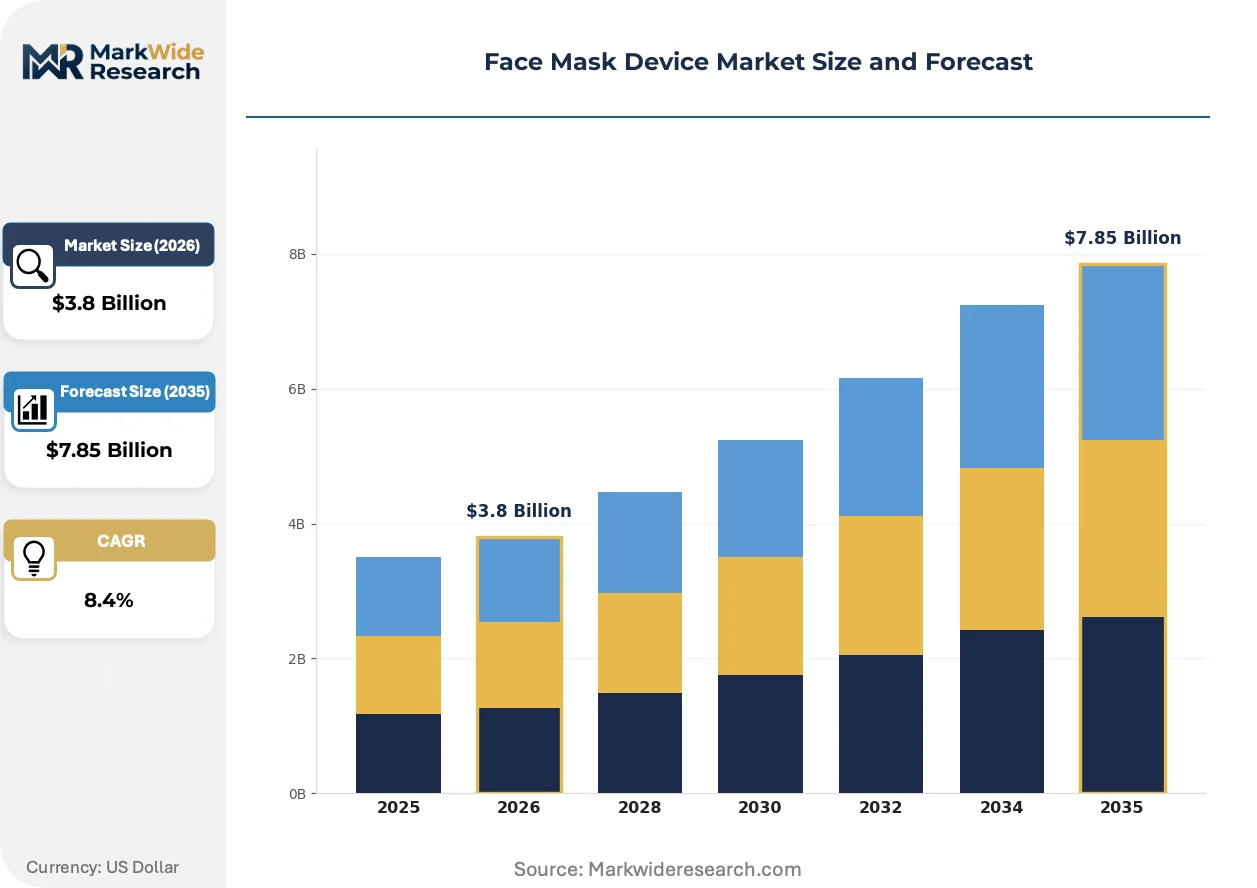
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Masks, N95 Respirators, Cloth Masks, Face Shields Application: Healthcare, Industrial Safety, Consumer Use, Laboratory Technology: Reusable, Disposable, Antimicrobial, Filter Technology End User: Hospitals, General Public, Industrial Workers, Healthcare Providers |
| Companies Covered | Philips, Panasonic Corporation, LG Electronics, NuFACE, Ya-Man, CurrentBody, Dr Dennis Gross, Foreo, LightStim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Mask Device Market Shifts & Advancements
Active filtration materials and connected monitoring capabilities are converging with dermatological light-therapy systems, blurring traditional boundaries between clinical respiratory protection and consumer wellness devices.
Electrospun nanofiber membranes are achieving sub-micron particle capture with reduced breathing resistance. Hospital procurement teams in the United States and Germany are piloting these materials in extended-wear N95 applications. The technology is miniaturizing filter footprints while maintaining certification-grade performance, enabling integration into wearable form factors previously constrained by bulk.
EU Medical Device Regulation enforcement is tightening post-market surveillance requirements for respiratory protective equipment. Manufacturers must now maintain technical documentation and vigilance systems comparable to implantable device standards. European suppliers are responding by consolidating quality-management systems across CE-marked and FDA-cleared product lines to reduce compliance redundancy.
Institutional buyers are unbundling after-sales service from equipment procurement contracts. Hospital systems in Japan are negotiating filter-replacement subscriptions separate from initial device purchases, compressing supplier revenue recognition timelines. This pattern is most visible in metropolitan acute-care networks where inventory management has shifted to third-party logistics providers.
Face Mask Device Market Segmentation
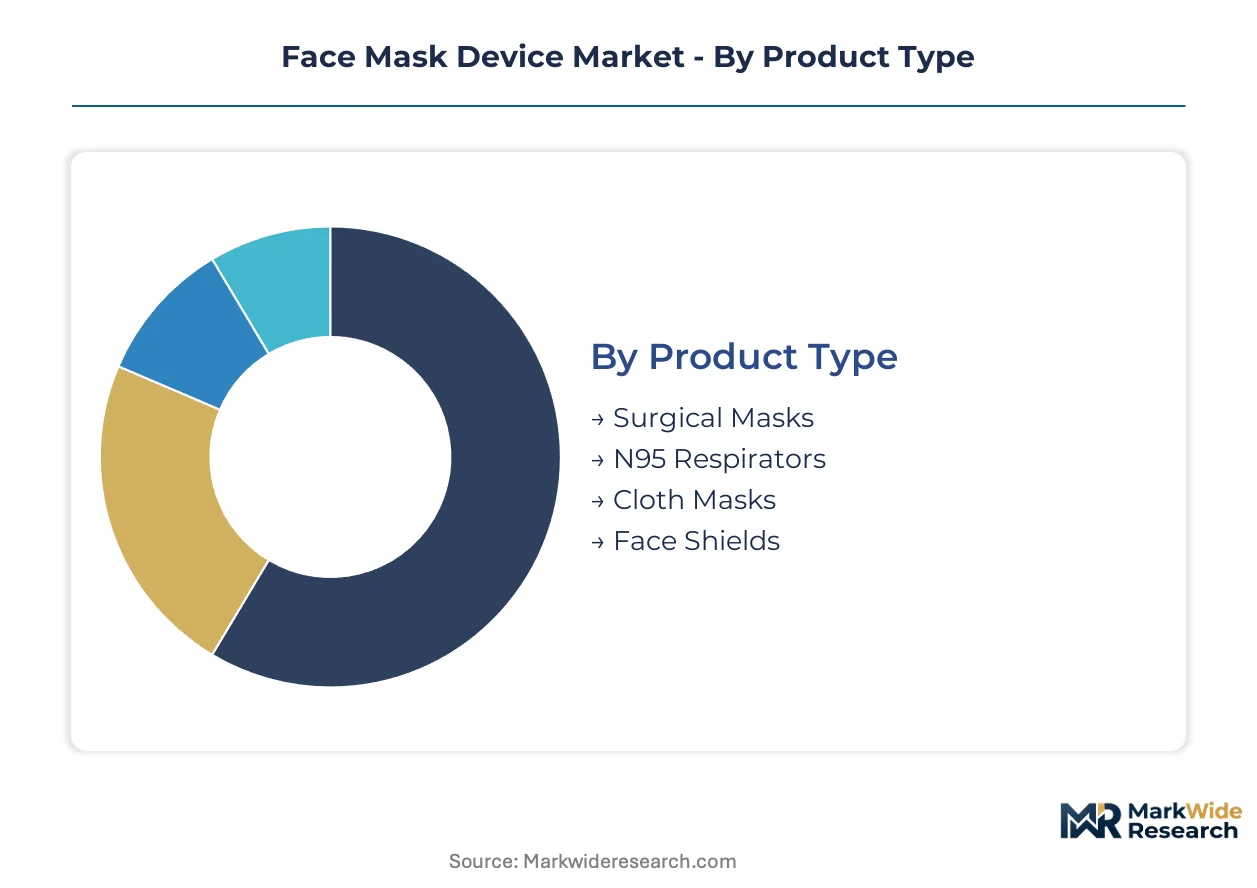
Segmentation in the face mask device market reveals how procurement mandates, certification tiers, and end-use specifications fragment revenue pools across fundamentally different technical and commercial requirements. Understanding these divisions exposes where margin concentration aligns with regulatory barriers versus where commoditization pressures dominate.
Product Type:
Margin pools concentrate where filtration certification creates procurement lock-in and replacement scheduling.
- N95 Respirators:Electrostatic melt-blown polypropylene layers achieve 95% particle filtration at 0.3 microns per NIOSH standards. Hospital systems in the United States enforce quarterly replacement cycles in airborne isolation units, sustaining contracted revenue streams.
- Surgical Masks:Three-ply nonwoven construction with fluid-resistant outer layers meets ASTM F2100 Level 1-3 benchmarks. German acute-care networks specify Level 3 units for operating theaters, where single-use protocols generate volume throughput independent of pandemic spikes.
- Cloth Masks:Woven cotton-polyester blends with optional filter pockets occupy consumer channels where fashion and comfort trade off against certified protection.
- Face Shields:PET or polycarbonate visors with foam forehead bands provide splash protection without respiratory filtration, serving dental and ophthalmology practices.
N95 Respirators hold installed capacity. Surgical Masks are rotating up the share rankings.
Application:
Application segments diverge sharply between regulated institutional procurement and discretionary consumer purchasing.
- Healthcare:Infection-control protocols in Japanese metropolitan hospitals mandate N95-grade protection for tuberculosis and varicella exposure, with METI-coordinated stockpile specifications layering demand atop routine procurement.
- Industrial Safety:OSHA respiratory-protection program requirements in United States manufacturing enforce fit-testing and medical clearance workflows that embed mask vendors into corporate safety infrastructure.
- Consumer Use:Retail channels and e-commerce platforms serve allergy management and public-transit protection needs with minimal regulatory overlay.
- Laboratory:Biosafety level 2 and 3 facilities require specialized respirators for aerosol-generating procedures with pathogenic agents.
Healthcare commands pricing power. Industrial Safety is climbing the fastest as manufacturing reshoring intensifies.
Technology:
Technology categories split between sustainability-driven reuse models and infection-control-driven disposability.
- Disposable:Single-use polypropylene construction dominates emergency-preparedness stockpiling and high-turnover hospital wards where cross-contamination protocols prohibit reuse.
- Antimicrobial:Silver-ion or copper-oxide integrated textiles target extended-wear applications in German industrial settings where replacement frequency carries labor costs.
- Reusable:Silicone elastomeric respirators with replaceable filter cartridges serve United States construction sectors where OSHA fit-testing investment favors durable platforms.
- Filter Technology:Electrospun nanofiber membranes enable sub-micron capture with reduced breathing resistance, piloting in extended-wear N95 applications.
Disposable maintains volume leadership. Antimicrobial is gaining share fastest on sustainability pressures.
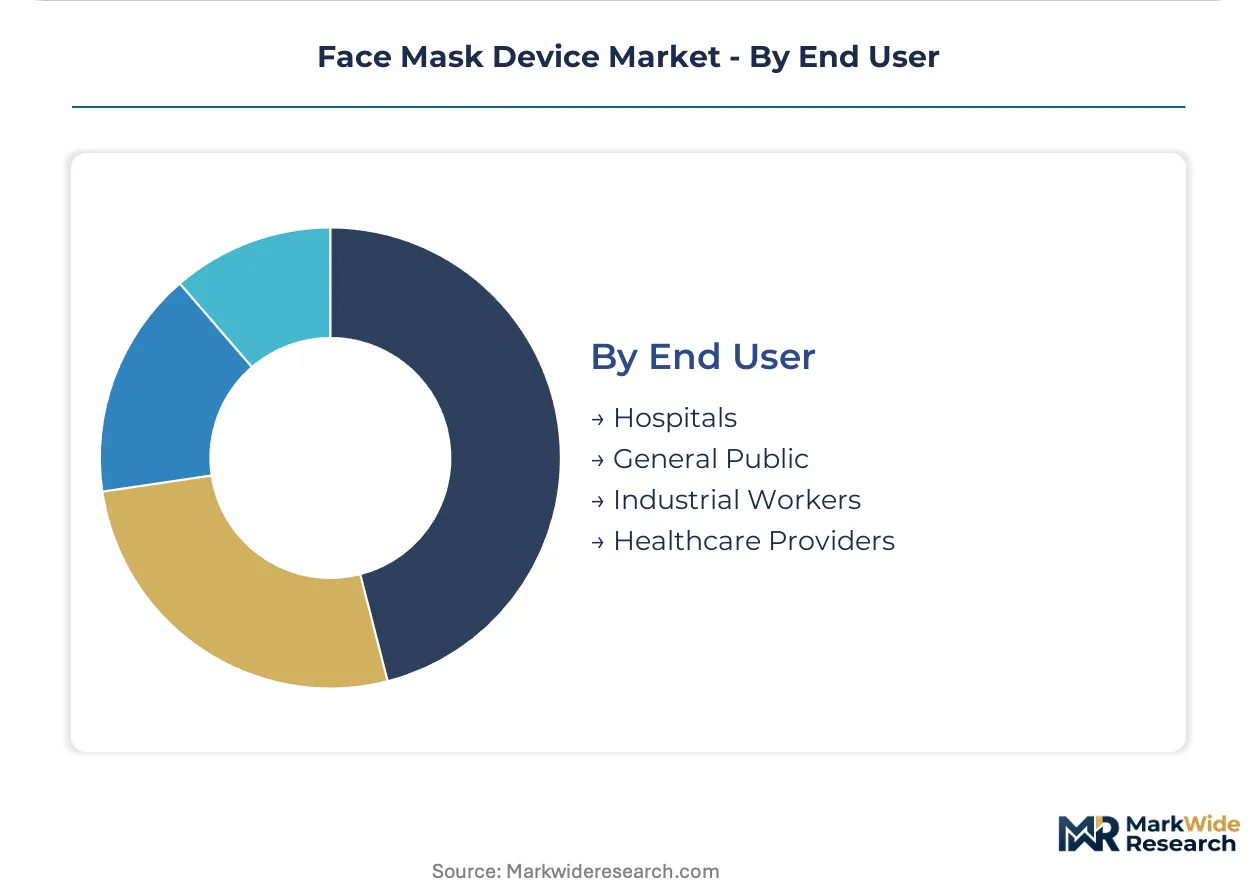
End User:
End-user concentration reflects how procurement centralization versus fragmentation shapes supplier access and pricing leverage.
- Hospitals:Group purchasing organizations in the United States consolidate demand across multi-hospital systems, compressing supplier margins in exchange for volume commitments and sole-source contracts.
- Healthcare Providers:Individual physician practices and outpatient clinics purchase through distributor channels with less pricing power than integrated delivery networks.
- Industrial Workers:Employer-mandated respiratory-protection programs in Japan's automotive and electronics manufacturing create recurring replacement demand tied to shift schedules.
- General Public:Seasonal and event-driven purchasing through retail and online channels exhibits price sensitivity and brand volatility.
Hospitals anchor contract value. Healthcare Providers are expanding fastest as ambulatory surgery center networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports electrospun nanofiber membranes and melt-blown polypropylene feedstock to hospital systems in Germany and the United States, anchoring the upstream supply corridor for certified respiratory protection.
United States
OSHA respiratory-protection programs in manufacturing and construction sectors enforce quarterly N95 replacement schedules. FDA 510(k) clearance pathways require documented filtration-efficiency equivalence for market entry. Hospital systems in Texas and California consolidate procurement through group purchasing organizations, compressing supplier margins in exchange for volume commitments.
Germany
Aging-population healthcare spending sustains above-average replacement cycles for medical-grade respiratory protection in acute-care settings. CE marking under the EU Medical Device Regulation extends qualification timelines for European market entry. Industrial clusters in Bavaria and North Rhine-Westphalia pilot antimicrobial-filter technology in extended-wear applications where replacement frequency carries labor costs.
Japan
METI-coordinated stockpile specifications layer demand atop routine hospital procurement for tuberculosis and varicella exposure protection. PMDA alignment with ISO filtration benchmarks creates multi-jurisdictional compliance pathways for scaled suppliers. Automotive and electronics manufacturing in the Chubu and Kansai regions generate recurring replacement demand tied to employer-mandated respiratory-protection programs.
China
Domestic production of melt-blown nonwoven feedstock supplies both local hospital systems and export markets. NMPA standards for medical device registration shape product-qualification timelines for domestic manufacturers. Yangtze River Delta industrial zones concentrate electrospun nanofiber membrane fabrication for sub-micron particle capture applications.
South Korea
MFDS medical device regulations govern respiratory protective equipment certification alongside semiconductor cleanroom filtration standards. Seoul Capital Area hospital networks specify N95-grade protection for infection-control protocols in high-turnover wards. Busan-Ulsan manufacturing corridors enforce sustained replacement schedules for industrial-safety mandates in shipbuilding and petrochemical sectors.
Face Mask Device Market Competitive Landscape
Listed leaders compete with private specialists across certification-tier positioning and channel access. The vendor base stratifies between respiratory-therapy heritage players, consumer-wearables innovators, and manufacturing-scale fabricators. Three archetypes dominate: hospital-procurement anchors leveraging FDA-cleared portfolios, premium consumer-channel specialists commanding price realization through skincare convergence, and precision-filter manufacturers extending semiconductor cleanroom expertise. Consolidation pressures favor backward integration into melt-blown feedstock and quality-management system unification across CE-marked and FDA-cleared product lines.
Among Asia-Pacific-based fabricators, Panasonic Corporation exemplifies the manufacturing-scale archetype, while LG Electronics occupies a diversified electronics position. Ya-Man represents the consumer-wearables specialization tier. Philips anchors the respiratory-therapy heritage segment in Western markets. NuFACE sits within the premium consumer-channel vector where LED-therapy convergence commands higher price realization.
| Leading Market Players |
|---|
| Philips |
| Panasonic Corporation |
| LG Electronics |
| NuFACE |
| Ya-Man |
| CurrentBody |
| Dr Dennis Gross |
| Foreo |
| LightStim |
| Others |
Supply & Pricing Matrix
Electrospun nanofiber membrane substitution for conventional melt-blown polypropylene is simultaneously shifting production geography toward China's Yangtze River Delta industrial zones and compressing margin structures for legacy filter manufacturers dependent on petrochemical feedstock pricing cycles.
Pricing Analysis
Next-generation electrospun nanofiber membranes command 40-60% premiums over conventional melt-blown N95 respirators, while prior-generation surgical masks face commodity pricing in high-volume hospital contracts. Three-tier pricing structure across premium antimicrobial-filter, standard N95-grade, and economy surgical tiers reflects certification-grade differentiation and volume scale. Cost compression in the economy tier is intensifying because Chinese feedstock suppliers are consolidating pricing power. Ambulatory surgery centers exhibit highest price sensitivity; integrated hospital systems leveraging group purchasing organization contracts demonstrate lowest sensitivity due to sole-source volume commitments.
Supply Chain Analysis
Extended lead times for specialized melt-blown polypropylene feedstock have compressed inventory buffers across United States and German hospital procurement networks. Manufacturing concentration centers on China for electrospun nanofiber membranes, Germany for precision filtration equipment, and the United States for NIOSH-certified respirator assembly. Raw material dependencies include polypropylene resin, silver-ion antimicrobial textiles, and silicone elastomer components. Single-source vulnerability in Yangtze River Delta electrospun membrane production creates exposure to regional logistics disruptions. Distribution runs through group purchasing organizations and third-party logistics providers serving metropolitan acute-care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified filtration engineering talent and multi-jurisdictional regulatory affairs capability represent scarce assets that constrain supplier scaling velocity and create acquisition premiums for qualified mid-tier manufacturers.
For Market Incumbents: Consolidate quality-management systems across CE-marked and FDA-cleared product lines to reduce compliance redundancy and defend against emerging electrospun membrane specialists. Backward integration into melt-blown polypropylene feedstock secures input cost stability against petrochemical volatility. Hospital procurement unbundling of filter-replacement subscriptions threatens revenue recognition timelines; channel control through direct service contracts mitigates this displacement. For New Entrants and Emerging Players: Lead with antimicrobial-filter technology targeting German industrial extended-wear applications where replacement frequency carries measurable labor cost savings. Japan's PMDA-ISO harmonization pathway offers the most penetrable regulatory entry for multi-jurisdictional qualification. A go-to-market angle emphasizing fit-testing workflow integration with employer safety infrastructure bypasses incumbent hospital procurement lock-in. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed respiratory-protection specialists possessing FDA 510(k) cleared portfolios but limited CE marking penetration. Long-term viability in this market hinges on dual-jurisdiction certification capability and electrospun membrane manufacturing scale. The inflection signal to watch is METI-coordinated Japanese stockpile specification shifts that would trigger demand-step changes independent of routine healthcare procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Opens United States hospital procurement channels requiring documented NIOSH filtration-equivalence. |
| CE Marking Under EU MDR | Enables European market access through extended qualification timelines with implantable-grade vigilance systems. |
| Hospital System Partnership | Secures sole-source contracts with group purchasing organizations in Texas and California metropolitan networks. |
| Backward Integration into Feedstock | Captures melt-blown polypropylene margin and insulates against Yangtze River Delta supply volatility. |
| Software Companion Development | Supports connected monitoring capabilities converging with dermatological light-therapy wearable platforms. |
Research Methodology
A standing panel of hospital procurement directors, biomedical engineers, GPO contracts managers, and OSHA compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, CE marking databases under EU MDR, NIOSH respirator approval lists, and hospital procurement contract repositories. Bottom-up demand modeling triangulated against top-down filtration equipment spending benchmarks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, application setting, technology platform, and end-user procurement centralization. CAGRs were derived from replacement cycle analysis, stockpile specification shifts, and antimicrobial-filter adoption curves. Forecast inputs incorporated OSHA enforcement intensity, METI stockpile coordination signals, and electrospun membrane manufacturing capacity expansion.
The analysis sits within stated boundaries; outcomes outside sustained healthcare spending growth, regulatory harmonization acceleration, or feedstock supply stability would require recalibration. Forecasts reflect documented assumptions regarding certification timeline trajectories and procurement mandate evolution. Pandemic demand volatility, polypropylene price spikes, or CE marking reciprocity failures represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Spinal Traction Market
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
PPG Biosensors Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Global Pupillometer Market