
 Book Printing Service Market | 2026-2036
Book Printing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Book Printing Service Market Insights
Print-on-demand fulfillment revenue is rewriting profit distribution across the book printing service value chain. Amazon KDP Print leverages its captive marketplace to control author acquisition costs. IngramSpark sustains wholesale distribution reach through physical infrastructure density. R.R. Donnelley anchors large-run offset contracts with major trade publishers.
Book printing service encompasses the commercial production of bound reading materials through mechanical reproduction processes, typically employing web-fed offset presses at speeds exceeding 15,000 impressions per hour or toner-based digital systems for runs below 500 copies, serving trade publishing, educational content, and corporate communication needs. Offset printing retains dominance in high-volume hardcover production where unit economics favor amortized plate costs across ten-thousand-copy runs. Digital printing captures accelerating paperback volume from self-published authors and academic niche titles where inventory risk outweighs per-unit premiums. Perfect binding has displaced saddle stitching across most adult trade segments as glue-bound spines accommodate thicker volumes and improved shelf presentation.
FDA guidelines for ink constituents in food-contact packaging indirectly constrain coating formulations migrating into book manufacturing supply chains, while EPA National Emission Standards for Hazardous Air Pollutants govern volatile organic compound discharge from commercial print facilities. The EU REACH regulation restricts certain pigment chemistries in imported printed goods, reshaping material sourcing for publishers with transatlantic distribution. Stakeholders must monitor how state-level extended producer responsibility legislation evolves, as California and New York explore book-specific recycling mandates that would alter reverse logistics obligations.
Market Dynamics
Digital print-on-demand infrastructure is collapsing the traditional offset-digital volume threshold, redistributing capacity investments away from large-run web presses toward toner and inkjet systems capable of profitable single-copy fulfillment.
Growth Catalysts
- Educational POD mandates:University systems in the United States are expanding print-on-demand textbook programs, eliminating inventory risk for academic publishers while preserving physical format preference among STEM disciplines.
- REACH pigment restrictions:The EU regulation is accelerating reformulation of coating chemistries, creating competitive advantage for European converters with certified solvent-free ink supply chains.
- Self-publishing platforms:Amazon KDP Print and IngramSpark have concentrated author acquisition through integrated distribution, pulling volume from traditional offset channels into digital-first fulfillment networks.
Market Restraints
- Paper pulp cost volatility:Unbleached softwood kraft prices fluctuate with Scandinavian and Brazilian supply disruptions, compressing margin predictability for mid-scale offset operators without long-term fiber contracts.
- Platemaking asset concentration:High-volume CTP (computer-to-plate) systems require capital intensity that favors consolidated North American and German equipment suppliers, limiting entry for regional competitors.
- E-reader substitution in trade fiction:Kindle and Kobo devices capture leisure reading hours, constraining paperback reprint demand for backlist titles previously sustaining offset run lengths.
Strategic Opportunities
- India educational localization:State textbook boards and private curriculum publishers present underpenetrated demand for regional-language digital printing as English-medium saturation limits growth in metropolitan markets.
- Extended producer responsibility tailwinds:California and New York legislative proposals for book-specific recycling mandates would create first-mover advantage for printers with established reverse logistics and fiber recovery partnerships.
- Web-to-print convergence:Integration of cloud-based design tools with digital press control systems enables direct-to-consumer hardcover production, collapsing traditional publisher-wholesaler-retailer intermediation.
Industry Challenges
- Prepress technician scarcity:Color management and ICC profile calibration expertise is concentrating among aging workforces in Midwestern United States print corridors, constraining quality consistency at expanding digital facilities.
- Legacy MIS integration:ERP systems designed for offset job ticketing require costly middleware development to accommodate variable-data digital workflows, delaying real-time production visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Book Printing Service Market |
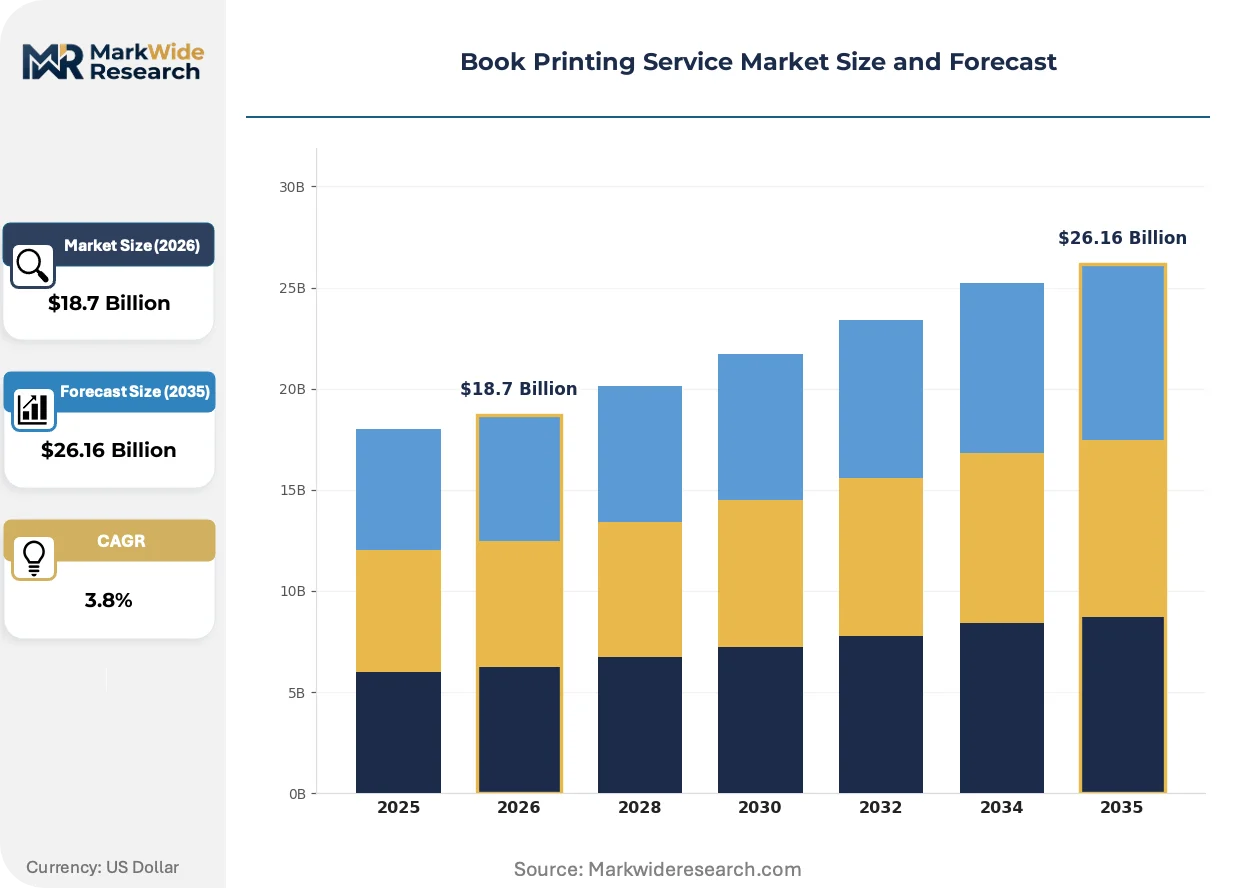
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardcover, Paperback, E-book, Audiobook Print Technology: Digital Printing, Offset Printing, Letterpress, Flexography Binding Type: Saddle Stitching, Perfect Binding, Spiral Binding, Comb Binding End User: Authors, Publishers, Educational Institutions, Corporations |
| Companies Covered | IngramSpark, Amazon KDP Print, BookBaby, Lulu, Blurb, R.R. Donnelley, Quebecor World, Transcontinental Printing, Gorham Printing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Book Printing Service Market Trends and Innovations
Sheet-fed inkjet technology is collapsing the cost barrier between digital and offset economics, enabling short-run color hardcovers at unit costs previously achievable only through amortized web press production.
High-speed inkjet web presses utilizing water-based pigment inks are collapsing the traditional 500-copy minimum for color trade books. Academic niche publishers and regional university presses in the United Kingdom and Germany are adopting these systems for print runs of 50-200 copies. The technology is collapsing inventory carrying costs and enabling just-in-time reprint models for slow-moving backlist titles.
EPA National Emission Standards for Hazardous Air Pollutants are tightening volatile organic compound discharge limits for commercial print facilities in the United States. Offset operators face capital expenditure requirements for thermal oxidizers or solvent recovery systems. Midwestern and Southeastern states with concentrated printing employment are experiencing accelerated facility consolidation as smaller operators exit rather than retrofit.
University procurement departments are consolidating textbook acquisition through centralized print-on-demand contracts, displacing decentralized bookstore purchasing. IngramSpark and Amazon KDP Print capture this consolidated demand through direct institutional agreements. The shift is most visible in California and Texas public university systems, where statewide purchasing cooperatives negotiate volume pricing with approved digital fulfillment networks.
Book Printing Service Market Segmentation
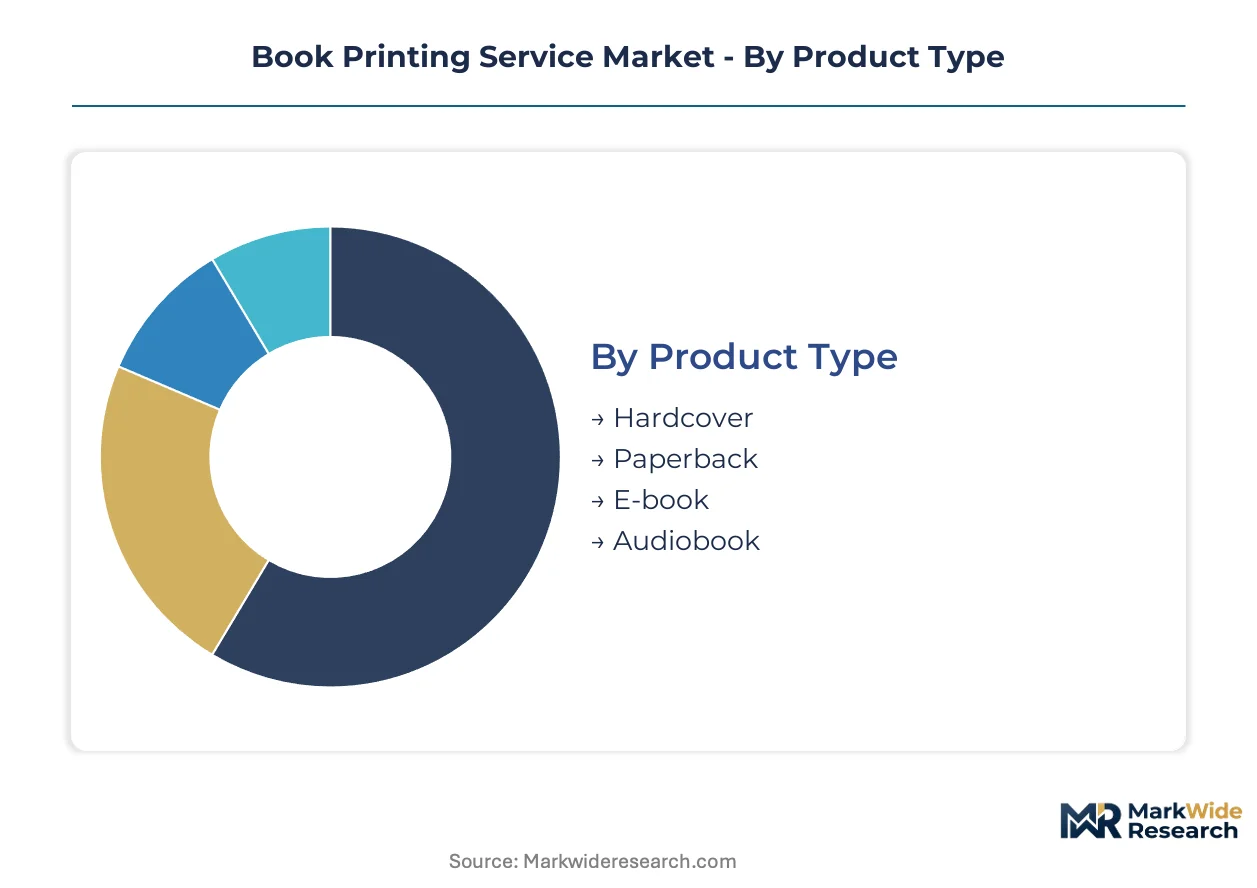
Segmentation in book printing services determines equipment specialization, margin profiles, and customer retention mechanics. Service providers configure press floors and finishing lines around specific format-technology combinations that lock in recurring volume from institutional buyers.
Product Type:
After-sales service intensity varies sharply across formats, with hardcover programs demanding binding repair partnerships and paperback fulfillment requiring rapid reprint responsiveness.
- Hardcover:Smyth-sewn or adhesive casebound construction with rigid board covers supports archival durability and premium retail presentation. University presses in the United States concentrate hardcover demand for monographs and library editions where replacement cycles extend across decades.
- Paperback:Perfect-bound softcover formats dominate trade fiction and mass-market distribution through lighter weight and lower unit cost. Self-published authors through Amazon KDP Print and IngramSpark pull paperback volume into digital-first fulfillment networks where inventory risk elimination outweighs per-unit premiums.
- E-book:Digital file distribution requires no physical production infrastructure but competes for publisher content acquisition budgets against print formats.
- Audiobook:Audio production and streaming distribution operates through distinct studio and platform economics with minimal overlap to print service providers.
By volume, paperback leads. By growth pace, hardcover is expanding most quickly through academic niche reprints.
Print Technology:
Cost tier stratification separates capital-intensive offset installations from digitally flexible toner and inkjet systems serving fragmented run-length demand.
- Digital Printing:Toner-based electrophotography and high-speed inkjet webs enable profitable single-copy fulfillment without platemaking overhead. IngramSpark and Amazon KDP Print route self-published and academic niche titles through digital networks where run lengths fall below offset economic thresholds.
- Offset Printing:Web-fed and sheet-fed lithographic systems amortize plate costs across high-volume runs exceeding ten thousand copies. R.R. Donnelley anchors large-run contracts with major trade publishers where unit economics favor amortized infrastructure.
- Letterpress:Relief printing from raised surfaces persists in specialty packaging and fine edition work with limited book application.
- Flexography:Rotary relief printing with flexible plates serves corrugated packaging and label markets with minimal book penetration.
By installed base, offset dominates. By capacity expansion, digital is climbing the fastest as toner and inkjet installations displace aging web press capacity.
Binding Type:
Application requirements dictate binding selection, with durability, lay-flat functionality, and cost trade-offs determining specification across end-use segments.
- Perfect Binding:Adhesive-bound square spines accommodate thicker volumes and improved shelf presentation across adult trade and academic segments. Glue-bound construction has displaced saddle stitching in most markets where spine branding and retail display matter.
- Saddle Stitching:Wire staples through the spine serve thin periodicals and children's booklets where low cost and rapid production outweigh durability concerns.
- Spiral Binding:Continuous wire or plastic coil enables full lay-flat functionality for workbooks, manuals, and educational materials requiring hands-free reference.
- Comb Binding:Plastic rectangular spines with removable pages persist in corporate training materials and presentation documents with low durability requirements.
By volume penetration, perfect binding leads. By functional differentiation, spiral binding is gaining share fastest through educational workbook expansion.
End User:
Customer type concentration shapes service bundling, with publishers demanding volume guarantees and educational institutions requiring procurement integration.
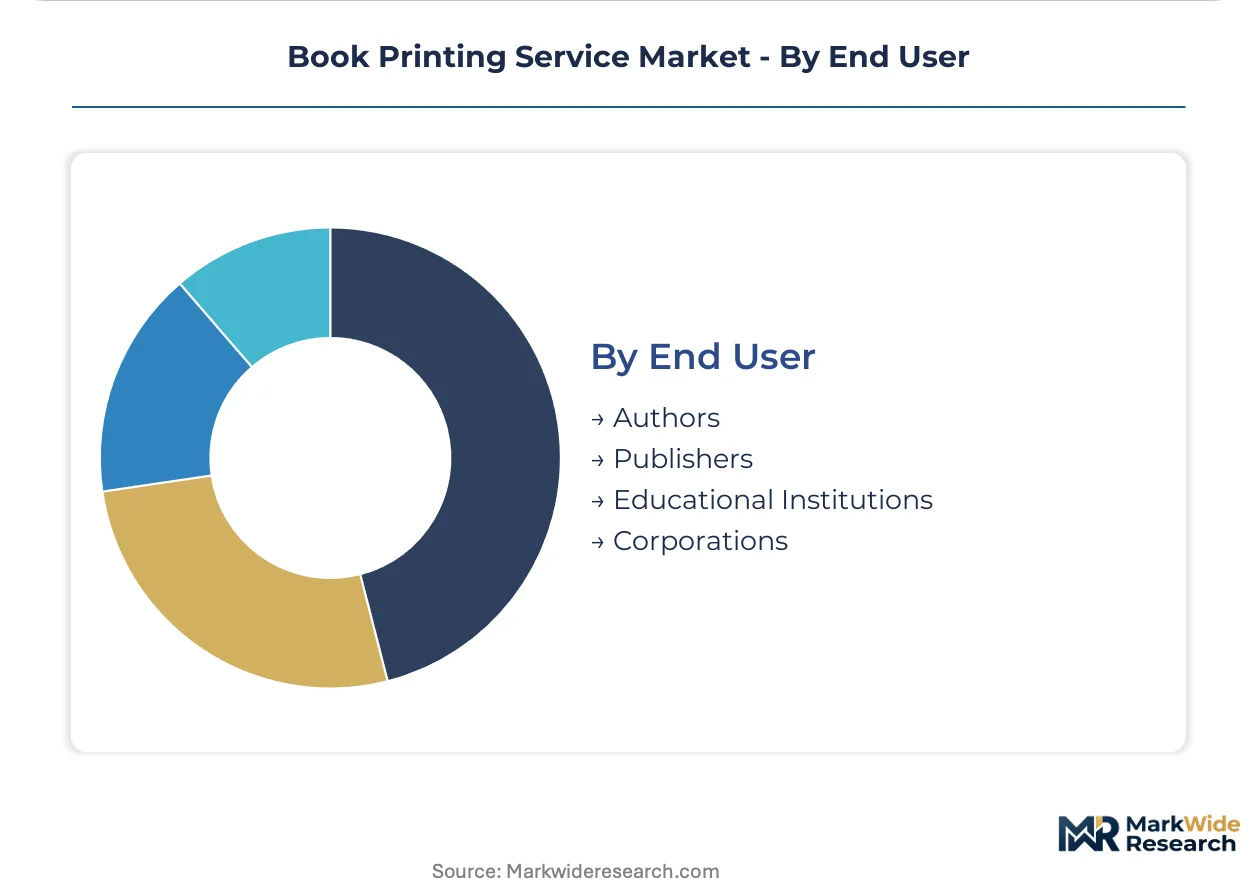
- Publishers:Trade, academic, and specialty houses contract for seasonal title production with complex logistics coordination and returns management. Consolidated procurement through centralized print-on-demand contracts is displacing decentralized purchasing in California and Texas public university systems.
- Authors:Self-publishing individuals access platforms like Amazon KDP Print and IngramSpark for direct-to-market distribution without traditional publisher intermediation.
- Educational Institutions:University presses and state textbook boards specify course materials with curriculum-aligned content and accessibility compliance requirements.
- Corporations:Annual reports, training manuals, and marketing collateral demand brand-consistent color reproduction with variable data personalization capabilities.
By revenue concentration, publishers lead. By platform-driven expansion, authors are climbing the fastest through self-publishing volume migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-format web press capacity clusters in the United States and Germany, while digital-first fulfillment networks expand fastest in India and Brazil. Regulatory divergence on emissions and chemical safety is fragmenting equipment sourcing strategies across jurisdictions.
United States
University presses and self-publishing platforms drive volume concentration, with California and Texas public systems consolidating textbook procurement through statewide purchasing cooperatives. EPA National Emission Standards for Hazardous Air Pollutants tighten volatile organic compound discharge limits, accelerating facility consolidation in Midwestern and Southeastern states. The Chicago-Milwaukee corridor retains prepress technician expertise, though aging workforces constrain quality consistency at expanding digital operations.
Germany
Academic niche publishers and regional university presses adopt high-speed inkjet webs for runs of 50-200 copies, collapsing inventory carrying costs for slow-moving backlist titles. EU REACH regulation restricts certain pigment chemistries in imported printed goods, reshaping material sourcing for publishers with transatlantic distribution. The Rhine-Ruhr industrial cluster hosts concentrated offset capacity serving European trade publishing seasonal demand.
United Kingdom
University procurement departments consolidate textbook acquisition through centralized print-on-demand contracts, displacing decentralized bookstore purchasing. Extended producer responsibility legislation proposals in Westminster mirror California and New York approaches, potentially altering reverse logistics obligations. London-Oxford-Cambridge academic publishing corridor sustains hardcover monograph demand for library editions.
India
State textbook boards and private curriculum publishers present underpenetrated demand for regional-language digital printing as English-medium saturation limits growth in metropolitan markets. Bureau of Indian Standards certification requirements for educational materials create compliance barriers for imported print services. Maharashtra and Gujarat industrial clusters expand toner-based capacity to serve domestic academic and corporate training segments.
Brazil
Trade publishing seasonal production and corporate annual report printing sustain offset capacity in São Paulo and Rio de Janeiro metropolitan areas. ANVISA guidelines for ink constituents in food-contact packaging indirectly constrain coating formulations migrating into book manufacturing supply chains. The Southeast region concentrates equipment investment as smaller regional operators exit rather than meet rising environmental compliance costs.
Book Printing Service Market Competitive Landscape
Integrated platform operators and legacy offset specialists split the market along run-length and fulfillment speed vectors. Consolidation pressure concentrates among mid-scale offset operators lacking long-term fiber contracts or digital transition capital. Three archetypes dominate: captive marketplace platforms controlling author acquisition, wholesale distribution networks sustaining physical infrastructure density, and large-run offset anchors securing amortized volume contracts. Competitive moves center on cloud-based design tool integration and reverse logistics partnership formation.
Within the integrated platform tier, Amazon KDP Print and IngramSpark exemplify archetype dominance through marketplace captivity and wholesale reach respectively. R.R. Donnelley occupies a position as the scale-driven offset anchor securing major trade publisher contracts. These three companies represent the strategic poles around which regional competitors and niche specialists organize their positioning.
| Leading Market Players |
|---|
| IngramSpark |
| Amazon KDP Print |
| BookBaby |
| Lulu |
| Blurb |
| R.R. Donnelley |
| Quebecor World |
| Transcontinental Printing |
| Gorham Printing |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Midwestern United States offset facilities is compressing per-unit pricing power while accelerating migration toward digital-first fulfillment networks where utilization rates favor smaller run lengths.
Pricing Analysis
After-sales service revenue from binding repair partnerships and reprint responsiveness programs drives lifetime customer value more than initial print contracts. Pricing stratifies across premium hardcover monographs, standard trade paperbacks, and economy mass-market editions based on quality grade and volume scale. Cost compression in mid-scale offset tiers is intensifying because paper pulp cost volatility erodes margin predictability for operators lacking long-term fiber contracts. Self-published authors through Amazon KDP Print and IngramSpark exhibit highest price sensitivity, while university presses demonstrate lowest sensitivity due to curriculum-mandated procurement requirements.
Supply Chain Analysis
Extended payment terms from Scandinavian and Brazilian pulp suppliers are tightening working capital requirements for North American converters without supply-chain finance facilities. Raw material sourcing draws from unbleached softwood kraft pulp concentrated in Scandinavia and Brazil, with coating chemistries anchored in German and Chinese specialty chemical production. Single-source vulnerability in CTP equipment from consolidated North American and German suppliers constrains regional competitor entry. Distribution runs through three-tier publisher-wholesaler-retailer structures for offset volume, collapsing to direct-to-consumer fulfillment for digital print-on-demand networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against e-reader platforms capturing leisure reading hours and constraining paperback reprint demand for backlist titles.
For Market Incumbents: Entrench hardcover monograph relationships with university presses through Smyth-sewn archival durability guarantees and library binding repair partnerships. Deepen backward integration into solvent-free ink formulation to preempt EPA emissions compliance costs that are accelerating facility consolidation among smaller offset operators. Channel control through direct institutional agreements with California and Texas public university systems locks out competing fulfillment networks.
For New Entrants and Emerging Players: Maharashtra and Gujarat industrial clusters in India present underpenetrated demand for regional-language digital printing as English-medium saturation limits growth in metropolitan markets. State textbook boards and private curriculum publishers offer white-space access through Bureau of Indian Standards certification partnerships. A web-to-print convergence play integrating cloud-based design tools with toner-based press control systems enables direct-to-consumer hardcover production without legacy publisher intermediation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across high-speed inkjet web installations as unit economics approach offset thresholds for 50-200 copy runs. Acquisition targets should prioritize European converters with certified solvent-free ink supply chains positioned for EU REACH pigment restriction compliance. Watch for California and New York extended producer responsibility legislation as the inflection signal creating first-mover advantage for printers with established reverse logistics partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Speed Inkjet Web Adoption | Collapses 500-copy minimum threshold for color trade books in academic niche publishing. |
| Solvent-Free Ink Certification | Preempts EPA thermal oxidizer capex requirements tightening across Midwestern states. |
| Reverse Logistics Partnership | Positions for California and New York book-specific recycling mandate implementation. |
| Cloud-Based Design Integration | Enables direct-to-consumer hardcover production collapsing traditional intermediation. |
| Regional-Language Digital Capacity | Captures Maharashtra and Gujarat state textbook board demand beyond English saturation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with university press procurement directors, commercial print facility managers, self-publishing platform operators, prepress technicians, and educational materials distributors. Secondary validation drew from EPA National Emission Standards documentation, EU REACH regulatory filings, Bureau of Indian Standards certification records, customs trade data for paper pulp imports, and SEC disclosures from publicly traded print service providers. Bottom-up equipment installation counts and top-down publisher revenue allocations were triangulated to anchor volume estimates.
Calibration against historical run-length migration patterns and technology adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, print technology, binding type, and end-user archetype alongside regional regulatory cluster differentiation. CAGRs were derived from installed base turnover rates and capacity expansion announcements. Forecast inputs incorporated university procurement consolidation trends and self-publishing platform volume routing algorithms.
Practitioners should monitor EPA emissions standard enforcement intensity, EU REACH pigment restriction expansion, and e-reader device penetration rates for early signals of trajectory revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
ID Card Printers Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
Print on Demand Software Market
Printing Technology
Digital Franking Machine Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Global Microprinting Market
Printing Technology
Large Character Printers Market
Printing Technology
Professional Printers Market
Printing Technology
Card Printers Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Digital Paper System Market
Printing Technology
US Print on Demand Market
Printing Technology
Printing Machinery Market
Printing Technology
Photo Printing Market
Printing Technology
Digital Printing Market