
 Rapid Prototyping Market | 2026-2036
Rapid Prototyping Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Prototyping Market Intelligence
Demand from aerospace and medical device sectors for functional prototypes is rotating away from basic concept modeling applications. Protolabs leverages its digital manufacturing platform to serve on-demand production needs across these high-value industries. Stratasys specializes in polymer-based technologies like Fused Deposition Modeling for complex engineering parts. 3D Systems competes with a broad portfolio spanning both hardware and materials for various end-user requirements.
Rapid prototyping encompasses a group of additive manufacturing techniques that fabricate a physical part directly from a 3D CAD model. The process builds objects layer-by-layer, enabling fast iteration and design validation before committing to expensive production tooling. Among technologies, Powder Bed Fusion methods like Selective Laser Sintering are gaining share for producing durable functional testing parts. Fused Deposition Modeling continues to dominate the concept modeling application due to its cost-effectiveness and material variety.
Material and process validation is governed by a mix of international and national standards. ISO/ASTM 52900 provides a common terminology framework, while the FDA in the United States sets stringent guidelines for prototypes used in medical device development. In Europe, materials must comply with REACH regulations, and final products often require CE marking. Stakeholders must now decide whether to pursue in-house process certification or rely on qualified service bureaus.
Market Dynamics
The primary force shaping the market is the maturation of additive manufacturing from a tool for visual concept models into a viable method for producing functional, load-bearing components, driven by innovations in metal and polymer processing technologies.
Growth Catalysts
- Binder Jetting Innovations:These enable faster, more cost-effective production of complex metal parts, meeting demand from the automotive industry for functional prototypes and tooling.
- Automotive Sector Demand:Engineering clusters in Germany and Japan are accelerating adoption for functional testing of vehicle components and systems, compressing development timelines.
- Standardization Frameworks:The ISO/ASTM 52900 terminology standard provides a common language, facilitating clearer communication and broader technology adoption across global industries.
Market Restraints
- High Capital Costs:The significant upfront investment required for industrial-grade systems, particularly Powder Bed Fusion machines, limits adoption among smaller enterprises and departments.
- Material Limitations:The available range of qualified, high-performance materials for some additive processes remains narrower than for conventional manufacturing methods, restricting certain applications.
- Regulatory Scrutiny:Stringent FDA guidelines for medical device prototypes create lengthy and expensive validation cycles, slowing market entry for new healthcare applications.
Strategic Opportunities
- On-Demand Production:Service bureaus can expand beyond prototyping into distributed manufacturing of end-use parts for the aerospace and medical device sectors.
- Multi-Material Printing:Developing systems capable of printing with multiple materials simultaneously opens new applications for creating complex, functionally integrated parts in one build.
- Digital Manufacturing Platforms:Online platforms that connect designers with a network of qualified service providers lower entry barriers and expand market access globally.
Industry Challenges
- Talent Scarcity:A persistent shortage of engineers and technicians skilled in Design for Additive Manufacturing (DfAM) principles constrains effective technology utilization and innovation.
- Process Qualification:Establishing and certifying repeatable, consistent processes for critical functional parts remains a complex and time-consuming hurdle for many end-users.
- Workflow Integration:Integrating additive manufacturing data streams and quality control into existing enterprise resource planning and manufacturing execution systems is a significant challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Prototyping Market |
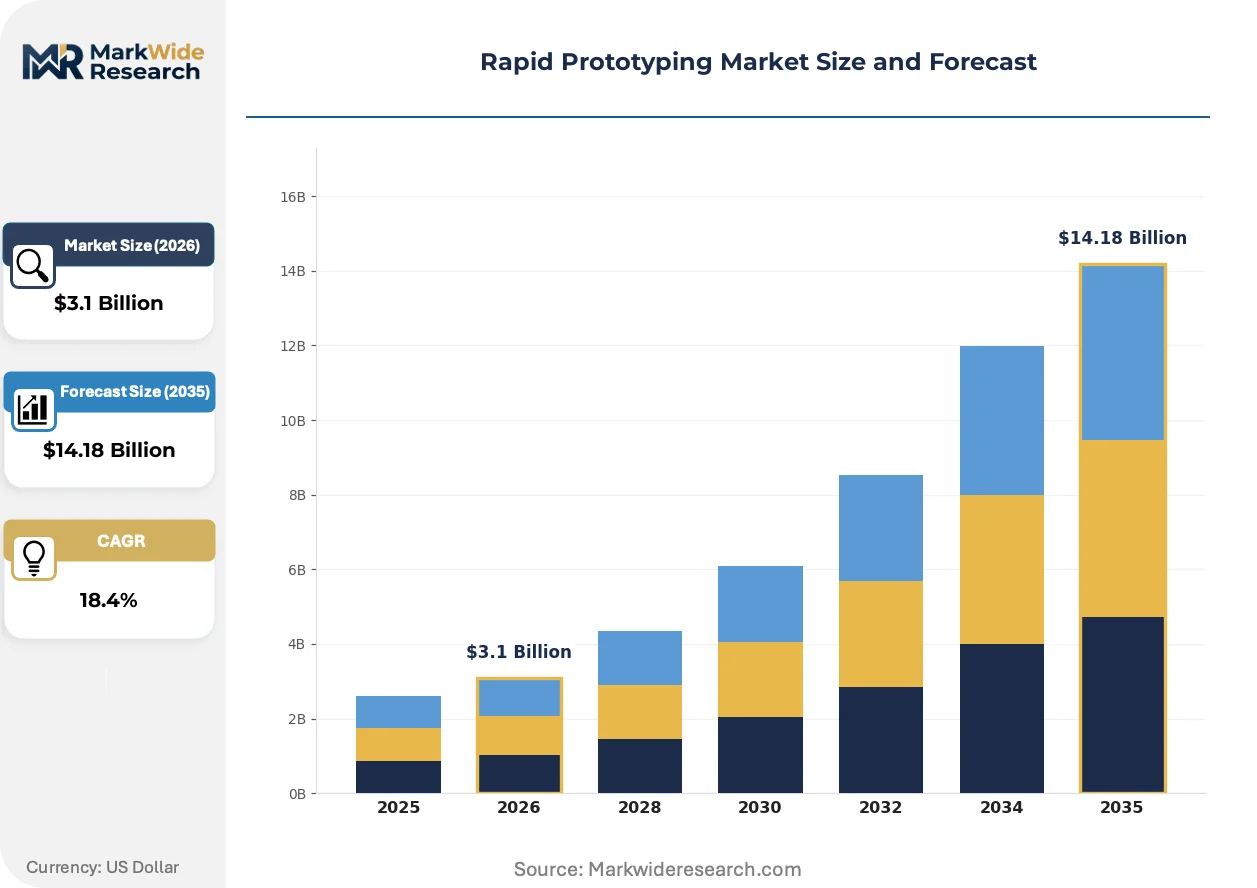
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $14.18 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stereolithography, Selective Laser Sintering, Fused Deposition Modeling, Digital Light Processing, Binder Jetting Technology: Laser-Based, Material Extrusion, Photopolymerization, Powder Bed Fusion, Material Jetting Application: Product Development, Tooling, Concept Modeling, Functional Testing, Educational Use End User Industry: Aerospace, Consumer Electronics, Medical Devices, Architecture, Automotive Suppliers |
| Companies Covered | Protolabs, Stratasys, WayKen Rapid Manufacturing, Xometry, IN3DTEC TECHNOLOGY, RPWORLD, 3D Systems, Formlabs, Kaiao Rapid Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Prototyping Market Strategic Shifts & Innovations
The industrialization of additive manufacturing defines current market evolution. This shift moves the technology's focus from one-off visualization aids toward repeatable, qualified processes suitable for both functional testing and direct part production across demanding sectors.
Powder Bed Fusion technologies like Selective Laser Sintering create durable parts from engineering-grade polymers. Aerospace and medical device industries are increasingly adopting this method for complex, functional prototypes that must withstand rigorous testing. This capability to produce robust, intricate geometries means PBF is supplanting traditional CNC machining for specific prototyping and low-volume production applications where design complexity is high.
Europe's REACH regulation imposes strict controls on chemical substances used in manufacturing. This directly impacts the polymers, resins, and metal powders central to rapid prototyping, requiring suppliers to conduct extensive safety and registration processes. Consequently, hardware manufacturers and service bureaus in the region increasingly favor pre-certified materials to ensure compliance and minimize supply chain risk.
A pivot toward distributed manufacturing is changing how companies source prototypes. Instead of relying on a single, centralized vendor, firms are using digital platforms to access a network of geographically dispersed, qualified service bureaus for on-demand production. This pattern is particularly visible within the automotive and consumer goods sectors, which prioritize supply chain agility and speed to market.
Rapid Prototyping Market Segmentation
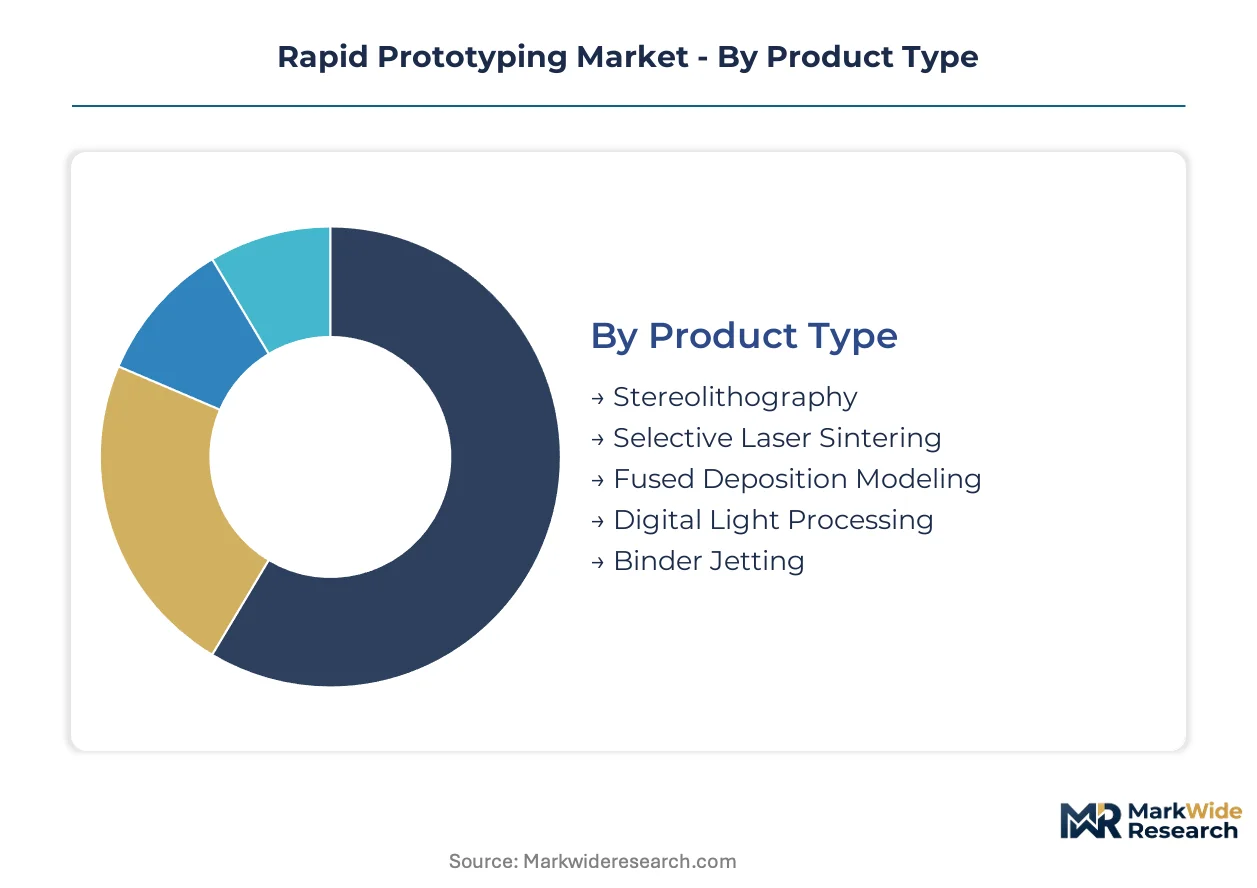
Rapid prototyping market segmentation reveals distinct demand patterns and technological preferences across diverse industrial applications. Understanding these categories informs strategic resource allocation for hardware manufacturers and service bureaus. This granular view highlights where value creation concentrates within the market.
Product Type:
Margin pools within product type segmentation are highest in technologies supporting functional, end-use part prototyping for demanding sectors.
- Selective Laser Sintering:This powder bed fusion method creates durable, functional prototypes from engineering-grade polymers. Aerospace and medical device industries demand these parts for rigorous testing.
- Binder Jetting:This additive process rapidly produces complex metal parts by binding powder layers. Automotive suppliers in Germany and Japan leverage this technology for cost-effective functional prototypes.
- Stereolithography:This photopolymerization process uses UV lasers to cure liquid resin, producing smooth, highly detailed visual models.
- Fused Deposition Modeling:This material extrusion technique builds parts by extruding thermoplastic filaments, offering cost-effective concept modeling.
- Digital Light Processing:This photopolymerization method uses a digital light projector to cure an entire layer of liquid resin simultaneously, enabling faster builds.
Fused Deposition Modeling holds installed capacity. Binder Jetting is rotating up the share rankings.
Technology:
Application focus drives technology selection across the rapid prototyping market, with specific processes optimized for different functional requirements.
- Powder Bed Fusion:This technology includes Selective Laser Sintering, producing strong, complex geometries from powders. Aerospace and medical device sectors adopt PBF for functional testing of load-bearing components.
- Material Extrusion:This technique, exemplified by Fused Deposition Modeling, builds objects layer-by-layer from extruded thermoplastic filaments. It remains cost-effective for concept modeling and basic fit-and-form prototypes.
- Laser-Based:These technologies, including Stereolithography and Selective Laser Sintering, utilize lasers for curing or fusing materials.
- Photopolymerization:This category encompasses Stereolithography and Digital Light Processing, relying on light to solidify liquid resins.
- Material Jetting:This process selectively deposits photopolymer resin droplets, cured by UV light, enabling multi-material and full-color prints.
Powder Bed Fusion technology provides a foundation for durable functional parts. Material Extrusion expands capabilities for accessible concept modeling.
Application:
Customer type drives application demand, with industrial users prioritizing functional validation and iterative design processes.
- Functional Testing:This application involves producing prototypes to validate performance, durability, and fit under operational conditions. Automotive suppliers and medical device manufacturers rely on this for design validation before mass production.
- Product Development:This application utilizes rapid prototyping for iterative design cycles, enabling quick modifications and evaluations of new product concepts. Speed to market for consumer electronics and industrial machinery benefits significantly.
- Tooling:Rapid prototyping creates jigs, fixtures, and molds for manufacturing processes, compressing production timelines.
- Concept Modeling:This application focuses on producing visual and tactile models for design review, form validation, and client presentations.
- Educational Use:Academic institutions and training centers employ rapid prototyping to teach design principles and additive manufacturing techniques.
Functional Testing drives significant investment in advanced materials. Product Development expands its user base across engineering disciplines.
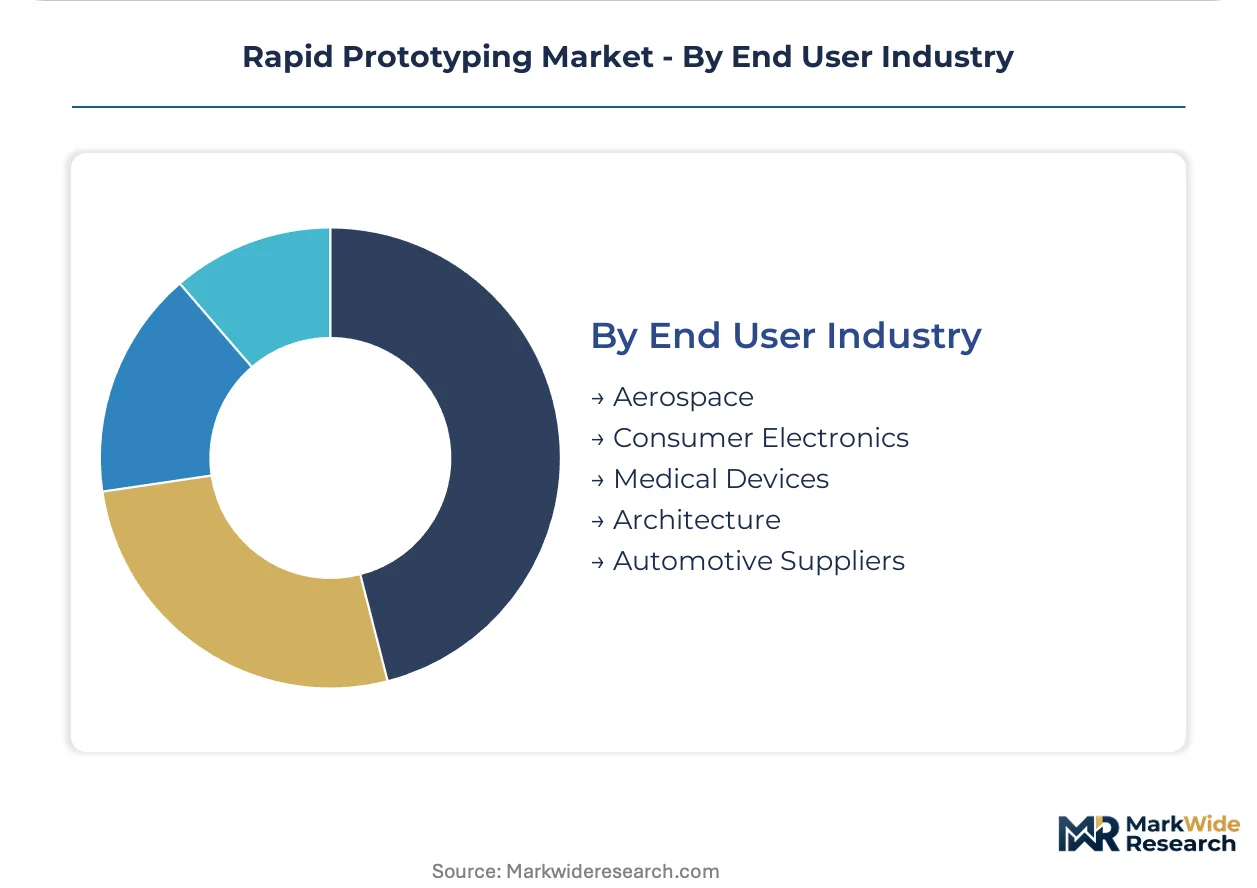
End User Industry:
Supply concentration influences service delivery models for end-user industries, with specialized bureaus serving highly regulated sectors.
- Automotive Suppliers:This segment leverages rapid prototyping for functional testing of vehicle components and systems. Engineering clusters in Germany and Japan are key demand centers for binder jetting innovations.
- Medical Devices:This sector utilizes prototypes for design validation and functional testing of implants, surgical tools, and diagnostic equipment. Stringent FDA guidelines in the United States govern material and process qualification.
- Aerospace:This industry employs rapid prototyping for complex, lightweight components and functional testing of critical parts.
- Consumer Electronics:This sector uses rapid prototyping for rapid iteration of product designs, accelerating time-to-market for new gadgets.
- Architecture:This industry applies rapid prototyping for creating detailed scale models and complex structural visualizations.
Automotive Suppliers demand stringent process validation. Medical Devices represent the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global rapid prototyping market benefits from advanced manufacturing infrastructure and established supply chains in key industrial regions. Major transportation hubs facilitate the movement of specialized equipment and materials for additive manufacturing. These regions are critical for both demand generation and technological innovation.
Germany
Germany's robust automotive engineering sector drives significant demand for functional prototypes and tooling. The KBA automotive regulator influences material and process validation for vehicle components. Industrial clusters in Bavaria and Baden-Württemberg concentrate advanced manufacturing facilities, accelerating binder jetting adoption for complex metal parts.
Japan
Japanese automotive manufacturers prioritize rapid iteration and functional testing of vehicle systems. METI policies support advanced manufacturing technologies and material science research. Tokyo and Nagoya serve as key centers for automotive R&D, fostering demand for cost-effective functional prototypes.
United States
The United States medical device industry demands rapid prototyping for design validation and functional testing. Stringent FDA guidelines govern material and process qualification for medical device prototypes. Silicon Valley and Boston's biotech hubs attract significant investment in advanced additive manufacturing capabilities for healthcare applications.
China
China's extensive industrial base and consumer electronics sector necessitate rapid product development and concept modeling. GB standards provide a framework for material and product quality across various industries. Manufacturing zones in the Yangtze River Delta and Pearl River Delta drive volume demand for cost-effective Fused Deposition Modeling solutions.
United Kingdom
The United Kingdom's aerospace sector increasingly adopts rapid prototyping for complex, lightweight components and functional testing. REACH regulations impact the chemical substances used in additive manufacturing materials within the region. Engineering hubs around Bristol and Derby focus on advanced materials and processes for critical aerospace applications.
Rapid Prototyping Market Key Industry Players
Listed leaders compete with private specialists across the rapid prototyping value chain, from hardware manufacturing to on-demand service provision. The market exhibits a tiered structure, with established players offering broad portfolios and niche firms focusing on specialized materials or applications. Strategic archetypes include integrated solution providers, specialized service bureaus, and material science innovators. Dominant competitive moves involve strategic partnerships for technology co-development and capacity expansion to meet regional demand.
Integrated solution providers like Protolabs and 3D Systems offer extensive digital manufacturing platforms and broad technology portfolios for diverse end-user requirements. These companies leverage their scale to serve on-demand production needs across high-value industries. Stratasys exemplifies a specialist in polymer-based technologies, focusing on Fused Deposition Modeling for complex engineering parts. These firms collectively anchor different segments of the rapid prototyping market, from concept modeling to functional testing.
| Leading Market Players |
|---|
| Protolabs |
| Stratasys |
| WayKen Rapid Manufacturing |
| Xometry |
| IN3DTEC TECHNOLOGY |
| RPWORLD |
| 3D Systems |
| Formlabs |
| Kaiao Rapid Manufacturing |
| Others |
Cost & Logistics Intelligence
High capacity utilization in industrial-grade rapid prototyping facilities drives economies of scale, influencing both supply concentration among major players and setting competitive price floors for various applications.
Pricing Analysis
Volume-based discount models characterize rapid prototyping pricing, particularly for high-volume concept modeling applications. Price differentiation stems from material certification levels, such as FDA compliance for medical devices, and the complexity of part geometry. Pricing softness for basic FDM services reflects increasing competition from smaller service bureaus. Automotive suppliers are generally less price-sensitive for functional testing parts compared to consumer goods manufacturers seeking basic visual prototypes.
Supply Chain Analysis
Minimized inventory holding is a key operational goal, especially for on-demand rapid prototyping services, impacting lead times. Supply concentration for advanced systems and materials draws heavily from Germany, Japan, and the United States. The sector relies on specialized polymer powders, metal alloys, and photopolymer resins as critical inputs. Regulatory restrictions like Europe's REACH for chemical substances pose a structural supply chain risk. Distribution runs primarily through direct sales channels for hardware and digital platforms for service bureaus.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rapid prototyping market incumbents must defend against substitution from advanced traditional manufacturing methods for low-volume production. CNC machining for specific complex geometries represents a persistent threat that established players must navigate.
For Market Incumbents: Consolidate digital manufacturing platforms to offer integrated hardware and service solutions across regions. Invest in process certification for highly regulated sectors like medical devices, countering the threat of specialized service bureaus. Deepen vertical integration into advanced material development, leveraging R&D to maintain a technological edge against emerging polymer processing technologies. Expand capacity in established manufacturing clusters, securing market share against regional competitors.
For New Entrants and Emerging Players: Certification fast-tracks for niche applications in less regulated industries offer a clear entry point. Target the consumer goods sector for rapid iteration of product designs, leveraging cost-effective FDM solutions. Focus on multi-material printing capabilities for functionally integrated parts, a white space with high demand from product development teams. A direct-to-consumer digital platform offering transparent pricing can attract smaller enterprises.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized service bureaus with validated processes for functional testing. Long-term viability across the next 5-10 years hinges on the industrialization of additive manufacturing for end-use parts. Target acquisition profiles include firms with strong intellectual property in binder jetting or advanced polymer processing. The signal to watch is the increasing adoption of PBF for aerospace and medical device production, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Streamlines order placement and production management for diverse end-user requirements. |
| Advanced Material R&D Investment | Expands application scope for functional prototypes in aerospace and medical device sectors. |
| Process Certification Expansion | Enables compliance with stringent FDA guidelines for medical device prototypes. |
| Binder Jetting Capacity Addition | Meets growing demand for cost-effective metal parts from automotive suppliers. |
| Multi-Material Printing Development | Unlocks new applications for complex, functionally integrated components in product development. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, regulatory specialists, and production engineers anchored the qualitative base for this analysis. Primary interviews with these industry stakeholders were triangulated with extensive secondary research. Secondary data sources included ISO/ASTM standards, FDA guidelines, REACH regulations, and patent databases. This approach ensured robust bottom-up and top-down validation of market dynamics.
Sensitivity analysis informed the projection framework, evaluating various market scenarios across the analysis window. The quantitative model segmented the market by product type, technology, application, end-user industry, and material class. Compound Annual Growth Rates were derived from historical trends and forward-looking demand indicators. Key forecast inputs included automotive production volumes and medical device regulatory approvals.
Decision-makers should treat outputs as directional under current material cost and technological development assumptions; material deviation would warrant model refresh. Forecasts reflect a baseline scenario, acknowledging risks like unexpected regulatory shifts impacting adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Saudi Arabia and Egypt Healthcare 3D Printing Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
3D Printer Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Global 3D Printing in Medical Applications Market