
 Global 4D Printing in Healthcare Market | 2026-2036
Global 4D Printing in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global 4D Printing in Healthcare Market Foresight
Shape memory alloys are decoupling from static implant economics as programmable morphing enables post-deployment adaptation inside vascular networks. Stratasys Ltd leverages multi-material deposition platforms to dominate hardware supply for research institutions. Materialise NV anchors software-to-print workflows through FDA-validated medical segmentation tools. 3D Systems sustains leadership in biocompatible photopolymer systems for dental and cranial reconstructions.
4D printing in healthcare refers to additive manufacturing of stimuli-responsive constructs that autonomously transform shape, property, or function after fabrication, typically triggered by heat, moisture, magnetic fields, or enzymatic activity with resolution thresholds below 50 microns for vascular compatibility. The primary purpose is to produce patient-specific implants, drug-release matrices, and engineered tissue scaffolds that evolve within physiological environments. Smart polymers and responsive hydrogels command current volume leadership due to established biocompatibility datasets and simpler regulatory characterization pathways. Tissue engineering and regenerative medicine applications represent the fastest-expanding demand pools, driven by unmet needs in organ replacement and cartilage repair where static 3D constructs fail to match biological remodeling rates.
FDA's 510(k) and De Novo pathways govern U.S. market entry for morphing implants, while EMA's Medical Device Regulation (MDR) imposes clinical evidence requirements for shape-changing constructs in Europe. Japan's PMDA accelerates conditional approvals for regenerative medicine products under the Act on Securing Quality, Efficacy and Safety of Products Including Pharmaceuticals and Medical Devices. Stakeholders must monitor how FDA draft guidance on patient-matched devices treats time-dependent geometric changes as design outputs or post-market performance variables.
Market Dynamics
Programmable morphing capabilities are decoupling implant economics from static manufacturing paradigms, forcing stakeholders to rebuild value capture around post-deployment adaptation rather than one-time device sales.
Growth Catalysts
- FDA 510(k) Streamlining:Responsive hydrogel implants now navigate abbreviated review pathways, compressing time-to-market for stimuli-responsive constructs and accelerating clinical translation.
- Japan PMDA Conditional Approvals:The Act on Securing Quality, Efficacy and Safety enables accelerated regenerative medicine product entry, pulling tissue engineering applications through regulatory gates faster than static alternatives.
- Shape Memory Alloy Integration:Programmable morphing in vascular stents enables post-deployment geometric adaptation, unlocking procedural outcomes impossible with conventional nitinol.
Market Restraints
- Smart Polymer Input Volatility:N-isopropylacrylamide and other thermoresponsive monomers face supply concentration among specialty chemical producers, exposing margins to feedstock price swings.
- EMA MDR Clinical Evidence Burden:Shape-changing constructs require extensive mechanical characterization across physiological trigger ranges, extending validation timelines and freezing smaller developers from European market entry.
- Static 3D Printing Substitution:Established titanium and PEEK implants with decades of safety data continue capturing orthopedic volume, particularly where morphing offers marginal clinical benefit.
Strategic Opportunities
- Germany Surgical Center Penetration:Tissue engineering applications remain underdeployed in German university hospital networks, creating first-mover advantage for responsive scaffold providers targeting cartilage repair protocols.
- India CDSCO Regenerative Medicine Pathway:The country's national pharmaceutical regulator is building accelerated approval frameworks for autologous tissue constructs, opening conditional market entry before full harmonization with ICH standards.
- Magnetic-Enzymatic Convergence:Dual-trigger systems combining remote field actuation with localized enzymatic response enable spatiotemporally precise drug release, differentiating next-generation matrices from single-stimulus predecessors.
Industry Challenges
- Biomaterials Process Engineering Talent Gap:Cross-disciplinary expertise spanning polymer chemistry, additive manufacturing, and vascular biology remains scarce, constraining scale-up from prototype to GMP production.
- ISO 13485 Certification Timeline Compression:Responsive device quality management systems must accommodate time-dependent design outputs, forcing auditors to develop novel inspection protocols that extend certification cycles.
- Legacy PACS Integration Friction:Morphing implants require dynamic imaging workflows incompatible with static surgical planning software, demanding costly hospital IT infrastructure overhauls.
Report Scope
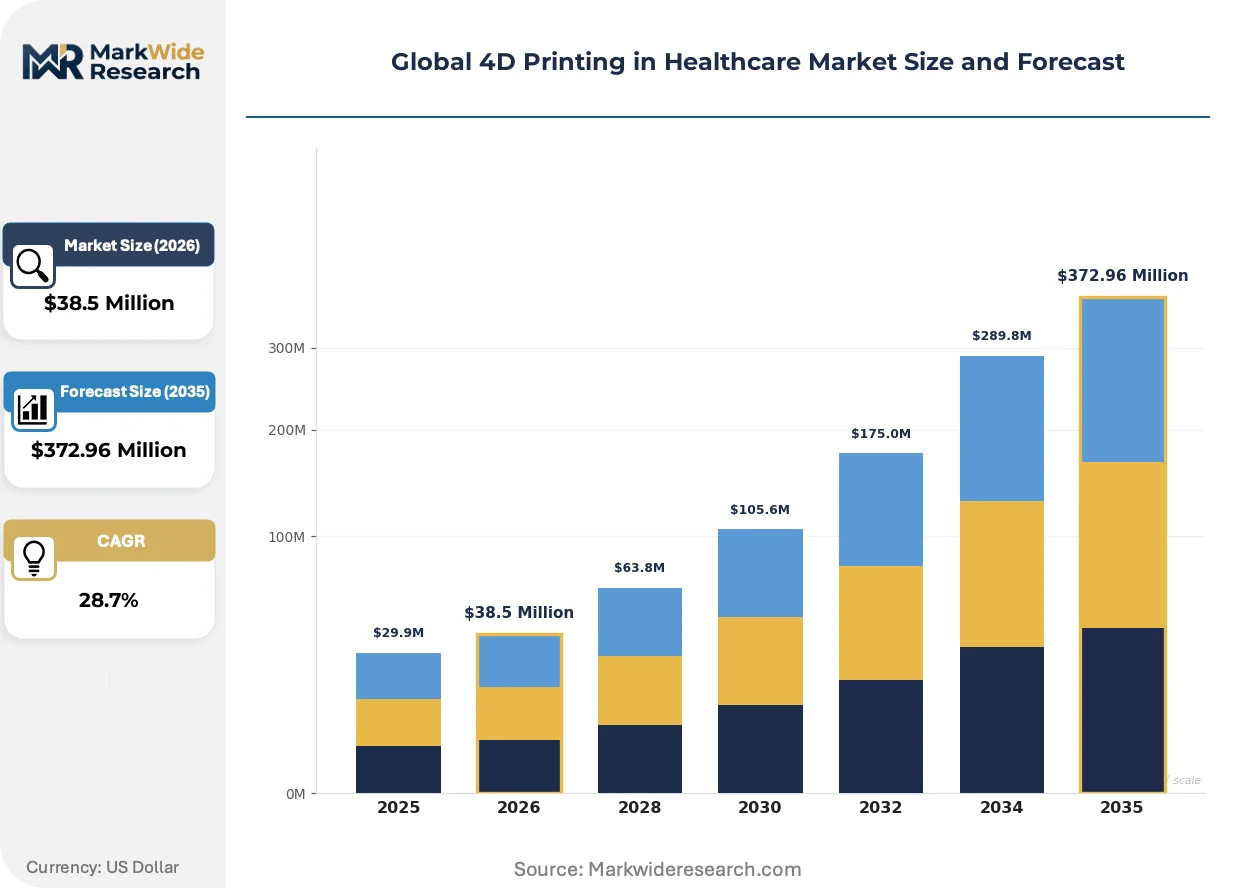
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 4D Printing in Healthcare Market |
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $372.96 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
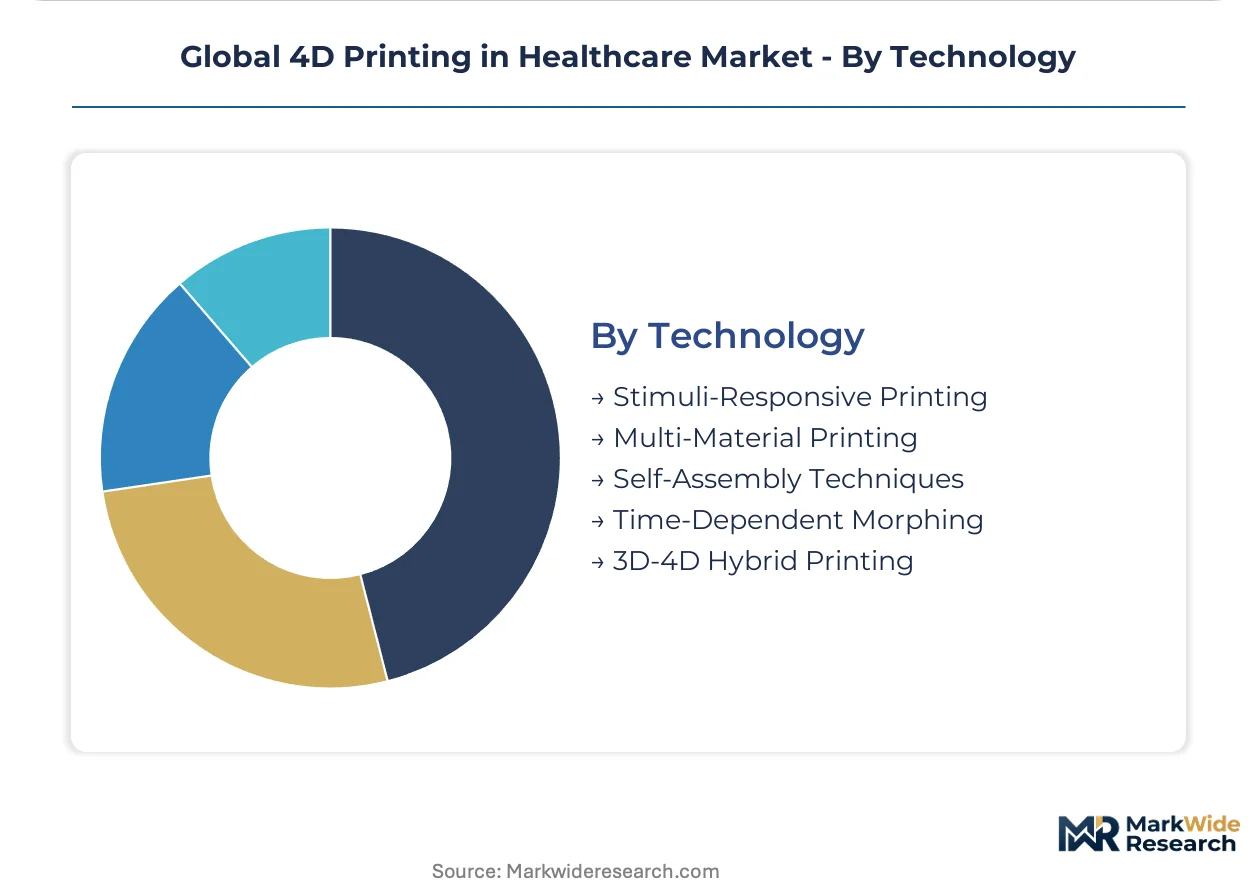
| Segmentation | Product Type: Smart Polymers, Bioinks, Shape Memory Alloys, Responsive Hydrogels, Composite Materials Application: Tissue Engineering, Drug Delivery Systems, Bioelectronics, Regenerative Medicine, Medical Implants End User: Research Institutions, Biotech Companies, Surgical Centers, Pharmaceutical Firms, Medical Device Manufacturers Technology: Stimuli-Responsive Printing, Multi-Material Printing, Self-Assembly Techniques, Time-Dependent Morphing, 3D-4D Hybrid Printing |
| Companies Covered | Stratasys Ltd, 3D Systems, Materialise NV, Organovo Holdings Inc, EnvisionTEC, HP Inc, Dassault Systèmes, Cellink, Poietis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 4D Printing in Healthcare Market Shifts & Advancements
Active material systems are rewriting competitive boundaries between hardware suppliers, software platforms, and clinical endpoints. Three developments are compressing traditional value chains.
Magnetic-responsive hydrogels are expanding into interventional cardiology workflows. These iron oxide-loaded matrices enable remote shape manipulation via external field application, allowing catheter-based deployment of complex geometries impossible through minimally invasive access. Boston Scientific and Abbott vascular divisions are piloting stent prototypes with post-implant diameter modulation, compressing the need for secondary intervention procedures.
Japan's PMDA revised its regenerative medicine product guidance in 2024 to explicitly address 4D constructs, creating conditional approval pathways for scaffolds with demonstrated shape-memory performance in animal models. The industrial consequence is a geographic arbitrage opportunity where Japanese clinical data packages accelerate subsequent FDA De Novo submissions. European developers are responding by establishing Yokohama-based preclinical facilities to capture this regulatory sequencing advantage.
Surgical procurement committees now require evidence of post-implant adaptation protocols before adding responsive constructs to formularies. This buyer-driven certification preference is displacing traditional device-tender processes with outcome-guarantee frameworks. The shift is most visible in German university hospital networks, where cartilage repair contracts now specify remodeling-rate milestones rather than static mechanical properties.
Global 4D Printing in Healthcare Market Segmentation
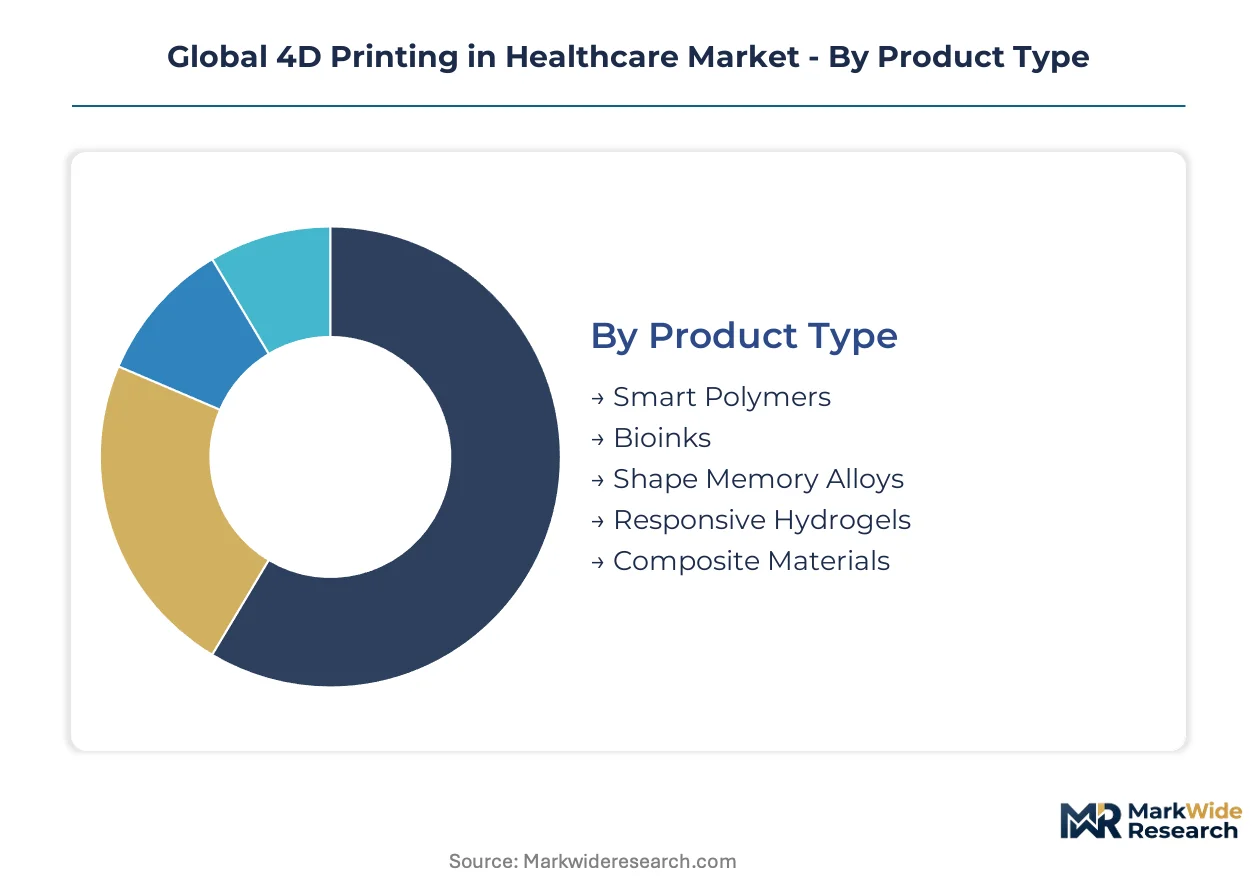
4D printing in healthcare demands granular segmentation because material responsiveness, application environment, and end-user capabilities determine regulatory pathways and reimbursement eligibility. Each dimension carries distinct technical specifications and commercial constraints that reshape procurement patterns across surgical centers and research institutions.
Product Type:
Customization intensity varies sharply across this category, with patient-matched implants requiring bespoke material formulations while standardized research consumables permit bulk production economies.
- Smart Polymers:Thermoresponsive and pH-sensitive polymer networks enable reversible shape transitions triggered by physiological conditions. Demand concentrates in German university hospital networks pursuing cartilage repair protocols where temperature-triggered expansion matches native tissue remodeling rates.
- Responsive Hydrogels:Cross-linked hydrophilic matrices with embedded stimulus-responsive moieties dominate current clinical translation due to established biocompatibility datasets. Japanese surgical centers are piloting these for post-deployment drug release in vascular applications, leveraging PMDA's conditional approval pathways for regenerative medicine products.
- Shape Memory Alloys:Nickel-titanium and copper-based systems enable programmable geometric recovery under thermal or magnetic fields.
- Bioinks:Cell-laden printable formulations combine structural polymers with living biological components.
- Composite Materials:Hybrid constructs integrating polymer matrices with ceramic or metallic reinforcements.
Most installed capacity flows through Responsive Hydrogels. Expansion is steepest in Shape Memory Alloys.
Application:
Cost tier separation distinguishes high-acuity surgical interventions from exploratory research applications, with reimbursement codes favoring implantable constructs over experimental tissue models.
- Tissue Engineering:Scaffold-based regeneration of bone, cartilage, and organ structures using patient-specific geometries that evolve within physiological environments. United States surgical centers are scaling these applications fastest, driven by FDA 510(k) streamlining for responsive constructs and unmet demand in organ replacement where static 3D alternatives fail.
- Drug Delivery Systems:Programmable matrices enabling spatiotemporally controlled therapeutic release through enzymatic, thermal, or magnetic triggers. German pharmaceutical firms are integrating these into combination product pipelines, exploiting EMA MDR pathways for device-drug hybrids.
- Medical Implants:Stents, valves, and orthopedic fixtures with post-deployment adaptation capabilities.
- Regenerative Medicine:Autologous tissue constructs for wound healing and functional restoration.
- Bioelectronics:Conductive responsive materials interfacing neural or cardiac tissue.
Volume leadership sits with Medical Implants. Tissue Engineering is gaining share fastest.
End User:
Customer sophistication determines procurement specifications, with research institutions tolerating experimental material variability while surgical centers demand validated quality management systems.
- Research Institutions:Academic medical centers and university laboratories driving preclinical validation of novel responsive materials. United States NIH-funded facilities account for dominant hardware demand, purchasing multi-material deposition platforms from established suppliers to support investigator-initiated studies.
- Surgical Centers:Hospital networks and specialty clinics adopting FDA-cleared responsive implants for clinical deployment. Japanese university hospitals are expanding fastest under PMDA's accelerated regenerative medicine frameworks.
- Biotech Companies:Venture-backed developers translating academic prototypes to scalable therapeutic products.
- Medical Device Manufacturers:Established orthopedic and cardiovascular firms integrating 4D capabilities into existing product portfolios.
- Pharmaceutical Firms:Drug developers pursuing combination products with programmable release kinetics.
Research Institutions anchor current procurement volume. Surgical Centers are climbing the fastest.
Technology:
Maturity gradients separate commercially validated printing modalities from experimental fabrication approaches still requiring GMP translation.
- Stimuli-Responsive Printing:Direct deposition of materials engineered for post-fabrication transformation through heat, moisture, magnetic fields, or enzymatic activity. German industrial research clusters are advancing these platforms fastest, integrating ISO 13485-compliant quality systems for medical device production.
- Multi-Material Printing:Simultaneous or sequential deposition of disparate material classes enabling functional gradients within single constructs. United States research institutions dominate hardware installation for this modality.
- 3D-4D Hybrid Printing:Workflows combining static structural elements with responsive components in unified fabrication sequences.
- Self-Assembly Techniques:Programmable components that autonomously organize into target geometries through molecular or macroscopic driving forces.
- Time-Dependent Morphing:Systems with precisely sequenced shape evolution over defined temporal windows.
Multi-Material Printing commands the largest installed base. Stimuli-Responsive Printing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yokohama's preclinical research corridor anchors the geographic distribution of 4D printing validation facilities, with regulatory sequencing strategies now determining where developers locate clinical operations. Material suppliers and contract manufacturers cluster near major surgical centers to compress logistics timelines for patient-matched constructs.
United States
FDA's 510(k) streamlining for responsive hydrogel implants pulls tissue engineering applications through regulatory gates faster than European alternatives. The NIH-funded research hospital network concentrates hardware procurement in the Boston-Cambridge corridor, where multi-material deposition platforms support investigator-initiated studies. Greater Boston's medical device cluster hosts the dominant share of preclinical validation contracts for morphing vascular constructs.
Germany
EMA's MDR imposes extensive mechanical characterization requirements for shape-changing constructs, freezing smaller developers from European market entry. Bavaria's university hospital networks specify remodeling-rate milestones rather than static mechanical properties in cartilage repair procurement contracts. The Eindhoven-Heidelberg industrial corridor advances ISO 13485-compliant quality systems for stimuli-responsive printing platforms.
Japan
PMDA's 2024 regenerative medicine guidance revision creates conditional approval pathways for scaffolds with demonstrated shape-memory performance. Tokyo's university hospitals expand fastest under accelerated frameworks, pulling clinical translation ahead of static 3D alternatives. The Yokohama-Kawasaki medical technology cluster hosts European developers establishing preclinical facilities to capture regulatory sequencing advantages.
India
CDSCO is building accelerated approval frameworks for autologous tissue constructs, opening conditional market entry before full ICH harmonization. Maharashtra's pharmaceutical manufacturing belt attracts contract developers seeking to bypass European clinical evidence burdens. The Hyderabad-Bangalore corridor concentrates biotech venture formation around regenerative medicine product pipelines.
United Kingdom
MHRA's post-Brexit device regulations maintain alignment with EMA MDR clinical evidence standards for responsive implants. London's academic medical centers pilot magnetic-responsive hydrogel workflows for interventional cardiology applications. The Oxford-Cambridge arc anchors software-to-print development for FDA-validated medical segmentation tools.
Global 4D Printing in Healthcare Market Competitive Landscape
Global majors compete with regional champions across hardware supply and software-to-print workflows, with consolidation pressure mounting where GMP translation capabilities determine contract awards. The vendor base separates into three tiers: multi-material platform suppliers, medical segmentation software providers, and biocompatible photopolymer specialists. Strategic moves concentrate on regulatory pre-validation partnerships and backward integration into smart polymer feedstock production.
Among hardware-centric suppliers, Stratasys Ltd and 3D Systems occupy positions at the scale-driven end of multi-material deposition, with the former representing the research institution procurement anchor and the latter exemplifying the dental-cranial reconstruction specialization tier. Materialise NV sits within the software-to-print workflow segment, anchoring FDA-validated medical segmentation capabilities that compress preclinical validation timelines. These three entities collectively illustrate how competitive positioning now depends on regulatory sequencing advantages rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Stratasys Ltd |
| 3D Systems |
| Materialise NV |
| Organovo Holdings Inc |
| EnvisionTEC |
| HP Inc |
| Dassault Systèmes |
| Cellink |
| Poietis |
| Others |
Supply & Pricing Matrix
German university hospital procurement committees mandating remodeling-rate milestones in cartilage repair contracts force responsive scaffold suppliers to absorb validation costs upfront, compressing margins for unproven developers while rewarding established ISO 13485-certified manufacturers with pricing power.
Pricing Analysis
Input-cost pass-through from N-isopropylacrylamide and thermoresponsive monomer feedstock volatility anchors contract-based long-term offtake agreements between specialty chemical producers and 4D printing material suppliers. Price differentiation separates FDA-validated responsive hydrogel tiers from experimental formulations lacking biocompatibility datasets, with surgical centers in Japan and the United States showing lowest price sensitivity due to reimbursement coverage for regenerative medicine products. Pricing pressure stems from static titanium and PEEK implant substitution in orthopedic applications where morphing offers marginal clinical benefit. Research institutions in the NIH-funded corridor exhibit highest price sensitivity, driving hardware suppliers toward volume discount structures for multi-material deposition platforms.
Supply Chain Analysis
Direct-to-surgical-center channels handle patient-matched construct demand in the United States, Germany, and Japan, while distributor-mediated flows serve research institutions requiring technical support integration. Smart polymer feedstock production concentrates in Germany, the United States, and Japan, with responsive hydrogel precursor synthesis anchored in specialty chemical clusters near Basel and Ludwigshafen. Raw material dependencies include nickel-titanium shape memory alloys, iron oxide nanoparticles for magnetic responsiveness, and photocurable acrylate resins. Single-source vulnerability in thermoresponsive monomer supply exposes margins to feedstock price swings. Distribution runs through GMP-certified contract manufacturers co-located with major university hospital networks to compress logistics timelines for autologous tissue constructs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global 4D Printing in Healthcare Market functions as a stable compounder, with regulatory sequencing advantages for responsive constructs creating durable competitive moats that compound over multi-year clinical translation cycles.
For Market Incumbents: Deepen backward integration into smart polymer feedstock production to defend against specialty chemical supplier concentration and N-isopropylacrylamide price volatility. Anchor capacity expansion in Yokohama and Boston-Cambridge corridors to capture PMDA conditional approval and FDA 510(k) streamlining synergies. Fortify ISO 13485 certification protocols for time-dependent design outputs before EMA MDR clinical evidence requirements harden further. For New Entrants and Emerging Players: Capture underdeployed tissue engineering applications in German university hospital networks by targeting cartilage repair protocols with remodeling-rate guarantees rather than static mechanical property claims. Exploit CDSCO's emerging regenerative medicine pathway in India to establish conditional market entry before full ICH harmonization. Lead with magnetic-enzymatic dual-trigger systems that differentiate from single-stimulus predecessors in interventional cardiology workflows. For Investors and Strategic Acquirers: Asymmetric upside sits with biocompatible photopolymer specialists possessing FDA-validated segmentation tools and GMP translation capabilities. Long-term viability over the analysis window hinges on regulatory pre-validation partnerships that compress time-to-market for morphing implants. Monitor FDA draft guidance on patient-matched devices as the critical inflection signal for how time-dependent geometric changes will be treated in quality management systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Streamlining Exploitation | Abbreviated review pathways for responsive hydrogel implants accelerate clinical translation timelines relative to European alternatives. |
| PMDA Conditional Approval Sequencing | Japanese clinical data packages enable subsequent De Novo submissions, creating geographic arbitrage for European developers. |
| Backward Integration into Smart Polymers | Captive supply of thermoresponsive monomers insulates margins from specialty chemical producer concentration. |
| Hospital System Partnership Development | Direct procurement relationships with German university hospitals secure remodeling-rate milestone contracts. |
| Software Companion Development | Dynamic imaging workflows compatible with morphing implants overcome legacy PACS integration friction. |
Research Methodology
Bottom-up surgical center procurement modeling reconciled against top-down multi-material platform installation tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs leads at responsive construct developers were combined with secondary validation against FDA 510(k) filings, PMDA submission databases, EMA MDR guidance documents, and hospital procurement records. Triangulation between demand-side adoption signals and supply-side capacity announcements ensures cross-verified volume estimates.
Input-output matrix framing maps stimuli-responsive material formulations through application endpoints to derive segment-level revenue allocations across the projection horizon. Segmentation dimensions modeled include product type, application environment, end-user sophistication, and technology maturity, with regulatory pathway status as an industry-specific overlay. CAGRs were derived from fitted adoption curves calibrated to historical 3D printing medical device penetration patterns and adjusted for 4D-specific clinical evidence requirements. Forecast inputs incorporate PMDA conditional approval velocity and EMA MDR mechanical characterization burden trajectories.
Underlying measurement precision varies by segment; FDA-cleared responsive hydrogels carry tighter precision than experimental shape memory alloy constructs still navigating preclinical validation. Forecasts reflect documented assumptions regarding regulatory sequencing timelines and reimbursement code expansion for morphing implants. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
Global 3D Pens Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
3D Printer Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market