
 Additive Manufacturing Platform Market | 2026-2036
Additive Manufacturing Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Additive Manufacturing Platform Market Analytics
Software-defined workflow orchestration is tilting production economics toward platforms that integrate design, simulation, and printer control in unified environments. EOS GmbH leverages its open-architecture strategy to sustain metal powder-bed leadership across European aerospace supply chains. HP Inc. anchors polymer production scale through its Multi Jet Fusion installed base, while GE Additive competes in aviation-qualified superalloy components with in-house qualification pathways.
An additive manufacturing platform comprises the integrated hardware, software, and material systems that execute layer-by-layer fabrication from digital models, typically operating within build envelopes of 100–1000 mm and achieving tolerances of ±0.1–0.3 mm depending on process modality. These systems serve industrial and commercial purposes by collapsing lead times for complex geometries that subtractive methods cannot economically produce. Metal additive manufacturing dominates aerospace and medical margin pools due to qualification costs and material value density, while polymer additive manufacturing occupies higher-volume automotive and consumer segments where throughput economics govern adoption. Prototyping remains the largest application category by installed base, though tooling and direct manufacturing are expanding as platform reliability matures.
The FDA governs platform validation for patient-specific medical devices through its 510(k) and De Novo pathways, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for implantable printed products. ASTM International and ISO 52900 standards shape material qualification protocols that determine market access for equipment vendors. Stakeholders must monitor evolving certification reciprocity between jurisdictions and the pace at which platform OEMs absorb in-process monitoring into standard product architectures.
Market Dynamics
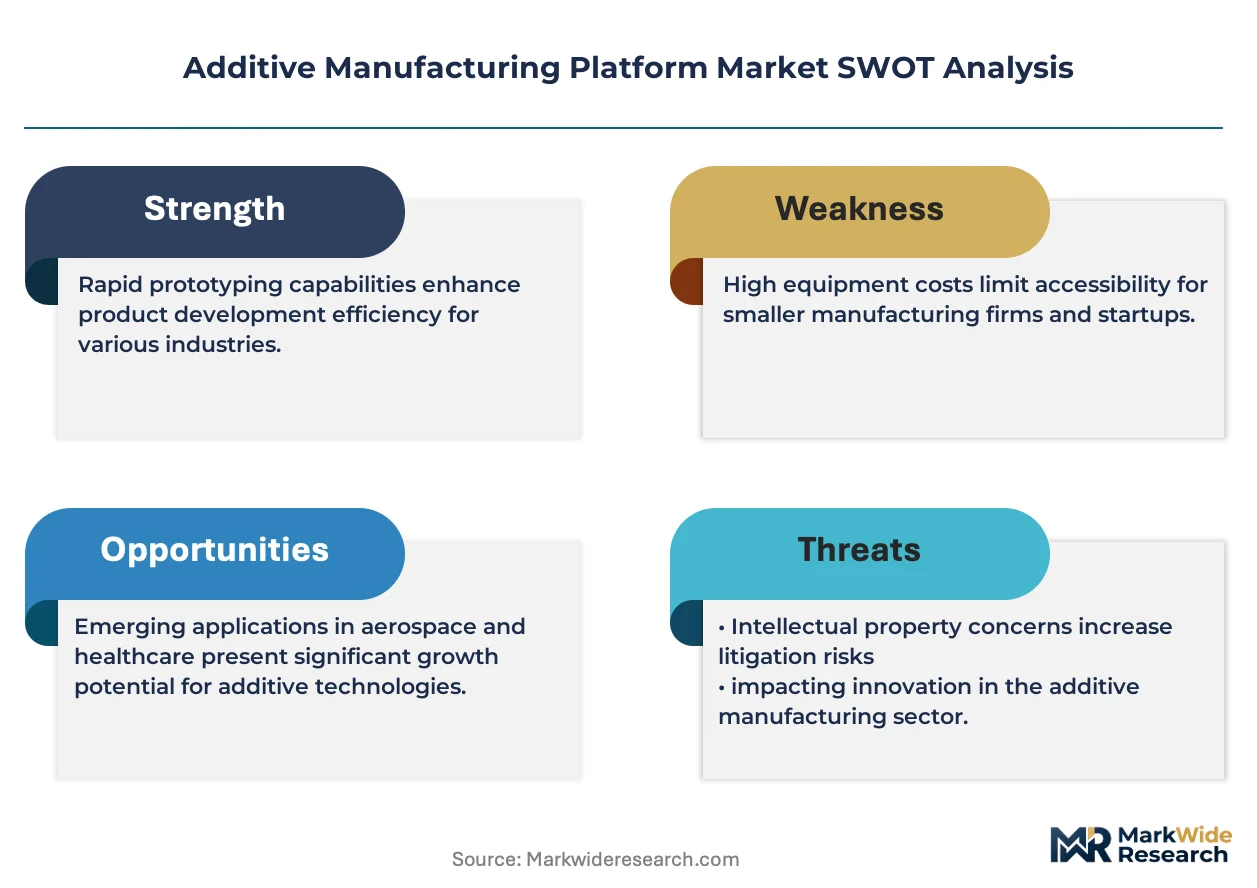
Flight-certification pathways for printed titanium and nickel superalloy components are compressing supplier qualification timelines, forcing platform vendors to embed in-process monitoring and traceability as standard architecture rather than aftermarket modules.
Growth Catalysts
- Aerospace qualification momentum:FAA and EASA are streamlining certification frameworks for flight-critical printed parts, enabling tier-one suppliers to substitute castings with topology-optimized geometries in landing gear and engine brackets.
- EU MDR implant pathway:The Medical Device Regulation's clinical evidence requirements for patient-specific implants are creating captive demand for platforms with integrated quality management systems and batch-level traceability.
- German research clustering:Government-backed Fraunhofer institutes and regional innovation clusters in Bavaria and Baden-Württemberg are accelerating powder-bed fusion process development for precision engineering applications.
Market Restraints
- Metal powder supply concentration:Spherical titanium and nickel alloy powder production concentrates among a handful of European and North American gas atomization facilities, exposing buyers to input cost volatility and allocation risk.
- Post-processing bottleneck:Hot isostatic pressing, CNC finishing, and surface treatment steps add 40-60% to total production cost, eroding the economic case against subtractive alternatives for simple geometries.
- Substitution by hybrid manufacturing:Directed energy deposition and CNC-hybrid systems are capturing repair and large-format applications where powder-bed fusion faces build envelope constraints.
Strategic Opportunities
- India industrialization:The PLI scheme for advanced manufacturing and CDSCO's evolving medical device framework are creating first-mover advantages for platform vendors establishing local technical centers in Pune and Bengaluru.
- Digital inventory models:Spare parts on-demand contracts with rail and energy operators are displacing physical warehousing, rewarding platforms with distributed print networks and secure file management.
- AI-driven process control:Machine learning layer monitoring is converging with physics-based simulation to reduce scrap rates and enable real-time parameter adjustment without human intervention.
Industry Challenges
- Certification timeline compression:Aerospace and medical OEMs are demanding qualified production systems in 12-18 month windows, straining platform vendors' engineering and field service capacity.
- Multi-material workflow integration:Operators struggle to manage powder changeover, contamination control, and parameter libraries when alternating between aluminum, titanium, and tool steel within single facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Additive Manufacturing Platform Market |
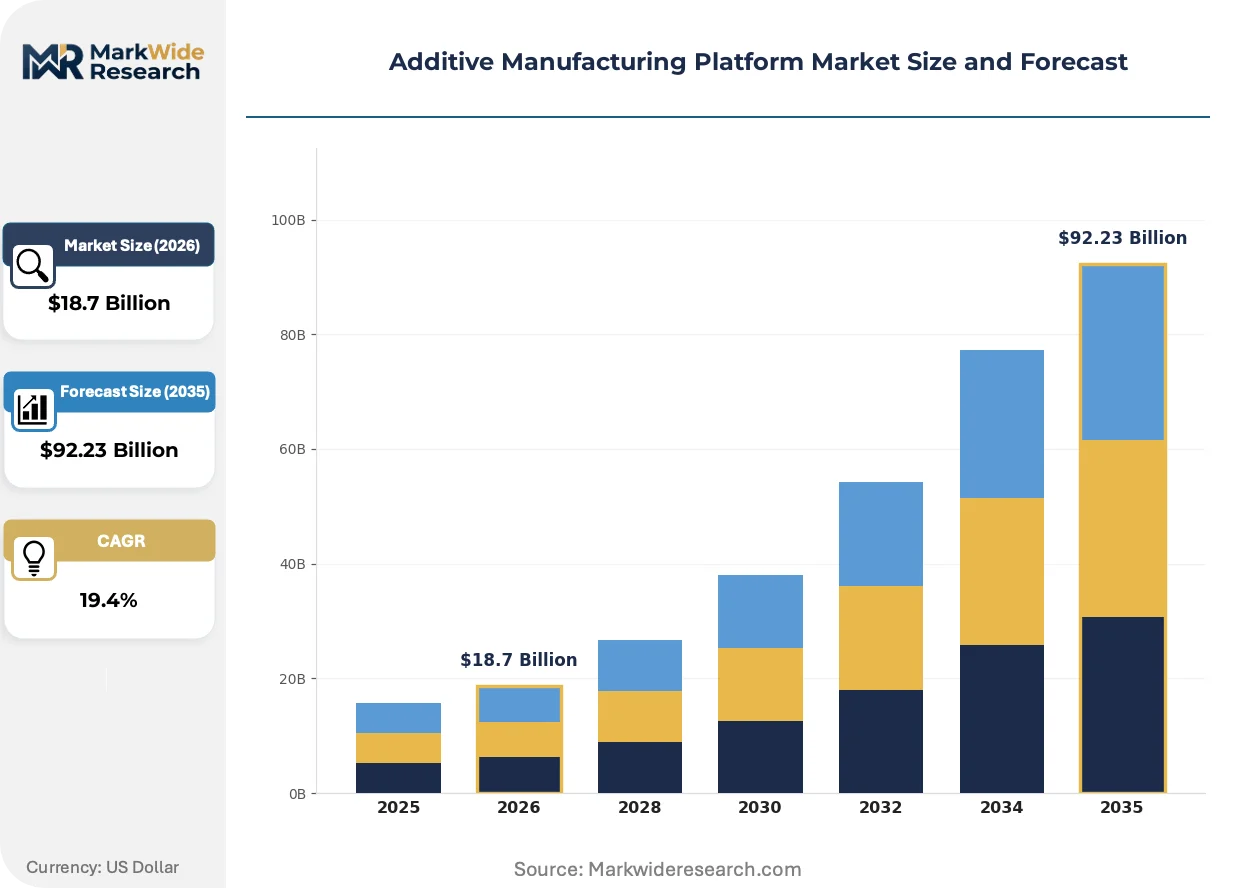
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printing, Stereolithography, Fused Deposition Modeling, Selective Laser Sintering End User: Aerospace, Automotive, Healthcare, Consumer Products Technology: Metal Additive Manufacturing, Polymer Additive Manufacturing, Hybrid Manufacturing, Bioprinting Application: Prototyping, Tooling, Manufacturing, Art & Design |
| Companies Covered | Stratasys, 3D Systems, EOS GmbH, HP Inc., GE Additive, Formlabs, Materialise, DMG Mori, Desktop Metal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additive Manufacturing Platform Market Evolving Landscape
Digital thread architectures are collapsing the traditional boundaries between design, build preparation, and production execution, enabling closed-loop systems that self-correct during fabrication.
Cloud-native build preparation software is virtualizing simulation and support generation workflows, allowing aerospace engineers in Toulouse and Hamburg to iterate lattice structures without local compute infrastructure. Tier-one suppliers are adopting these platforms to compress design-to-first-article timelines from months to weeks. The shift is virtualizing hardware-specific expertise into portable, vendor-agnostic toolchains that reduce switching costs between printer OEMs.
The EU AI Act's risk classification framework is imposing documentation and human oversight requirements on machine learning systems used for defect detection in medical implant production. Platform vendors must now maintain algorithmic audit trails and performance validation datasets to support notified body reviews. German and French medical device manufacturers are responding by segregating AI-enabled inspection lines from legacy equipment to isolate compliance scope.
Spare parts procurement for aging industrial equipment is migrating from forecast-driven stocking to digital warehouse models where OEMs license geometry files rather than shipping physical components. Rail operators in Germany and power utilities in the US are piloting these arrangements for obsolete turbine blades and brake housings. The transition rewards platform vendors with distributed service networks and cybersecurity-hardened file vaults over centralized manufacturing scale.
Additive Manufacturing Platform Market Segmentation
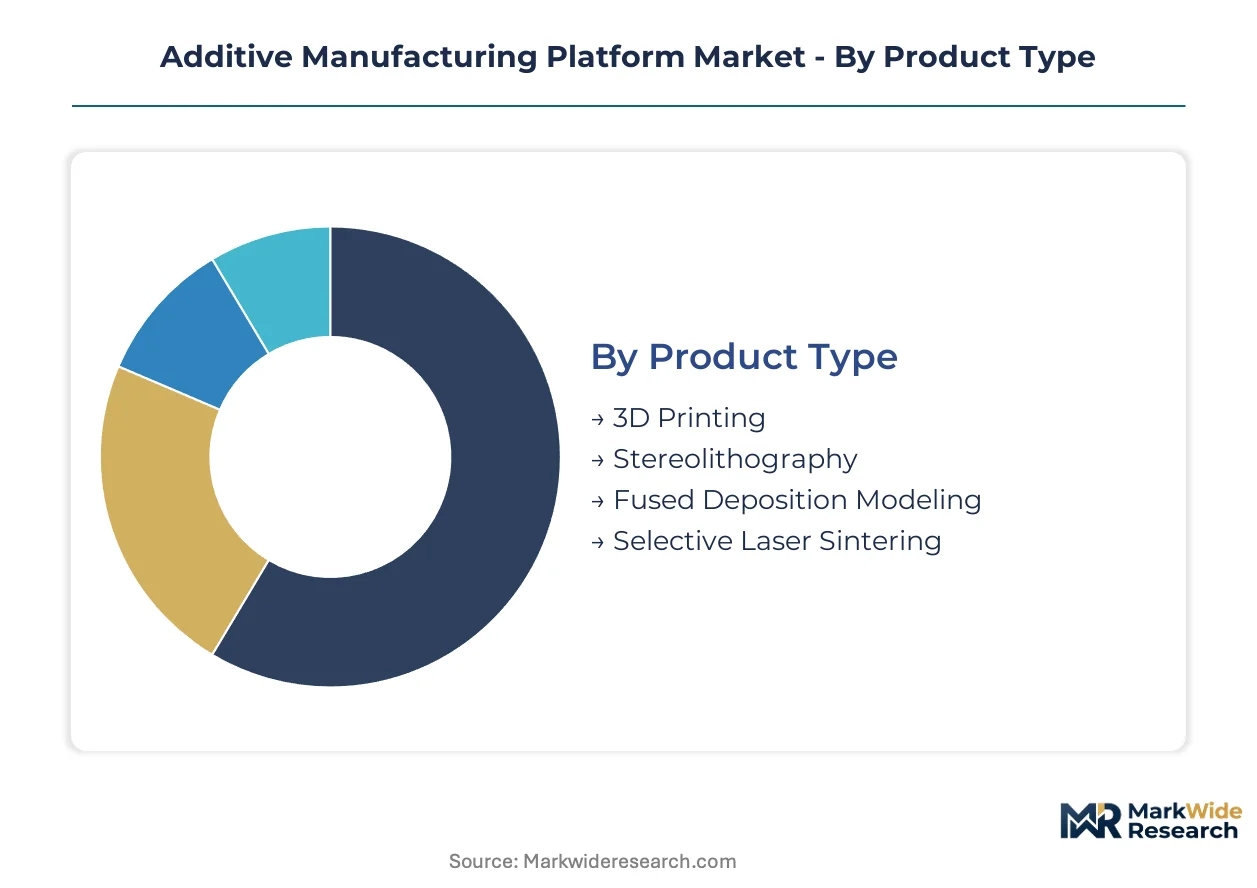
Platform configuration varies sharply across process modalities, with service contracts and consumable replenishment driving lifetime value equations differently for metal powder-bed versus polymer extrusion systems. Segmentation clarity enables vendors to align R&D pipelines with qualification-heavy aerospace demand or high-throughput automotive volumes.
Product Type:
After-sales intensity escalates from polymer extrusion through laser-based systems, with powder handling and optical component replacement dominating service revenue for metal platforms.
- Selective Laser Sintering:Powder-bed fusion using CO₂ or fiber lasers to fuse polymer or metal particles layer-by-layer, achieving surface finishes of Ra 4–10 μm. Demand concentrates in German aerospace supply chains and medical device clusters in Bavaria, driven by EU MDR traceability requirements for implantable geometries.
- 3D Printing:Binder jetting and material jetting systems deposit liquid binding agents or photopolymers through piezoelectric printheads, enabling full-color prototypes and sand casting molds. Automotive styling studios in Stuttgart and Turin deploy these platforms for rapid design iteration where surface aesthetics govern procurement decisions.
- Stereolithography:UV laser or DLP projection cures liquid photopolymer resins, delivering the finest feature resolution among commercial platforms. Dental aligner production in the US and hearing aid shell manufacturing in Denmark exploit this precision for patient-matched devices.
- Fused Deposition Modeling:Thermoplastic filament extrusion through heated nozzles constructs parts with anisotropic mechanical properties. Education markets and consumer prototyping absorb volume here, though industrial variants with high-temperature chambers penetrate jigs and fixtures applications.
Selective Laser Sintering holds the largest share; momentum sits with 3D Printing as binder jetting scales for production metal components.
End User:
Qualification burden and batch traceability requirements segment customer economics, with flight-certified aerospace contracts commanding premium platform configurations unavailable to consumer product tiers.
- Aerospace:Tier-one suppliers and engine OEMs deploy electron beam and laser powder-bed systems for titanium aluminide turbine blades and nickel superalloy structural brackets. FAA and EASA certification pathways for flight-critical parts concentrate demand in Connecticut, Ohio, and southwestern Germany where supply chain proximity to prime contractors accelerates qualification timelines.
- Healthcare:Patient-specific implants and surgical guides require platforms with integrated quality management systems and material lot tracking. The EU MDR's clinical evidence mandates and FDA 510(k) pathways for printed devices drive adoption among orthopedic and maxillofacial specialists in Switzerland, the US, and South Korea.
- Automotive:Tooling, jigs, and end-use powertrain components exploit polymer and metal additive manufacturing for complexity-unconstrained geometries. Motorsport applications in the UK and Italy lead adoption, with series production tooling for electric vehicle platforms expanding in China and Germany.
- Consumer Products:Eyewear, footwear, and electronics housings leverage polymer platforms for mass customization and limited-edition releases. Italian luxury goods manufacturers and US athletic brands deploy distributed print networks to compress regional fulfillment cycles.
Healthcare holds the largest share; momentum sits with Aerospace as flight-certification frameworks mature.
Technology:
Material-process coupling determines margin architecture, with metal systems capturing value through powder supply agreements and parameter development services unavailable in polymer commoditization.
- Metal Additive Manufacturing:Laser and electron beam powder-bed fusion, directed energy deposition, and binder jetting sintering process titanium, aluminum, nickel, and cobalt-chrome alloys. Aerospace engine programs and orthopedic implant lines in Germany, the US, and Japan absorb capacity, constrained by spherical powder supply concentration and post-processing bottlenecks.
- Polymer Additive Manufacturing:Powder-bed fusion, material extrusion, and vat photopolymerization process PA12, TPU, ABS, and photopolymer resins. Automotive interior components and consumer goods production in China and Mexico exploit throughput economics where tolerance relaxation permits.
- Hybrid Manufacturing:CNC-integrated directed energy deposition repairs turbine blades and produces near-net forgings exceeding powder-bed envelope limits. Maintenance, repair, and overhaul operators in Singapore and the US Gulf Coast deploy these systems for legacy aviation fleet support.
- Bioprinting:Extrusion, inkjet, and laser-assisted deposition of cell-laden bioinks constructs tissue scaffolds and organ models. Academic medical centers in the Netherlands, Japan, and the US drive equipment demand, with regulatory pathways for implantable tissues remaining under development.
Metal Additive Manufacturing holds the largest share; momentum sits with Hybrid Manufacturing as repair applications expand.
Application:
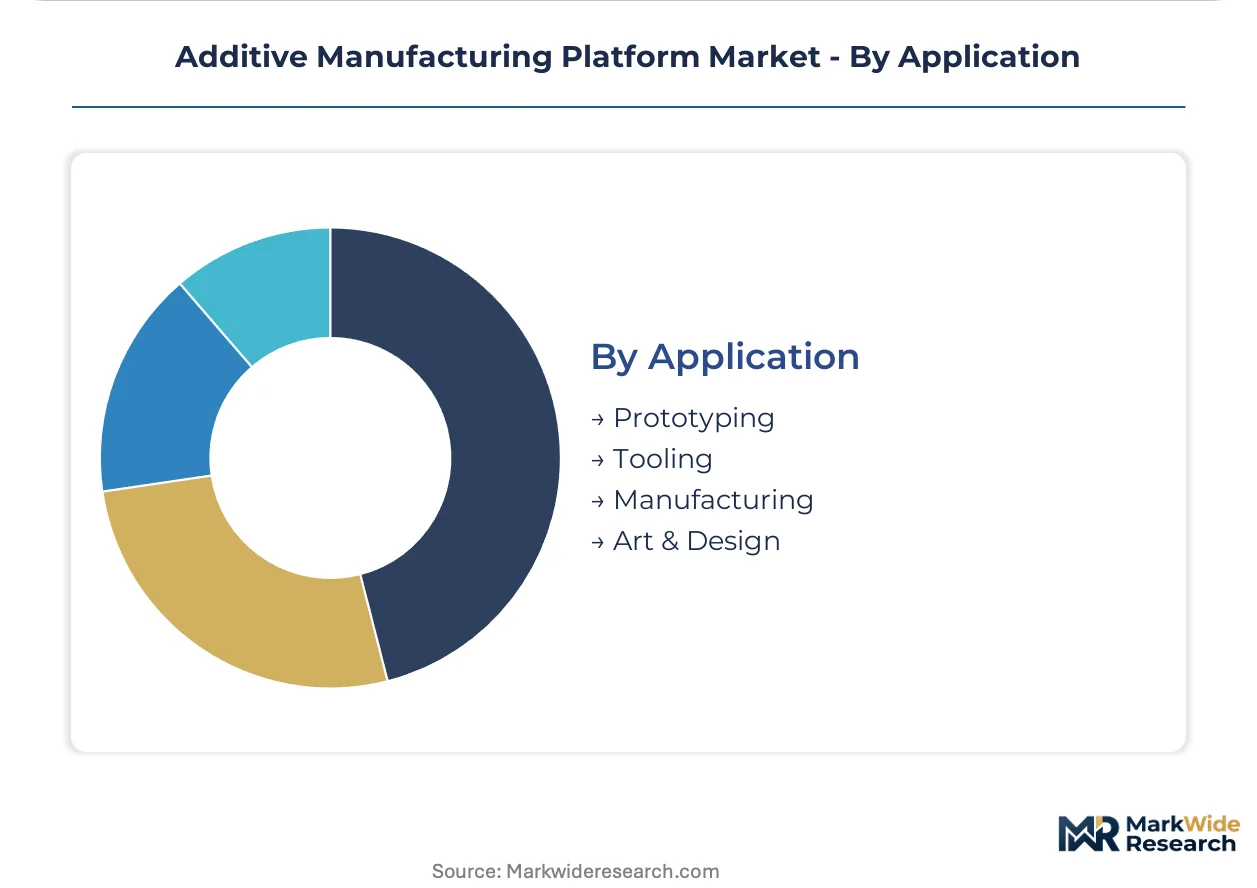
Volume economics invert across the application spectrum, with prototyping amortizing equipment costs through job shop utilization while direct manufacturing requires dedicated lines and captive powder supply.
- Manufacturing:Direct production of end-use components—flight brackets, dental implants, heat exchangers—exploits design freedom unconstrained by tooling. German precision engineering clusters and US aerospace supply chains lead qualification, with batch consistency requirements driving platform OEMs toward closed-loop process control.
- Prototyping:Design validation and form-fit-function iteration across product development cycles consumes the largest installed base of polymer and metal platforms. Engineering services bureaus in the UK, India, and China aggregate demand from fragmented industrial and consumer product developers.
- Tooling:Conformal-cooled injection molds, die casting inserts, and composite layup tools compress cycle times and improve part quality. Automotive and packaging manufacturers in Germany, Italy, and the US deploy metal-printed tooling where cooling channel complexity governs performance.
- Art & Design:Sculptural objects, architectural elements, and jewelry exploit metal and polymer platforms for geometries impossible through casting or carving. Design studios in Milan, London, and New York commission limited editions where digital fabrication authenticates provenance.
Prototyping holds the largest share; momentum sits with Manufacturing as platform reliability matures for production duty cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform procurement concentrates among aerospace primes, medical device OEMs, and precision engineering clusters that demand flight-certified or implant-grade production systems. Buyers prioritize suppliers with established qualification pathways and regional service density.
United States
FAA certification momentum for flight-critical titanium components drives demand among Connecticut and Ohio-based tier-one aerospace suppliers. The FDA's 510(k) and De Novo pathways govern platform validation for patient-specific implants, concentrating adoption among orthopedic manufacturers in Massachusetts and California research corridors.
Germany
EU MDR traceability requirements for implantable devices are tightening quality mandates across Bavarian and Baden-Württemberg medical device clusters. Fraunhofer institutes anchor government-backed powder-bed fusion research, while southwestern supply chains feed Airbus and MTU Aero Engines qualification programs.
China
MIIT industrial upgrading directives and dual carbon goals are accelerating metal additive manufacturing adoption for aerospace and energy applications. Yangtze River Delta precision engineering hubs in Shanghai and Jiangsu province are deploying platforms for conformal-cooled tooling and heat exchanger production.
Japan
METI technology roadmaps prioritize additive manufacturing for aerospace superalloy components and dental restorations. Nagoya-area automotive and aviation suppliers integrate platforms for jigs and repair applications, while Osaka medical device manufacturers pursue PMDA-qualified implant production systems.
India
PLI scheme incentives for advanced manufacturing and CDSCO's evolving medical device framework are creating first-mover opportunities. Pune and Bengaluru technical centers concentrate demand from aerospace MRO operators and orthopedic implant startups seeking localized production capabilities.
Additive Manufacturing Platform Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that fragments by process modality and end-use qualification burden. Metal powder-bed fusion systems command premium positioning due to aerospace and medical certification requirements, while polymer platforms face commoditization pressure in prototyping and consumer segments. Strategic archetypes include integrated platform OEMs with captive materials ecosystems, software-centric workflow orchestrators, and regional service bureaus aggregating distributed demand. Competitive moves center on embedding in-process monitoring as standard architecture and securing powder supply agreements to insulate customers from input volatility.
Within the integrated platform tier, EOS GmbH and GE Additive exemplify archetypes that combine hardware architecture with qualification pathway expertise. HP Inc. occupies a position bridging polymer production scale and industrial workflow integration. Stratasys and 3D Systems represent established vendors with broad modality portfolios spanning prototyping through direct manufacturing applications.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| EOS GmbH |
| HP Inc. |
| GE Additive |
| Formlabs |
| Materialise |
| DMG Mori |
| Desktop Metal |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese powder-bed fusion equipment is compressing utilization rates among second-tier vendors and forcing pricing discipline across European and North American suppliers. This utilization gap simultaneously erodes aftermarket service margins and accelerates consolidation in spherical metal powder supply.
Pricing Analysis
Cost-plus contracts with LME nickel indexation dominate metal platform procurement, locking aerospace buyers into pass-through arrangements for titanium and superalloy feedstock. Price differentiation hinges on FAA/EASA certification tier and bundled field service density, with flight-qualified systems commanding substantial premiums over industrial-grade configurations. Cost compression in polymer extrusion tiers is intensifying because HP Inc. and Chinese vendors are scaling Multi Jet Fusion clones. Job shop operators in prototyping segments exhibit the highest price sensitivity, while orthopedic OEMs accepting EU MDR liability show minimal elasticity.
Supply Chain Analysis
Upstream spherical titanium and nickel alloy powder production draws from gas atomization facilities concentrated in Germany, the United States, and the United Kingdom. Critical dependencies include argon gas supply, plasma spheroidization equipment, and plasma torch consumables sourced from specialized industrial gas distributors. Single-source vulnerability pervades the superalloy powder tier, where Pratt & Whitney and GE Aviation have captive offtake agreements with limited spot market availability. Distribution runs through authorized reseller networks with regional service depots, though direct OEM relationships dominate aerospace and medical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid manufacturing systems and CNC-integrated repair platforms pose a direct substitution threat to pure-play powder-bed fusion vendors, requiring incumbents to defend their installed base through workflow lock-in rather than hardware differentiation alone.
For Market Incumbents: Pre-empt directed energy deposition encroachment by embedding in-process monitoring as standard architecture and securing exclusive powder supply agreements with European gas atomizers. Consolidate field service capacity in southwestern Germany and Connecticut to compress aerospace qualification timelines. Certification investment in FDA 510(k) and EU MDR pathways remains the critical defensive lever against emerging Asian platform vendors.
For New Entrants and Emerging Players: Pursue untapped demand in Indian aerospace MRO and CDSCO-tracked orthopedic implant production, where localized technical centers confer first-mover advantage before PLI scheme maturation. Target conformal-cooled tooling applications in Yangtze River Delta automotive clusters as the most penetrable volume segment. A software-centric go-to-market angle—cloud-native build preparation and AI-driven parameter optimization—sidesteps capital-intensive hardware manufacturing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across polymer extrusion and binder jetting sub-segments as Chinese equipment achieves functional parity. Long-term viability favors platform vendors with captive materials ecosystems and qualification pathway expertise rather than pure hardware plays. Acquisition targets should display integrated powder supply agreements and established aerospace OEM relationships. Watch for inflection when FAA publishes streamlined certification guidance for flight-critical printed brackets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spherical Powder Production | Captive gas atomization capacity insulates aerospace customers from LME nickel volatility and allocation risk. |
| Cloud-Native Build Preparation Platform Launch | Virtualized simulation workflows reduce switching costs between printer OEMs for Toulouse and Hamburg engineering teams. |
| EU MDR-Compliant Quality Management System Certification | Batch-level traceability architecture unlocks Bavarian and Baden-Württemberg implant manufacturing contracts. |
| India Technical Center Establishment | Pune and Bengaluru facilities capture PLI scheme incentives and CDSCO framework first-mover positioning. |
| AI-Driven In-Process Monitoring Integration | Machine learning layer inspection reduces scrap rates and enables real-time parameter adjustment without human intervention. |
Research Methodology
A standing panel of powder-bed fusion platform engineers, aerospace tier-one procurement directors, orthopedic device regulatory affairs leads, and Fraunhofer institute research coordinators provided ongoing calibration throughout the study period. Primary interviews with these stakeholders were cross-referenced against secondary validation from FAA certification bulletins, EASA design approval records, FDA 510(k) and De Novo submission databases, and EU MDR notified body guidance documents. Bottom-up equipment shipment data and top-down aerospace and medical device capital expenditure estimates were triangulated to establish market sizing.
Scenario-bracketing framed demand projections across the analysis window, with base, upside, and downside cases reflecting varying assumptions about flight-certification timeline compression and EU MDR enforcement intensity. Segmentation dimensions modeled include process modality, material class, end-use industry, application type, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to historical qualification cycle data and announced OEM platform deployment schedules. Forecast inputs incorporated spherical powder capacity expansion announcements and post-processing automation adoption curves.
Macroeconomic conditions sit as an overlay; deviation in aerospace capital expenditure cycles, medical device reimbursement rates, or industrial metal powder spot pricing would shift the trajectory. Forecasts reflect documented assumptions about certification reciprocity between FAA and EASA and the pace of AI-enabled inspection standardization. Cross-checking against disclosed capital expenditure plans from Airbus, Boeing, and major orthopedic OEMs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
Selective Laser Sintering Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
US Additive Manufacturing Market