
 US Additive Manufacturing Market | 2026-2036
US Additive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
US Additive Manufacturing Market Intelligence
Modular hardware-software bundling is broadening buyer choice across the US Additive Manufacturing Market, as vendors package printers with proprietary design platforms and material subscriptions. GE Additive leverages its aviation heritage to dominate metal powder-bed systems for turbine blades. Stratasys sustains polymer printer leadership through channel control across dental and aerospace service bureaus. Desktop Metal competes on manufacturing scale in binder jetting for automotive production runs.
Additive manufacturing builds three-dimensional objects by depositing material layer-by-layer from digital models, typically operating with layer resolutions between 50 and 200 microns and utilizing feedstocks ranging from photopolymer resins to nickel superalloys, primarily to produce complex geometries unattainable through subtractive methods or to eliminate tooling costs in low-volume production. Metal powder-bed fusion captures the deepest margin pools as aerospace and defense buyers qualify flight-critical titanium and Inconel components. Fused deposition modeling retains volume leadership in prototyping and jigs across automotive supply chains. Healthcare applications in patient-specific surgical guides and orthopedic implants represent the fastest-growing end-user segment as FDA 510(k) clearances accumulate.
The FAA governs airworthiness certification for additively manufactured flight components, while FDA oversees medical device qualification, and OSHA sets workplace exposure limits for metal powders and volatile photopolymers, collectively shaping capital deployment timelines and facility design standards. NIST measurement standards and ASTM International process specifications further define repeatable quality benchmarks that buyers demand before production contracts. Stakeholders must monitor pending FAA rulemaking on powder-bed fusion qualification as this will determine which suppliers secure tier-one aviation supply positions.
Market Dynamics
Flight-critical certification pathways are compressing supplier qualification timelines as FAA rulemaking accelerates powder-bed fusion acceptance for structural aviation components. Defense procurement offices in Ohio, Texas, and California are rewriting sourcing specifications to favor additively manufactured titanium and Inconel parts.
Growth Catalysts
- FAA Airworthiness Pathways:Evolving certification frameworks for powder-bed fusion components are reducing qualification cycles from years to months for tier-one aviation suppliers.
- Ohio Defense Clusters:Concentrated aerospace and defense procurement in the state's manufacturing corridor is anchoring supplier ecosystem formation and talent pipelines.
- Patient-Specific Implants:Accumulating FDA 510(k) clearances for titanium orthopedic devices and surgical guides are unlocking hospital system procurement at scale.
Market Restraints
- Nickel Superalloy Supply Concentration:Dependence on limited domestic powder metallurgy suppliers creates input cost volatility for flight-critical component producers.
- OSHA Metal Powder Exposure Limits:Workplace ventilation and PPE mandates inflate facility capital costs and constrain facility siting options.
- Subtractive Machining Substitution:Five-axis CNC centers retain cost advantages for simple geometries above ten-thousand-unit production runs.
Strategic Opportunities
- Texas Energy Corridor:Oilfield services procurement for downhole drilling components remains underpenetrated by metal additive relative to traditional casting.
- IRA Clean Energy Manufacturing Credits:Domestic production incentives for advanced manufacturing equipment are improving project IRRs for capital-intensive printer deployments.
- AI-Driven Topology Optimization:Convergence of generative design software with powder-bed systems is compressing part-to-print workflows for complex structural lattices.
Industry Challenges
- Non-Destructive Testing Talent Scarcity:Qualified technicians for CT scanning and ultrasonic validation of internal porosity remain concentrated at national laboratories and top-tier aviation suppliers.
- Legacy ERP Integration Friction:Additive job scheduling and traceability systems require custom middleware to connect with SAP and Oracle manufacturing modules deployed across defense primes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Additive Manufacturing Market |
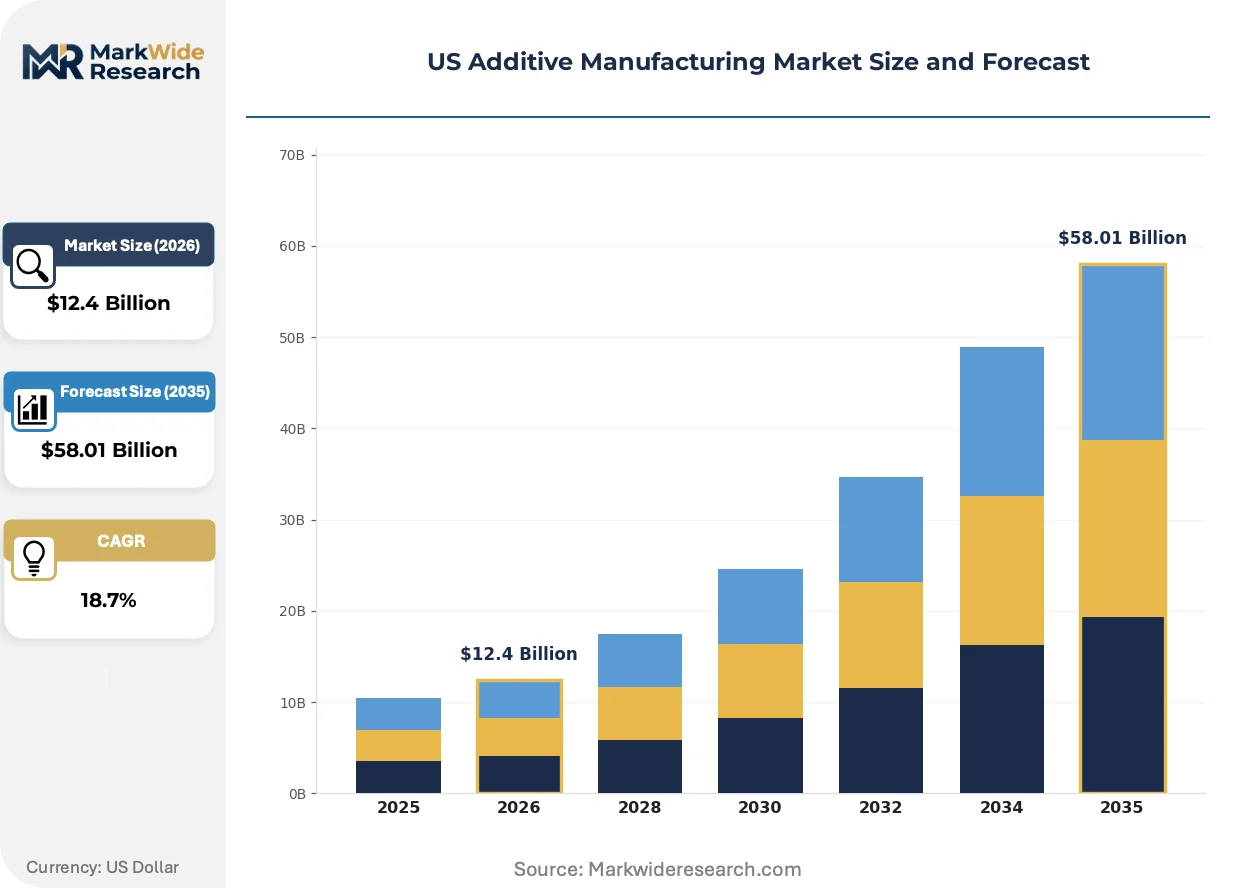
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Metal, Ceramic, Composite Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Aerospace, Automotive, Healthcare, Consumer Goods Application: Prototyping, Manufacturing, Tooling, Customization |
| Companies Covered | 3D Systems, Stratasys, GE Additive, Markforged, Proto Labs, HP Development Company, Materialise, Renishaw, Desktop Metal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Additive Manufacturing Market Strategic Shifts & Innovations
Real-time process monitoring and machine learning feedback loops are displacing post-build inspection as the primary quality assurance mechanism. Vendors are embedding sensor arrays directly into build chambers to capture thermal history and melt pool dynamics.
Multi-laser powder-bed systems are converging with predictive maintenance algorithms to maximize machine utilization in high-throughput production environments. Automotive and aerospace contract manufacturers are adopting these platforms for small-batch structural runs. The technology is converging with digital twin platforms to compress first-article qualification timelines and reduce scrap rates.
FAA rulemaking on powder-bed fusion qualification pathways is creating tiered supplier certification categories based on process control maturity. Flight-critical component producers must demonstrate statistical process control across thermal cycles and atmospheric conditions. Aviation procurement teams in Washington State and South Carolina are prioritizing suppliers holding advanced qualification tiers for next-generation narrowbody programs.
Hospital supply chains are consolidating orthopedic implant sourcing around additive manufacturers offering sterilization-ready packaging and consignment inventory models. Device vendors are displacing traditional distributors with direct-to-hospital logistics networks. This concentration is most visible in Midwestern health systems where group purchasing organizations have consolidated buying power.
US Additive Manufacturing Market Segmentation
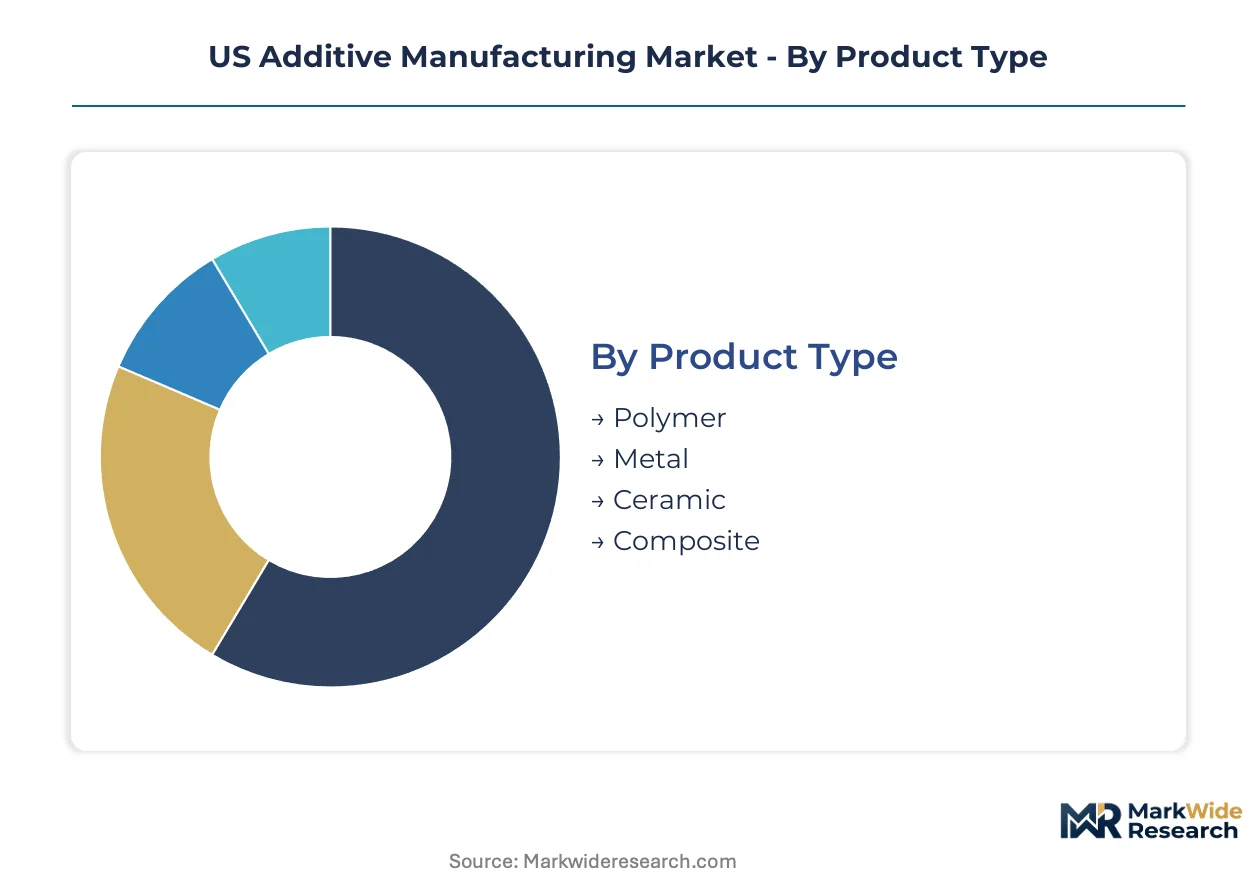
Segmentation in additive manufacturing reveals how material constraints, certification requirements, and production economics partition buyer budgets across distinct technology stacks. Each axis—material, process, end-use, and application—carries unique regulatory and supply chain implications that shape vendor positioning.
Product Type:
Material chemistry determines thermal processing parameters, post-build requirements, and the regulatory pathways available for qualification.
- Metal:Powder-bed fusion of titanium, Inconel, and aluminum alloys dominates flight-critical aerospace procurement. FAA qualification timelines for structural aviation components compress as process control standards mature, anchoring supplier consolidation in Ohio and Texas defense clusters.
- Polymer:Photopolymer resins and thermoplastic filaments retain volume leadership through fused deposition modeling systems deployed across automotive prototyping and dental service bureaus. Material subscriptions bundled with hardware lock in recurring revenue for channel-dominant vendors.
- Ceramic:Oxide and non-oxide ceramics serve high-temperature applications in semiconductor processing equipment and biomedical implants. Limited domestic feedstock suppliers constrain batch-to-batch consistency for production-scale adoption.
- Composite:Continuous fiber-reinforced thermoplastics deliver specific strength advantages for drone airframes and sporting goods. Deposition head technology limitations restrict build speeds relative to unreinforced polymer systems.
Metal leads on scale; composite leads on momentum.
Technology:
Process architecture governs capital intensity, layer resolution, and the geometric complexity achievable without support structures.
- Fused Deposition Modeling:Extrusion-based thermoplastic deposition dominates installed base volumes through low equipment cost and material openness. Automotive supply chains deploy these systems for welding fixtures and assembly jigs where dimensional tolerance requirements remain permissive.
- Selective Laser Sintering:Powder-bed fusion of polymers enables functional prototypes and short-run end-use parts without support removal. Healthcare applications in patient-specific surgical guides accumulate FDA 510(k) clearances that unlock hospital system procurement.
- Stereolithography:UV-cured resin vat polymerization delivers the finest surface finishes for dental aligners and investment casting patterns. Post-cure requirements and resin handling constraints limit adoption in uncontrolled production environments.
- Digital Light Processing:Projector-based photopolymer curing accelerates layer times relative to laser scanning for equivalent build volumes. Jewelry and dental markets favor these systems for small-batch customization with minimal operator intervention.
Fused Deposition Modeling anchors installed capacity; Selective Laser Sintering commands the steepest expansion trajectory in production applications.
End User:
Industry-specific certification regimes and procurement specifications filter which additive technologies achieve production qualification.
- Aerospace:Flight-critical component procurement concentrates among tier-one suppliers holding FAA-recognized process control certifications. Powder-bed fusion of nickel superalloys for turbine hardware anchors the deepest margin pools in the market.
- Healthcare:Patient-specific orthopedic implants and surgical guides accumulate FDA clearances that consolidate sourcing around vendors offering sterilization-ready packaging. Midwestern hospital systems drive demand through group purchasing organization consolidation.
- Automotive:Low-volume production runs and tooling applications favor polymer systems for cost efficiency, while metal binder jetting penetrates powertrain prototyping. OEM qualification timelines lag aerospace but accelerate for non-structural components.
- Consumer Goods:Mass customization of eyewear, footwear, and electronics enclosures leverages photopolymer and polymer powder systems. Direct-to-consumer distribution models compress traditional retail channel margins.
Aerospace dominates value capture; healthcare expands most quickly through regulatory pathway maturation.
Application:
Use case economics determine acceptable unit costs, lead time sensitivity, and the degree of post-processing automation required.
- Prototyping:Form and fit verification drives the largest installed base of polymer systems across automotive and consumer product development cycles. Design iteration velocity outweighs material property optimization in this segment.
- Manufacturing:Production of end-use parts demands statistical process control and traceability systems that integrate with SAP and Oracle manufacturing modules. Flight-critical aviation components and FDA-cleared medical devices anchor qualification investments.
- Tooling:Conformal cooling channels in injection molds and die cast tooling reduce cycle times for high-volume manufacturing. Metal powder-bed systems serve this application where heat transfer optimization justifies premium material costs.
- Customization:Patient-matched implants and bespoke consumer products leverage design automation to compress order-to-delivery timelines. Digital workflow integration distinguishes vendors in this segment from traditional manufacturing alternatives.
Prototyping retains volume leadership; manufacturing commands the premium pricing tier as qualification barriers concentrate supply among certified producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Additive manufacturing scaled from Midwest defense prototyping labs during the 1980s before dispersing across federally funded research corridors and private sector production centers.
Ohio
Defense procurement offices at Wright-Patterson Air Force Base drive titanium and Inconel component demand for next-generation aircraft programs. FAA collaborates with local suppliers to validate powder-bed fusion process controls for structural aviation parts. The Dayton-Cincinnati corridor anchors supplier ecosystems serving tier-one aerospace primes.
Texas
Oilfield services procurement for downhole drilling hardware creates demand for corrosion-resistant metal components in high-pressure environments. OSHA metal powder exposure regulations shape facility ventilation investments across Houston-area production sites. The Permian Basin energy corridor remains underpenetrated by additive manufacturing relative to traditional investment casting suppliers.
California
Space launch vehicle manufacturers qualify printed combustion chambers and turbopump housings for reusable rocket programs. State-level clean energy manufacturing incentives complement IRA federal credits for advanced production equipment deployment. Los Angeles-area defense contractors integrate additive job scheduling with legacy ERP systems for traceability compliance.
Washington
Commercial aviation procurement teams prioritize suppliers holding advanced FAA qualification tiers for narrowbody program contracts. Boeing's Everett and Renton facilities drive specification standards for flight-critical printed components across Pacific Northwest supplier networks. The state's aerospace cluster concentrates non-destructive testing talent for CT scanning validation of internal porosity.
Michigan
Automotive tooling applications leverage conformal cooling channels in injection molds to reduce cycle times for high-volume manufacturing. Ford and General Motors qualify non-structural printed components for production vehicle programs. Detroit-area suppliers bridge additive job scheduling with SAP manufacturing modules deployed across OEM supply chains.
US Additive Manufacturing Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tier and material specialization vectors. Metal powder-bed system vendors capture the deepest margin pools where FAA flight-critical qualifications create supply scarcity. Three archetypes dominate: aviation-heritage industrial conglomerates, polymer-focused channel controllers, and venture-backed scale challengers in binder jetting. Consolidation pressure intensifies through strategic partnerships between hardware OEMs and materials suppliers, while geographic expansion into Midwest defense clusters anchors regional share positions.
Among established additive manufacturing specialists, 3D Systems and Stratasys occupy positions spanning polymer hardware and service bureau networks. GE Additive exemplifies the aviation-heritage archetype through metal powder-bed system deployment for turbine applications. These three entities represent contrasting strategic postures across material specialization, vertical integration depth, and end-market certification breadth.
| Leading Market Players |
|---|
| 3D Systems |
| Stratasys |
| GE Additive |
| Markforged |
| Proto Labs |
| HP Development Company |
| Materialise |
| Renishaw |
| Desktop Metal |
| Others |
Cost & Logistics Intelligence
Multi-laser powder-bed system deployment simultaneously compresses per-part production costs and concentrates supplier bargaining power among certified aviation component producers. FAA qualification tiers create asymmetric pricing power where tier-one holders command premium positioning while uncertified competitors face margin compression from raw material volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates flight-critical aerospace components from industrial tooling and consumer prototyping tiers. Price differentiation centers on FAA certification maturity and metal powder metallurgy grade, with nickel superalloy feedstock commanding the steepest premiums. Cost compression in the standard tier is intensifying because polymer system vendors bundle hardware with material subscriptions to lock recurring revenue. Automotive prototyping teams exhibit the highest price sensitivity, while defense procurement offices absorb premium positioning for qualified titanium components.
Supply Chain Analysis
Regional distribution centers in Ohio, Texas, and Washington State anchor hub-and-spoke patterns for metal powder and finished component logistics. Domestic supply draws from limited domestic powder metallurgy suppliers in Pennsylvania and Ohio, with titanium sponge feedstock sourcing from Japan and Russia. Single-source vulnerability in nickel superalloy powder production creates exposure to input cost spikes. Distribution runs through defense prime vendor-managed inventory systems and hospital GPO consignment models for orthopedic implants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US additive manufacturing rests on powder-bed fusion qualification automation compressing inspection labor costs and tier-one certification scarcity supporting premium pricing persistence.
For Market Incumbents: Extend FAA qualification tier coverage into next-generation narrowbody programs before emerging binder-jetting scale challengers achieve process control parity. Anchor backward integration into domestic titanium powder production to offset nickel superalloy supply concentration. Channel control through dental and aerospace service bureau networks locks out polymer-focused entrants from high-margin recurring revenue streams. For New Entrants and Emerging Players: Capture the Texas Permian Basin oilfield services corridor where downhole drilling component demand remains underpenetrated by metal additive relative to investment casting incumbents. Prioritize corrosion-resistant alloy development for high-pressure environments. A direct-to-operator sales model bypasses traditional distributor markups in this price-sensitive segment. For Investors and Strategic Acquirers: Roll-up economics work for regional service bureau consolidation because FAA certification timelines create localized supply scarcity that regional scale can exploit. Five-to-ten year viability hinges on software-enabled process control differentiation rather than hardware commoditization. Monitor pending FAA rulemaking on powder-bed fusion structural component acceptance as the inflection signal for tier-one supplier valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Qualification Tier Advancement | Unlocks Boeing and Lockheed Martin flight-critical procurement contracts for structural aviation components. |
| Domestic Metal Powder Backward Integration | Reduces exposure to nickel superalloy supply concentration and OSHA import handling compliance costs. |
| AI-Driven Topology Optimization Partnership | Compresses part-to-print workflows for complex lattice structures in aerospace and medical implant applications. |
| Hospital GPO Consignment Model Expansion | Consolidates orthopedic implant sourcing through sterilization-ready packaging and direct-to-hospital logistics networks. |
| Multi-Laser System Predictive Maintenance Platform | Maximizes machine utilization in high-throughput production environments for automotive contract manufacturers. |
Research Approach
Bottom-up aerospace and healthcare procurement modeling reconciled against top-down metal powder and printer shipment tracking forms the analytical core of this study. Primary interviews with FAA certification engineers, defense procurement officers at Wright-Patterson Air Force Base, hospital GPO contracts managers, and additive manufacturing operations directors informed demand-side assumptions. Secondary validation drew from FAA airworthiness directives, FDA 510(k) clearance databases, NIST measurement standard publications, and ASTM International process specification releases.
Historical trendline analysis of powder-bed fusion system deployments and material consumption patterns established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated material chemistry, process architecture, end-user industry certification requirements, and application use case economics. CAGR derivation rested on qualification timeline compression rates, defense procurement specification rewrites, and IRA clean energy manufacturing credit uptake assumptions.
Nickel superalloy supply disruption, FAA rulemaking delays on structural component acceptance, and OSHA metal powder exposure limit enforcement intensity are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
Additive Manufacturing Platform Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
4D Printing Market
3D Printing Technology
3D Printing Software Market