
 North America Additive Manufacturing Market | 2026-2036
North America Additive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Additive Manufacturing Market Analytics
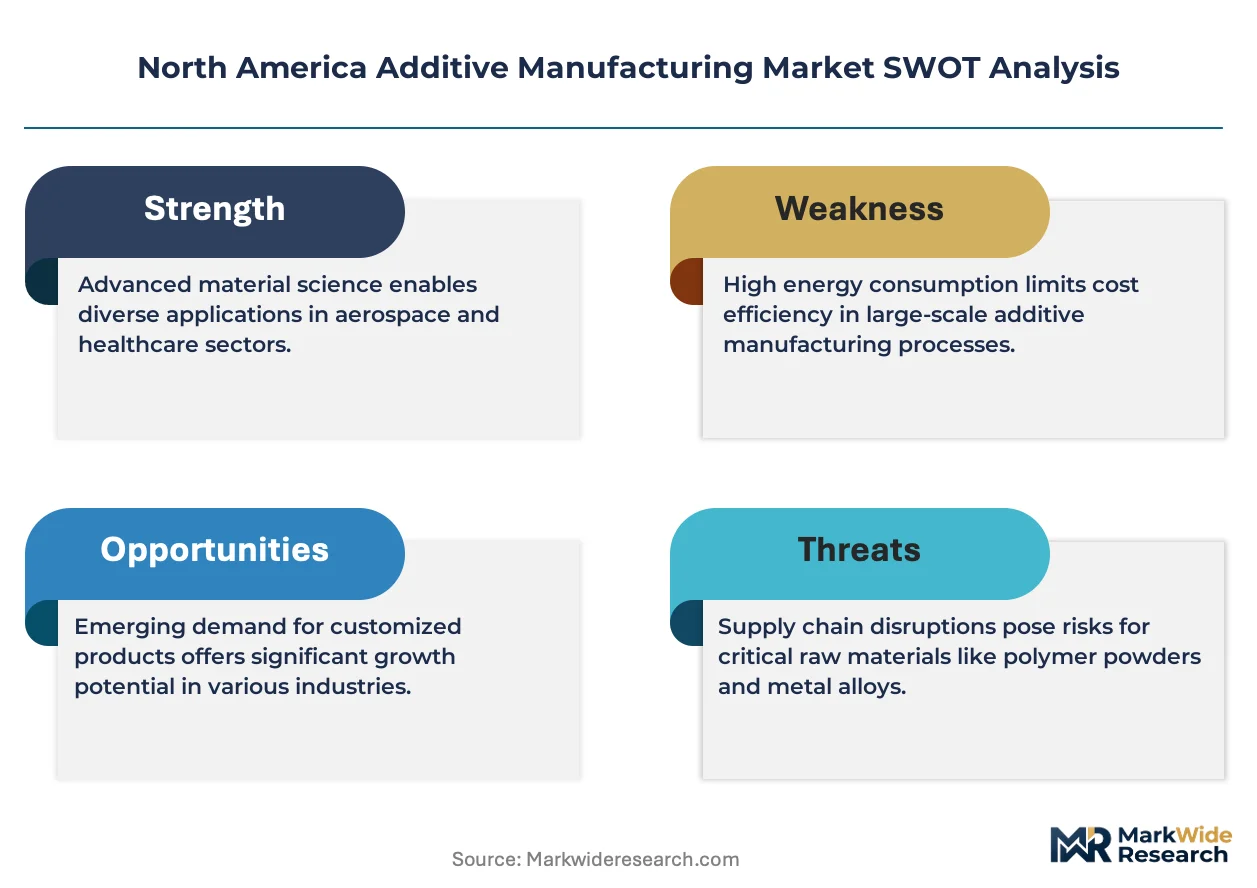
The capital-intensity divergence between metal-capable and polymer-only platforms is unwinding competitive hierarchies across North America. GE Additive leverages its captive aerospace supply chain to dominate high-value superalloy applications. Stratasys Ltd. anchors the mid-market polymer segment through extensive channel control and brand recognition. Desktop Metal, Inc. competes aggressively on system price points to extend its installed base among smaller contract manufacturers.
Additive manufacturing denotes layer-by-layer fabrication processes that build three-dimensional objects from digital models, typically operating with resolution tolerances between 25 and 100 microns depending on the specific technology. These systems serve industrial and commercial purposes by enabling geometric complexity, material efficiency, and supply chain compression that subtractive methods cannot replicate. Services and materials together capture the dominant margin pools as hardware commoditization pressures intensify across FDM and SLA technology tiers. Aerospace and healthcare end-user segments command premium pricing due to stringent certification requirements and patient-specific customization needs.
The FAA's evolving airworthiness directives, FDA's 3D-printed medical device guidance, and NIST measurement science frameworks collectively shape product standards and market access across the United States. Canadian regulators under Transport Canada and Health Canada maintain parallel but distinct qualification pathways that fragment certification strategies for cross-border suppliers. Stakeholders must monitor the divergence between American and Canadian regulatory timetables when allocating capital for qualification investments.
Market Dynamics
Flight certification pathways at the FAA are compressing supplier qualification timelines while elevating process documentation requirements across the aerospace supply chain.
Growth Catalysts
- Superalloy qualification frameworks:FAA airworthiness directives for additively manufactured turbine blades are unlocking production contracts for flight-critical components. Defense procurement offices in the United States and Canada are accelerating source approvals.
- Point-of-care manufacturing:FDA 3D-printed medical device guidance is enabling hospital-based production of patient-specific surgical guides and orthopedic implants. Health Canada maintains parallel qualification streams for cross-border device suppliers.
- California-Texas manufacturing corridor:Concentrated defense and space manufacturing clusters in these states are driving demand for metal powder bed fusion systems and associated post-processing infrastructure.
Market Restraints
- Titanium powder supply concentration:Spherical titanium feedstock production concentrates among a limited set of plasma atomization suppliers, creating input cost volatility and qualification dependency.
- Cross-border regulatory divergence:Transport Canada maintains distinct airworthiness certification timelines from FAA pathways, fragmenting qualification investments for suppliers serving both markets.
- Subtractive machining substitution:Five-axis CNC systems retain cost advantages for medium-complexity geometries in production volumes above 10,000 units, limiting AM penetration in automotive supply chains.
Strategic Opportunities
- Mexico contract manufacturing expansion:Underpenetrated industrial regions in Querétaro and Baja California present greenfield opportunities for AM service bureaus targeting aerospace tier-2 suppliers.
- NIST measurement science frameworks:Federal funding for AM-specific metrology standards is creating qualification infrastructure that reduces barrier-to-entry for mid-market polymer and metal system vendors.
- Digital inventory convergence:Cloud-based part repositories combined with distributed printing networks are displacing traditional warehousing for legacy aerospace and industrial spare parts.
Industry Challenges
- Process control engineer scarcity:Qualified personnel capable of managing laser powder bed fusion parameter optimization and in-situ monitoring systems command premium compensation, constraining production scaling.
- HIP equipment capex requirements:Hot isostatic pressing systems for densifying metal AM components require seven-figure capital commitments, creating capacity bottlenecks for flight-critical part suppliers.
- Multi-site certification synchronization:AS9100 and NADCAP audits across distributed printing operations create compliance timeline mismatches that delay contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Additive Manufacturing Market |
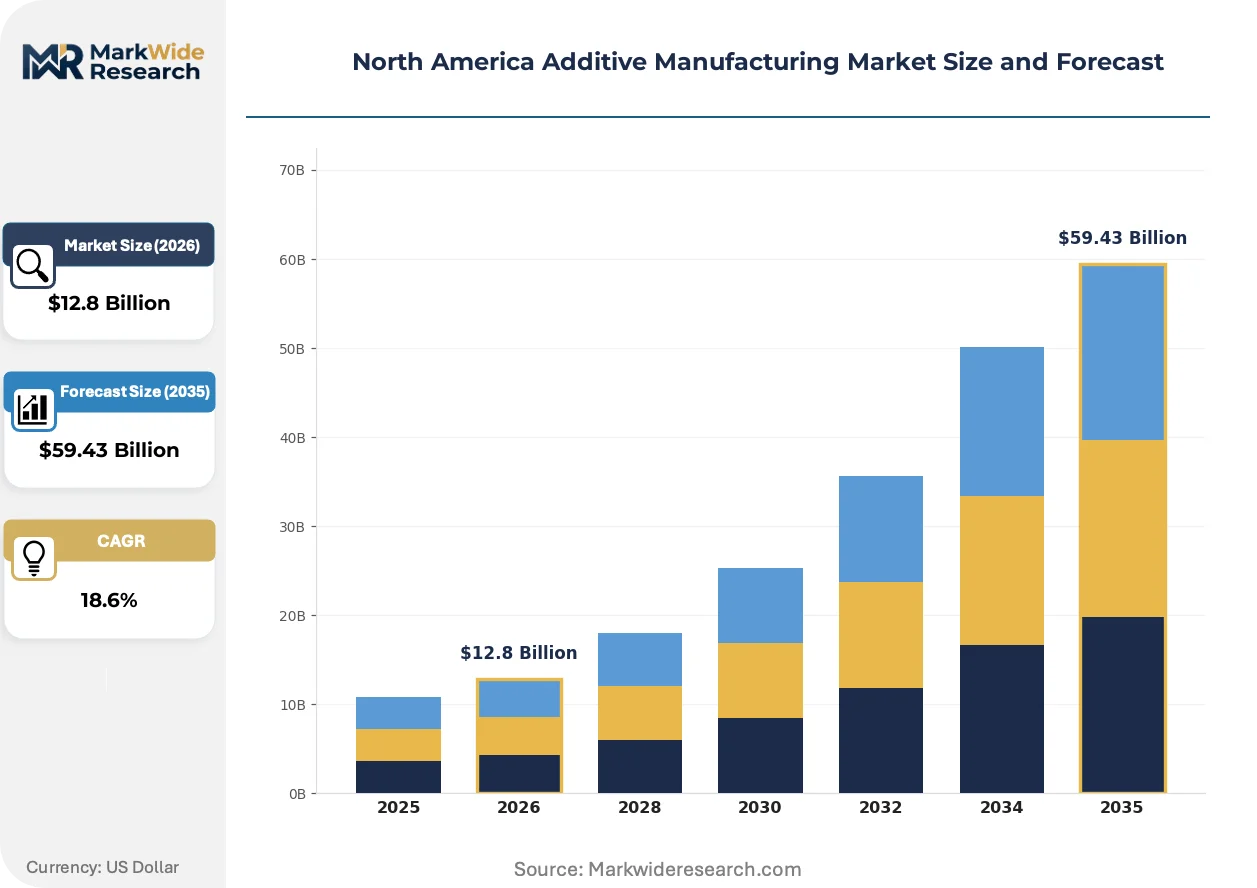
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $59.43 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printers, Materials, Software, Services End User: Aerospace, Automotive, Healthcare, Consumer Goods Technology: FDM, SLS, SLA, DLP Application: Prototyping, Tooling, Production, Design |
| Companies Covered | 3D Systems Corporation, Stratasys Ltd., Proto Labs, HP Inc., Desktop Metal, Inc., Markforged, GE Additive, Materialise, Formlabs, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Additive Manufacturing Market Evolving Landscape
Process monitoring technologies and qualification automation are compressing the gap between prototype validation and production release across North American aerospace and medical device supply chains.
Directed energy deposition systems for repair applications are miniaturizing from gantry-scale installations to portable units deployable at maintenance facilities. MRO providers at Delta and United Airlines technical operations centers are piloting these systems for turbine blade restoration. The technology is miniaturizing field repair economics by eliminating component removal and shipping costs while extending mean time between overhauls.
FAA Order 8110.37C updates for additively manufactured parts are mandating digital thread documentation from powder lot to finished component. Aerospace prime contractors are restructuring supplier agreements to enforce traceability software integration. Tier-1 suppliers in Connecticut and Arizona are responding by consolidating process control software vendors to reduce audit complexity.
Consignment powder inventory models are displacing traditional feedstock purchasing for high-volume metal AM operations. Service bureaus in Ohio and Pennsylvania are negotiating vendor-managed inventory agreements with titanium and nickel superalloy suppliers. This shift concentrates most visibly among defense contractors managing ITAR-controlled material flows where stockout risks carry program delay penalties.
North America Additive Manufacturing Market Segmentation
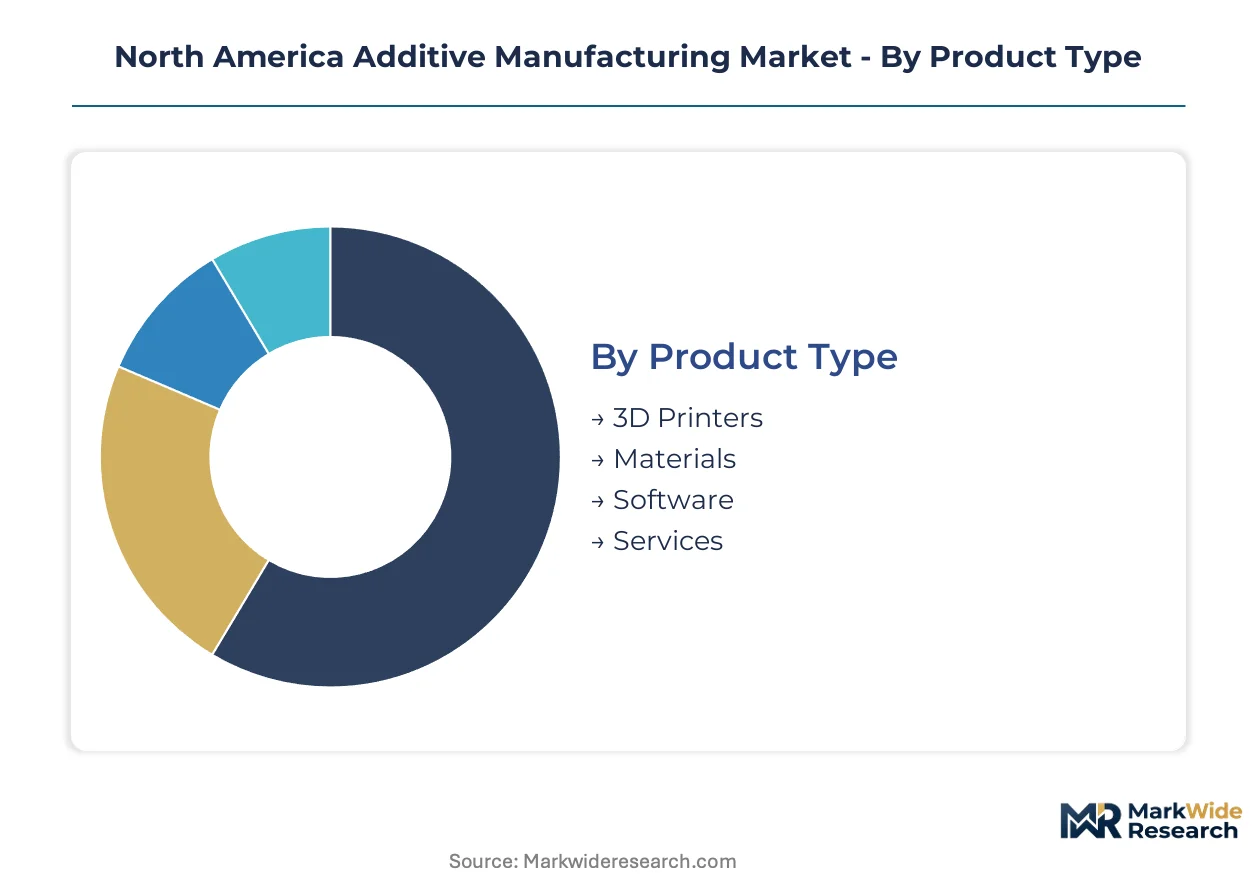
Segmentation in North American additive manufacturing reveals where capital deployment concentrates and where substitute technologies retain cost advantages. Aerospace certification requirements and healthcare patient-specific demands create divergent margin structures across product categories.
Product Type:
Services face the strongest substitution pressure from in-house printer acquisitions as unit economics improve for metal systems.
- Services:Contract manufacturers operate powder bed fusion and directed energy deposition cells for clients lacking capital for captive capacity. Demand clusters in Ohio and Pennsylvania where aerospace tier-2 suppliers outsource flight-critical component production to avoid NADCAP qualification costs.
- Materials:Spherical titanium and nickel superalloy powders command premium pricing due to plasma atomization bottlenecks. California defense contractors negotiate consignment inventory agreements to secure ITAR-controlled feedstock flows.
- 3D Printers:Hardware revenue concentrates in metal powder bed fusion systems for aerospace applications.
- Software:Process control and digital thread documentation tools capture recurring licensing revenue from AS9100-compliant operations.
Services retains volume leadership; Materials holds the steepest expansion curve.
End User:
Cost tier stratification separates flight-certified aerospace demand from price-sensitive automotive prototyping.
- Aerospace:FAA airworthiness directives for additively manufactured turbine blades mandate digital thread documentation from powder lot to finished component. Connecticut and Arizona tier-1 suppliers consolidate process control software vendors to reduce audit complexity.
- Healthcare:FDA 3D-printed medical device guidance enables hospital-based production of patient-specific surgical guides. Health Canada maintains parallel qualification streams for cross-border device suppliers.
- Automotive:Five-axis CNC systems retain cost advantages for medium-complexity geometries above 10,000 units.
- Consumer Goods:Polymer FDM systems serve low-volume customization and bridge manufacturing applications.
Aerospace dominates premium pricing tiers; Healthcare gains share fastest among regulated end-use segments.
Technology:
Application maturity varies sharply between established polymer extrusion and emerging metal deposition methods.
- FDM:Fused deposition modeling dominates polymer prototyping and jigs/fixtures production with lowest system cost and operational simplicity. Desktop systems penetrate educational institutions and small contract manufacturers across Texas and California.
- SLS:Selective laser sintering of nylon and TPU enables functional prototypes and end-use parts without support structures. Medical device manufacturers in Minnesota leverage SLS for surgical planning models.
- SLA:Stereolithography delivers highest polymer resolution for dental and jewelry applications requiring fine feature detail.
- DLP:Digital light processing accelerates photopolymer curing for dental aligner production at reduced per-part cost.
FDM maintains installed base dominance; SLS climbs fastest in production part applications.
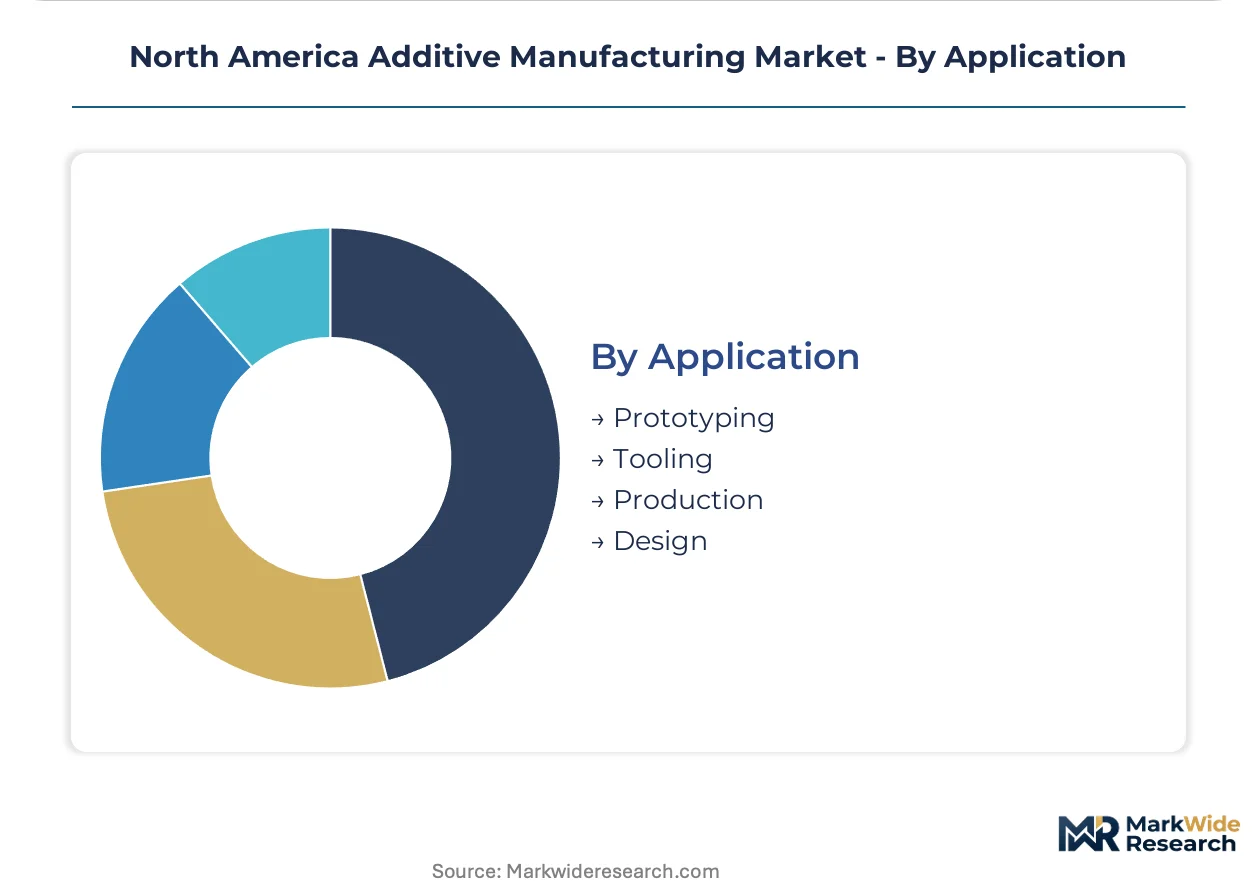
Application:
Volume scale separates mass customization production from one-off prototyping economics.
- Production:Flight-certified turbine blades and orthopedic implants command process validation investments that barrier entry for mid-market competitors. Hot isostatic pressing requirements for metal densification create seven-figure capital thresholds.
- Prototyping:Design iteration speed drives polymer system utilization across automotive and consumer electronics development cycles. Ford and General Motors technical centers maintain captive FDM and SLA capacity.
- Tooling:Conformal cooling channels in injection mold inserts reduce cycle times for high-volume plastic part manufacturing.
- Design:Topology optimization software generates lattice structures impossible to machine subtractively.
Production captures margin concentration; Prototyping sustains volume leadership in system utilization hours.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America runs a structural surplus in aerospace-grade additive manufacturing exports, with United States superalloy components and Canadian medical device prints flowing to European and Asian assembly operations. Import dependence concentrates in spherical titanium feedstock from plasma atomization suppliers outside the region.
United States
FAA airworthiness directives for flight-certified turbine blades drive capital deployment toward metal powder bed fusion systems. The Department of Defense accelerates source approvals for additively manufactured defense components under revised acquisition guidelines. Connecticut and Arizona tier-1 suppliers consolidate process control software vendors to reduce AS9100 audit complexity across distributed operations.
Canada
Health Canada maintains parallel qualification streams for 3D-printed medical devices that enable hospital-based production of patient-specific surgical guides. Transport Canada airworthiness certification timelines diverge from FAA pathways, fragmenting qualification investments for cross-border aerospace suppliers. Ontario and Quebec medical device manufacturers leverage this regulatory clarity to serve North American healthcare systems.
Mexico
Querétaro and Baja California aerospace clusters present underpenetrated demand for AM service bureaus targeting tier-2 suppliers. The Secretariat of Economy promotes advanced manufacturing adoption through sectoral development programs. Contract manufacturers in these industrial corridors seek outsourced metal printing capacity to avoid captive NADCAP qualification costs.
North America Additive Manufacturing Market Competitive Landscape
Concentration sits with diversified industrial conglomerates controlling captive aerospace supply chains and mid-market polymer specialists with extensive channel control. The vendor base spans three tiers: integrated superalloy fabricators serving flight-critical applications, polymer system vendors dominating prototyping and jigs production, and emerging metal platform competitors competing on system price points. Strategic moves center on backward integration into spherical powder production and geographic expansion into underpenetrated contract manufacturing regions.
Within the diversified industrial tier, GE Additive exemplifies the captive supply chain archetype leveraging aerospace customer relationships. Stratasys Ltd. and Desktop Metal, Inc. occupy distinct positions in the polymer and accessible-metal segments respectively, with Stratasys anchoring mid-market channel density and Desktop Metal competing aggressively on capital equipment accessibility for smaller fabricators.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| Stratasys Ltd. |
| Proto Labs |
| HP Inc. |
| Desktop Metal, Inc. |
| Markforged |
| GE Additive |
| Materialise |
| Formlabs |
| Others |
Value Network & Pricing Analysis
Consignment powder inventory agreements lock in both titanium feedstock access and price visibility for defense contractors managing ITAR-controlled material flows. These vendor-managed arrangements concentrate among Ohio and Pennsylvania service bureaus negotiating directly with plasma atomization suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in North American additive manufacturing. Premium tiers attach to FAA-certified flight-critical components with full digital thread documentation, while standard tiers cover production parts without airworthiness mandates. Cost compression in polymer FDM systems is intensifying because hardware commoditization pressures mount across Desktop Metal and Formlabs price points. Tier-2 aerospace suppliers exhibit highest price sensitivity due to NADCAP qualification cost avoidance, whereas prime contractors demonstrate lowest sensitivity given captive superalloy supply chains.
Supply Chain Analysis
Canada and the United States anchor spherical titanium and nickel superalloy powder production for aerospace-grade additive manufacturing. These countries draw from limited plasma atomization capacity concentrated among a handful of qualified suppliers. Feedstock sourcing rests on ITAR-controlled material flows where stockout risks carry program delay penalties. Single-source vulnerability persists for spherical titanium grades meeting FAA airworthiness specifications. Distribution runs through direct vendor-managed inventory agreements rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American additive manufacturing functions as a service-attach opportunity where materials and process control software capture recurring revenue expanding faster than hardware unit sales.
For Market Incumbents: Secure captive powder supply through backward integration into spherical atomization capacity or exclusive offtake agreements with plasma atomization specialists. Consolidate process control software vendors across distributed operations to reduce AS9100 audit complexity. Emerging metal platform competitors competing aggressively on system price points threaten mid-market polymer margins.
For New Entrants and Emerging Players: Lead with Mexico contract manufacturing expansion targeting Querétaro and Baja California aerospace clusters where tier-2 suppliers seek outsourced capacity without NADCAP qualification investments. Hospital-based point-of-care manufacturing for patient-specific orthopedic implants presents the most penetrable healthcare segment. Position through FDA 510(k) pathway expertise bundled with clinical training services.
For Investors and Strategic Acquirers: Powder bed fusion service bureaus with existing FAA source approvals and ITAR-compliant facilities represent the priority acquisition archetype. Long-term viability hinges on qualification moats widening as FAA Order 8110.37C documentation requirements escalate. Watch for inflection when NIST measurement science frameworks standardize in-situ monitoring data formats across metal AM platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spherical Powder Production | Captive titanium feedstock supply insulates defense contractors from plasma atomization bottlenecks. |
| Digital Thread Documentation Platform | FAA Order 8110.37C compliance creates recurring software licensing revenue from aerospace suppliers. |
| Mexico Service Bureau Expansion | Querétaro aerospace clusters seek outsourced metal printing without NADCAP qualification costs. |
| Hospital System Partnership | FDA 3D-printed device guidance enables point-of-care manufacturing for patient-specific surgical guides. |
| Consignment Inventory Agreement | Vendor-managed titanium feedstock reduces stockout risks for ITAR-controlled defense programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directives, FDA 510(k) submissions, and NIST measurement science publications. Interviews with powder bed fusion process engineers, aerospace tier-1 procurement directors, hospital biomedical engineers, and plasma atomization supplier account managers inform operational assumptions. SEC 10-K filings from Stratasys, Desktop Metal, and 3D Systems provide hardware revenue segmentation. Customs data on titanium powder imports and Department of Defense contract announcements validate demand signals. Bottom-up capacity estimates from Ohio and Pennsylvania service bureaus triangulate against top-down aerospace production forecasts.
Segmentation dimensions modeled include product type, end-user industry, technology platform, and application maturity across the projection horizon. Aerospace certification tiers separate flight-critical turbine blades from non-structural prototypes. Metal powder bed fusion, polymer FDM, and directed energy deposition systems carry distinct utilization and margin assumptions. CAGRs derive from installed base expansion rates multiplied by materials consumption per machine-hour. Defense procurement acceleration under revised acquisition guidelines and Health Canada parallel qualification streams for medical devices inform regional growth differentials.
Forecasts assume regulatory continuity in FAA airworthiness certification pathways and FDA 3D-printed medical device guidance; material policy shifts would require re-modeling. Forecasts reflect assumptions on titanium powder supply concentration persisting and process control engineer scarcity constraining production scaling. Recalibration cycles align with material shifts in NIST metrology standard finalization and Transport Canada certification timeline convergence with FAA pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
3D Printing Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
Selective Laser Sintering Market
3D Printing Technology
US Additive Manufacturing Market