
 Hybrid Additive Manufacturing Market | 2026-2036
Hybrid Additive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Additive Manufacturing Market Intelligence
The performance gap between premium hybrid cells and commodity retrofit kits is broadening. DMG MORI leverages its LASERTEC series to dominate turnkey five-axis integration, while Matsuura Machinery Corporation anchors its position through powder bed fusion mills that sustain micron-level tolerances. Sandvik AB competes via captive supply of specialty metal powders and cutting tools that extend across both additive and subtractive stages.
Hybrid additive manufacturing fuses deposition-based build processes with precision CNC finishing in a single work envelope, typically achieving surface roughness below Ra 3.2 µm without secondary handling. Its primary purpose is to eliminate setup transfers for complex metal components that would otherwise require multiple machines and extended lead times. Powder bed fusion systems command the deepest margin pools in aerospace and medical device applications where porosity control proves critical. Directed energy deposition leads growth in repair and remanufacturing of large turbine shafts and propellers. Material extrusion segments occupy the most price-sensitive tier, serving jigs, fixtures, and polymer prototyping where dimensional tolerance requirements remain relaxed.
FDA device manufacturing regulations and EU MDR conformity requirements shape validation protocols for medical hybrid systems, while FAA airworthiness directives govern traceability standards for flight-critical metal parts. OSHA laser safety standards and ISO 12100 machinery risk assessments further constrain system design and operator training requirements. Stakeholders must monitor how NIST measurement science advances and evolving EPA metal powder exposure limits will alter capital deployment timelines and facility certification costs.
Market Dynamics
CE marking under the EU Machinery Directive and the EU AI Act are forcing OEMs to redesign hybrid systems around certified integrated platforms rather than retrofit assemblies. This regulatory compression favors turnkey five-axis cells over modular kits.
Growth Catalysts
- EU AI Act compliance mandates:OEMs must demonstrate conformity for autonomous process control in hybrid cells, accelerating replacement of legacy retrofit systems with certified integrated platforms across German and Italian aerospace supply chains.
- Titanium aluminide turbine blades:Powder bed fusion mills achieve the porosity control required for flight-critical aerospace components, pulling demand from conventional investment casting for single-crystal blade geometries.
- Remanufacturing economics:Directed energy deposition repair of large Inconel shafts and marine propellers extends asset life cycles, concentrating adoption around US Navy maintenance depots and European wind turbine service hubs.
Market Restraints
- Specialty metal powder supply concentration:Spherical titanium and nickel superalloy powders rely on a limited set of gas atomization facilities, with European supply particularly exposed to energy cost volatility at German and Swedish production sites.
- CE marking technical documentation burden:The Machinery Directive requires extensive risk assessments and notified body involvement for laser-hybrid systems, extending time-to-market by 8-14 months for non-European OEMs.
- Electron beam welding substitution:Deep-penetration EBW retains cost advantages for thick-section titanium joining in defense applications, limiting hybrid AM penetration in certain aerospace structural assemblies.
Strategic Opportunities
- India PLI scheme for capital goods:Domestic production incentives for precision manufacturing equipment create localized assembly opportunities for mid-range hybrid cells serving automotive and general engineering sectors.
- Real-time melt pool monitoring convergence:Integration of high-speed pyrometry with machine learning-based defect prediction enables closed-loop parameter adjustment, opening medical implant applications where FDA process validation requirements previously blocked entry.
- Service-based revenue models:Powder subscription and per-part pricing arrangements reduce customer capex barriers, with particular traction among US job shops and Italian mold-making clusters seeking production flexibility without full system ownership.
Industry Challenges
- Multi-physics simulation expertise scarcity:Thermal-mechanical modeling of deposition-distortion interactions requires specialized computational skills that outpace current vocational training output in most manufacturing economies.
- FAA airworthiness certification timelines:Qualification of new hybrid AM processes for flight-critical metal parts demands extensive mechanical testing and statistical process control documentation, stretching approval cycles to 24-36 months.
- Legacy ERP integration friction:Hybrid cells generate heterogeneous data streams from additive, subtractive, and in-process monitoring subsystems that resist clean ingestion into established manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Additive Manufacturing Market |
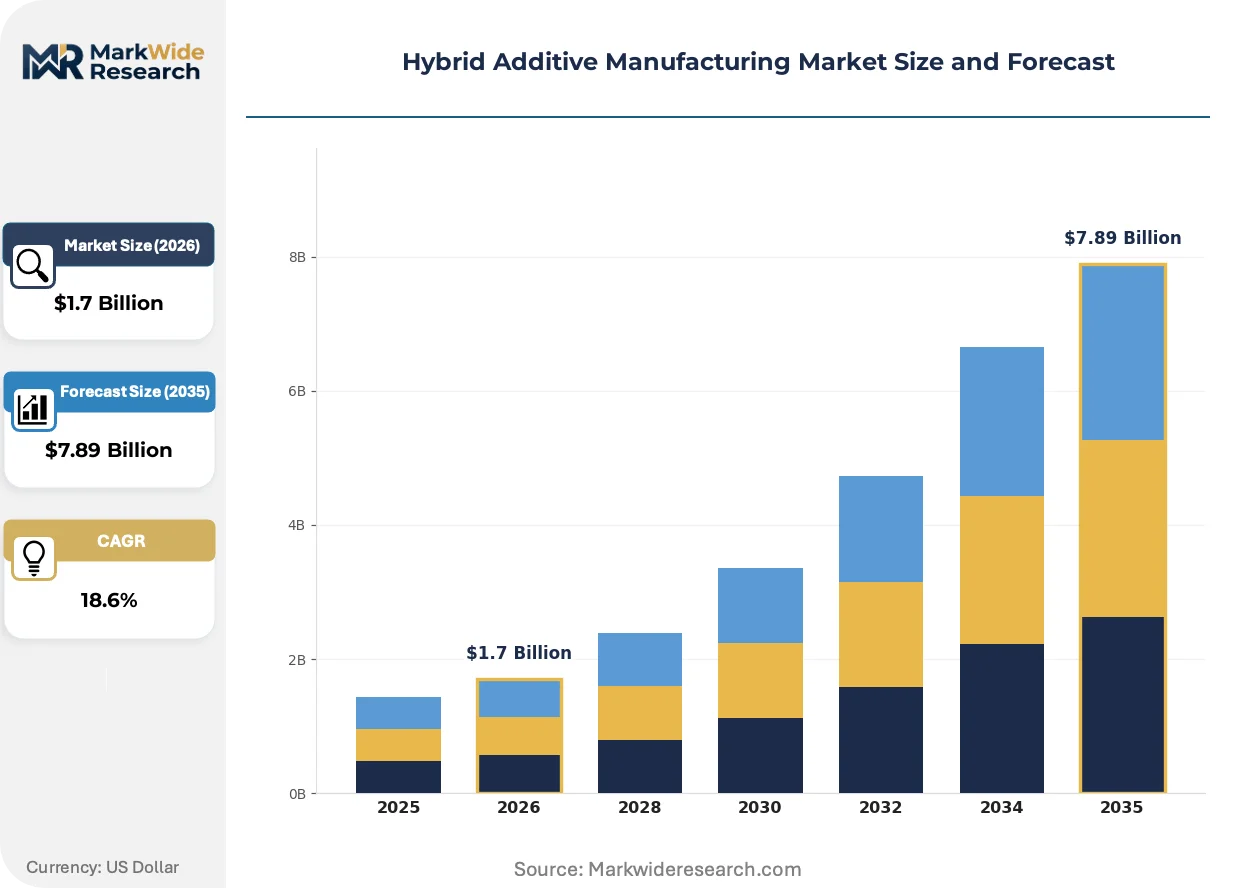
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $7.89 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Material Extrusion, Powder Bed Fusion, Directed Energy Deposition, Hybrid Manufacturing End User: Aerospace, Automotive, Medical Devices, Tooling Material Type: Metals, Plastics, Composites, Ceramics Technology: 3D Printing, CNC Machining, Laser Sintering, Electron Beam Melting |
| Companies Covered | 3D Systems, Matsuura Machinery Corporation, DMG MORI, Optomec, Stratasys, Yamazaki Mazak Corporation, Renishaw, Sandvik AB, GE Additive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Additive Manufacturing Market Strategic Shifts & Innovations
Process intelligence and regulatory automation are compressing the validation cycle for hybrid manufacturing. Three developments are restructuring how systems are deployed, certified, and monetized across aerospace, medical, and industrial end-uses.
Closed-loop melt pool control using coaxial photodiode arrays and spectral imaging is automating real-time laser power modulation during directed energy deposition. Tier-one aerospace suppliers in Germany and the US are retrofitting existing hybrid cells with these sensor packages to reduce post-process inspection overhead. The technology is compressing the feedback loop between deposition anomalies and corrective action from offline metrology to milliseconds.
EU MDR conformity requirements for patient-specific implants are mandating process validation documentation that traces every build parameter to mechanical outcome. Medical device OEMs are responding by embedding statistical process control software directly into hybrid cell controllers, creating digital thread continuity from design file to sterilized implant. French and German notified bodies are prioritizing audit resources toward facilities with this integrated documentation capability.
Buyers are unbundling equipment procurement from powder supply and maintenance contracts, treating hybrid cells as capital assets while sourcing consumables through separate annual agreements. This pattern is most visible among US job shops and Italian tool-and-die manufacturers, where volume uncertainty makes fixed powder commitments economically unattractive. Equipment vendors are responding with lower upfront pricing and higher recurring revenue streams tied to certified material throughput.
Hybrid Additive Manufacturing Market Segmentation
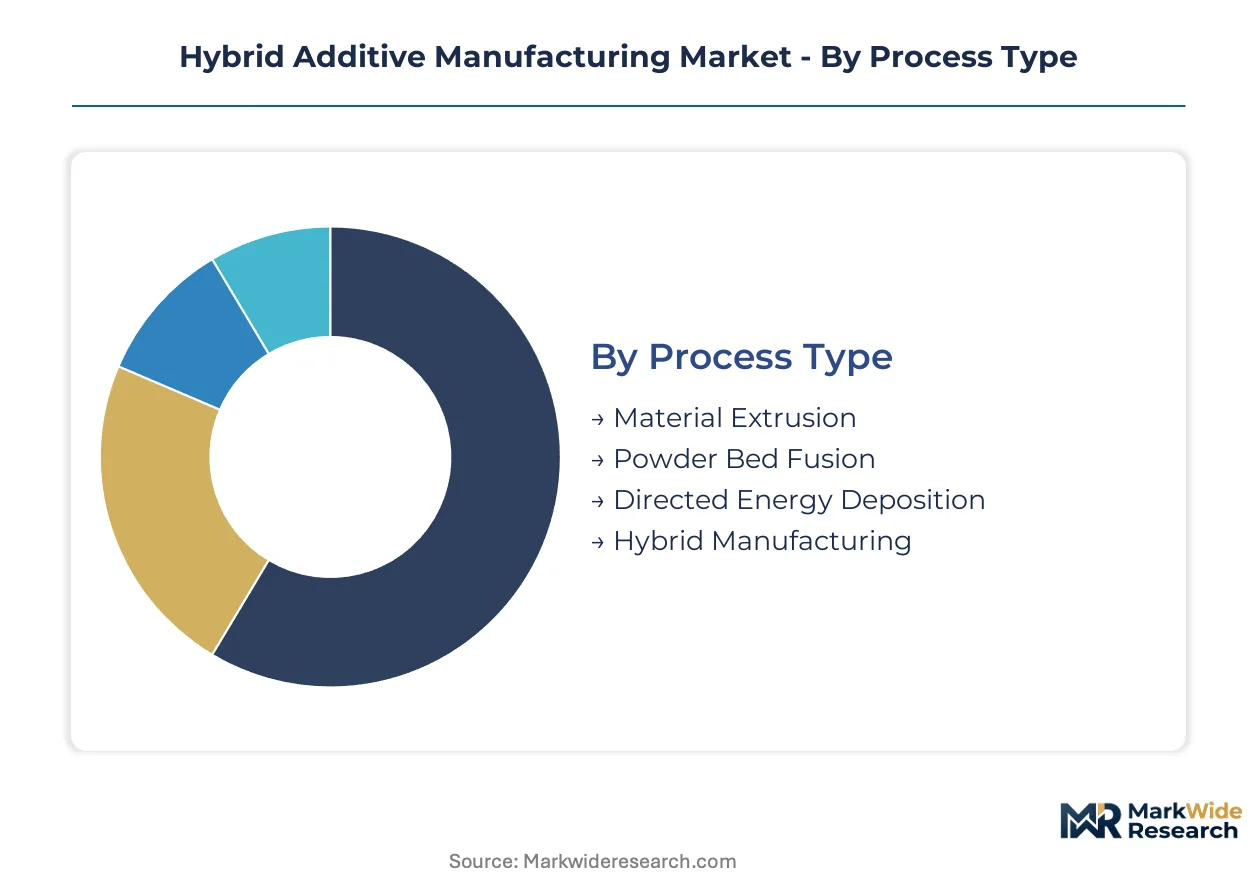
Hybrid additive manufacturing segments by process intensity, material criticality, and regulatory validation burden. Each dimension shapes capital deployment patterns and margin structures differently across aerospace repair, medical implant production, and precision tooling applications.
Process Type:
Powder bed fusion and directed energy deposition capture the premium tier through aerospace qualification, while material extrusion serves price-sensitive prototyping and fixture production.
- Powder Bed Fusion:Laser-based selective melting of metal powders achieves porosity control below 0.1% in titanium aluminide and nickel superalloy components. Demand concentrates in German and US aerospace supply chains for turbine blade production, where FAA airworthiness directives mandate statistical process validation.
- Directed Energy Deposition:Wire or powder-fed laser cladding builds near-net shapes with deposition rates exceeding 5 kg/hour for large Inconel shafts. Repair applications at US Navy maintenance depots and European wind turbine service hubs drive adoption, extending asset life cycles without full replacement.
- Material Extrusion:Thermoplastic filament deposition serves jigs, fixtures, and polymer prototyping where dimensional tolerances remain relaxed.
- Hybrid Manufacturing:Integrated deposition-machining cells combine both modalities in single work envelopes for complex metal components.
Mature deployment sits with powder bed fusion systems in certified aerospace production. Newer deployment is concentrated in directed energy deposition for field repair and remanufacturing applications.
End User:
Medical device and aerospace segments command qualification-intensive procurement, while automotive and tooling buyers prioritize throughput economics and capital efficiency.
- Aerospace:Flight-critical metal parts demand FAA traceability standards and extensive mechanical testing, stretching qualification cycles to 24-36 months. Turbine blade repair and single-crystal geometries pull investment toward turnkey five-axis hybrid cells.
- Medical Devices:Patient-specific implants require FDA process validation and EU MDR conformity documentation tracing every build parameter. French and German notified bodies prioritize audit resources toward facilities with embedded statistical process control software.
- Automotive:Powertrain prototyping and low-volume production runs seek mid-range hybrid cells with reduced capex barriers.
- Tooling:Mold and die manufacturers in Italian clusters favor service-based powder subscription models to manage volume uncertainty.
Regulatory validation intensity peaks in medical devices. Volume scaling potential concentrates in automotive powertrain applications.
Material Type:
Metals dominate value capture through specialty powder supply concentration, while plastics and composites serve peripheral applications with relaxed specification requirements.
- Metals:Spherical titanium and nickel superalloy powders rely on gas atomization facilities concentrated in Germany and Sweden, exposing supply to European energy cost volatility. Aerospace and medical implant specifications demand particle size distributions and oxygen content controls that limit qualified suppliers.
- Plastics:Engineering thermoplastics serve prototyping and non-structural fixtures where surface roughness requirements remain above Ra 6.3 µm.
- Composites:Continuous fiber reinforcement hybrid processes address automotive structural components seeking weight reduction without full metal replacement.
- Ceramics:Bioactive glass and zirconia applications concentrate in dental and orthopedic implant segments with emerging process validation protocols.
Supply chain investment flows toward metal powder atomization capacity. Process development activity is accelerating most quickly in ceramic hybrid deposition for patient-specific bioceramic implants.
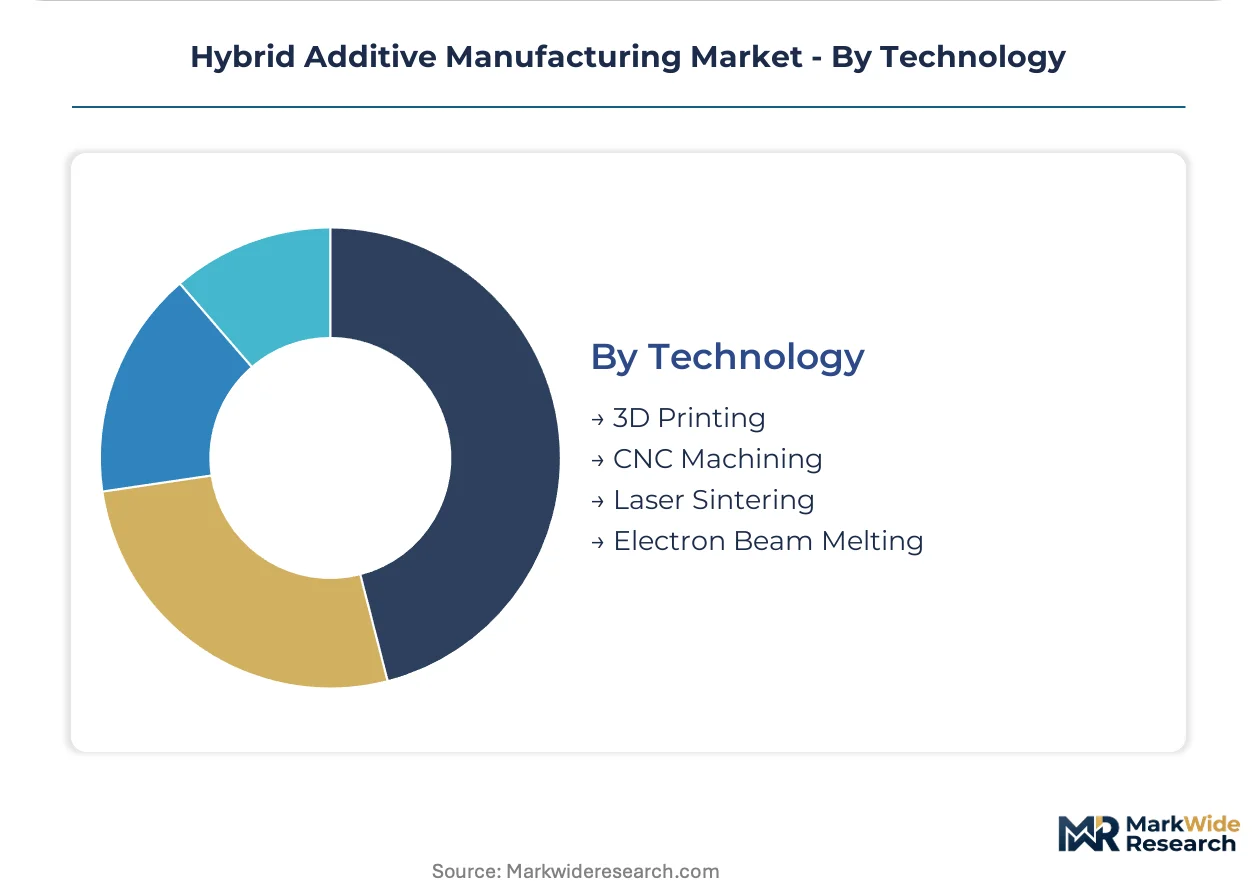
Technology:
Laser-based modalities anchor production deployment, while electron beam systems retain defense-aerospace niche positions and CNC machining provides precision finishing integration.
- 3D Printing:Fused deposition and material jetting technologies serve polymer prototyping and concept validation with minimal post-processing requirements.
- CNC Machining:Five-axis milling integration achieves surface roughness below Ra 0.8 µm on hybrid-built metal components, eliminating secondary handling and fixture transfers.
- Laser Sintering:Selective laser melting of metal powders dominates aerospace and medical production with closed-loop melt pool monitoring enabling real-time defect prediction.
- Electron Beam Melting:Vacuum-based electron beam systems retain cost advantages for thick-section titanium joining in defense structural assemblies, limiting hybrid AM penetration in certain applications.
Platform consolidation favors laser sintering integration with CNC finishing. Electron beam melting maintains position in specialized defense supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paderborn and the surrounding Ostwestfalen-Lippe region anchor European hybrid additive manufacturing demand through DMG MORI's demonstration facilities and advanced machining clusters.
Germany
CE marking under the EU Machinery Directive and EU AI Act compliance mandates accelerate replacement of legacy retrofit systems with certified integrated platforms across Bavarian and Baden-Württemberg aerospace supply chains. The country's notified bodies prioritize audit resources toward facilities with embedded statistical process control software. Paderborn and Bielefeld host concentrated demonstration centers where turnkey five-axis hybrid cells undergo operator certification.
United States
FAA airworthiness directives govern traceability standards for flight-critical metal parts while OSHA laser safety standards constrain system design requirements. The Department of Defense sustains directed energy deposition demand at Navy maintenance depots for Inconel shaft repair. Greater Boston and Pacific Northwest aerospace clusters concentrate adoption of powder bed fusion systems for titanium aluminide turbine blade production.
Japan
METI industrial technology roadmaps prioritize closed-loop melt pool monitoring convergence for medical implant applications where process validation requirements previously blocked market entry. JIS standards and PMDA device regulations shape validation protocols for patient-specific implants. Nagoya and Osaka manufacturing belts concentrate Matsuura Machinery Corporation's powder bed fusion mill deployments.
India
The PLI scheme for capital goods creates localized assembly opportunities for mid-range hybrid cells serving automotive and general engineering sectors. BIS machinery safety standards and CDSCO device regulations establish conformity frameworks for medical and industrial applications. Gujarat and Maharashtra industrial corridors concentrate demand from mold-making clusters seeking production flexibility without full system ownership.
France
ANSM and CNIL oversight of medical device data integrity combines with EU MDR conformity requirements to mandate process validation documentation tracing every build parameter. French notified bodies prioritize facilities with digital thread continuity from design file to sterilized implant. Île-de-France and Auvergne-Rhône-Alpes aerospace supply chains drive laser-hybrid system qualification for flight-critical components.
Hybrid Additive Manufacturing Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and integration complexity, with turnkey five-axis cells commanding pricing multiples over modular retrofit kits. Market structure consolidates around three strategic archetypes: diversified machine tool conglomerates with captive additive portfolios, specialized deposition system builders, and captive powder suppliers extending into cutting tools. Dominant competitive moves include backward integration into specialty gas atomization capacity and technology licensing partnerships for real-time melt pool monitoring.
Among diversified machine tool conglomerates, DMG MORI and Yamazaki Mazak Corporation occupy positions exemplifying turnkey integration archetypes, while Matsuura Machinery Corporation represents specialized powder bed fusion expertise. Sandvik AB anchors the captive supply archetype through upstream control over spherical metal powder production. These three companies collectively illustrate how competitive positioning stratifies across integration depth, geographic origin, and supply chain configuration.
| Leading Market Players |
|---|
| 3D Systems |
| Matsuura Machinery Corporation |
| DMG MORI |
| Optomec |
| Stratasys |
| Yamazaki Mazak Corporation |
| Renishaw |
| Sandvik AB |
| GE Additive |
| Others |
Cost & Logistics Intelligence
Closed-loop melt pool monitoring convergence simultaneously compresses validation cycles and concentrates procurement power among aerospace OEMs capable of absorbing premium turnkey system costs. This technological inflection redraws cost economics around certified integrated platforms while squeezing modular retrofit providers into commodity positioning.
Pricing Analysis
Outcome-based pricing anchored to qualified part throughput dominates procurement negotiations, with aerospace buyers paying premiums for FAA-traceable build documentation. Three-tier pricing structure across certified production, qualified prototyping, and unvalidated development tiers separates flight-critical medical implants from polymer jigs and fixtures. Pricing pressure stems from powder subscription models that unbundle equipment capex from consumable commitments. Automotive powertrain prototyping clusters exhibit highest price sensitivity, while German turbine blade manufacturers absorb premium positioning for single-crystal geometries.
Supply Chain Analysis
Regional distribution centers in Germany, Sweden, and the United States anchor spherical metal powder logistics through hub-and-spoke patterns serving qualified aerospace and medical facilities. Gas atomization capacity draws from limited European energy-intensive production sites, with titanium and nickel superalloy feedstock resting on German and Swedish supply nodes. Single-source vulnerability concentrates in specialty powder particle size distribution controls. Distribution runs through captive powder agreements bundled with maintenance contracts or unbundled annual throughput commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gas atomization capacity constraints prop pricing power for qualified spherical powder suppliers, with European energy cost volatility amplifying supply scarcity premiums across aerospace and medical certification tiers.
For Market Incumbents: Deploy backward integration into captive gas atomization facilities to secure titanium and nickel superalloy powder supply against German and Swedish energy volatility. Consolidate demonstration center networks around Paderborn and Nagoya clusters to accelerate operator certification pipelines. Electron beam welding substitution in thick-section defense applications threatens hybrid AM penetration; counter through FAA qualification acceleration for directed energy deposition repair protocols. For New Entrants and Emerging Players: Mid-range hybrid cell buyers in Indian automotive corridors and Italian mold-making clusters face unmet demand for localized assembly with reduced capex barriers. White-space concentration sits with per-part pricing arrangements and powder subscription models that transfer volume risk from job shops to vendors. Target service-based revenue architectures that decouple equipment ownership from certified material throughput. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified machine tool conglomerates seeking captive additive portfolios. Long-term viability favors targets with embedded statistical process control software and EU MDR audit-ready documentation capabilities. Monitor NIST measurement science advances as inflection signal for facility certification cost escalations that reshape capital deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gas Atomization Capacity | Secures spherical titanium powder supply against Swedish energy volatility for aerospace qualification tiers. |
| Embedded SPC Software Integration | Accelerates EU MDR audit prioritization for French and German notified body resources. |
| Per-Part Pricing Model Deployment | Reduces capex barriers for US job shops and Italian tooling clusters facing volume uncertainty. |
| Closed-Loop Melt Pool Monitoring | Enables FDA process validation for medical implants previously blocked by defect prediction gaps. |
| Regional Demonstration Center Expansion | Accelerates operator certification pipelines at DMG MORI and Yamazaki Mazak training facilities. |
Research Approach
Document review covered SEC filings from machine tool OEMs, FAA airworthiness directives, and EU MDR conformity guidance, complemented by interviews with plant engineers at German aerospace suppliers, biomedical engineers at French implant manufacturers, and aftermarket service heads at US Navy maintenance depots. Secondary validation drew from NIST measurement science publications, EPA metal powder exposure limit proposals, and customs data on spherical titanium powder trade flows. Bottom-up system deployment counts triangulated against top-down addressable market sizing across the analysis window.
Historical qualification timeline data cross-referenced against expert panel inputs on CE marking documentation burdens and FDA process validation cycles. Segmentation modeling spanned process type, end-use industry, material criticality, and geographic regulatory cluster. CAGRs derived from curve-fitting approaches against announced capacity expansions and PLI scheme uptake trajectories. Forecast inputs incorporated OSHA laser safety standard evolution and METI technology roadmap priorities.
Revisions become necessary when EPA metal powder exposure limits tighten, EU AI Act enforcement intensifies, or FAA qualification timelines compress beyond modeled assumptions. Forecasts reflect documented assumption sets around certification cost trajectories and powder supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
Additive Manufacturing Machines Market