
 Upper Respiratory Tract Infection Treatment Market | 2026-2036
Upper Respiratory Tract Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Upper Respiratory Tract Infection Treatment Market Outlook
Good Manufacturing Practice certification for sterile nasal spray production is reorganizing competitive entry barriers across the Upper Respiratory Tract Infection Treatment landscape. GlaxoSmithKline Plc leverages its vertically integrated respiratory portfolio to dominate retail pharmacy shelf space in North America. Pfizer Inc. sustains R&D intensity across antiviral programs targeting rhinovirus and influenza co-infections. AstraZeneca Plc anchors its position through biologics development for severe pharyngitis cases requiring hospital administration.
Upper respiratory tract infection treatment encompasses pharmaceutical and non-pharmaceutical interventions targeting mucosal inflammation of the nasal cavity, pharynx, larynx, and paranasal sinuses, with formulations typically containing active pharmaceutical ingredients at concentrations between 0.05% and 10% depending on delivery mode and regulatory classification. These products function primarily to reduce symptom duration, alleviate mucosal edema, and prevent secondary bacterial complications in both immunocompetent and immunocompromised patient populations. Antibiotics and decongestants lead product type revenue pools, though cough suppressants generate disproportionate margins in pediatric segments where formulation palatability commands premium positioning. Oral delivery mode retains volume dominance across all therapy areas, while nasal spray formulations capture growing share within home care settings due to faster onset kinetics and reduced systemic exposure.
FDA monograph reform and EMA's revised guidance on topical decongestant cardiovascular safety are tightening formulation standards and reshaping over-the-counter label claims across multiple jurisdictions. The WHO's Essential Medicines List updates for antibiotics in upper respiratory indications are influencing national procurement policies and generic substitution rates in emerging markets. Stakeholders must monitor evolving antimicrobial stewardship protocols that restrict empirical antibiotic prescribing for viral pharyngitis and sinusitis, as these clinical guideline shifts directly alter volume trajectories across retail and institutional channels.
Market Dynamics
Antimicrobial stewardship protocols are compressing antibiotic prescribing volumes across retail and institutional channels, forcing manufacturers to pivot toward antiviral and symptomatic relief portfolios while reformulating legacy products for OTC monograph compliance.
Growth Catalysts
- Pediatric viral load expansion:Rising rhinovirus and respiratory syncytial virus circulation among children under five is elevating ambulatory care visits and driving demand for palatable pediatric formulations in urgent care settings.
- EMA cardiovascular safety reviews:The agency's tightened topical decongestant guidance is accelerating reformulation investment toward phenylephrine-free and saline-based alternatives that bypass systemic absorption concerns.
- Home care delivery mode shift:Nasal spray kinetics with reduced systemic exposure are capturing preference among immunocompromised patients managing mucosal inflammation outside hospital settings.
Market Restraints
- API supply concentration:Pseudoephedrine precursor sourcing clusters in specific Asian manufacturing zones, exposing formulators to import restriction volatility and diversion control audits.
- Antibiotic resistance protocols:WHO Essential Medicines List stewardship criteria and national formularies are restricting empirical prescribing for viral pharyngitis, collapsing historical volume baselines for macrolide and penicillin derivatives.
- Substitution by non-pharmaceutical interventions:Humidification devices and saline irrigation systems are capturing share among educated patient populations seeking to avoid pharmacologic dependency.
Strategic Opportunities
- Direct-to-consumer channel expansion:Telehealth platforms and pharmacy subscription services are creating bypass routes around traditional physician gatekeeping for symptomatic relief products.
- Biologics convergence with severe pharyngitis:Monoclonal antibody development targeting Group A Streptococcus exotoxins offers hospital administration pathways distinct from commoditized oral antibiotics.
- India PLI scheme for APIs:The country's production-linked incentive framework for bulk drug manufacturing is attracting contract development investment to diversify precursor supply away from concentrated zones.
Industry Challenges
- Sterile manufacturing certification timelines:Good Manufacturing Practice compliance for aqueous nasal spray production requires 18-24 month facility validation cycles that delay product launch windows.
- Formulation palatability engineering:Pediatric segments demand taste-masking complexity that extends R&D cycles and elevates bioequivalence study costs for generic entrants.
- Legacy system integration:Enterprise resource planning upgrades to track lot-level serialization for FDA track-and-trace compliance are straining mid-sized manufacturer IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Upper Respiratory Tract Infection Treatment Market |
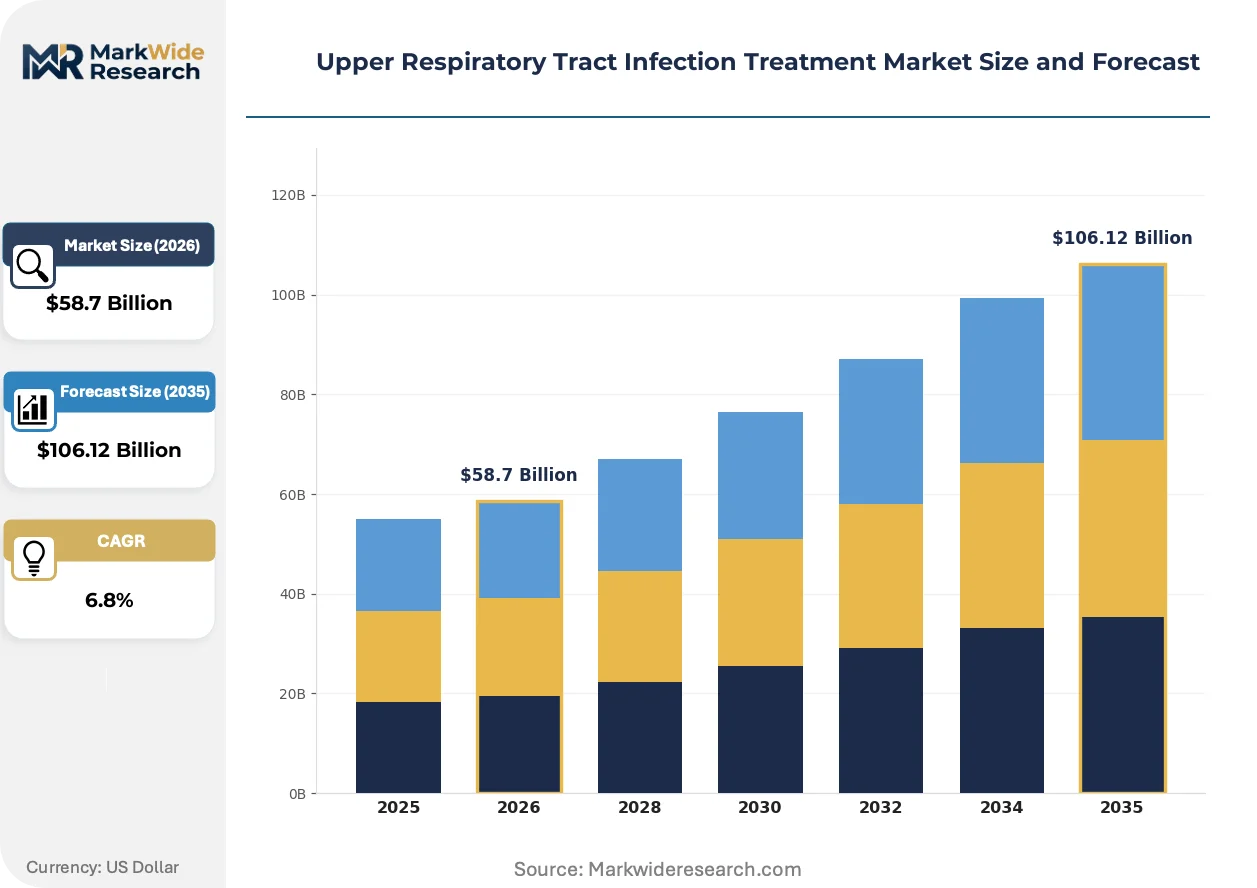
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antihistamines, Decongestants, Cough Suppressants Therapy Area: Common Cold, Sinusitis, Pharyngitis, Laryngitis Delivery Mode: Oral, Nasal Spray, Topical, Injectable End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | GlaxoSmithKline Plc, Pfizer Inc., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., AstraZeneca Plc, Sanofi, Novartis AG, Johnson & Johnson, Regeneron Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Upper Respiratory Tract Infection Treatment Market Strategic Shifts
Formulation science and delivery mechanism innovation are compressing symptom onset windows while regulatory pressure on systemic decongestants accelerates investment in localized, non-absorbed alternatives.
Intranasal corticosteroid suspensions with mucoadhesive polymers are supplanting oral antihistamine-decongestant combinations in allergic rhinitis overlap populations. Allergy specialists and primary care networks in the United States are adopting these formulations at accelerating rates for patients with recurrent sinusitis. The technology is supplanting first-line oral therapy by reducing systemic anticholinergic exposure while delivering faster edema reduction through direct mucosal deposition.
REACH-compliant solvent restrictions and EMA propellant phase-down mandates are forcing reformulation of metered-dose nasal delivery systems across European manufacturing facilities. Industrial consequence includes accelerated capital deployment into aqueous pump systems and dry powder platforms that eliminate hydrofluoroalkane dependency. Otolaryngology-focused products in Germany and France are responding with dose-counter integration and preservative-free single-use vials to maintain reimbursement positioning.
Retail pharmacy chains are consolidating shelf space decisions through centralized formulary committees that prioritize private-label and exclusive distribution agreements over traditional branded portfolios. Independent community pharmacies and regional grocery health sections are losing direct vendor relationships as purchasing concentrates through three national wholesalers. This concentration is most visible in United States suburban markets where CVS Health and Walgreens Boots Alliance control endcap placement and inventory turns for cough-cold seasonality.
Upper Respiratory Tract Infection Treatment Market Segmentation
Channel economics and regulatory pathways diverge sharply across product formats and care settings in respiratory therapeutics. Manufacturers must align formulation investments with where prescribing authority and purchasing decisions actually concentrate.
Product Type:
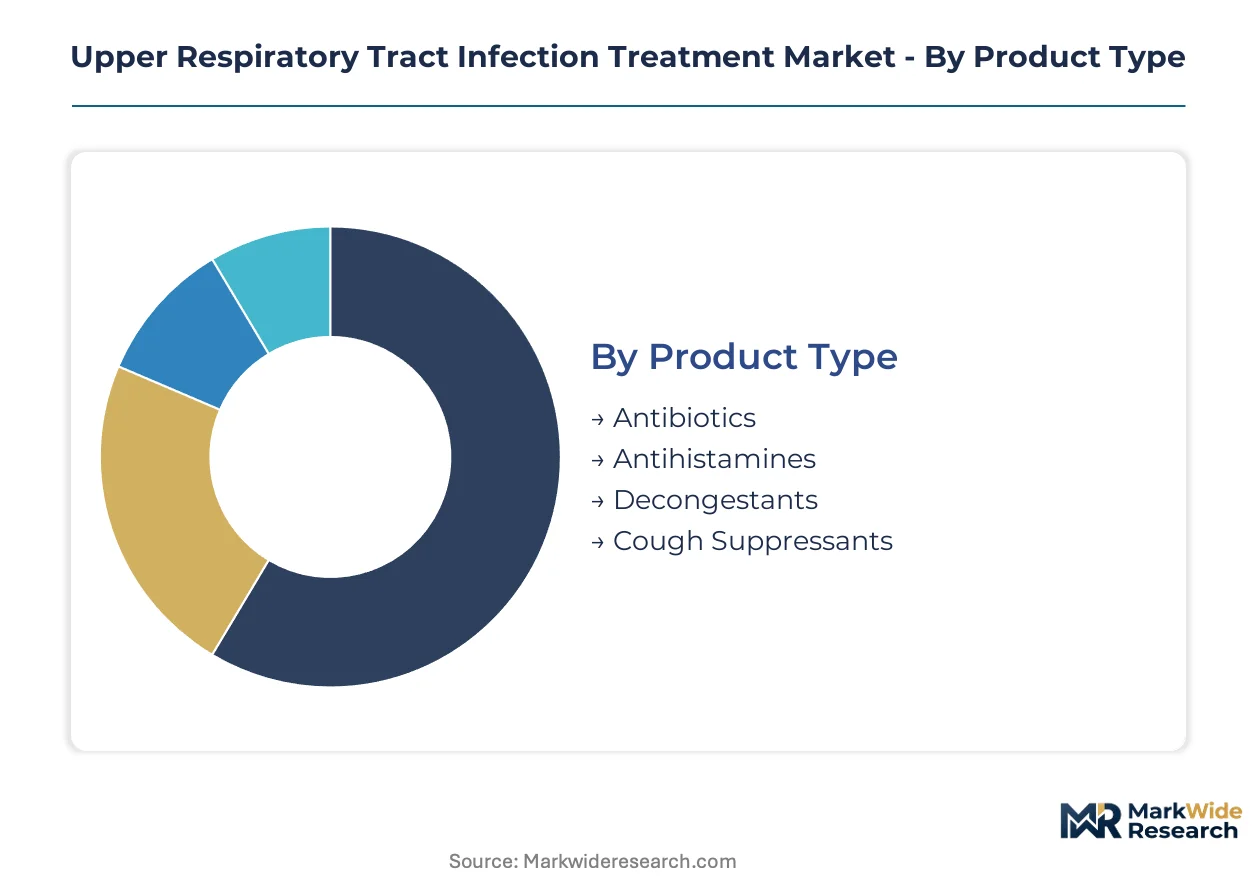
Retail pharmacy chains and direct-to-consumer platforms move decongestants and cough suppressants in highest volumes, while antibiotics and antihistamines face tighter gatekeeping through prescriber channels.
- Antibiotics:Macrolide and penicillin derivatives target bacterial sinusitis and streptococcal pharyngitis. Antimicrobial stewardship protocols in ambulatory care networks are restricting empirical prescribing, collapsing historical volume baselines for legacy formulations.
- Antihistamines:First- and second-generation H1 antagonists reduce rhinorrhea and sneezing in allergic overlap populations. Seasonal demand spikes in United States suburban markets drive inventory pre-positioning through CVS Health and Walgreens distribution centers.
- Decongestants:Oral pseudoephedrine and topical phenylephrine formulations alleviate mucosal edema through vasoconstriction. FDA monograph reform and EMA cardiovascular safety reviews are forcing phenylephrine-free reformulation investment.
- Cough Suppressants:Dextromethorphan and codeine-based antitussives reduce cough reflex sensitivity. Palatability-engineered pediatric liquids command premium positioning in urgent care settings where caregiver compliance determines repurchase rates.
Decongestants dominate installed base. Cough suppressants is where expansion concentrates.
Therapy Area:
Cost tier stratification separates acute self-limiting conditions from chronic recurrent presentations requiring specialist referral and biologic intervention.
- Common Cold:Viral rhinovirus and coronavirus infections drive highest-frequency, lowest-acuity encounters. Symptomatic relief products move through retail self-selection with minimal clinical oversight.
- Sinusitis:Acute bacterial and chronic rhinosinusitis presentations generate antibiotic prescriptions and intranasal corticosteroid adoption. United States otolaryngology practices are expanding mucoadhesive polymer formulations for recurrent cases.
- Pharyngitis:Viral and Group A Streptococcus etiologies split between symptomatic management and antimicrobial therapy. AstraZeneca's biologics development targets severe hospital-administered cases with exotoxin-neutralizing monoclonal antibodies.
- Laryngitis:Acute laryngeal inflammation from viral or vocal strain etiologies receives limited pharmacologic intervention. Voice therapy and humidification devices capture share among professional voice users seeking to avoid pharmacologic dependency.
Common cold dominates installed base. Sinusitis is where expansion concentrates.
Delivery Mode:
Volume concentration and margin capture invert across oral dominance versus nasal spray growth trajectories in home care migration.
- Oral:Tablets, capsules, and liquids retain volume leadership across all therapy areas due to manufacturing scale and patient familiarity. Solid dose forms accommodate the widest range of active pharmaceutical ingredient concentrations from 0.05% to 10%.
- Nasal Spray:Aqueous and aerosolized pump systems deliver localized corticosteroid and decongestant action with reduced systemic exposure. Faster onset kinetics are capturing preference among immunocompromised patients managing mucosal inflammation outside hospital settings.
- Topical:Throat lozenges, chest rubs, and nasal ointments provide sensory relief with limited systemic absorption. REACH-compliant solvent restrictions and EMA propellant phase-down mandates are forcing aqueous reformulation across European manufacturing.
- Injectable:Ceftriaxone and other parenteral antibiotics serve severe bacterial complications in emergency department and inpatient settings. Hospital formulary placement requires 18-24 month GMP facility validation cycles that delay competitive entry.
Oral dominates installed base. Nasal spray is where expansion concentrates.
End User:
Customer type determines reimbursement pathway complexity and private-label vulnerability in purchasing concentration.
- Hospitals:Inpatient and emergency departments manage severe pharyngitis, complicated sinusitis, and secondary bacterial pneumonia. Biologics and parenteral antibiotics anchor formulary positioning through infectious disease specialist influence.
- Clinics:Urgent care and primary care networks handle the majority of ambulatory respiratory encounters. Pediatric viral load expansion among children under five is elevating visit frequency and palatable formulation demand.
- Home Care:Self-administered nasal sprays, humidification devices, and saline irrigation systems bypass traditional physician gatekeeping. Telehealth platforms and pharmacy subscription services are creating direct-to-consumer bypass routes for symptomatic relief.
- Pharmacies:Retail chains and independent dispensaries represent the terminal distribution node for OTC and prescription products. Centralized formulary committees at CVS Health and Walgreens Boots Alliance now control endcap placement and inventory turns for cough-cold seasonality.
Pharmacies dominate installed base. Home care is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's production-linked incentive scheme for active pharmaceutical ingredients is attracting contract development investment and diversifying precursor supply chains away from concentrated Asian manufacturing zones. Germany's EMA-aligned regulatory framework is accelerating phenylephrine-free reformulation timelines across European nasal spray production. Brazil's national pharmaceutical procurement policies are shifting generic substitution rates for upper respiratory antibiotics.
United States
Pediatric viral load expansion among children under five is elevating urgent care visit frequency and palatable formulation demand. FDA monograph reform is reshaping over-the-counter approval pathways for nasal decongestants. Retail pharmacy chains in suburban markets concentrate shelf space decisions through CVS Health and Walgreens Boots Alliance distribution centers.
Germany
REACH-compliant solvent restrictions and EMA propellant phase-down mandates are forcing aqueous pump system investment. The country's federal pharmaceutical regulator maintains tightened topical decongestant cardiovascular safety guidance. Otolaryngology-focused manufacturing clusters in Bavaria and North Rhine-Westphalia are deploying preservative-free single-use vial technologies.
India
The PLI scheme for bulk drug manufacturing is attracting fermentation and chemical synthesis capacity for pseudoephedrine precursors. CDSCO alignment with WHO Essential Medicines List stewardship criteria is restricting empirical antibiotic prescribing protocols. API production corridors in Gujarat and Maharashtra are expanding sterile nasal spray facility validation cycles.
Japan
Aging population immunocompromised cohorts are capturing preference for reduced systemic exposure delivery modes. PMDA guidance on intranasal corticosteroid suspensions is accelerating mucoadhesive polymer adoption. Pharmaceutical manufacturing in the Kanto region around Tokyo is integrating dose-counter technologies for reimbursement positioning.
Brazil
Seasonal viral circulation patterns are driving inventory pre-positioning through national pharmacy distribution networks. ANVISA procurement alignment with antimicrobial stewardship protocols is collapsing macrolide volume baselines. Generic substitution manufacturing in São Paulo and Rio de Janeiro states is pivoting toward antiviral and symptomatic relief portfolios.
Upper Respiratory Tract Infection Treatment Market Competitive Environment
Player mix skews toward vertically integrated pharmaceutical conglomerates with respiratory portfolio depth, mid-sized generic manufacturers with API backward integration, and biologics specialists targeting severe hospital-administered cases. The structure concentrates around three strategic archetypes: multinational innovators with retail pharmacy shelf space dominance, regional formulators with cost-optimized oral solid dose capacity, and monoclonal antibody developers pursuing exotoxin-neutralizing pathways. Competitive moves center on sterile manufacturing certification timelines for aqueous nasal spray production and direct-to-consumer channel expansion through telehealth platform partnerships.
Within the multinational innovator tier, GlaxoSmithKline Plc and Pfizer Inc. occupy positions exemplifying vertically integrated respiratory portfolio strategies, while AstraZeneca Plc represents the biologics convergence archetype for severe pharyngitis hospital administration. These entities anchor distinct competitive vectors: GlaxoSmithKline exemplifies retail pharmacy chain formulary influence, Pfizer occupies antiviral program R&D intensity positioning, and AstraZeneca sits within the hospital-administered monoclonal antibody development pathway for Group A Streptococcus exotoxin targets.
| Leading Market Players |
|---|
| GlaxoSmithKline Plc |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| AstraZeneca Plc |
| Sanofi |
| Novartis AG |
| Johnson & Johnson |
| Regeneron Pharmaceuticals Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for pseudoephedrine precursors lock in supply access and price visibility for nasal decongestant manufacturers navigating API import restriction volatility. These arrangements concentrate purchasing power among vertically integrated pharmaceutical conglomerates while exposing mid-sized formulators to spot market exposure during diversion control audits.
Pricing Analysis
Certification level (FDA-grade GMP versus standard pharmaceutical grade) creates the primary spread between premium and economy positioning in nasal spray production. Three-tier pricing structure across premium, standard, and economy levels reflects sterile manufacturing validation status, with 18-24 month facility certification cycles embedding cost premiums into hospital-administered biologics. Cost compression in economy oral solid dose segments is intensifying because of Indian generic substitution manufacturing scale. Retail pharmacy chains exhibit highest price sensitivity, while hospital formulary committees prioritize clinical efficacy over unit cost.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for pseudoephedrine precursors and macrolide antibiotic fermentation. Supply chains draw from concentrated Asian manufacturing zones for chemical synthesis inputs, hydrofluoroalkane propellants, and mucoadhesive polymer excipients. Single-source vulnerability in pseudoephedrine precursor sourcing exposes formulators to import restriction volatility and diversion control audits. Distribution runs through three national wholesalers concentrating purchasing decisions for CVS Health and Walgreens Boots Alliance retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
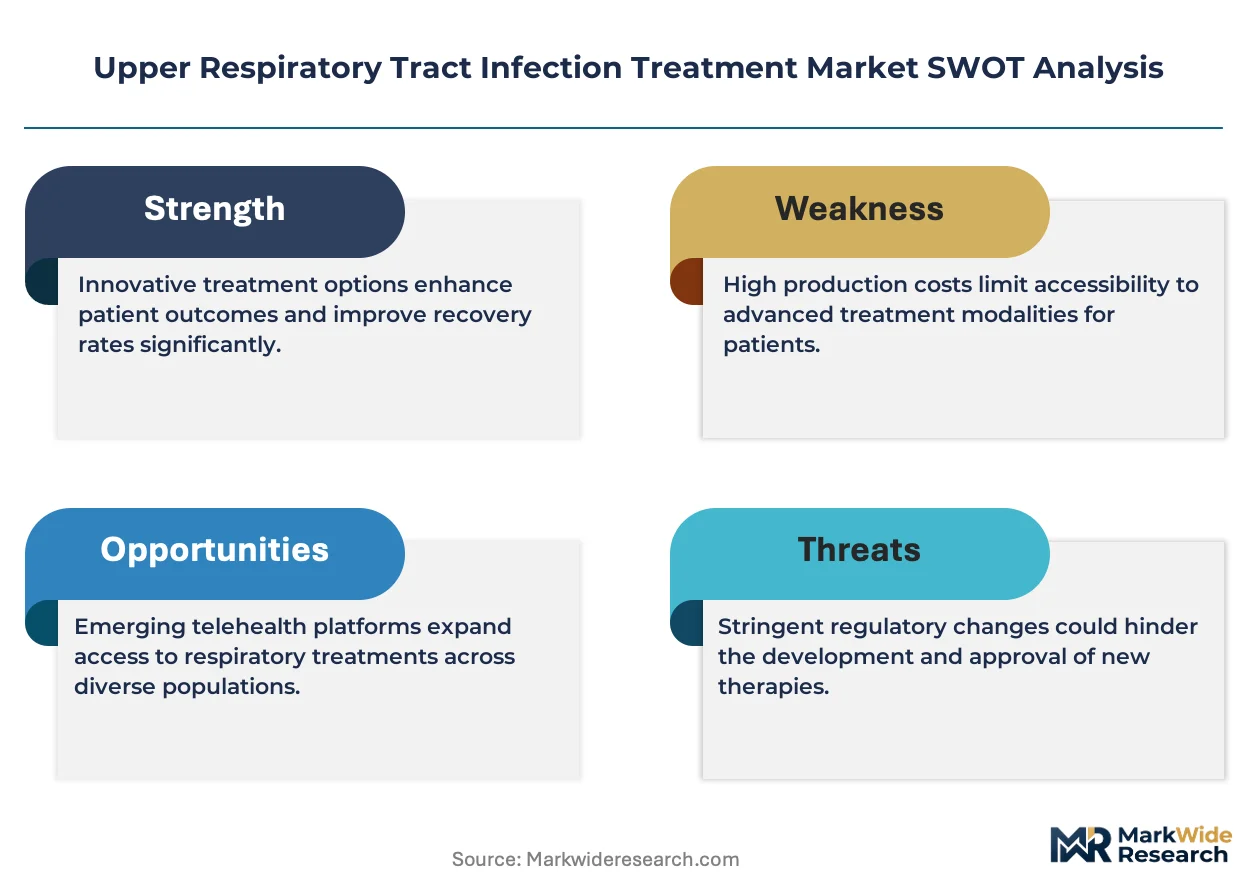
The Upper Respiratory Tract Infection Treatment Market sits in early-cycle expansion as home care delivery mode shifts bypass traditional physician gatekeeping. Pediatric viral load expansion and direct-to-consumer channel growth create penetration tailwinds for nasal spray formulations.
For Market Incumbents: Fortify sterile manufacturing certification moats by accelerating GMP facility validation cycles ahead of competitors. Defend retail pharmacy shelf space through exclusive distribution agreements with CVS Health and Walgreens Boots Alliance, while pivoting R&D investment toward phenylephrine-free reformulation to preempt FDA monograph compliance disruption. For New Entrants and Emerging Players: Telehealth platform integration gaps in urgent care settings offer white-space entry points for palatable pediatric formulation specialists. Target home care segments with saline-based nasal spray alternatives bypassing cardiovascular safety concerns. Pursue contract manufacturing partnerships with India's PLI scheme beneficiaries to secure API supply diversification. For Investors and Strategic Acquirers: Mid-sized generic manufacturers with backward integration into Indian API production corridors present consolidation targets with margin expansion potential. Long-term viability hinges on antimicrobial stewardship protocol adaptation and biologics pipeline optionality. Watch FDA monograph reform timing as inflection indicator for decongestant portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Phenylephrine-Free Reformulation | FDA monograph compliance secures OTC approval pathway for decongestant portfolios. |
| Sterile Nasal Spray Facility Certification | GMP validation cycles create 18-24 month competitive moats in aqueous pump production. |
| Direct-to-Consumer Channel Expansion | Telehealth platform partnerships bypass physician gatekeeping for symptomatic relief products. |
| Biologics Development for Severe Pharyngitis | Monoclonal antibody programs target hospital-administered cases distinct from commoditized antibiotics. |
| API Supply Diversification via India PLI | Production-linked incentive contracts attract fermentation capacity away from concentrated Asian zones. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO Essential Medicines List updates preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary fieldwork across North American, European, and Asian markets combined with secondary validation from customs trade data and pharmaceutical procurement databases. Bottom-up volume modeling and top-down market sizing triangulated segment-level outputs.
Variance decomposition across product type, therapy area, delivery mode, and end user dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic and epidemiological drivers. Modeled inputs incorporated pediatric viral circulation patterns, antimicrobial stewardship protocol adoption curves, and nasal spray formulation preference shifts among immunocompromised populations.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO jurisdictions; material policy shifts would require re-modeling volume trajectories across retail and institutional channels. Specific risks include phenylephrine efficacy reclassification, API import restriction tightening, and biologics reimbursement compression. Recalibration cycles align with material shifts in monograph reform timing and stewardship protocol implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Emphysema Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Lung Injury Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Lung Management Products Market