
 Global Chronic Obstructive Pulmonary Disease Market | 2026-2036
Global Chronic Obstructive Pulmonary Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chronic Obstructive Pulmonary Disease Market Foresight
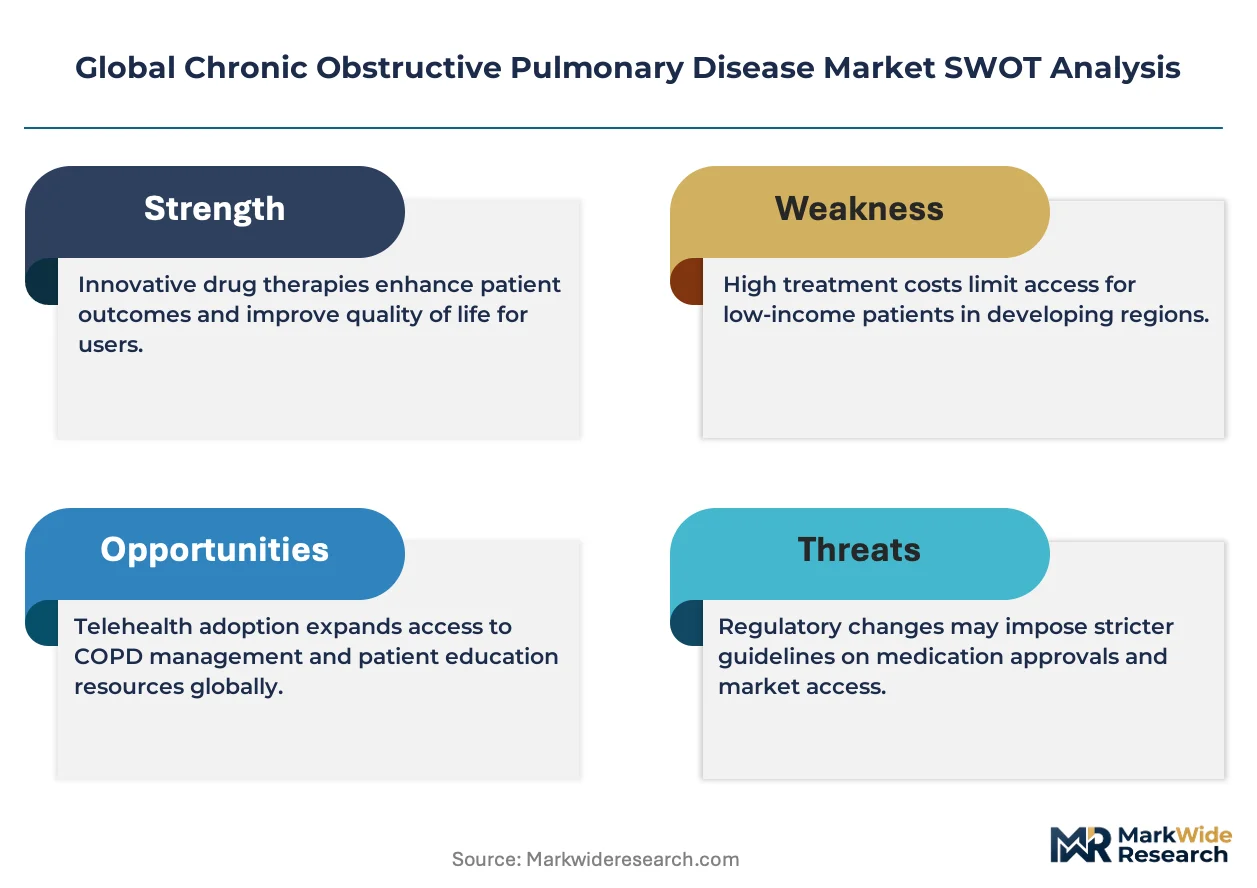
FDA bioequivalence guidance for orally inhaled drug products is hardening the cost-of-entry calculus for new entrants. GlaxoSmithKline plc leverages its vertically integrated respiratory manufacturing network to sustain supply security across multiple continents. Boehringer Ingelheim GmbH anchors its position through deep specialization in long-acting muscarinic antagonist formulations. AstraZeneca plc differentiates via biologics development targeting eosinophilic COPD phenotypes.
Chronic obstructive pulmonary disease comprises persistent respiratory airflow limitation driven by chronic bronchitis, emphysema, or mixed pathology, measured clinically through forced expiratory volume in one second below 70% of predicted values. The condition demands continuous pharmacological management to reduce exacerbation frequency and slow functional decline. Combination inhalers dominate current prescribing patterns due to superior adherence profiles versus separate bronchodilator and corticosteroid devices. Home healthcare delivery modes represent the fastest-expanding structural channel as payors shift reimbursement toward outpatient chronic disease management. Hospitals retain the deepest margin pools through acute exacerbation episodes requiring nebulized therapies and oxygen escalation.
FDA, EMA, and Japan's PMDA collectively enforce evolving standards for inhaler device interoperability, environmental impact of propellants, and real-world evidence requirements for label expansion. These frameworks shape R&D prioritization, manufacturing location decisions, and geographic launch sequencing for portfolio managers. Stakeholders must monitor propellant transition timelines and device recycling mandates as these forces will determine competitive viability in regulated markets.
Market Dynamics
Home healthcare infrastructure expansion is compressing acute-care admission rates while FDA bioequivalence standards for inhalers are filtering generic manufacturer participation. These twin pressures are restructuring competitive entry economics and channel economics simultaneously.
Growth Catalysts
- Japan's PMDA streamlined approval pathways:Accelerated review timelines for combination bronchodilator therapies are shortening commercialization cycles for device-inhalant pairings.
- Elderly homebound populations:Medicare Advantage and comparable European reimbursement structures are expanding remote monitoring and nebulizer delivery coverage for mobility-limited patients.
- Long-acting muscarinic antagonist formulations:Once-daily dosing protocols are improving adherence metrics versus short-acting rescue inhalers in real-world registry data.
Market Restraints
- Propellant transition costs:Hydrofluoroalkane reformulation mandates under EU F-Gas Regulation are forcing manufacturing line retooling for metered-dose inhaler producers.
- Device interoperability failures:Misalignment between EMA and FDA standards for dose counter accuracy is duplicating validation expenses for cross-Atlantic submissions.
- Specialist pulmonologist concentration:Rural and exurban United States regions face diagnostic capacity gaps that delay COPD identification and treatment initiation.
Strategic Opportunities
- Germany's DiGA fast-track:Digital health application reimbursement for remote spirometry monitoring is creating software-enabled service revenue streams alongside hardware sales.
- Biologics for eosinophilic phenotypes:Anti-interleukin-5 and anti-interleukin-4/13 pathways are opening addressable patient segments previously managed with bronchodilators alone.
- Closed-loop oxygen delivery:Integration of pulse oximetry with portable concentrators is enabling subscription-based respiratory management models in Japanese home healthcare markets.
Industry Challenges
- Inhaler device engineering talent scarcity:Cross-functional expertise spanning fluid dynamics, plastics molding, and human factors design commands premium compensation in Boston and Basel clusters.
- Real-world evidence collection infrastructure:Post-market surveillance requirements for label expansion demand investment in registry partnerships and data interoperability with electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chronic Obstructive Pulmonary Disease Market |
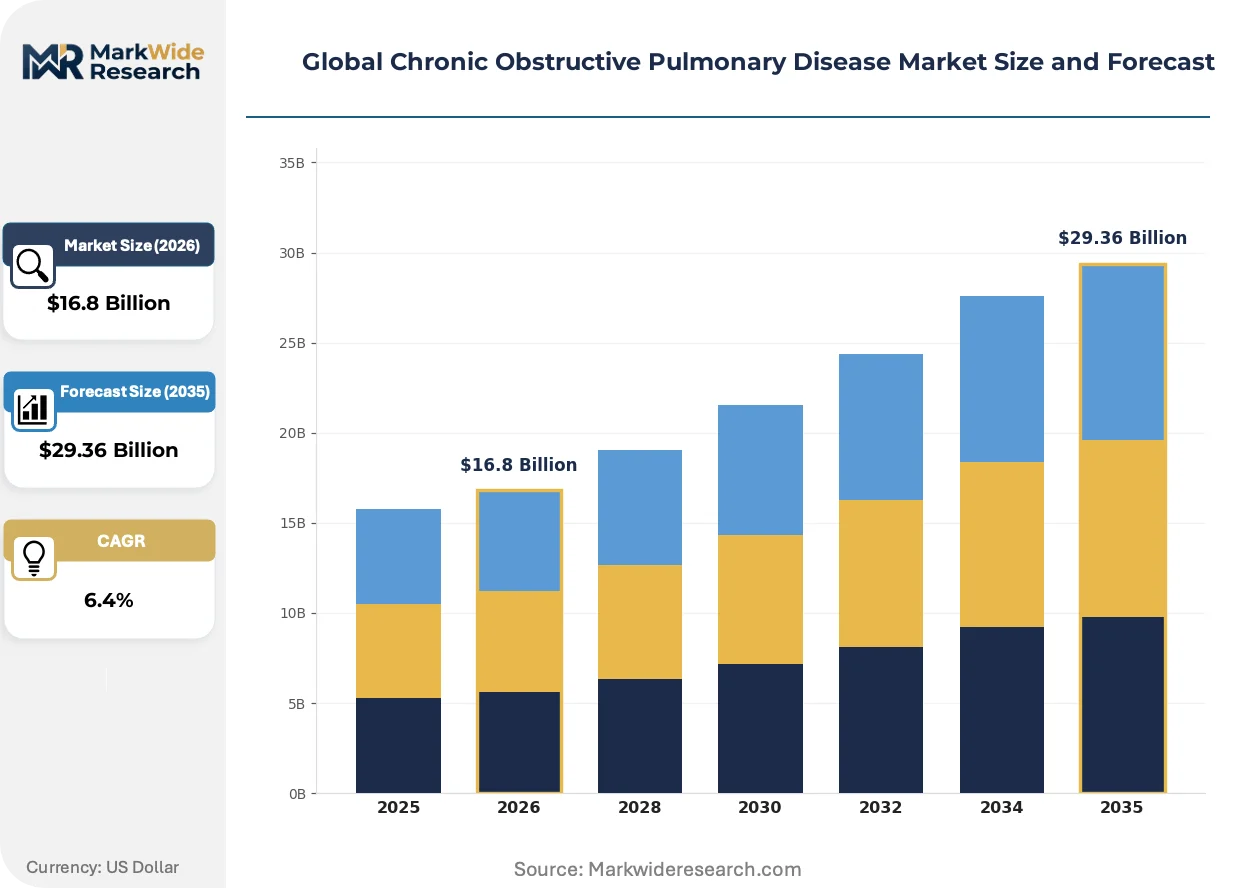
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Phosphodiesterase-4 Inhibitors, Combination Inhalers, Mucolytics Therapy Area: Acute Exacerbation, Stable COPD, Chronic Bronchitis, Emphysema, Mixed COPD-Asthma Care Setting: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers, Long-Term Care Facilities Delivery Mode: Inhalers, Nebulizers, Oral Medications, Injectable Therapies, Transdermal Patches |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca plc, Boehringer Ingelheim GmbH, Novartis AG, Teva Pharmaceutical Industries Ltd, Pfizer Inc., Sanofi, Chiesi Farmaceutici S.p.A., Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chronic Obstructive Pulmonary Disease Market Shifts & Advancements
Connected inhaler technology is generating granular adherence datasets that reshape contracting between manufacturers and pharmacy benefit managers. This data layer is becoming a distinct competitive battleground separate from molecule efficacy.
Smart inhaler platforms with embedded sensors and Bluetooth connectivity are absorbing patient behavior data streams that previously required clinical trial capture. Pulmonology practices in the United States and Netherlands are deploying these devices to identify suboptimal technique patterns. The resulting feedback loops are compressing the interval between observed non-adherence and intervention deployment.
EPA and FDA coordinated scrutiny of inhaler propellant environmental impact is accelerating hydrofluoroalkane phase-down timelines. Manufacturers with captive propellant chemistry capabilities are securing supply continuity while competitors face raw material sourcing constraints. Dry powder inhaler categories are capturing share in markets where propellant transition costs weigh heaviest on portfolio economics.
Hospital-at-home reimbursement expansion is displacing traditional skilled nursing facility placements for post-exacerbation COPD patients. United States Medicare and comparable German statutory health insurance frameworks are reimbursing remote patient monitoring bundles that include nebulizers and pulse oximeters. Pulmonology groups in Texas and Bavaria are restructuring around these episodes rather than facility-based revenue models.
Global Chronic Obstructive Pulmonary Disease Market Segmentation
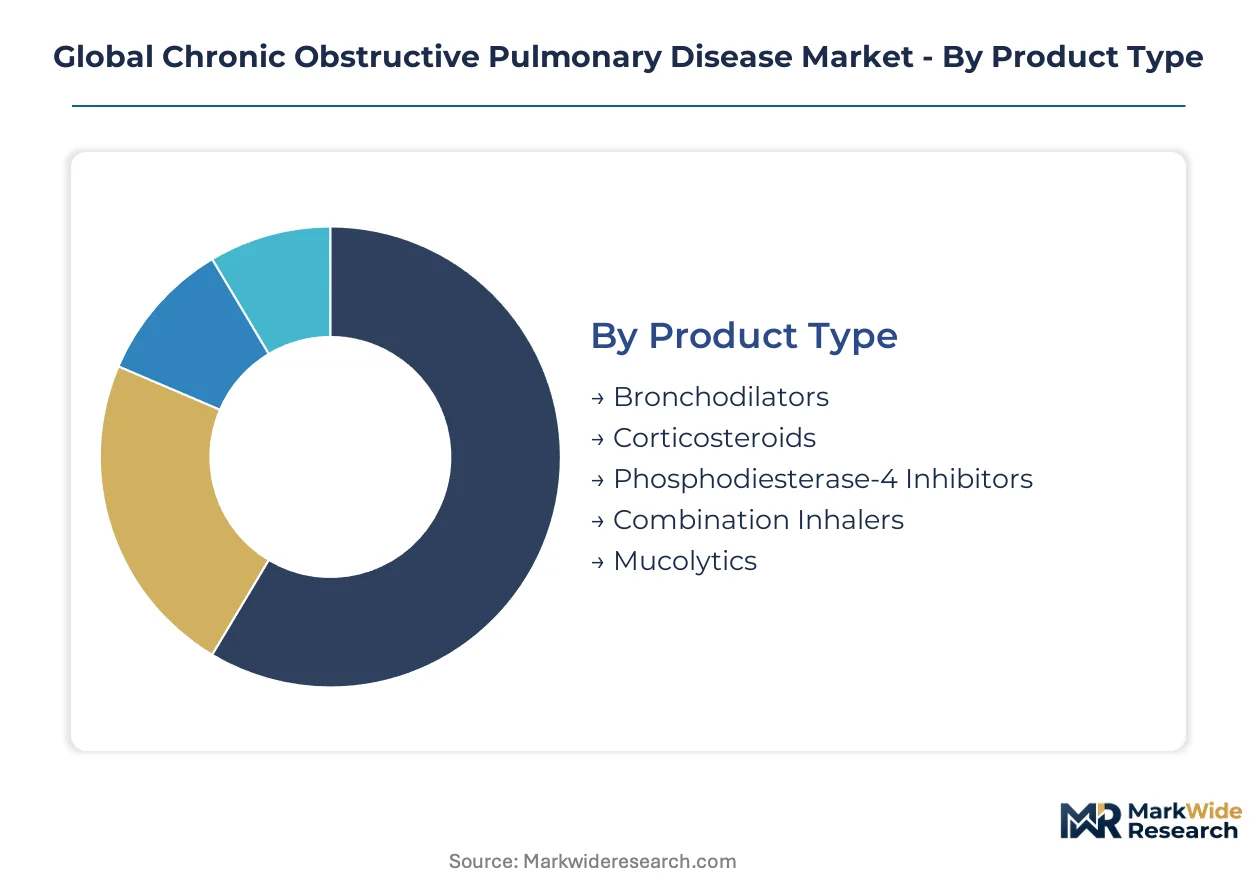
Segmentation in the COPD market reveals distinct purchasing logics across pharmacological categories, care venues, and delivery technologies. Manufacturers must align portfolio investments with where reimbursement concentration and clinical workflow priorities intersect.
Product Type:
Cost tier differentiation separates chronic maintenance prescriptions from rescue medications and acute interventions.
- Combination Inhalers:Fixed-dose combinations of long-acting beta-agonists with corticosteroids or muscarinic antagonists reduce device burden and improve adherence metrics in elderly populations. Medicare Part D and German statutory insurance reimbursement favor these formulations for moderate-to-severe disease stages, compressing market share for separate component prescribing.
- Bronchodilators:Short-acting beta-agonists and anticholinergics provide rescue relief during acute symptom episodes. Demand concentrates in United States emergency departments and Japanese primary care clinics where rapid onset protocols dominate acute management pathways.
- Corticosteroids:Inhaled and oral formulations suppress airway inflammation in frequent exacerbator phenotypes.
- Phosphodiesterase-4 Inhibitors:Oral roflumilast targets chronic bronchitis-dominant patients with frequent exacerbations despite bronchodilator therapy.
- Mucolytics:Agents like carbocysteine reduce sputum viscosity in productive cough phenotypes prevalent in East Asian prescribing patterns.
Combination inhalers lead volumes today; phosphodiesterase-4 inhibitors are gaining share fastest in severe chronic bronchitis segments.
Therapy Area:
Application severity determines pricing power and regimen complexity across the disease continuum.
- Stable COPD:Maintenance bronchodilation with scheduled long-acting formulations defines this largest-addressable population. Japanese and German payors reimburse preventive regimens most generously, while United States commercial plans impose prior authorization hurdles for biologic escalation.
- Acute Exacerbation:Systemic corticosteroids, nebulized bronchodilators, and oxygen escalation characterize hospital-presenting episodes. Revenue concentrates in United States hospital systems and German acute-care networks where bundled payment models incentivize rapid stabilization.
- Chronic Bronchitis:Productive cough-predominant phenotypes drive mucolytic and phosphodiesterase-4 inhibitor demand.
- Emphysema:Parenchymal destruction-predominant pathology favors bronchodilator-heavy regimens with lung volume reduction surgical referrals.
- Mixed COPD-Asthma:Overlapping inflammatory mechanisms justify corticosteroid-bronchodilator combinations with eosinophil-guided biologic add-ons.
Stable COPD commands the largest prescription volumes; acute exacerbation therapies generate the steepest per-patient revenue.
Care Setting:
Channel economics diverge sharply between institutional reimbursement and emerging home-based models.
- Home Healthcare:Remote monitoring, nebulizer delivery, and portable oxygen concentrators are expanding fastest among Medicare Advantage and German DiGA reimbursement frameworks. Texas and Bavaria pulmonology practices are restructuring revenue models around these episodes.
- Hospitals:Acute exacerbation management retains the deepest margin pools through nebulized therapies, oxygen escalation, and intensive care step-down. United States health systems and Japanese university hospitals anchor this high-acuity segment.
- Clinics:Outpatient pulmonology and primary care sites initiate and titrate maintenance therapy.
- Rehabilitation Centers:Post-acute pulmonary rehabilitation programs incorporate bronchodilator optimization and exercise training.
- Long-Term Care Facilities:Nursing home populations with limited mobility drive nebulizer and adherence packaging demand.
Hospitals lead absolute spending today; home healthcare is expanding most quickly as payors shift reimbursement toward outpatient chronic disease management.
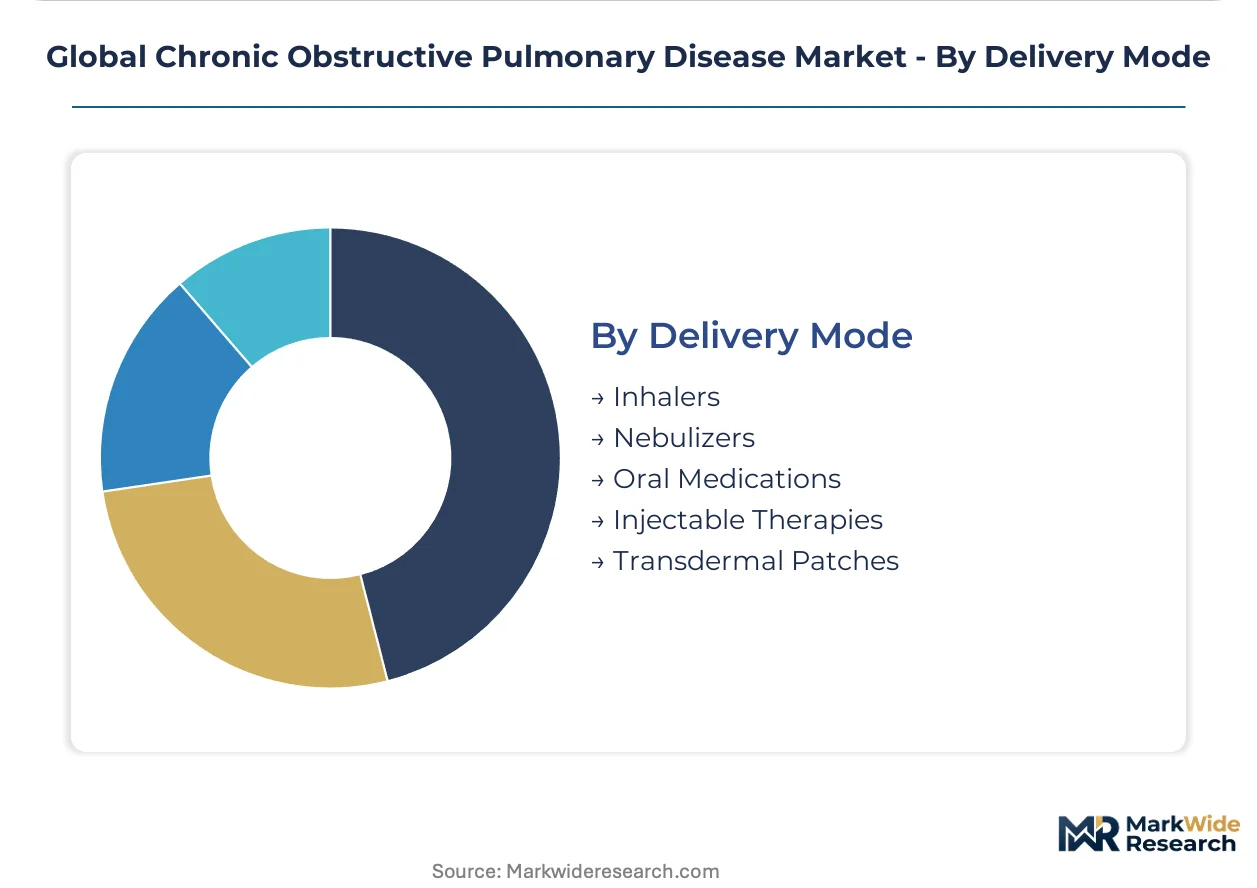
Delivery Mode:
Device technology maturity and patient dexterity requirements shape competitive positioning.
- Inhalers:Metered-dose and dry powder devices dominate maintenance prescribing. FDA bioequivalence standards and EU F-Gas propellant regulations are elevating manufacturing complexity, favoring incumbents with captive chemistry capabilities.
- Nebulizers:Jet and mesh nebulizers serve pediatric, geriatric, and severely dyspneic patients unable to coordinate breath-actuated devices. Japanese home healthcare markets and United States long-term care facilities are absorbing connected nebulizer platforms with adherence monitoring.
- Oral Medications:Tablets and capsules address phosphodiesterase-4 and mucolytic categories where inhalation is impractical.
- Injectable Therapies:Subcutaneous biologics target eosinophilic phenotypes with anti-interleukin pathways.
- Transdermal Patches:Emerging nicotine cessation adjuncts and experimental bronchodilator delivery formats.
Inhalers lead prescription volumes today; nebulizers are climbing the fastest in home healthcare channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulmonology specialist density and respiratory device engineering talent clusters determine regional competitive positioning. Germany's precision manufacturing workforce and Japan's geriatric care infrastructure anchor device innovation. United States reimbursement scale and United Kingdom biotech translation capacity shape pharmaceutical development cycles.
United States
Medicare Advantage expansion and hospital-at-home reimbursement bundles are accelerating nebulizer and remote monitoring deployment among elderly homebound populations. FDA tightened bioequivalence standards for orally inhaled products are elevating generic manufacturer entry costs. Texas pulmonology practices are restructuring revenue models around outpatient chronic disease management episodes rather than facility-based care.
Germany
Statutory health insurance frameworks reimburse preventive bronchodilator regimens generously while DiGA fast-track pathways enable digital health application reimbursement for remote spirometry monitoring. EU F-Gas Regulation mandates hydrofluoroalkane propellant reformulation, forcing metered-dose inhaler manufacturing line retooling. Bavaria anchors connected nebulizer platform adoption within hospital-at-home networks serving post-exacerbation patients.
Japan
PMDA streamlined approval pathways for combination bronchodilator therapies are shortening commercialization cycles for device-inhalant pairings. METI-supported home healthcare infrastructure expansion is compressing acute-care admission rates among mobility-limited elderly. Kanto region university hospitals anchor high-acuity segment revenue through nebulized therapies and oxygen escalation during exacerbation episodes.
United Kingdom
NHS long-term plan commitments to respiratory disease reduction are expanding community-based spirometry screening and maintenance therapy initiation. MHRA alignment with EMA standards for dose counter accuracy is duplicating validation expenses for cross-Atlantic submissions. Greater London biotech translation clusters are advancing biologics development targeting eosinophilic COPD phenotypes previously managed with bronchodilators alone.
China
NMPA accelerated review pathways for innovative respiratory devices are shortening registration timelines for smart inhaler platforms with embedded sensors. Dual carbon goals and environmental ministry scrutiny of inhaler propellant impact are accelerating hydrofluoroalkane phase-down timelines. Yangtze River Delta manufacturing hubs are capturing dry powder inhaler category share as propellant transition costs weigh on metered-dose portfolio economics.
Global Chronic Obstructive Pulmonary Disease Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the COPD therapeutic landscape. The market structure consolidates around incumbent pharmaceutical manufacturers with captive respiratory device capabilities and vertically integrated supply chains. Three archetypes dominate: vertically integrated respiratory specialists with in-house propellant chemistry, biologics developers targeting eosinophilic phenotypes, and generic manufacturers navigating hardened FDA bioequivalence standards. Competitive moves concentrate on strategic partnerships for real-world evidence collection and manufacturing line retooling for environmental compliance.
Within the vertically integrated specialist tier, GlaxoSmithKline plc and Boehringer Ingelheim GmbH occupy positions sustained by manufacturing network control across multiple continents. AstraZeneca plc exemplifies the biologics-focused archetype through eosinophil-guided therapeutic development. These three entities anchor competitive dynamics as regulatory standards harden and home healthcare channel expansion restructures reimbursement flows.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Boehringer Ingelheim GmbH |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc. |
| Sanofi |
| Chiesi Farmaceutici S.p.A. |
| Viatris Inc. |
| Others |
Supply & Pricing Matrix
Captive propellant chemistry capabilities anchor both supply security and pricing power for metered-dose inhaler manufacturers facing EU F-Gas Regulation mandates. Manufacturers with in-house hydrofluoroalkane production in Germany and the United States command premium positioning against competitors forced into spot-market sourcing or dry powder platform pivots.
Pricing Analysis
Bundled remote monitoring and nebulizer subscription services separate premium positioning from unbundled device-only transactions in home healthcare channels. Three-tier pricing structure across premium, standard, and economy levels tracks device connectivity, clinical support intensity, and propellant chemistry ownership. Pricing pressure stems from Medicare Advantage reimbursement compression in United States outpatient settings. Hospital systems exhibit lowest price sensitivity due to bundled payment insulation, while long-term care facilities face acute margin constraints.
Supply Chain Analysis
Direct-to-hospital procurement channels handle acute exacerbation demand, while specialty pharmacy and home medical equipment distributors serve maintenance therapy populations. Manufacturing concentrates in Germany, Switzerland, and the United States for precision device assembly, with active pharmaceutical ingredient synthesis anchored in India and China. Hydrofluoroalkane propellant supply rests on limited chemical producers in Belgium and the United States. Single-source vulnerability in propellant chemistry creates exposure to EU environmental regulatory acceleration. Distribution runs through GPO-negotiated contracts for United States hospital systems and statutory insurance tenders for German outpatient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Japan's PMDA accelerated review timelines and the United States FDA bioequivalence burden creates differential cost-of-entry economics for combination device developers. Manufacturers can sequence launches to exploit regulatory speed in Tokyo while accumulating real-world evidence for Washington submissions.
For Market Incumbents: To counter generic manufacturer cost advantages under hardened FDA standards, deepen captive propellant production in Basel and Boston corridor facilities. Secure GPO contract renewals with embedded remote monitoring data-sharing clauses to raise switching costs for United States hospital systems. For New Entrants and Emerging Players: Smart inhaler sensor platforms with Bluetooth adherence tracking offer technology-first wedge into Japanese home healthcare reimbursement expansion. Target Germany's DiGA fast-track for software-enabled spirometry services alongside hardware partnerships. Pursue white-label manufacturing arrangements with established device engineering houses to bypass talent scarcity in fluid dynamics and human factors design. For Investors and Strategic Acquirers: Roll-up economics work for connected respiratory device platforms because fragmented regional reimbursement pathways favor consolidated data infrastructure spanning multiple payor contracts. Target mid-cap specialists with FDA-cleared devices and underexploited European CE marking pathways. Watch PMDA approval velocity relative to FDA timelines as signal for geographic launch sequencing arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Chemistry Backward Integration | In-house HFA production insulates against EU F-Gas supply disruption and secures MDI manufacturing continuity. |
| Connected Inhaler FDA Submission | Embedded sensor platforms generate adherence datasets that reshape PBM contracting leverage and reimbursement positioning. |
| DiGA Fast-Track Reimbursement Strategy | Remote spirometry software qualification in Germany enables subscription revenue streams alongside hardware sales. |
| Biologics Pipeline Diversification | Anti-interleukin pathways for eosinophilic phenotypes open addressable segments beyond bronchodilator-managed populations. |
| Hospital-at-Home Partnership Development | Medicare Advantage bundled episode restructuring in Texas and Bavaria displaces traditional skilled nursing facility placements. |
Research Methodology
Bottom-up patient population modeling reconciled against top-down prescription volume tracking forms the analytical core. Primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists informed demand-side assumptions. Secondary validation drew from FDA 510(k) filings, EMA regulatory submissions, Medicare Part D claims databases, and Japanese Ministry of Health reimbursement bulletins. Cross-referencing manufacturer shipment data against national prescription audits enabled volume reconciliation across geographic markets.
Input-output matrices mapped therapy area severity, delivery mode technology maturity, and care setting reimbursement intensity to project segment-level trajectories across the analysis window. Modeled dimensions encompassed pharmacological category, device connectivity tier, patient mobility status, and regional regulatory cluster. CAGRs derived from patient epidemiology trends, payor coverage expansion schedules, and propellant transition timeline assumptions. Forecast inputs incorporated PMDA review velocity differentials and EU F-Gas phase-down regulatory schedules.
The model holds under stable reimbursement frameworks and propellant supply continuity; deviation in FDA bioequivalence standard enforcement or hydrofluoroalkane raw material disruption would shift competitive entry economics and geographic launch sequencing. Forecasts reflect documented assumptions regarding patient adherence improvement from connected device deployment and hospital-at-home reimbursement expansion velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Emphysema Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market