
 GCC Industrial Air Filtration Market | 2026-2036
GCC Industrial Air Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Industrial Air Filtration Market Foresight
Saudi Arabia's updated National Ambient Air Quality Standards is decoupling filtration procurement from pure capital-expenditure cycles and tying it to compliance deadlines. Donaldson Company leverages its regional distribution network to sustain aftermarket revenue streams across cement and petrochemical installations. Camfil Group anchors premium HEPA and molecular filtration through localized assembly capabilities in the UAE.
Industrial air filtration encompasses engineered systems designed to remove particulate matter, gaseous contaminants, and aerosols from process and ambient air streams, typically achieving capture efficiencies from MERV 11 through HEPA H14 grades depending on fiber density and pleat geometry. These systems protect rotating equipment, ensure product integrity in cleanroom environments, and enable regulatory discharge compliance across heavy process industries. HEPA filters command disproportionate margin pools due to pharmaceutical and electronics cleanroom specifications, while bag filters dominate volumetric demand in cement manufacturing and metal processing where high dust loading occurs. Activated carbon filters are gaining share in chemical processing and petrochemical facilities confronting volatile organic compound regulations.
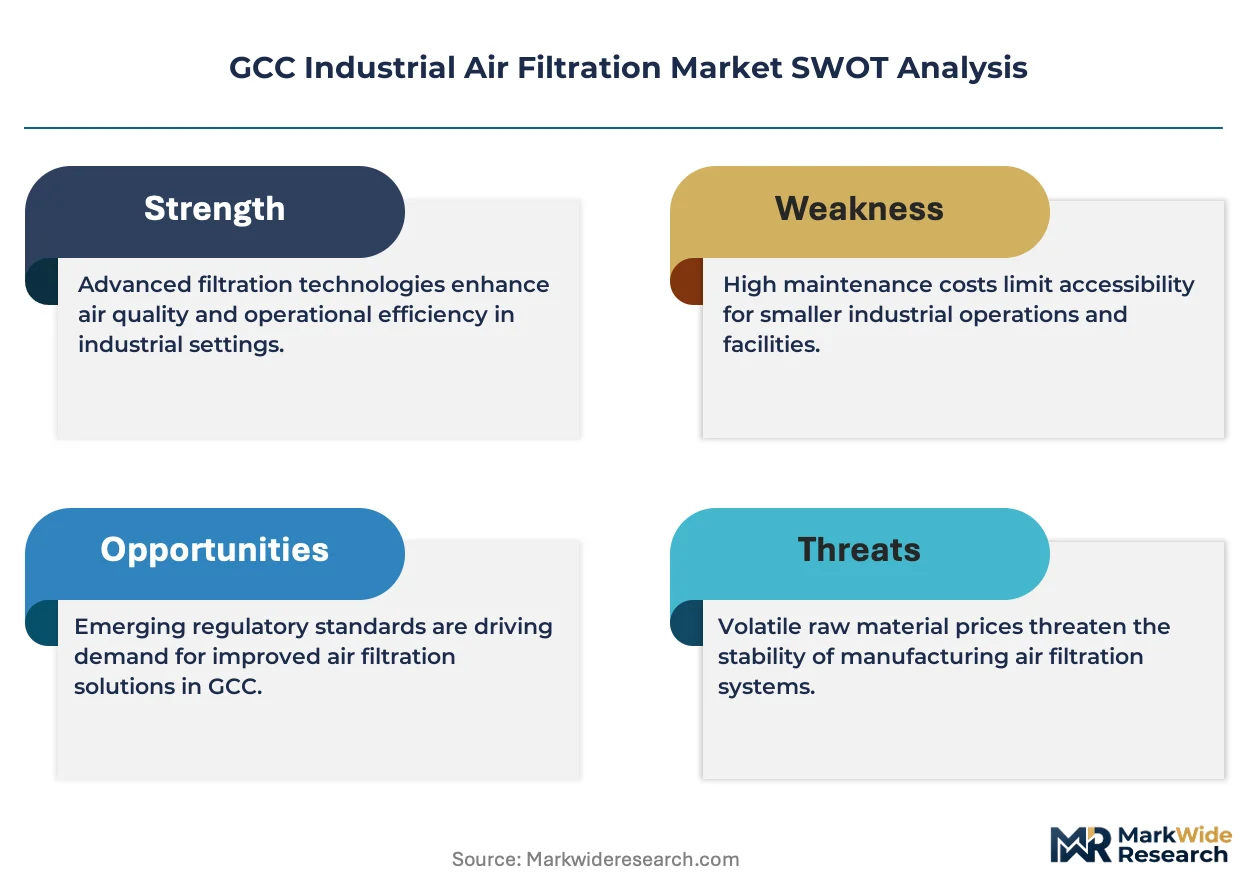
The UAE's Ministry of Climate Change and Environment, Saudi Arabia's General Authority for Meteorology and Environmental Protection, and Kuwait's Environmental Public Authority collectively enforce escalating particulate and VOC discharge limits that mandate continuous monitoring and documented maintenance intervals. These frameworks effectively mandate predictive filter-replacement schedules rather than failure-based maintenance, embedding recurring revenue into equipment procurement decisions. Stakeholders must weigh the trade-off between higher-efficiency media with extended changeout intervals against standard products with lower unit costs but more frequent service requirements.
Market Dynamics
Saudi Arabia's General Authority for Meteorology and Environmental Protection has decoupled filtration procurement from pure capital-expenditure cycles, tying equipment replacement to hard compliance deadlines rather than failure-based maintenance schedules.
Growth Catalysts
- Eastern Province Petrochemical Corridor:Saudi Aramco's downstream expansion is generating concentrated demand for high-capacity baghouse systems and molecular filtration units across cracking and polymerization facilities.
- UAE National Air Quality Strategy:Stricter industrial emissions protocols are accelerating replacement cycles for aging electrostatic precipitators in cement and aluminum smelting operations.
- HEPA Media Localization:Domestic assembly capabilities in Dubai and Jeddah are reducing lead times for pharmaceutical cleanroom specifications, cutting procurement cycles from sixteen weeks to under eight.
Market Restraints
- Specialized Media Import Dependency:Microglass HEPA media and activated carbon substrates remain concentrated among European and East Asian suppliers, exposing buyers to freight cost volatility and currency fluctuation.
- Technical Limitation in High-Temperature Applications:Standard synthetic filter media degrade above 120°C, forcing petrochemical operators toward costly ceramic or sintered metal alternatives for catalytic reformer vents.
- Regulatory Friction from Divergent Standards:Kuwait's Environmental Public Authority maintains particulate limits that differ from Saudi and UAE frameworks, complicating multi-country operator standardization.
Strategic Opportunities
- Qatar's North Field Expansion:LNG train construction is creating demand for offshore platform air handling systems with corrosion-resistant filtration specifications.
- Predictive Maintenance Integration:Differential pressure sensors linked to facility SCADA systems enable condition-based filter replacement, opening recurring service revenue streams.
- Bahrain's Aluminum Sector:Alba Line 6 expansion and downstream metal processing investments are driving demand for fume collection systems with fluorine-specific scrubbing media.
Industry Challenges
- Certification Timeline Compression:Saudi Food and Drug Authority GMP inspections for pharmaceutical facilities now mandate documented filter integrity testing protocols that extend commissioning schedules.
- Integration Complexity with Legacy Infrastructure:Retrofitting baghouse systems into 1980s-era cement kilns requires custom ductwork fabrication and structural reinforcement that strains maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Industrial Air Filtration Market |
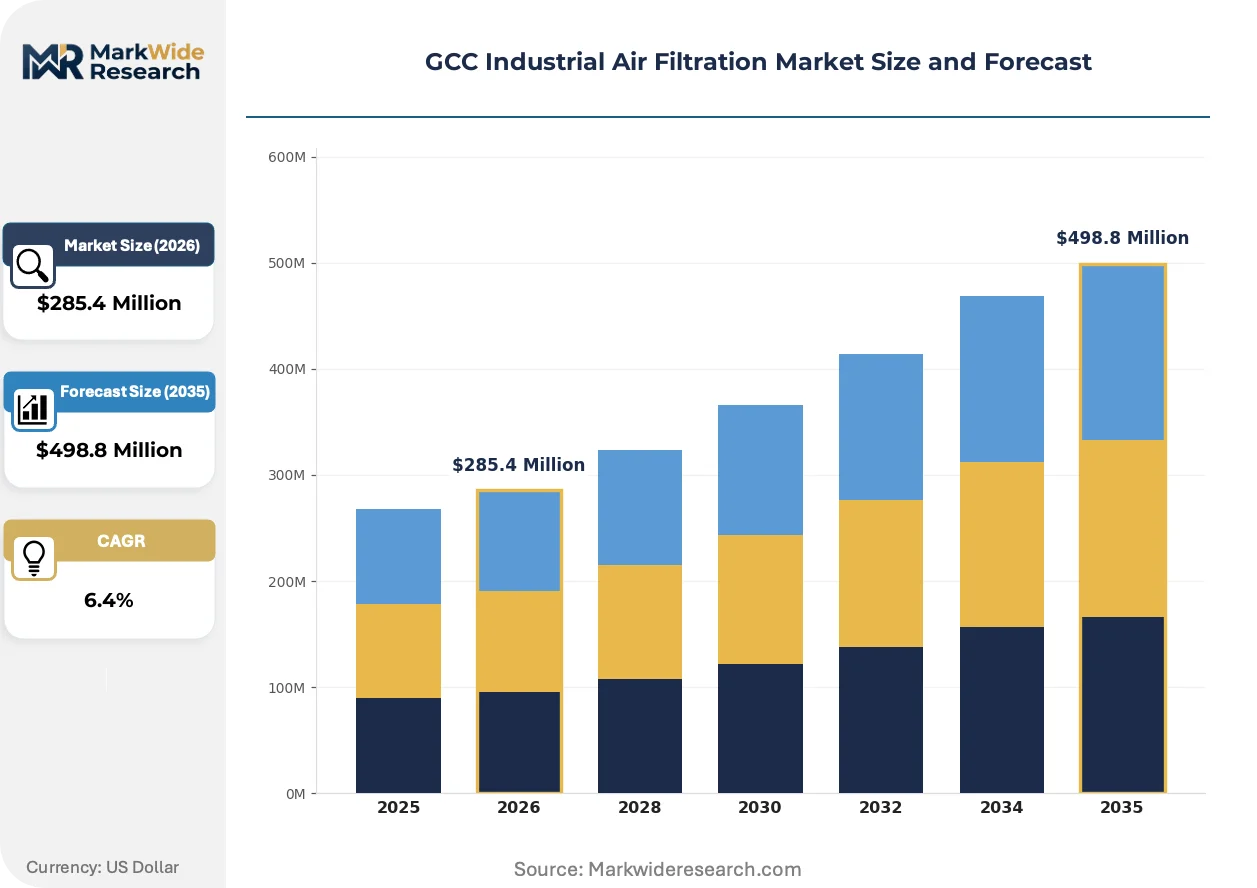
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $498.8 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bag Filters, HEPA Filters, Electrostatic Precipitators, Activated Carbon Filters, Pleated Filters, Panel Filters Technology: Mechanical Filtration, Electrostatic Filtration, UV Purification, Ionization Technology, Photocatalytic Oxidation, Ozone Generation Application: Metal Processing, Pharmaceutical Manufacturing, Food & Beverage Production, Chemical Processing, Cement Manufacturing, Electronics Assembly End User: Manufacturing Plants, Chemical Plants, Electronics Facilities, Food Processing Units, Cement Factories, Pharmaceutical Facilities |
| Companies Covered | Donaldson Company, Inc, Camfil Group, Esta Extraction Technology, Intensive Filter Himenviro, Wam Group, Tama Aernova, Absolent Air Care Group, Hanza Environment Technology Factory, Filter Concept Pvt. Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Industrial Air Filtration Market Shifts & Advancements
Filtration media engineering and monitoring instrumentation are converging to transform equipment from passive consumables into active process control elements, compressing maintenance intervals while extending service life.
PTFE membrane media is overtaking traditional cellulose-synthetic blends in pulse-jet baghouse applications across cement and steel operations. Saudi cement producers are specifying these membranes for kiln raw mill circuits where moisture and temperature cycling degrade conventional media. The shift is compressing filter replacement intervals from eighteen months to thirty-six months while reducing compressed air consumption for pulse cleaning.
UAE Ministry of Climate Change and Environment enforcement of continuous emissions monitoring is mandating real-time filter performance verification. Facilities must now install permanent differential pressure transmitters and particulate opacity meters with data logging to regulatory servers. Pharmaceutical and electronics cleanroom operators in Dubai Industrial City are responding by specifying HEPA filters with built-in test ports and scan probe accommodations.
Service unbundling is fragmenting traditional equipment-procurement relationships. End-users in the petrochemical corridor are separating filter supply from installation and validation services, awarding maintenance contracts to third-party specialists rather than original equipment manufacturers. This pattern is most visible in Jubail Industrial City, where SABIC affiliates now source media from regional distributors while retaining separate service agreements for filter bank testing and certification.
GCC Industrial Air Filtration Market Segmentation
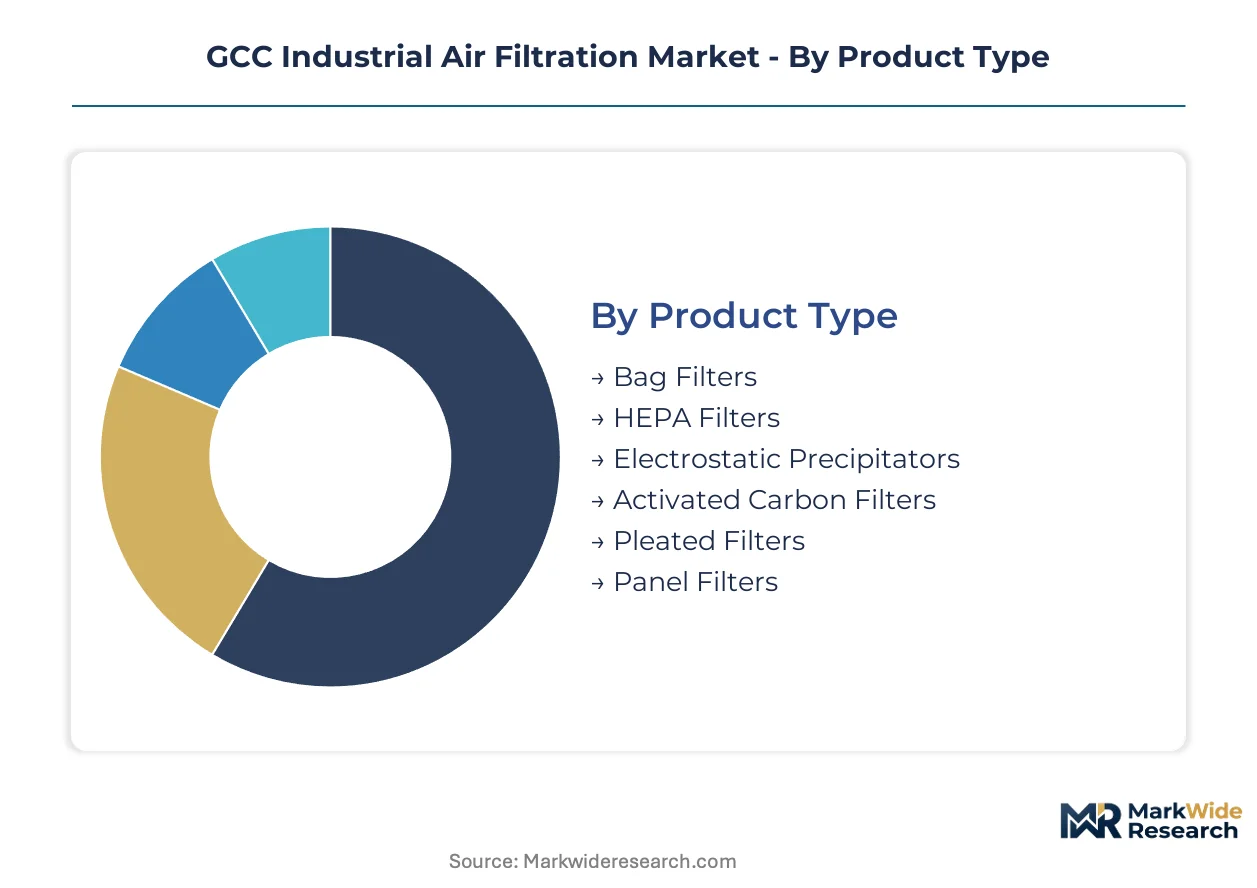
Industrial air filtration procurement in the GCC splits across performance tiers, with pharmaceutical cleanrooms demanding certified HEPA integrity while cement operations prioritize dust-loading capacity and service intervals. Segmentation reveals how regulatory pressure from Saudi Arabia's General Authority for Meteorology and Environmental Protection and the UAE's Ministry of Climate Change and Environment is fragmenting demand specifications across product categories and end-use verticals.
Product Type:
Customization intensity varies sharply across this category, with pharmaceutical-grade HEPA requiring documented test protocols while bag filters for cement kilns follow commodity procurement patterns.
- Bag Filters:Woven or felt fabric media configured in cylindrical sleeves for pulse-jet cleaning systems, typically achieving MERV 11-16 efficiency. Demand concentrates in Saudi Arabia's Eastern Province petrochemical corridor and UAE cement operations where high dust loading necessitates frequent replacement cycles and bulk procurement.
- HEPA Filters:Extended-surface microglass media with aluminum separators or pleated mini-pleat geometry, certified to EN 1822 or IEST-RP-CC001 for 99.97% efficiency at 0.3 microns. Pharmaceutical manufacturing facilities across Saudi Arabia are expanding filtration capacity to meet Saudi Food and Drug Authority GMP standards, compressing lead times through Dubai and Jeddah assembly operations.
- Electrostatic Precipitators:High-voltage ionization chambers with collection plates for sub-micron particulate removal in heavy process industries.
- Activated Carbon Filters:Impregnated carbon substrates for VOC and odor adsorption in chemical processing vents.
- Pleated Filters:Synthetic media with extended surface area for HVAC and general industrial applications.
- Panel Filters:Flat or V-bank configurations for pre-filtration and coarse dust removal.
Leading the category by volume: Bag Filters. Growing fastest: HEPA Filters.
Technology:
Cost-to-performance ratios separate mature mechanical methods from emerging electrochemical approaches still seeking validation in GCC regulatory frameworks.
- Mechanical Filtration:Physical barrier media including fibrous depth filters and surface membranes, representing the installed base across cement and metal processing. Saudi cement producers are specifying PTFE membrane media for kiln raw mill circuits, extending replacement intervals from eighteen to thirty-six months while reducing compressed air consumption.
- Electrostatic Filtration:Charged-media or ionizing systems for fine particulate capture without pressure-drop penalties. UAE cement and aluminum smelting operations are accelerating replacement cycles for aging electrostatic precipitators under stricter national air quality protocols.
- UV Purification:Germicidal irradiation for biological contamination control in pharmaceutical and food processing environments.
- Ionization Technology:Bipolar ion generation for airborne particle agglomeration in commercial and light industrial settings.
- Photocatalytic Oxidation:Titanium dioxide-coated substrates activated by UV for VOC decomposition.
- Ozone Generation:Controlled ozone production for odor neutralization in wastewater and chemical processing facilities.
Mechanical Filtration retains dominant share. Photocatalytic Oxidation is climbing the fastest on petrochemical VOC compliance requirements.
Application:
End-use maturity correlates with regulatory enforcement intensity, with pharmaceuticals and electronics facing continuous monitoring mandates while metal processing operates under less prescriptive frameworks.
- Metal Processing:Fume collection for welding, cutting, and smelting operations with high-temperature and spark-resistant specifications. Bahrain's Alba Line 6 expansion and downstream investments are driving demand for fluorine-specific scrubbing media in aluminum smelting operations.
- Pharmaceutical Manufacturing:Cleanroom environments requiring ISO 14644-1 compliance with HEPA terminal filtration and unidirectional airflow. Saudi Food and Drug Authority GMP inspections now mandate documented filter integrity testing protocols that extend commissioning schedules.
- Food & Beverage Production:Hygienic air handling for product contamination prevention and employee exposure control.
- Chemical Processing:Corrosive gas and vapor removal with chemically resistant media and containment housing.
- Cement Manufacturing:Kiln and raw mill dust collection with moisture-resistant and temperature-tolerant specifications.
- Electronics Assembly:Mini-environment and cleanroom filtration for semiconductor and display manufacturing.
Cement Manufacturing leads by installed base. Pharmaceutical Manufacturing is expanding most quickly on GMP compliance deadlines.
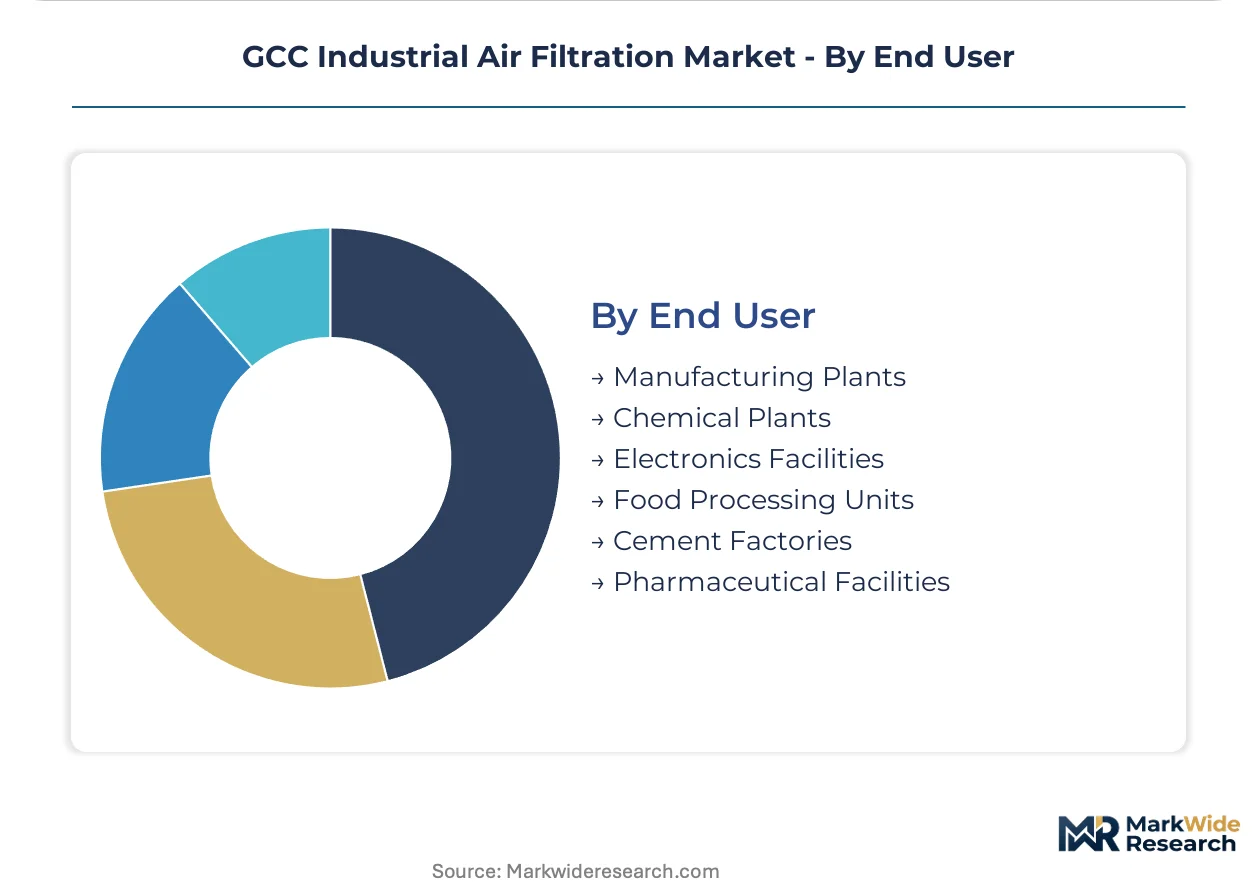
End User:
Customer scale determines procurement sophistication, with integrated petrochemical operators unbundling service contracts while smaller facilities rely on bundled equipment-and-maintenance agreements.
- Manufacturing Plants:Diverse industrial facilities spanning automotive, textiles, and general fabrication with varying contamination profiles.
- Chemical Plants:Process-intensive operations requiring corrosion-resistant materials and explosive atmosphere certifications.
- Electronics Facilities:Cleanroom and controlled environment operations with stringent particle count specifications.
- Food Processing Units:Hygiene-critical environments regulated by national food safety authorities across the GCC.
- Cement Factories:High-dust, high-temperature operations with continuous kiln running schedules dictating maintenance windows. Retrofitting baghouse systems into 1980s-era kilns requires custom ductwork fabrication and structural reinforcement that strains maintenance budgets.
- Pharmaceutical Facilities:GMP-regulated environments with validated filtration systems and documented change control procedures. End-users in Jubail Industrial City are separating filter supply from installation and validation services, awarding maintenance contracts to third-party specialists rather than original equipment manufacturers.
Cement Factories represent the largest volume segment. Pharmaceutical Facilities are gaining share fastest on regulatory compliance investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors filtration procurement volume across the GCC, with Saudi Aramco's downstream expansion generating concentrated demand for high-capacity baghouse systems and molecular filtration units. The Eastern Province petrochemical corridor concentrates upgrade cycles tied to compliance deadlines rather than traditional capital-expenditure schedules.
Saudi Arabia
The General Authority for Meteorology and Environmental Protection has decoupled equipment replacement from failure-based maintenance, mandating hard compliance deadlines for particulate discharge limits. Pharmaceutical manufacturing facilities in Riyadh and Jeddah are expanding HEPA filtration capacity to meet Saudi Food and Drug Authority GMP standards. Domestic assembly capabilities in Jeddah are cutting procurement lead times from sixteen weeks to under eight for cleanroom specifications.
United Arab Emirates
The Ministry of Climate Change and Environment enforces continuous emissions monitoring with real-time data logging to regulatory servers, accelerating replacement cycles for aging electrostatic precipitators in cement and aluminum smelting operations. Dubai Industrial City hosts pharmaceutical and electronics cleanroom operators specifying HEPA filters with built-in test ports. Localized assembly in Dubai reduces freight exposure for premium media.
Kuwait
The Environmental Public Authority maintains particulate limits that diverge from Saudi and UAE frameworks, complicating multi-country operator standardization and forcing customized procurement specifications. Petrochemical facilities in the Shuaiba Industrial Area confront technical limitations in high-temperature applications above 120°C, requiring costly ceramic or sintered metal alternatives for catalytic reformer vents. Import dependency for microglass HEPA media exposes buyers to freight cost volatility.
Qatar
The North Field Expansion is creating demand for offshore platform air handling systems with corrosion-resistant filtration specifications across LNG train construction. Ras Laffan Industrial City concentrates process-intensive operations requiring explosive atmosphere certifications for chemical plants. Service unbundling is fragmenting traditional equipment-procurement relationships, with operators separating filter supply from installation contracts.
Bahrain
The Alba Line 6 expansion and downstream metal processing investments are driving demand for fume collection systems with fluorine-specific scrubbing media across aluminum smelting operations. The Askar Industrial Area hosts metal processing facilities requiring spark-resistant specifications for welding and cutting operations. Predictive maintenance integration through differential pressure sensors linked to SCADA systems is opening recurring service revenue streams.
GCC Industrial Air Filtration Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade filtration, with HEPA integrity testing and documented validation protocols commanding price multiples over standard bag filters. The vendor base organizes into three strategic archetypes: multinational specialists with regional distribution networks, regional assemblers leveraging localized production, and commodity distributors competing on unit cost and inventory availability. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into predictive maintenance services.
Within the multinational specialist tier, Donaldson Company and Camfil Group exemplify contrasting approaches to regional positioning. Donaldson leverages its distribution infrastructure to sustain aftermarket revenue streams across cement and petrochemical installations. Camfil anchors premium HEPA and molecular filtration through localized assembly capabilities in the UAE, reducing lead times for pharmaceutical cleanroom specifications. Among European-originated fabricators, Esta Extraction Technology and Tama Aernova occupy positions tied to industrial ventilation and fume collection applications.
| Leading Market Players |
|---|
| Donaldson Company, Inc |
| Camfil Group |
| Esta Extraction Technology |
| Intensive Filter Himenviro |
| Wam Group |
| Tama Aernova |
| Absolent Air Care Group |
| Hanza Environment Technology Factory |
| Filter Concept Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Saudi Arabia's National Ambient Air Quality Standards gates qualified supply and premium-tier pricing access by mandating documented filter integrity testing protocols that only certified assemblers can fulfill. Pharmaceutical cleanroom specifications in Jeddah and Dubai command price multiples over standard bag filters for cement kilns, compressing procurement into validated supplier networks.
Pricing Analysis
Uptime guarantees anchor value-based pricing for HEPA filtration in pharmaceutical facilities, where unplanned downtime costs dwarf media replacement expenses. Three-tier pricing structure across premium, standard, and economy levels separates EN 1822-certified HEPA from commodity bag filters and pre-filtration panels. Cost compression in standard bag filters is intensifying because Saudi cement producers are consolidating procurement volumes and extending replacement intervals through PTFE membrane specifications. Cement factories exhibit highest price sensitivity due to bulk procurement patterns, while pharmaceutical facilities show lowest sensitivity given GMP compliance mandates.
Supply Chain Analysis
SFDA GMP certification and UAE Ministry of Climate Change and Environment registration requirements gate qualified supply, restricting premium HEPA assembly to Dubai and Jeddah facilities with documented validation capabilities. Microglass HEPA media draws from Germany, Japan, and the United States; activated carbon substrates source from Belgium and South Korea; PTFE membranes feed from Italy and the United States. Single-source vulnerability concentrates in microglass HEPA media where European suppliers dominate specialized fiber production. Distribution runs through regional distributors in Jubail Industrial City and Dubai Industrial City, with service unbundling fragmenting traditional equipment-procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into specialized media production represents the decisive vertical-integration race in this market, as domestic assembly capabilities without captive fiber supply remain exposed to freight cost volatility and currency fluctuation.
For Market Incumbents: Acquire specialized media production assets in microglass HEPA fiber and activated carbon substrate categories to reduce import dependency exposure. Cement and petrochemical procurement consolidation threatens distributor margins; defend by locking long-term service contracts with predictive maintenance integration through differential pressure sensor networks.
For New Entrants and Emerging Players: Direct-to-end-user digital channels bypass established distributor relationships in Jubail Industrial City and Ras Laffan Industrial City. Qatar's North Field Expansion and Bahrain's aluminum downstream investments represent the most penetrable white-space targets. Lead with condition-based filter replacement platforms linked to facility SCADA systems, unbundling supply from installation to capture recurring service revenue.
For Investors and Strategic Acquirers: Saudi Food and Drug Authority GMP inspection acceleration is the leading indicator that pharmaceutical filtration capacity will tighten faster than supply response. Over a multi-year horizon, vertically integrated assemblers with captive media supply and regional distribution infrastructure demonstrate superior margin resilience. Watch for differential pressure sensor mandate announcements from UAE and Saudi regulators as the signal for predictive maintenance platform valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Media Production | Captive microglass HEPA fiber supply insulates Saudi assemblers from European freight volatility. |
| Predictive Maintenance Platform Deployment | SCADA-linked differential pressure sensors open recurring revenue streams in Jubail petrochemical corridor. |
| Pharmaceutical Cleanroom Certification Expansion | SFDA GMP validation capabilities in Jeddah capture Saudi Arabia's fastest-expanding filtration segment. |
| PTFE Membrane Specification Conversion | Saudi cement producers extending replacement intervals from eighteen to thirty-six months reduce competitor attach rates. |
| Service Unbundling and Third-Party Validation | SABIC affiliates separating filter supply from installation contracts fragment traditional OEM relationships. |
Research Methodology
Trade flow databases, regulatory filing repositories, and industry association technical standards formed the secondary backbone of this analysis. Primary interviews with plant engineers at Saudi Aramco downstream facilities, procurement leads at SABIC affiliates, maintenance directors in UAE cement operations, and aftermarket service heads at regional distributors were combined with secondary validation. Bottom-up and top-down triangulation cross-checked facility-level procurement patterns against national emissions enforcement timelines.
Bottom-up modeling built from individual facility upgrade cycles and compliance deadlines, while top-down analysis tracked national regulatory enforcement intensity across the GCC. Segmentation dimensions modeled include product type tier, end-use vertical, technology category, and customer scale archetype. CAGRs were derived from regression analysis of historical replacement cycles against regulatory phase-in schedules, incorporating pharmaceutical GMP inspection queue data and cement capacity utilization rates as industry-specific inputs.
Inputs from Saudi General Authority for Meteorology and Environmental Protection, UAE Ministry of Climate Change and Environment, and Kuwait Environmental Public Authority were available through the study window; gaps in real-time facility-level procurement data introduce uncertainty bands around replacement cycle timing. Forecasts reflect assumptions regarding regulatory enforcement consistency and media import cost stability. A model refresh is warranted upon material change in Saudi pharmaceutical GMP inspection velocity or UAE continuous emissions monitoring mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
ePTFE Filter Film Market
Filters
Ceramic Filters Market
Filters
Industrial Filter Paper Market
Filters
Filter Bag Market
Filters
Anti-Microbial Filter Market
Filters
Residential Filters Market
Filters
Global Filtration and Contamination Control Market
Filters
Adsorbent Market
Filters
North America Gas Filtration Media Market
Filters
Filter Media Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Coolant Filtration Systems Market
Filters
Color Filter Glass Market
Filters
Global Filter Market
Filters
Filtration and Separation Market
Filters
Global High Temperature Filters Market