
 Fabric Filters Market | 2026-2036
Fabric Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Filters Market Analysis
Chinese non-woven fabric production is hardening as domestic suppliers scale melt-blown and needle-punch capacity for high-temperature filtration. Freudenberg Filtration Technologies leverages its R&D footprint in Germany to sustain premium membrane laminates for pharmaceutical cleanrooms. Donaldson Company anchors North American aftermarket demand through captive distribution networks serving power generation rebuild schedules. Ahlstrom-Munksjö Oyj differentiates via cellulose-synthetic blends that extend service intervals in cement kiln tail gas applications.
Fabric filters are porous textile media engineered from woven, non-woven, or fiberglass substrates with defined permeability ratings, typically measured in cubic feet per minute per square foot, designed to intercept particulate matter from industrial gas streams. Baghouse filter technology dominates capital expenditure flows due to mature engineering standards and retrofit compatibility across existing ductwork infrastructure. Non-woven fabrics represent the fastest-expanding product category as pulse-jet cleaning systems displace older shaker mechanisms in minerals processing. Liquid filtration applications in chemical processing command margin premiums where PTFE membrane composites resist corrosive solvent exposure.
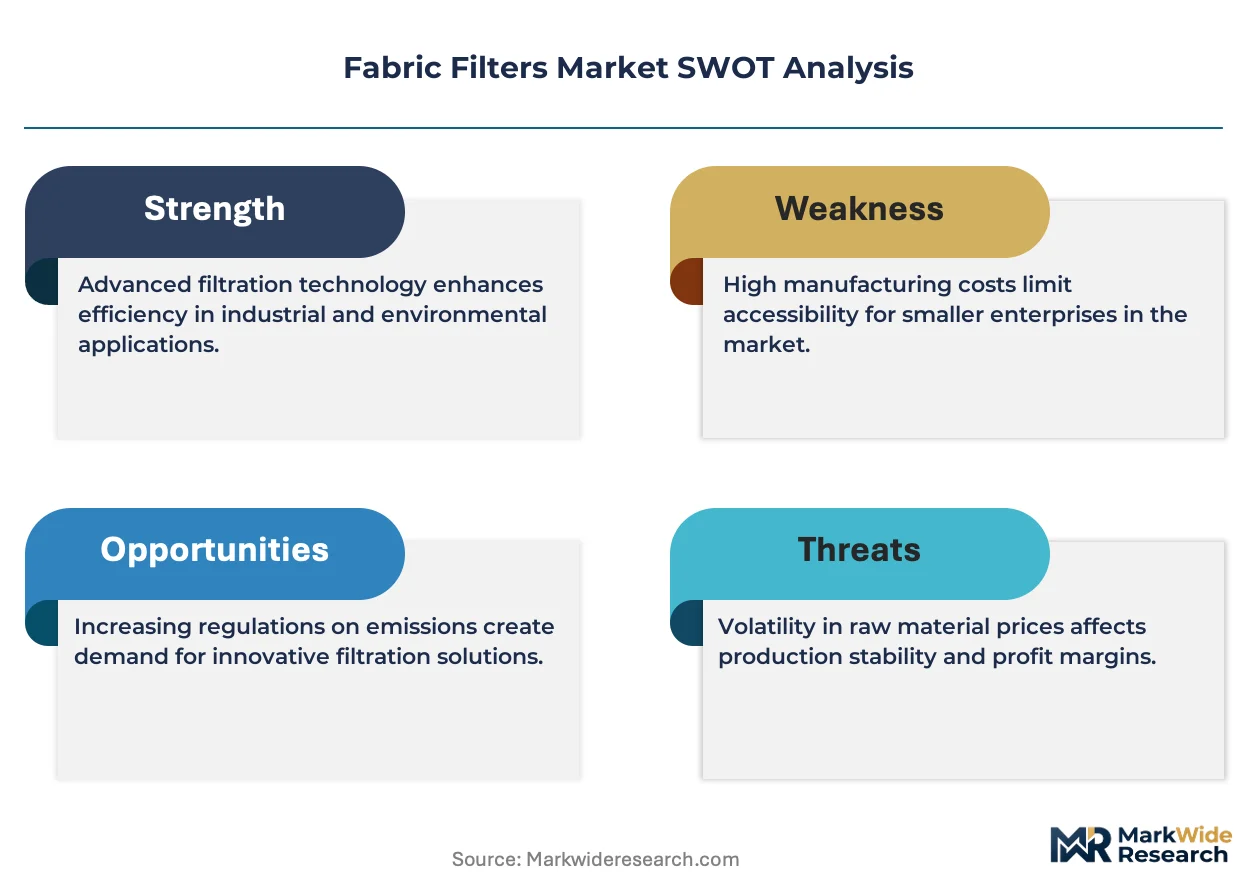
EPA Maximum Achievable Control Technology standards and EU F-Gas Regulation revisions compel cement and power generation operators to upgrade from woven glass bags to membrane-equipped non-woven configurations. China's Ministry of Ecology and Environment enforces ultra-low emission thresholds for coal-fired boilers that filter suppliers must certify against under GB standards. Stakeholders should monitor regulatory calibration cycles in India and Brazil where notification lags create procurement timing arbitrage for filter system integrators.
Market Dynamics
Baghouse filter technology is consolidating around pulse-jet cleaning architectures as cement and power operators abandon mechanical shaker systems to meet tightening particulate emission thresholds. This engineering transition is compressing replacement cycles and redrawing supplier relationships across heavy industry procurement desks.
Growth Catalysts
- EPA Maximum Achievable Control Technology standards:Coal-fired boiler operators in the United States must upgrade woven glass configurations to membrane-equipped non-woven media, forcing systematic filter replacement programs.
- Cement capacity expansion:Chinese and Indian producers are installing new baghouse infrastructure at greenfield clinker plants to preempt enforcement actions by environmental regulators.
- PTFE membrane composites:Chemical processing facilities specify these materials for liquid filtration duties where corrosive solvent exposure degrades conventional substrates.
Market Restraints
- High-temperature fiberglass supply concentration:Specialized yarn production concentrates among a limited supplier base in Germany and Japan, creating input bottlenecks during demand surges.
- EU F-Gas Regulation compliance costs:Refrigeration and HVAC filter applications face elevated certification expenses that compress margins for mid-tier membrane laminators.
- Electrostatic precipitator substitution:Power generation utilities in cost-sensitive markets retain legacy ESP installations rather than converting to fabric filter baghouses.
Strategic Opportunities
- India's emission control infrastructure gap:Industrial capacity expansion outpaces filter deployment, creating procurement timing arbitrage for system integrators ahead of anticipated CDSCO-aligned environmental notifications.
- Pharmaceutical cleanroom demand:Biologics manufacturing growth in Singapore and South Korea requires premium membrane laminates with validated particulate retention specifications.
- Digital predictive maintenance convergence:IoT pressure-drop monitoring integrated with pulse-jet controllers enables condition-based filter replacement, opening service revenue streams for equipment OEMs.
Industry Challenges
- GB standards certification timelines:China's Ministry of Ecology and Environment requires third-party testing for ultra-low emission coal boiler filters, creating six-to-nine-month approval backlogs that delay project commissioning.
- Retrofit engineering complexity:Existing ductwork configurations at 1970s-era cement kilns demand custom baghouse redesigns that strain in-house technical teams and extend project risk windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Filters Market |
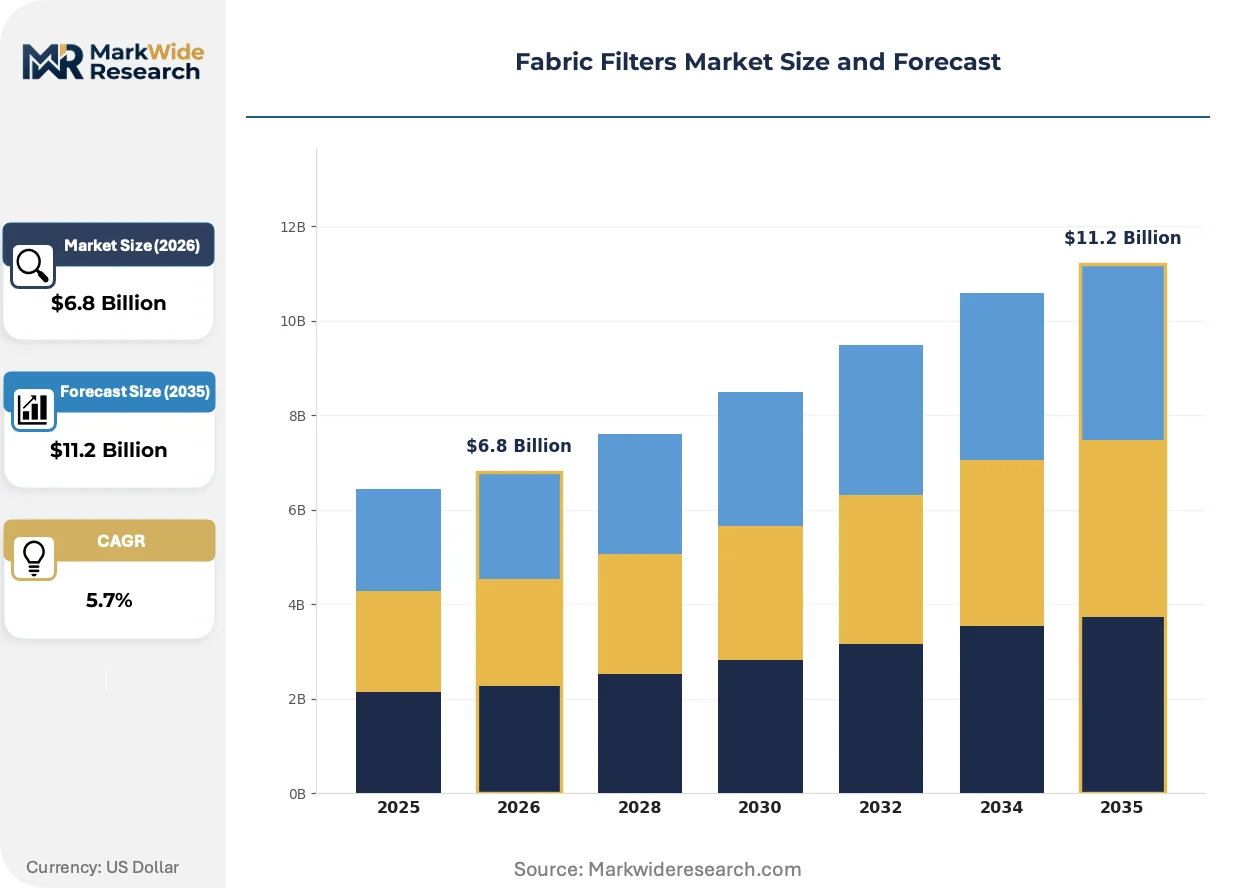
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Fiberglass, Polyester Application: Air Pollution Control, Dust Collection, Liquid Filtration, Chemical Processing End User: Power Generation, Cement, Food & Beverage, Pharmaceuticals Technology: Electrostatic Precipitators, Baghouse Filters, Cartridge Filters, Dry Scrubbers |
| Companies Covered | Ahlstrom-Munksjö Oyj, Freudenberg Filtration Technologies, Valmet Oyj, Lydall Inc., Johns Manville, Donaldson Company, Sefar Holding AG, Clear Edge Filtration, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Filters Market Emerging Trajectories
Filter media engineering is converging on hybrid constructions that merge mechanical durability with surface filtration efficiency. This materials evolution is compressing the performance gap between commodity non-wovens and premium membrane laminates.
Nanofiber surface coating technology is unifying depth filtration capture with surface release characteristics in a single substrate. Cement kiln tail gas applications in Germany and Poland are adopting these constructions at accelerating rates. The technology is unifying what were previously separate procurement categories for high-temperature bags and membrane upgrades.
China's GB standards for ultra-low emissions are mandating particulate thresholds below 10 milligrams per cubic meter for coal-fired boilers. Domestic filter suppliers must certify media combinations against these specifications to qualify for state-owned utility tenders. Non-woven configurations with expanded PTFE membranes are capturing specification share from traditional woven glass in this compliance-driven replacement cycle.
Aftermarket procurement patterns are fragmenting as power generation operators unbundle filter supply from original equipment service contracts. Independent distributors in the United States are capturing rebuild schedule data through direct utility relationships, bypassing captive OEM channels. This disintermediation is most visible in Texas and Ohio where merchant power plant ownership concentration supports third-party sourcing at scale.
Fabric Filters Market Segmentation
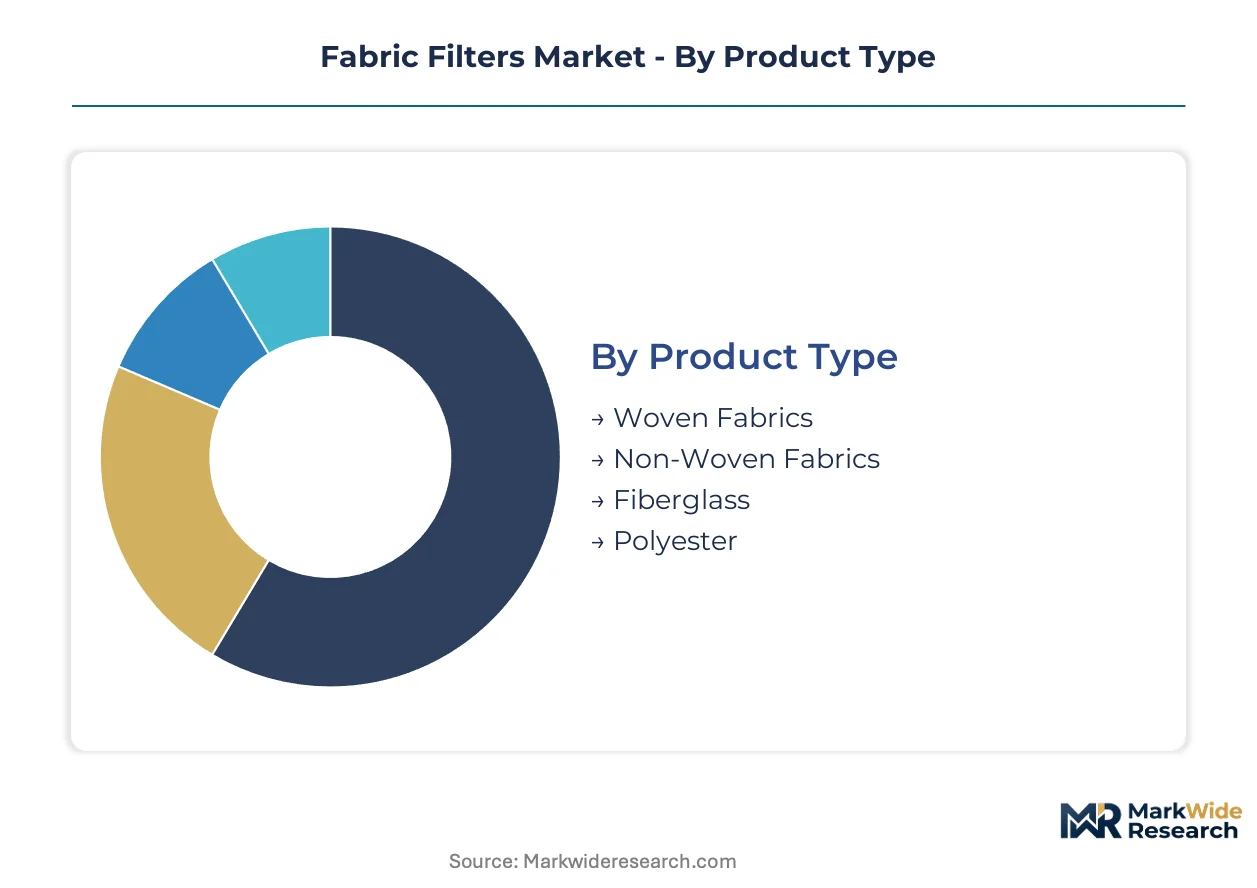
Fabric filter procurement decisions hinge on media engineering specifications that must align with temperature, chemical, and particulate loading profiles. Segmentation reveals where membrane laminates command premium positioning against commodity needle-punch alternatives across divergent end-use requirements.
Product Type:
Standalone baghouse installations favor woven and fiberglass constructions with established mechanical integrity, while embedded pulse-jet systems increasingly specify non-woven media for surface filtration efficiency.
- Woven Fabrics:These textile constructions interlock warp and weft yarns into defined pore structures rated by permeability and tensile strength. Cement kiln tail gas applications in Germany and Poland specify woven glass for thermal stability above 260°C, though EPA MACT standards now force membrane retrofits that compromise pure woven economics.
- Non-Woven Fabrics:Needle-punched and melt-blown matrices create tortuous filtration paths with depth capture characteristics. Chinese domestic suppliers are scaling capacity for high-temperature variants as MEE ultra-low emission thresholds below 10 mg/m³ displace traditional woven configurations in coal-fired boiler retrofits.
- Fiberglass:Specialized yarn production concentrates in Germany and Japan, creating supply bottlenecks during demand surges for power generation rebuild schedules.
- Polyester:Commodity synthetic staple fibers serve ambient-temperature dust collection in food processing and agricultural applications where chemical resistance requirements remain moderate.
Woven fabrics lead volumes today; non-woven configurations are gaining share fastest.
Application:
Cost tier differentiation separates compliance-driven capital expenditure from maintenance-driven aftermarket procurement across these functional categories.
- Air Pollution Control:Stationary source emission systems intercept particulate matter from industrial stacks. Chinese and Indian cement producers deploy baghouse infrastructure at greenfield clinker plants to preempt MEE and CDSCO-aligned enforcement actions.
- Dust Collection:Dry particulate recovery systems protect worker exposure limits and product quality in minerals processing. Pulse-jet cleaning architectures are displacing mechanical shaker mechanisms across heavy industry procurement desks.
- Liquid Filtration:PTFE membrane composites resist corrosive solvent exposure in chemical processing duties where margin premiums reflect validated retention specifications.
- Chemical Processing:Aggressive media environments demand hybrid constructions merging mechanical durability with surface filtration efficiency.
Air pollution control commands the largest capital allocation; liquid filtration delivers the steepest margin expansion.
End User:
Customer type fragmentation separates integrated operators with captive engineering teams from merchant facilities reliant on system integrators for specification compliance.
- Power Generation:Coal-fired boiler operators in the United States face EPA MACT-mandated upgrades from woven glass to membrane-equipped non-woven media. Texas and Ohio merchant plants are unbundling filter supply from OEM service contracts, enabling third-party distributor capture of rebuild schedules.
- Cement:Clinker production generates abrasive, high-temperature tail gas requiring specialized baghouse engineering. Retrofit complexity at 1970s-era kilns strains in-house technical teams and extends project risk windows.
- Food & Beverage:Ambient-temperature dust collection for grain handling and powder processing specifies FDA-compliant synthetic media with validated cleanability.
- Pharmaceuticals:Biologics manufacturing in Singapore and South Korea requires premium membrane laminates with validated particulate retention specifications for cleanroom HVAC and process isolation.
Power generation anchors replacement demand; pharmaceutical applications are climbing the fastest.
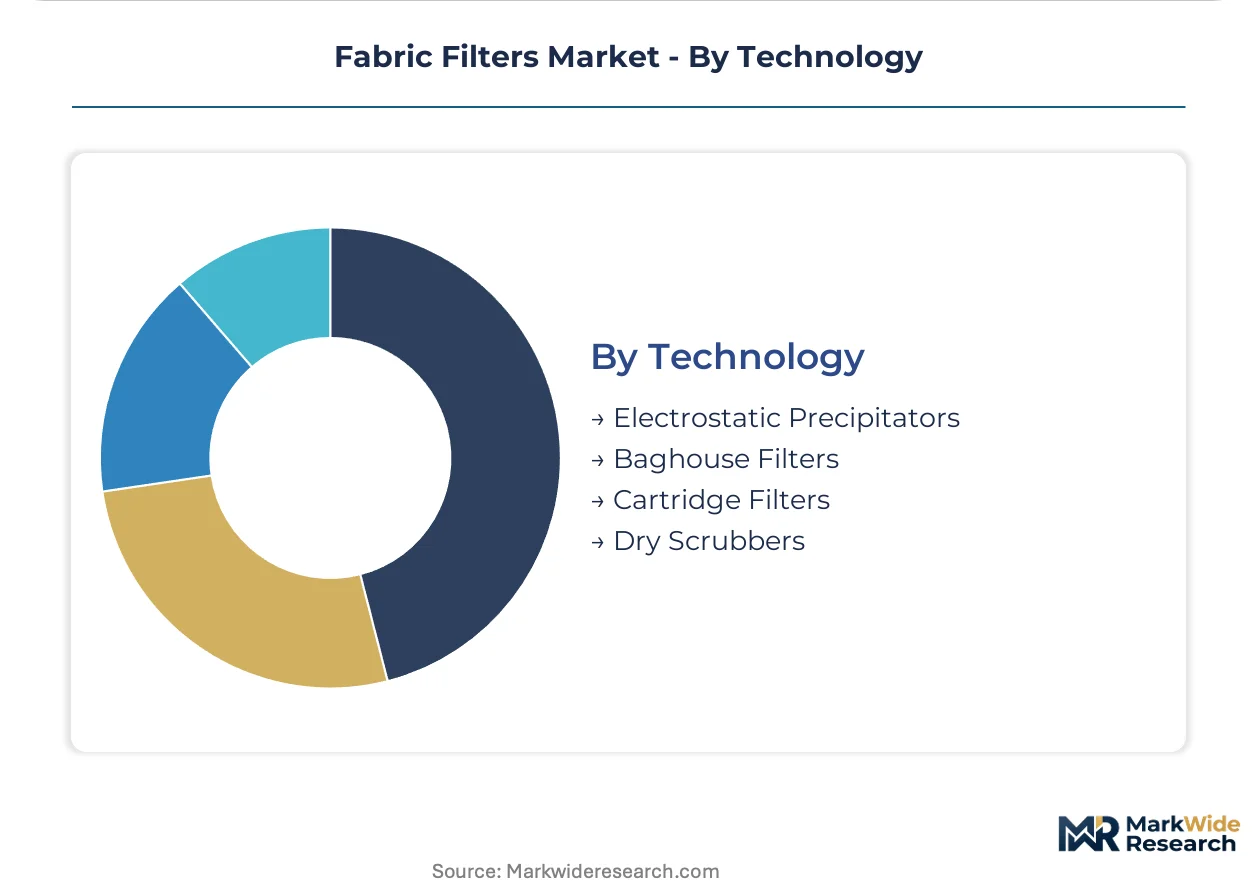
Technology:
Maturity gradients separate legacy installations with sunk capital from greenfield specifications adopting convergent digital monitoring architectures.
- Electrostatic Precipitators:Ionization-based particulate removal retains installed base in cost-sensitive markets where utilities defer conversion to fabric filter baghouses despite inferior sub-micron capture efficiency.
- Baghouse Filters:Fabric media arrays with mechanical or pulse-jet cleaning dominate capital flows due to retrofit compatibility across existing ductwork infrastructure. IoT pressure-drop monitoring integration is enabling condition-based replacement revenue streams.
- Cartridge Filters:Pleated media configurations maximize surface area in compact footprints for compressed air and indoor air quality applications.
- Dry Scrubbers:Sorbent injection systems for acid gas control operate upstream or in parallel with particulate filtration stages.
Baghouse technology holds the dominant installed position; cartridge systems are expanding most quickly in indoor air and compressed air segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's cement producers deploy baghouse infrastructure at triple the rate of German counterparts, yet both markets face converging EPA and EU F-Gas Regulation compliance deadlines that compress replacement cycles for legacy filter media.
China
Coal-fired boiler operators in Hebei and Shanxi provinces retrofit woven glass configurations to membrane-equipped non-woven media under MEE ultra-low emission thresholds below 10 mg/m³. GB standards certification requires third-party testing that creates six-to-nine-month approval backlogs. Yangtze River Delta filter suppliers scale melt-blown and needle-punch capacity to capture state-owned utility tenders.
United States
Texas and Ohio merchant power plants unbundle filter supply from OEM service contracts, enabling independent distributors to capture rebuild schedules through direct utility relationships. EPA Maximum Achievable Control Technology standards force systematic replacement programs across coal-fired boiler infrastructure. Appalachian cement kilns strain in-house technical teams with custom baghouse redesigns for 1970s-era ductwork configurations.
Germany
Specialized high-temperature fiberglass yarn production concentrates among limited supplier bases, creating input bottlenecks during power generation demand surges. Cement kiln tail gas applications in the industrial Rhineland adopt nanofiber surface coatings at accelerating rates. Freudenberg leverages its domestic R&D footprint to sustain premium membrane laminates for pharmaceutical cleanroom specifications.
India
Industrial capacity expansion in Gujarat and Maharashtra outpaces emission control infrastructure deployment, creating procurement timing arbitrage for system integrators ahead of anticipated CDSCO-aligned environmental notifications. Clinker producers install greenfield baghouse infrastructure to preempt enforcement actions. Domestic non-woven fabric production hardens as suppliers scale capacity for high-temperature filtration duties.
South Korea
Biologics manufacturing growth in the Seoul Capital Area requires premium membrane laminates with validated particulate retention specifications for cleanroom HVAC and process isolation. Pharmaceutical cleanroom demand climbs fastest among Asia-Pacific fabrication clusters. Local filter integrators position for Singapore and regional biologics export markets.
Fabric Filters Market Vendor Landscape
German producers anchor one tier with specialized high-temperature yarn and membrane laminate capabilities; Chinese specialists hold volume positions in non-woven needle-punch and melt-blown expansion. The vendor base stratifies across three archetypes: integrated multinationals with captive R&D footprints, regional fabricators scaling domestic capacity, and niche membrane laminators serving validated cleanroom specifications. Competitive moves concentrate on backward integration into specialized yarn production and geographic expansion through distributor network capture.
Within the integrated multinational tier, Freudenberg Filtration Technologies and Donaldson Company exemplify divergent geographic anchoring strategies. Freudenberg occupies a position tied to European premium membrane development, while Donaldson represents North American aftermarket channel dominance. Ahlstrom-Munksjö Oyj sits within the materials science archetype, with its corporate structure suggesting Nordic-Finnish origins. These three entities collectively illustrate how competitive positioning fragments across R&D intensity, distribution control, and substrate engineering specialization rather than converging on unified scale advantages.
| Leading Market Players |
|---|
| Ahlstrom-Munksjö Oyj |
| Freudenberg Filtration Technologies |
| Valmet Oyj |
| Lydall Inc. |
| Johns Manville |
| Donaldson Company |
| Sefar Holding AG |
| Clear Edge Filtration |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
State-owned utility procurement in China anchors contract-based long-term offtake structures, compressing spot-market liquidity and forcing Western membrane laminators toward premium-tier positioning in pharmaceutical and power generation rebuild schedules.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for commodity needle-punch media, eroding margins for mid-tier European suppliers. Three-tier pricing structure across premium membrane laminates, certified non-woven configurations, and commodity needle-punch separates validated pharmaceutical specifications from cement kiln retrofits. Cost compression in standard-grade polyester media is intensifying because domestic Chinese suppliers scale melt-blown capacity. Merchant power plants in Texas and Ohio exhibit highest price sensitivity due to unbundled procurement from OEM service contracts, while pharmaceutical cleanroom operators in Singapore and South Korea absorb premium positioning for validated retention specifications.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and China coordinate hub-and-spoke patterns for high-temperature fiberglass yarn, with specialized production concentrating in the Rhine-Ruhr and Osaka-Kobe industrial corridors. Raw material draws from borosilicate glass feedstock, PTFE resin, and synthetic staple fibers, with membrane laminate production resting on fluoropolymer coating capacity concentrated among German and Japanese chemical processors. Single-source vulnerability in specialized high-temperature yarn creates bottleneck risk during power generation rebuild surges. Distribution runs through captive OEM channels for original equipment sales and independent distributors for aftermarket rebuild schedules, with disintermediation accelerating in North American merchant power markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane laminate premiumization and Chinese domestic capacity expansion create divergent margin trajectories, rewarding backward integration into specialized yarn production while compressing returns for commodity non-woven suppliers.
For Market Incumbents: Lock in long-term offtake agreements with state-owned Chinese utilities before GB standards certification backlogs clear, insulating against price erosion from domestic capacity scaling. Deepen upstream control over high-temperature fiberglass yarn supply through exclusive supplier arrangements or in-house production investments, neutralizing the single-source bottleneck risk that disrupts power generation rebuild schedules. Secure validated membrane laminate specifications for pharmaceutical cleanroom applications in Singapore and South Korea, where biologics manufacturing growth sustains premium positioning. For New Entrants and Emerging Players: The mid-tier price gap between German membrane laminates and Chinese commodity needle-punch offers white-space positioning for hybrid nanofiber-coated constructions in European cement kiln retrofits. Target India's Gujarat and Maharashtra industrial corridors ahead of CDSCO-aligned environmental notifications, where emission control infrastructure deployment lags capacity expansion. Enter through system integrator partnerships rather than direct OEM channel competition, leveraging procurement timing arbitrage before regulatory enforcement accelerates. For Investors and Strategic Acquirers: Filter media specialists with captive pharmaceutical validation are the most active acquirer in this space, consolidating membrane laminate capabilities for biologics manufacturing growth. Long-term viability hinges on exposure to compliance-driven replacement cycles rather than discretionary capital expenditure, with power generation and cement emission upgrades providing recurring revenue visibility. Monitor GB standards certification timeline compression as an inflection indicator for Chinese domestic supplier market share gains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialized Yarn Production | Captive supply of high-temperature fiberglass neutralizes German-Japanese supplier bottlenecks during demand surges. |
| Membrane Laminate Validation Investment | Pharmaceutical cleanroom certification in Singapore and South Korea unlocks premium pricing for biologics manufacturing. |
| System Integrator Partnership Expansion | Channel control in India and Brazil captures procurement timing arbitrage ahead of environmental notification enforcement. |
| Pulse-Jet Controller Digital Integration | IoT pressure-drop monitoring enables condition-based replacement revenue streams for equipment OEMs. |
| Regional Distribution Center Localization | Hub-and-spoke logistics in China's Yangtze River Delta reduce delivery costs for state-owned utility tenders. |
Methodological Framework
Coverage spans China, the United States, Germany, India, and South Korea, with primary inputs from each market combining interviews with plant engineers, procurement leads at cement and power operators, aftermarket service heads, and technical R&D directors with secondary validation. Secondary sources include EPA enforcement databases, EU F-Gas Regulation compliance filings, Chinese GB standards documentation, Indian customs and trade data, and SEC 10-K disclosures from listed filter manufacturers. Bottom-up unit economics for baghouse installations triangulate against top-down capital expenditure flows from industrial end-users.
Granularity-level modeling captures product type distinctions between woven, non-woven, fiberglass, and polyester constructions; application segmentation across air pollution control, dust collection, liquid filtration, and chemical processing; technology differentiation between electrostatic precipitators, baghouse filters, cartridge systems, and dry scrubbers; and end-user verticals spanning power generation, cement, food and beverage, and pharmaceuticals. CAGRs derive from installed base replacement cycle analysis and greenfield capacity expansion trajectories across the projection horizon. Industry-specific inputs include EPA MACT compliance timelines, MEE ultra-low emission threshold enforcement intensity, and pharmaceutical cleanroom validation specification adoption rates.
The model assumes a particular technology adoption path; alternative pathways for electrostatic precipitator retention in cost-sensitive power markets would alter the outlook for baghouse filter penetration. Forecasts reflect documented assumptions regarding regulatory enforcement calibration, raw material supply elasticity, and membrane laminate certification timeline compression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Color Filter Glass Market
Filters
High Purity Chemical Filters Market
Filters
String Wound Filter Materials Market
Filters
United States Activated Carbon Market
Filters
Polishing Filter Market
Filters
Global Hollow Fiber Filtration Market
Filters
Single-Use Filtration Assemblies Market
Filters
Global Cartridge Filters Market
Filters
Europe Activated Carbon Market
Filters
Adsorbent Market
Filters
Global Laboratory Filtration Market
Filters
Anti-Microbial Filter Market
Filters
Air Filtration Media Market
Filters
Aerospace Filter Market
Filters
ePTFE Filter Film Market
Filters
Global Filter Press Market