
 Non-Wood Fiber Market | 2026-2036
Non-Wood Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Wood Fiber Market Analytics
Project finance tied to biorefinery infrastructure is rewriting competitive entry barriers across the Non-Wood Fiber landscape. Lenzing AG leverages its integrated dissolving pulp-to-fiber model to sustain cost discipline at scale. Aditya Birla Group anchors significant viscose staple fiber capacity in South Asia. EcoPlanet Bamboo Group specializes in plantation-to-fiber traceability that differentiates its supply contracts with European textile brands.
Non-wood fibers comprise cellulose-based materials extracted from agricultural residues, grasses, and bast crops such as hemp, kenaf, and bamboo, typically processed through mechanical, chemical, or semi-chemical methods to achieve lignin content below 5% for textile-grade pulp. These fibers serve as direct substitutes for wood pulp in paper, composites, and regenerated cellulose applications where carbon footprint reduction carries procurement weight. Hemp and kenaf within the product type dimension lead raw material sourcing due to low water intensity and absence of pesticide dependency, while cotton occupies mature, price-sensitive segments where organic certification commands premium positioning. The end use industry segmentation shows textiles and biodegradable plastics as the fastest-expanding demand pools, with margin concentration in specialty-grade outputs for automotive composites and medical nonwoven fabrics.
Regulatory frameworks including the EU Green Deal, REACH chemical registration requirements, and the F-Gas Regulation collectively constrain synthetic fiber production methods while creating preferential market access for certified low-carbon cellulose sources. China's GB standards and dual carbon goals impose parallel emissions intensity thresholds on domestic viscose producers, reshaping export eligibility for non-wood fiber derivatives. Stakeholders must monitor evolving biogenic carbon accounting methodologies and certification scheme interoperability between European and Asian compliance systems to secure long-term offtake agreements.
Market Dynamics
Biorefinery project finance is restructuring competitive entry barriers across the Non-Wood Fiber landscape, as capital-intensive dissolving pulp-to-fiber integration separates scalable producers from merchant pulp buyers.
Growth Catalysts
- EU Green Deal compliance mandates:REACH chemical registration requirements and F-Gas Regulation constraints are systematically disqualifying synthetic fiber production methods from European textile supply chains.
- Automotive composite specifications:Lightweighting targets in electric vehicle platforms are pulling bast fiber reinforcement into structural interior panels and underbody shields.
- China's dual carbon policy framework:GB standards emissions intensity thresholds are reshaping export eligibility criteria for viscose staple fiber derivatives bound for EU markets.
Market Restraints
- Caustic soda and sulfuric acid price volatility:Chemical pulping cost structures remain exposed to energy-intensive input swings that compress margin predictability at merchant pulp converters.
- Plantation supply concentration:Bamboo fiber processing clusters in China's Fujian and Sichuan provinces create geographic single-source risk for European offtake contracts.
- Lignin removal technical ceiling:Mechanical processing methods struggle to achieve sub-5% lignin content thresholds required for textile-grade dissolving pulp without chemical augmentation.
Strategic Opportunities
- India's technical textile expansion:The country's PLI scheme for man-made fiber and technical textile segments offers capital subsidy pathways for bast fiber composite entrants.
- Blockchain-enabled traceability platforms:Plantation-to-garment digital verification is opening premium contract tiers with Scandinavian and German apparel brands.
- Semi-chemical pulping convergence:Integration of enzymatic pre-treatment with mechanical refining is reducing chemical load while preserving fiber length for high-tenacity applications.
Industry Challenges
- Dissolving pulp process engineering talent scarcity:Specialized expertise in alpha-cellulose extraction from non-wood feedstocks remains concentrated among legacy viscose producers.
- EU Deforestation Regulation traceability timeline:Compliance documentation requirements for farm-level geolocation data are extending certification cycles beyond standard contract negotiation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Wood Fiber Market |
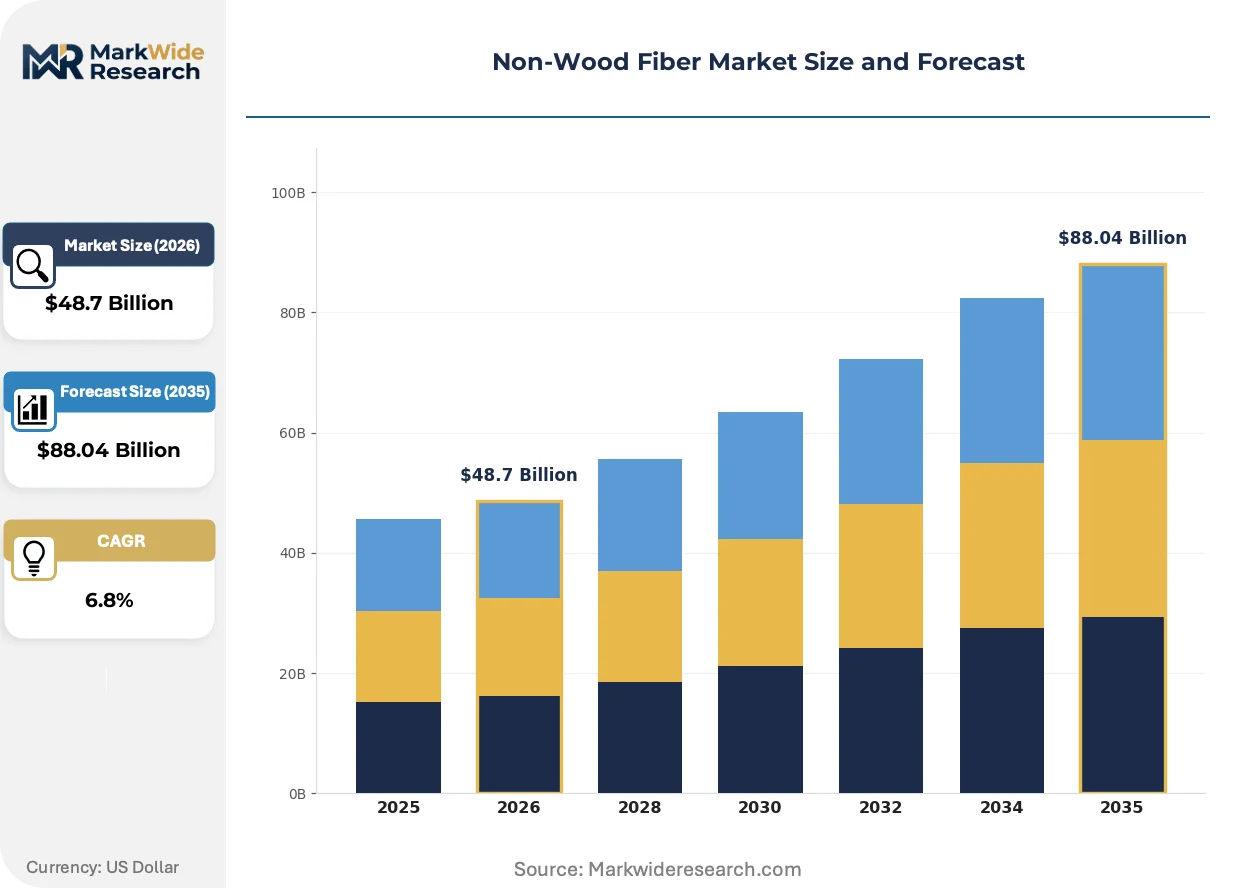
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemp, Kenaf, Cotton, Flax End Use Industry: Textiles, Paper, Composites, Biodegradable Plastics Application: Insulation, Reinforcement, Packaging, Nonwoven Fabrics Grade: Standard, Premium, Industrial, Specialty |
| Companies Covered | Genera, Lenzing AG, Goonvean Fibres, Chempolis Biorefining Park, Aditya Birla Group, Shanghai Tenbro Bamboo Textile Co., Willamette Falls Paper Company, EcoPlanet Bamboo Group, AWA Paper and Technological Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Wood Fiber Market Evolving Landscape
Processing technology convergence and regulatory compliance automation are actively restructuring how non-wood fiber producers qualify for premium textile supply chains.
Enzyme-assisted mechanical pulping is hybridizing traditional chemical-intensive dissolving pulp production. Specialty chemical suppliers are deploying cellulase cocktails that reduce caustic soda consumption by enabling selective hemicellulose hydrolysis. European textile mills are qualifying these hybrid outputs for lyocell feedstock, compressing the capital barrier between merchant pulp buyers and integrated biorefinery operators.
REACH registration dossier automation platforms are streamlining compliance documentation for novel cellulose derivatives. ECHA's substance evaluation workflows are forcing reformulation of traditional viscose auxiliary chemicals. German and Austrian fiber producers are deploying predictive toxicology modeling to preempt regulatory scrutiny, accelerating time-to-market for modified fiber variants.
Certificate-of-origin purchasing is displacing spot-market procurement in premium apparel segments. Direct contracting between plantation operators and finished garment brands is bypassing traditional pulp merchant intermediaries. This disintermediation is most visible in Netherlands and Denmark, where fashion houses are establishing multi-year offtake agreements with bamboo and hemp fiber processors.
Non-Wood Fiber Market Segmentation
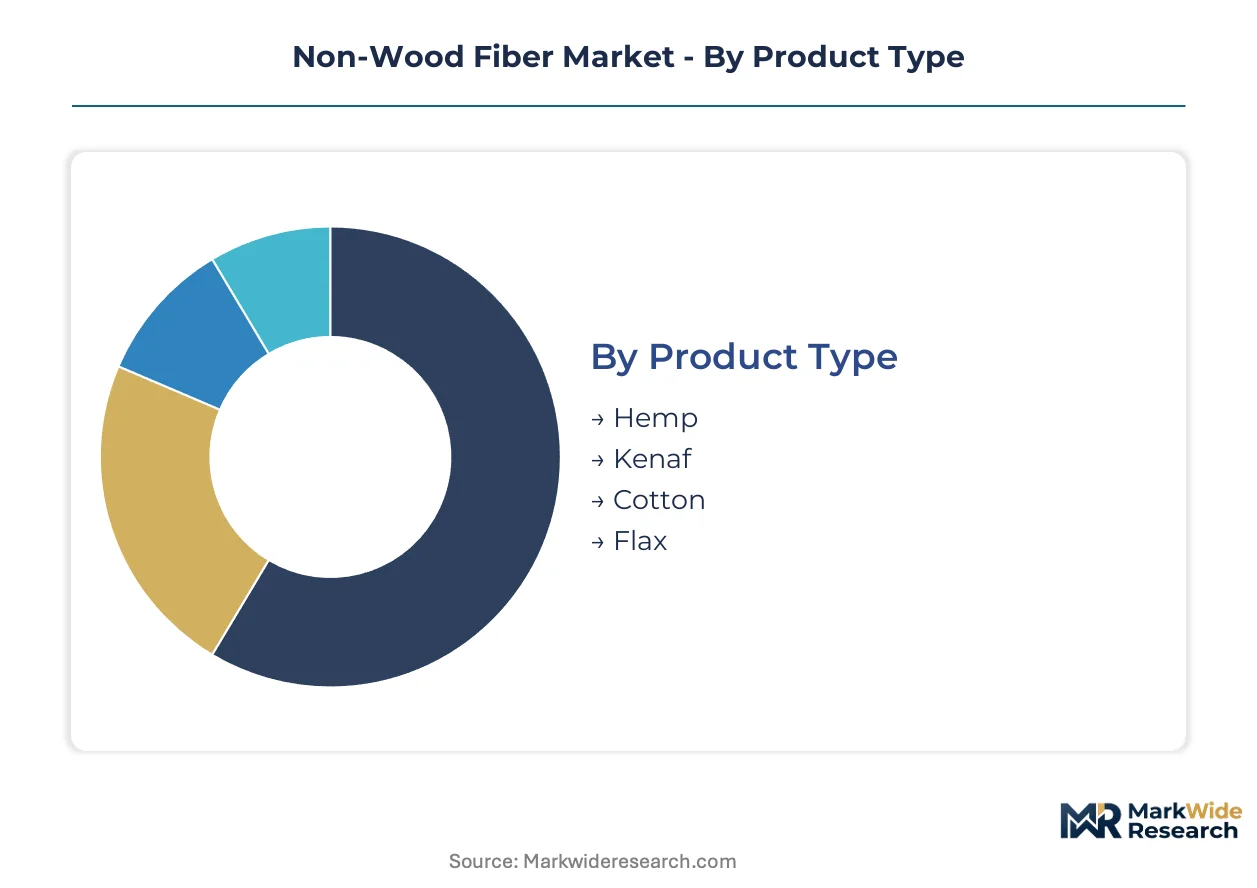
Non-wood fiber procurement decisions hinge on lignin content thresholds, carbon intensity certifications, and end-use performance specifications. Manufacturers segment supply contracts across four critical dimensions that determine processing method selection and margin realization.
Product Type:
The use-case spectrum spans apparel-grade dissolving pulp to structural composite reinforcement, with each bast crop delivering distinct tensile properties and agricultural input profiles.
- Hemp:Alpha-cellulose content reaches 70-75% in decorticated bast strips, enabling direct substitution for wood pulp in lyocell production. European automotive suppliers are qualifying hemp fiber mats for electric vehicle interior panels under EU Green Deal carbon accounting protocols.
- Kenaf:Core fiber exhibits lower lignin burden than jute, supporting semi-chemical pulping with reduced caustic soda loads. Indian technical textile mills under the PLI scheme are integrating kenaf reinforcement into geotextile drainage applications.
- Cotton:Mature commodity segment where organic certification commands supply contract premiums from Scandinavian apparel brands.
- Flax:Linen-grade long fiber retains historical positioning in premium home textile segments with limited expansion into technical applications.
The dominant share belongs to Hemp, while Kenaf is closing the gap fastest.
End Use Industry:
Margin concentration varies sharply across customer categories, with automotive and medical applications extracting premium pricing for certified low-carbon cellulose.
- Textiles:Regenerated cellulose fiber production—viscose, lyocell, modal—consumes the highest-grade dissolving pulp with sub-5% lignin thresholds. China's Fujian and Sichuan processing clusters supply both domestic mills and EU-bound export volumes under tightening GB standards emissions protocols.
- Biodegradable Plastics:Cellulose acetate and PLA-cellulose compounds are expanding most quickly as single-use plastic bans proliferate across German and French packaging regulations.
- Composites:Bast fiber reinforcement serves electric vehicle lightweighting targets in structural panels and underbody shields.
- Paper:Agricultural residue pulps compete on cost with recycled fiber in corrugated packaging segments.
Textiles capture the dominant value share, though Biodegradable Plastics is climbing the fastest.
Application:
Processing intensity and certification requirements diverge across functional end-uses, with thermal performance specifications driving insulation-grade procurement.
- Reinforcement:High-tenacity bast fiber rovings qualify for automotive structural composites under OEM specifications for crash energy absorption. German Tier 1 suppliers are qualifying hemp-epoxy prepregs for EV battery enclosure applications.
- Nonwoven Fabrics:Medical-grade absorbent layers and filtration media demand controlled fiber diameter distributions achievable through enzymatic pre-treatment methods.
- Insulation:Hemp and flax batts compete with mineral wool in residential construction under French RE2020 environmental regulations.
- Packaging:Molded fiber trays and protective cushioning represent volume-driven segments with limited differentiation.
Reinforcement holds the dominant position, while Nonwoven Fabrics is gaining share fastest.
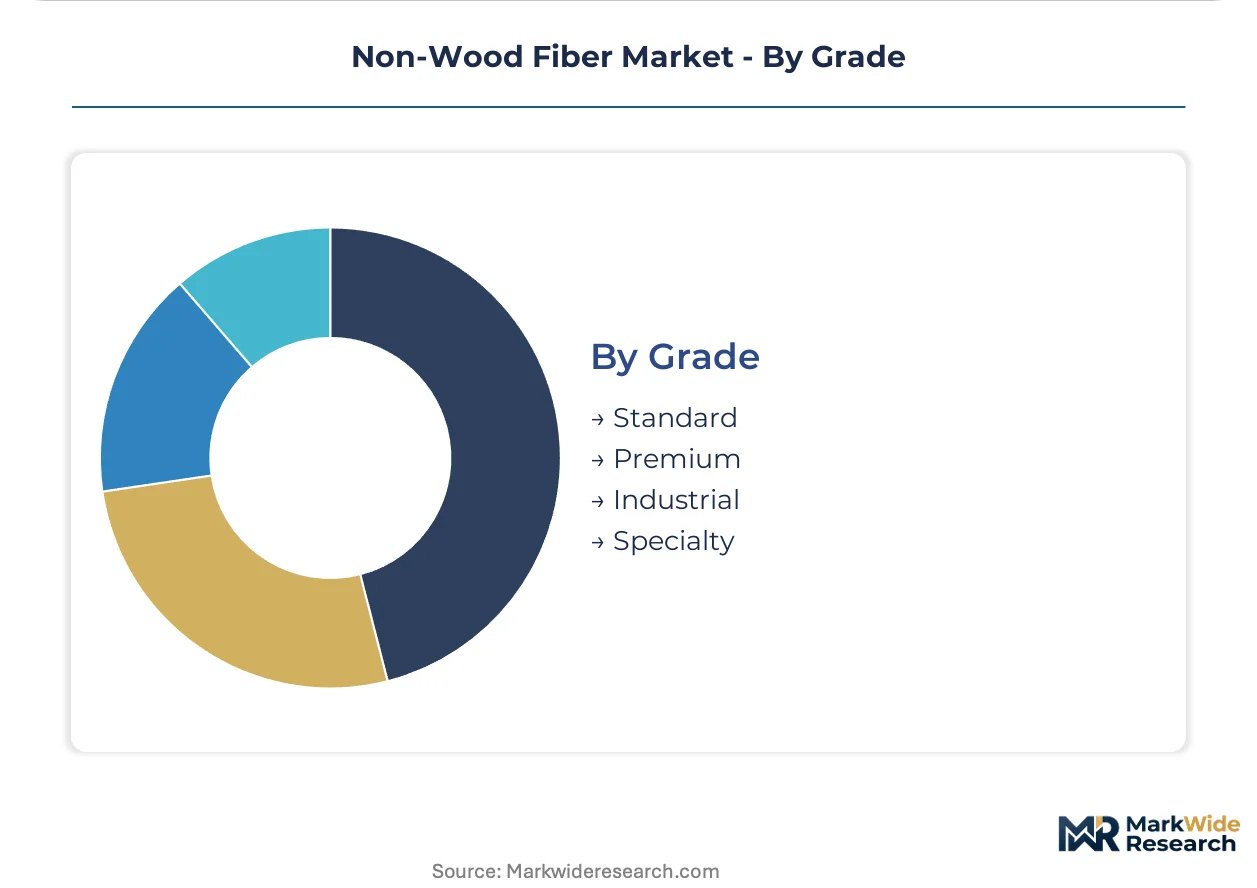
Grade:
Certification tier and traceability documentation separate contract pricing bands, with specialty grades commanding multi-year offtake premiums.
- Specialty:Medical and aerospace applications require batch-level carbon footprint documentation and REACH-compliant chemical treatment records. Austrian and German fiber producers are deploying predictive toxicology modeling to accelerate ECHA substance evaluation clearance for modified fiber variants.
- Premium:Blockchain-enabled plantation-to-garment traceability qualifies supply contracts with Netherlands and Denmark fashion houses.
- Industrial:Standardized tensile specifications serve automotive and construction composite tiers without full certification documentation.
- Standard:Commodity-grade outputs compete on delivered cost in packaging and lower-tier textile applications.
Specialty grade commands the dominant margin pool, though Premium is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China maintains a structural export surplus in dissolving pulp derivatives while European Union import dependency deepens for certified low-carbon cellulose feedstocks. The regional configuration reflects divergent regulatory enforcement timelines and plantation infrastructure maturity across major producing and consuming markets.
China
Fujian and Sichuan provinces host concentrated bamboo fiber processing clusters supplying domestic viscose mills and EU-bound export volumes. GB standards emissions intensity thresholds under the dual carbon policy framework are reshaping export eligibility criteria for staple fiber derivatives. Shanghai Tenbro Bamboo Textile Co. anchors integrated production capacity in the Yangtze River Delta corridor.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are qualifying hemp-epoxy prepregs for electric vehicle battery enclosures under EU Green Deal carbon accounting protocols. ECHA's REACH substance evaluation workflows are forcing reformulation of traditional viscose auxiliary chemicals. Berlin-Brandenburg hosts predictive toxicology modeling capabilities that accelerate modified fiber variant clearance.
India
Technical textile mills in Gujarat and Maharashtra integrate kenaf reinforcement into geotextile drainage applications under the PLI scheme for man-made fiber segments. BIS standards compliance requirements are tightening for imported dissolving pulp substitutes. Tamil Nadu spinning clusters are expanding bast fiber blending capacity for apparel export contracts.
United States
EPA emissions guidelines and state-level carbon disclosure mandates in California and New York are pulling agricultural residue pulps into corrugated packaging segments. Willamette Falls Paper Company exemplifies Pacific Northwest concentration in non-wood fiber paper manufacturing. Southeast textile converters are qualifying hemp fiber imports for technical fabric applications.
Netherlands
Amsterdam and Rotterdam fashion houses establish multi-year offtake agreements directly with plantation operators, bypassing traditional pulp merchant intermediaries. EU Deforestation Regulation traceability documentation requirements are extending certification cycles for farm-level geolocation data. Blockchain-enabled verification platforms concentrate in Randstad logistics corridors.
Non-Wood Fiber Market Competitive Landscape
On the supply side, the industry is bifurcating between integrated biorefinery operators and merchant pulp converters exposed to chemical input volatility. Capital-intensive dissolving pulp-to-fiber integration separates scalable producers from price-takers at the conversion tier. Three archetypes dominate: legacy viscose conglomerates with captive forestry, plantation-to-fiber traceability specialists, and regional paper-grade diversifiers. Competitive moves concentrate on backward integration into plantation assets and enzymatic pre-treatment technology licensing.
Within the integrated biorefinery tier, Lenzing AG and Aditya Birla Group exemplify scale-driven dissolving pulp-to-fiber models that sustain cost discipline through captive chemical recovery systems. EcoPlanet Bamboo Group occupies a position in plantation-to-fiber traceability that differentiates supply contracts with European textile brands requiring EUDR-compliant documentation. Among specialty chemical biorefining ventures, Chempolis Biorefining Park represents the semi-chemical pulping convergence archetype integrating enzymatic pre-treatment with mechanical refining methods.
| Leading Market Players |
|---|
| Genera |
| Lenzing AG |
| Goonvean Fibres |
| Chempolis Biorefining Park |
| Aditya Birla Group |
| Shanghai Tenbro Bamboo Textile Co. |
| Willamette Falls Paper Company |
| EcoPlanet Bamboo Group |
| AWA Paper and Technological Company, Inc. |
| Others |
Value Network & Pricing Analysis
Fujian and Sichuan bamboo processing clusters anchor upstream supply concentration, funneling margin capture toward integrated biorefinery operators with captive dissolving pulp-to-fiber capabilities while compressing returns at merchant pulp converters exposed to chemical input volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Specialty-grade outputs with REACH-compliant documentation and blockchain-enabled traceability command contract premiums from European automotive and medical textile purchasers. Price differentiation rests on certification tier and volume scale, with caustic soda price swings compressing margins at chemical-dependent conversion tiers. Apparel-grade dissolving pulp buyers exhibit highest price sensitivity, while medical nonwoven fabric purchasers absorb premium positioning for batch-level carbon documentation.
Supply Chain Analysis
Shanghai Tenbro Bamboo Textile Co. and Lenzing AG hold concentrated dissolving pulp-to-fiber capacity. Raw material flows draw from bamboo plantations in China's Fujian and Sichuan provinces, kenaf cultivation clusters in Gujarat and Maharashtra, and hemp decortication facilities in Germany's Bavaria region. Single-source geographic concentration in Chinese bamboo processing creates vulnerability for European offtake contracts under EU Deforestation Regulation timelines. Distribution runs through direct multi-year contracting between plantation operators and finished garment brands, displacing traditional pulp merchant intermediaries in Netherlands and Denmark corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Non-Wood Fiber Market tracks a cyclical recovery as biorefinery project finance availability tightens and consolidates production capacity among integrated operators with proven chemical recovery systems.
For Market Incumbents: Harden supply contract durability through backward integration into plantation assets with EUDR-compliant geolocation documentation. Invest in enzymatic pre-treatment licensing to reduce caustic soda exposure and defend margin position against semi-chemical pulping entrants. Priority lever: captive chemical recovery systems that insulate cost structures from sulfuric acid volatility. For New Entrants and Emerging Players: India's technical textile expansion under the PLI scheme represents the most penetrable entry point for bast fiber composite ventures. Kenaf reinforcement for geotextile drainage applications in Gujarat and Maharashtra offers capital-subsidized pathways with lower certification barriers than EU medical textile tiers. Go-to-market angle: partner with Tamil Nadu spinning clusters expanding bast fiber blending capacity for apparel export contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed plantation-to-fiber traceability specialists lacking integrated dissolving pulp capacity. Long-term viability across the analysis window favors acquisition targets with enzymatic pre-treatment IP and established EUDR documentation workflows. Signal to watch: biorefinery project finance closure rates as proxy for scalable capacity addition feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | EUDR-compliant geolocation data secures multi-year offtake contracts with Netherlands fashion houses. |
| Enzymatic Pre-treatment Technology Licensing | Cellulase cocktails reduce caustic soda loads while preserving fiber length for lyocell feedstock qualification. |
| Blockchain-Enabled Traceability Platform Deployment | Plantation-to-garment verification opens premium contract tiers with Scandinavian apparel brands. |
| Semi-Chemical Pulping Capacity Expansion | Hybrid mechanical-enzymatic methods compress capital barriers between merchant pulp buyers and integrated biorefinery operators. |
| REACH Registration Dossier Automation | Predictive toxicology modeling accelerates ECHA substance evaluation clearance for modified fiber variants. |
Research Methodology
The analysis maps dissolving pulp-to-fiber integration tiers, enzymatic pre-treatment technology licensing, and plantation-to-garment traceability platforms, each validated through biorefinery project finance officers, textile mill procurement directors, and specialty chemical R&D leads. Primary interviews with EUDR compliance consultants and REACH registration specialists combined with secondary validation from customs trade data, GB standards emissions disclosures, and SEC filings from listed fiber producers. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across product type and end-use dimensions.
Assumptions held fixed include regulatory enforcement timelines for EU Deforestation Regulation geolocation requirements and GB standards emissions intensity thresholds, while enzyme cost curves and biorefinery financing availability were varied across sensitivity scenarios. Segmentation dimensions modeled encompass bast crop type, processing method intensity, certification tier, and regional production hub clustering. CAGRs derive from installed capacity utilization rates and substitution elasticity estimates for synthetic fiber displacement in automotive and textile applications.
Practitioners should monitor biorefinery project finance closure rates, caustic soda price volatility indices, and EUDR certification cycle extensions for early signals of forecast revision. Quarterly review of enzyme-assisted mechanical pulping adoption rates and direct contracting volumes between plantation operators and finished garment brands is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Nonwoven Fabric Production Line Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market