
 Global Automotive Nonwoven Fabrics Market | 2026-2036
Global Automotive Nonwoven Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Nonwoven Fabrics Market Analysis
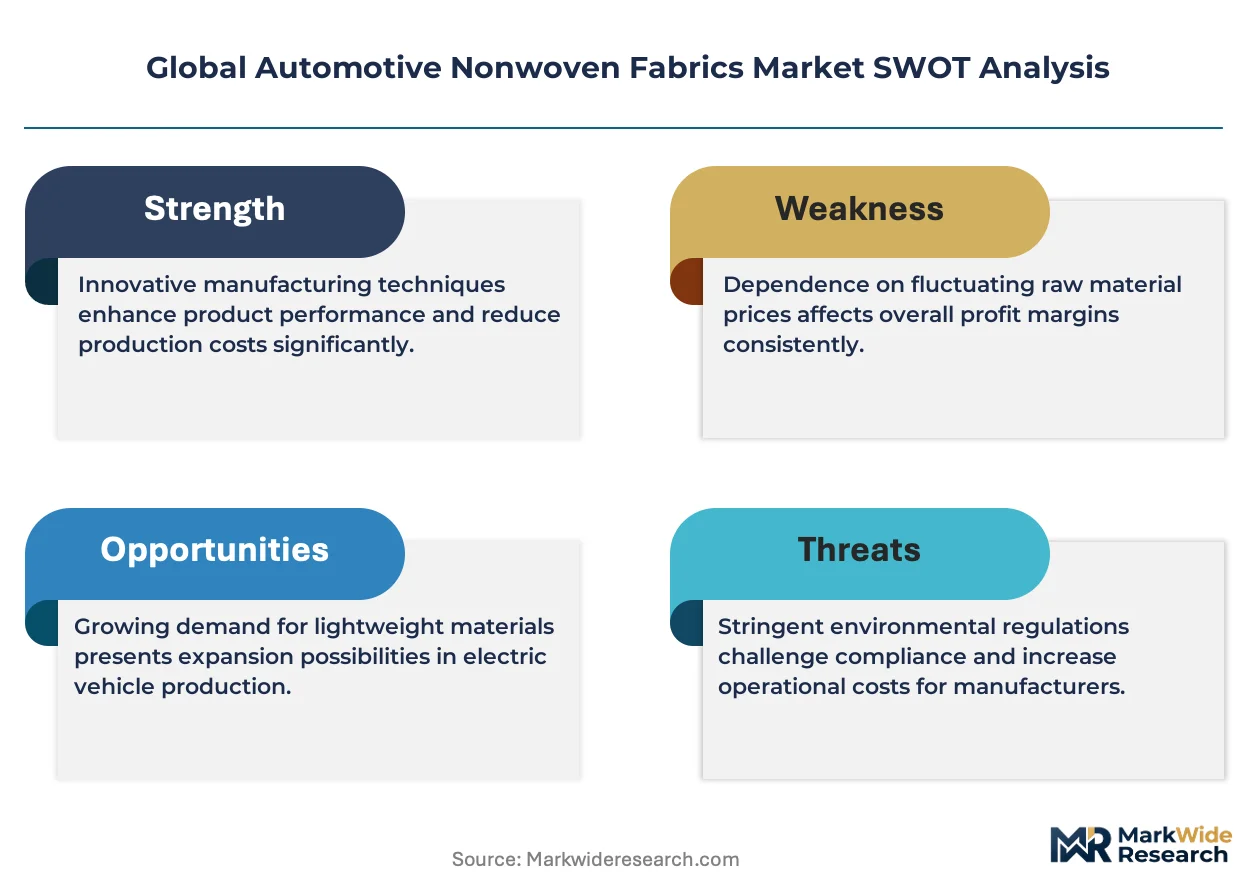
The EU Green Deal is recalibrating material selection criteria across European automotive supply chains, compelling Tier-1 suppliers to certify recycled content in cabin components. Freudenberg Performance Materials leverages its spunbond technology leadership to supply acoustic insulation meeting these specifications. Ahlstrom-Munksjö anchors its position through filtration media engineered for hybrid powertrains. DuPont de Nemours differentiates via bio-based polyamide nonwovens targeting premium OEM sustainability scorecards.
Automotive nonwoven fabrics are engineered sheet structures composed of directionally or randomly oriented fibers bonded through thermal, chemical, or mechanical means, typically measuring 10-500 grams per square meter in basis weight, serving functions of filtration, sound absorption, thermal management, and surface finishing in vehicle assemblies. Air filters and acoustic insulation command the dominant share of product value given their non-discretionary fitment across powertrain types, while upholstery applications in electric vehicles attract faster growth as cabin architecture shifts toward flat-floor designs requiring new textile solutions. Polyester and polypropylene materials lead volume consumption due to cost-efficiency and chemical resistance, though PET recycled-content grades gain traction as OEMs harden circularity requirements.
EMA's MDR framework and REACH chemical restrictions constrain adhesive and finishing chemistries used in European automotive textiles, while EPA fuel economy standards in the United States indirectly drive lightweight nonwoven adoption through mass reduction mandates. China's GB standards on interior air quality and Japan's JIS specifications for flame resistance create layered compliance obligations for multinational suppliers. Stakeholders must monitor divergence between regional recyclability certifications and OEM-specific material passports to avoid specification misalignment.
Market Dynamics
Electric vehicle platform architectures are compressing traditional supply chains by eliminating engine compartments and demanding flat-floor cabin designs, forcing nonwoven suppliers to reengineer acoustic and thermal solutions for entirely different spatial constraints.
Growth Catalysts
- EU Green Deal circularity mandates:OEM sustainability scorecards now penalize conventional foam alternatives, redirecting procurement toward certified recycled-content nonwovens across German and French supply chains.
- Lightweighting imperatives in battery-electric architectures:Mass reduction targets for range extension are elevating spunbond and meltblown materials into structural cabin applications previously served by heavier substrates.
- China's GB standards on interior air quality:Volatile organic compound limits are accelerating substitution of leather and PVC with low-emission polyester nonwovens in domestic EV production.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyester resin prices swing with crude oil benchmarks, compressing margin visibility for converters serving annual automotive supply agreements.
- Adhesive chemistry constraints under REACH:ECHA restrictions on formaldehyde-releasing binders and flame retardants are eliminating incumbent formulation options faster than certified replacements achieve scale.
- Mechanical recycling limitations:Mixed-fiber nonwovens and multi-layer laminates resist conventional reprocessing, creating circularity gaps that OEM material passports increasingly flag.
Strategic Opportunities
- Underpenetrated Indian passenger vehicle market:Domestic OEMs are localizing cabin trim production under PLI scheme incentives, opening specification windows for acoustic nonwoven suppliers establishing technical centers in Pune and Chennai.
- Vehicle-to-grid thermal management:Battery conditioning systems require engineered nonwoven separators and insulation layers that conventional HVAC suppliers lack capacity to produce at automotive grade.
- Bio-based polyamide feedstocks:Castor oil-derived PA11 and PA610 polymers offer drop-in performance for high-temperature underhood applications with quantified carbon intensity advantages for EU CSRD reporting.
Industry Challenges
- Cross-functional material passport compliance:OEMs demand granular recycled-content documentation and carbon footprint data that legacy ERP systems cannot extract from multi-tier supplier networks.
- Tooling amortization across low-volume EV platforms:Dedicated nonwoven forming lines require seven-figure capital commitments that strain returns when annual vehicle programs fall below 50,000 units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Nonwoven Fabrics Market |
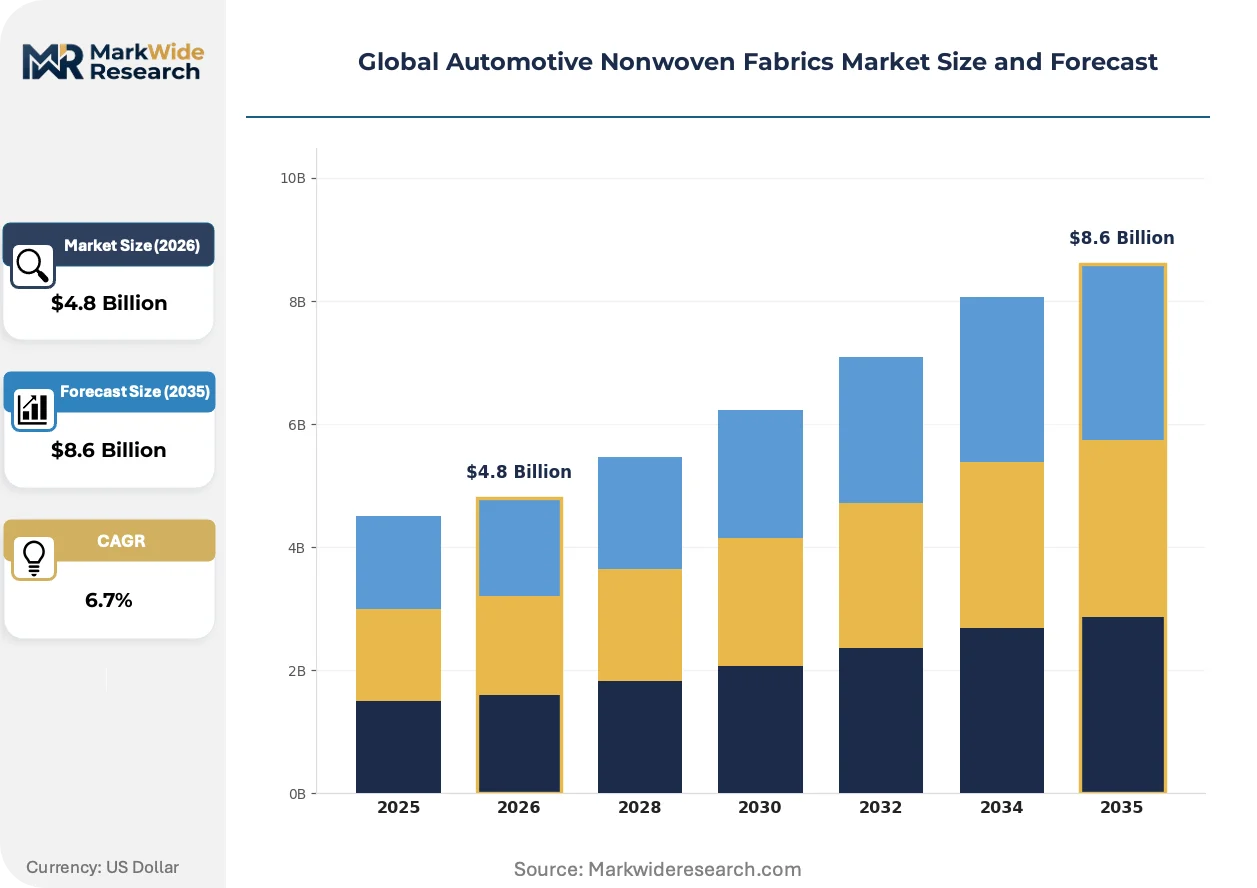
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Filters, Acoustic Insulation, Carpet, Upholstery Application: Interior, Exterior, Engine Compartment, Sound Deadening End User: OEMs, Tier-1 Suppliers, Aftermarket, Dealerships Material: Polyester, Polypropylene, PET, Viscose |
| Companies Covered | Freudenberg Performance Materials, Ahlstrom-Munksjö, Kimberly-Clark Corporation, DuPont de Nemours, Toray Industries, Mitsui Chemicals, Berry Global Group, Asahi Kasei Corporation, Hollingsworth & Vose Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Nonwoven Fabrics Market Emerging Trajectories
Material science breakthroughs are converging with digital manufacturing methods to compress development cycles and enable mass customization of functional nonwoven structures for heterogeneous EV cabin architectures.
Spunlace-hydroentangled cotton-polyester blends are electrifying premium seating applications by delivering leather-like tactile properties at 40% lower mass, with Volvo and BMW design studios specifying these materials for flagship EV launches scheduled across 2025-2027 production windows. Tier-1 seating suppliers are consolidating finishing and cutting operations to capture value that previously leaked to leather processors.
REACH MDR framework amendments are tightening chemical migration limits for cabin air filtration media, compelling Ahlstrom-Munksjö and comparable suppliers to validate alternative wet-laid binder systems through extended aging protocols. German KBA type-approval timelines have extended by four to six months for new filtration constructions, compressing competitive windows for unvalidated entrants.
Consolidated procurement through OEM direct material passports is disintermediating traditional Tier-2 nonwoven distributors, with Volkswagen Group and Stellantis mandating supplier-of-record status for recycled-content certification. Chinese EV specialists including NIO and XPeng are adopting parallel qualification pathways that favor domestic spunbond producers with integrated fiber-to-fabric operations in Jiangsu and Zhejiang provinces.
Global Automotive Nonwoven Fabrics Market Segmentation
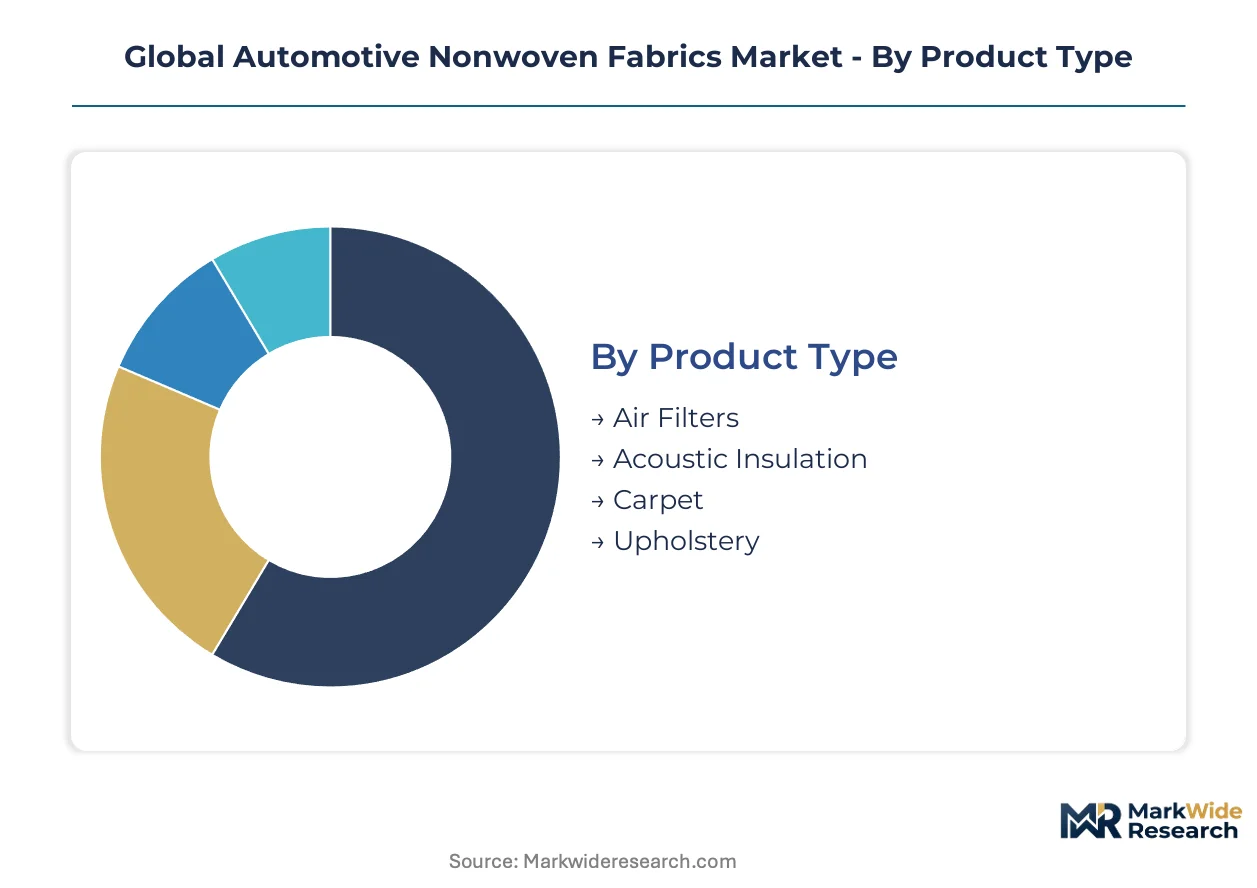
Segmentation in automotive nonwovens reveals how certification burdens and specification complexity concentrate value in certain product configurations. Understanding these divides exposes where margin pools form and which material platforms command pricing power across divergent OEM sustainability requirements.
Product Type:
Certification intensity varies sharply across product categories, with filtration media facing EMA MDR migration limits while acoustic solutions navigate KBA type-approval timelines that extend development cycles by months.
- Air Filters:Wet-laid synthetic media bonded with alternative chemistries to meet REACH formaldehyde restrictions. Demand concentrates in German supply chains where Volkswagen Group and Stellantis mandate recycled-content certification through direct material passports.
- Acoustic Insulation:Spunbond and meltblown laminates engineered for flat-floor EV architectures eliminating traditional engine compartments. Chinese EV specialists NIO and XPeng are qualifying domestic suppliers from Jiangsu and Zhejiang provinces for these applications.
- Carpet:Needle-punched polyester backings with low-VOC emissions meeting China's GB interior air quality standards.
- Upholstery:Spunlace cotton-polyester blends specified by Volvo and BMW design studios for premium EV seating launches.
Leading the category by volume: Air Filters. Growing fastest: Acoustic Insulation.
Application:
Cost tier stratification separates mass-market interior fitments from specialized underhood thermal management commanding premium pricing.
- Interior:Cabin trim components spanning headliners, door panels, and seating substrates where low-emission polyester nonwovens displace leather and PVC under Chinese GB standards. OEM sustainability scorecards now penalize conventional foam alternatives across German and French procurement.
- Exterior:Wheel arch liners and underbody shields requiring UV-stabilized polypropylene with flame-retardant chemistries constrained by ECHA restrictions on incumbent formulations.
- Engine Compartment:High-temperature nonwoven separators for battery conditioning systems in vehicle-to-grid thermal management applications.
- Sound Deadening:Multi-layer laminates facing mechanical recycling limitations that OEM material passports increasingly flag as circularity gaps.
Interior applications generate the highest absolute volume. Exterior applications face the steepest regulatory headwinds.
End User:
Customer type determines specification authority and documentation burden, with OEM direct material passports disintermediating traditional Tier-2 distribution channels.
- OEMs:Volkswagen Group and Stellantis now mandate supplier-of-record status for recycled-content certification, consolidating procurement through direct material passports that demand granular carbon footprint data legacy ERP systems cannot extract.
- Tier-1 Suppliers:Seating and trim specialists consolidating finishing and cutting operations to capture value previously leaked to leather processors, requiring spunlace-hydroentangled material qualification.
- Aftermarket:Replacement filtration media subject to extended aging protocols under amended REACH MDR frameworks.
- Dealerships:Accessory and upgrade applications with lighter certification requirements but price-sensitive volume.
OEMs dominate specification authority. Tier-1 Suppliers are gaining procurement leverage through consolidated operations.
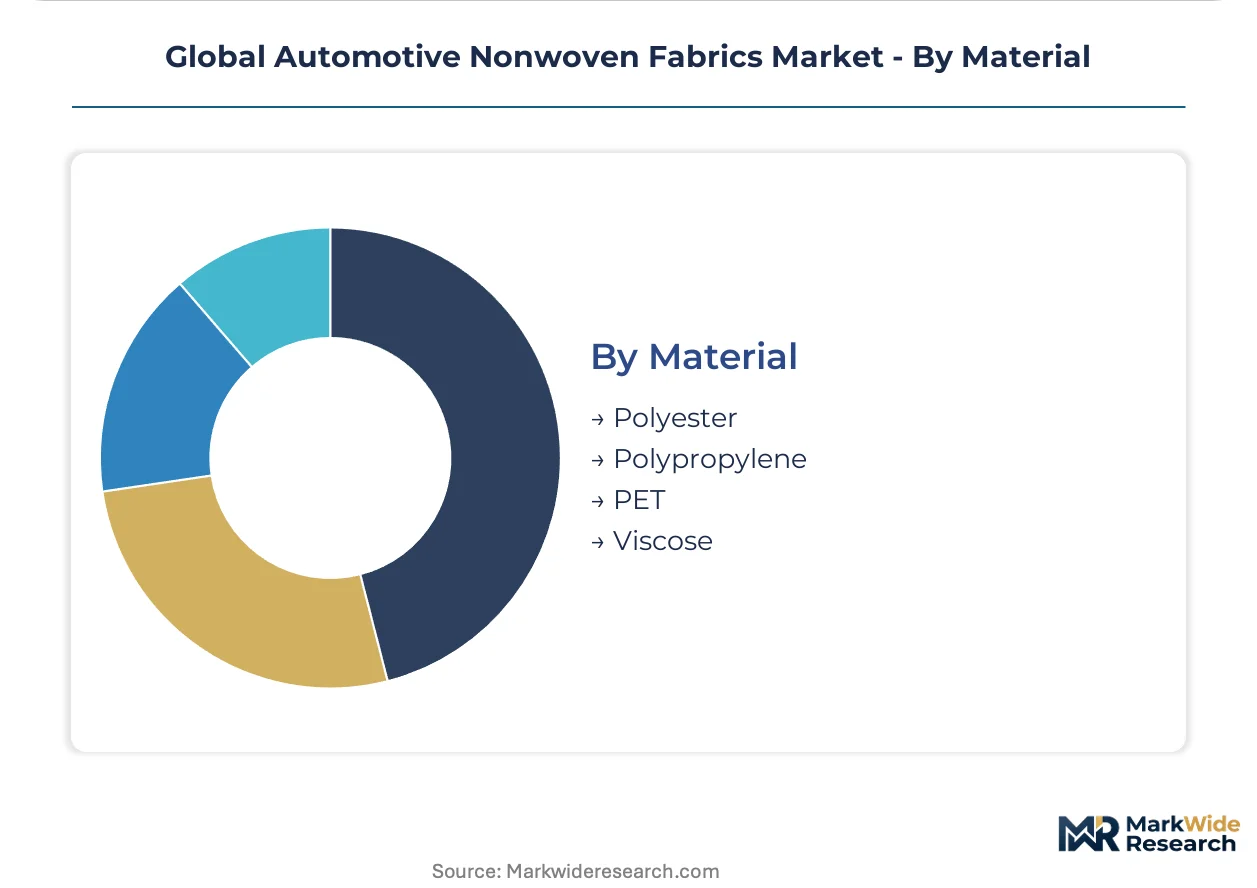
Material:
Supply concentration in petrochemical feedstocks creates margin volatility that bio-based alternatives exploit for carbon intensity reporting advantages.
- Polyester:PET recycled-content grades gain traction as circularity requirements harden, though mixed-fiber constructions resist conventional reprocessing. Freudenberg Performance Materials leverages spunbond technology leadership for acoustic insulation meeting EU Green Deal specifications.
- Polypropylene:Cost-efficient volume leader for interior applications with chemical resistance suited to underhood environments, exposed to crude oil benchmark price swings.
- PET:Recycled-content variants differentiated for OEM sustainability scorecards with quantified carbon intensity advantages.
- Viscose:Cellulosic alternative for premium tactile applications in spunlace constructions.
Polyester leads by installed volume. Bio-based polyamide feedstocks are climbing fastest in high-temperature segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European nonwoven specification activity where OEM sustainability scorecards now mandate recycled-content certification for cabin components. This industrial corridor concentrates spunbond technology deployment for acoustic insulation serving flat-floor EV architectures.
United States
EPA fuel economy standards indirectly elevate lightweight nonwoven adoption through mass reduction mandates for battery-electric range extension. California Air Resources Board recyclability specifications reshape supplier qualification pathways for acoustic and filtration media. Detroit-area technical centers coordinate Tier-1 consolidation of finishing operations previously outsourced to leather processors.
Germany
KBA type-approval timelines extend four to six months for new filtration constructions under amended REACH MDR framework migration limits. EU Green Deal circularity mandates redirect procurement toward certified recycled-content grades across Volkswagen Group and Stellantis supply chains. Freudenberg Performance Materials leverages spunbond leadership from Weinheim facilities to meet these specifications.
China
GB standards on interior air quality accelerate substitution of leather and PVC with low-emission polyester nonwovens in domestic EV production. NIO and XPeng adopt qualification pathways favoring Jiangsu and Zhejiang spunbond producers with integrated fiber-to-fabric operations. Dual carbon goals harden circularity requirements for material passports in premium vehicle programs.
India
PLI scheme incentives localize cabin trim production for domestic OEMs expanding passenger vehicle capacity. BIS standards on automotive textiles create compliance frameworks that multinational suppliers must navigate for market entry. Pune and Chennai technical centers anchor acoustic nonwoven specification windows as production scales toward export readiness.
Japan
JIS specifications for flame resistance constrain adhesive and finishing chemistries in underhood thermal management applications. METI carbon neutrality targets elevate bio-based polyamide feedstocks for high-temperature battery conditioning systems. Toray Industries and Asahi Kasei anchor domestic supply chains serving hybrid powertrain filtration demand.
Global Automotive Nonwoven Fabrics Market Vendor Landscape
The competitive structure tilts toward diversified materials conglomerates with captive fiber production and specialized nonwoven converters serving automotive qualification pathways. Tier-1 seating and trim suppliers consolidate finishing operations to capture value previously leaked to leather processors. Three archetypes dominate: integrated petrochemical-to-fabric operators, spunbond technology specialists, and premium-tier bio-based material innovators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs mandate supplier-of-record status for recycled-content certification.
Among diversified materials conglomerates, Freudenberg Performance Materials and DuPont de Nemours exemplify archetypes positioned around technology leadership and bio-based innovation respectively. Freudenberg anchors spunbond deployment for acoustic insulation meeting EU Green Deal specifications from German manufacturing bases. DuPont occupies a position within premium-tier supply chains through bio-based polyamide nonwovens targeting OEM sustainability scorecards with quantified carbon intensity advantages. Ahlstrom-Munksjö represents the filtration-focused specialist archetype, anchoring wet-laid media qualification for hybrid powertrain applications under tightening ECHA chemical restrictions.
| Leading Market Players |
|---|
| Freudenberg Performance Materials |
| Ahlstrom-Munksjö |
| Kimberly-Clark Corporation |
| DuPont de Nemours |
| Toray Industries |
| Mitsui Chemicals |
| Berry Global Group |
| Asahi Kasei Corporation |
| Hollingsworth & Vose Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal circularity mandates gate qualified supply for automotive nonwoven fabrics, reserving premium-tier pricing access to converters with certified recycled-content documentation and granular carbon footprint data that legacy ERP systems struggle to extract from multi-tier supplier networks.
Pricing Analysis
Value-based pricing anchored to carbon intensity outcomes dominates premium tiers, with bio-based polyamide grades commanding markups over conventional polyester for EU CSRD reporting advantages. Price differentiation separates certified recycled-content grades from virgin material tiers, with volume scale and OEM direct material passport status as secondary drivers. Cost compression in standard-grade spunbond is intensifying because annual automotive supply agreements lock in margins despite petrochemical feedstock volatility. Mass-market OEM procurement teams exhibit highest price sensitivity, while premium EV programs prioritize sustainability scorecard compliance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German spunbond technology leadership for acoustic insulation meeting KBA type-approval timelines, creating concentration risk for European EV platform qualification. Geographic supply draws from Germany, China, and the United States, with Jiangsu and Zhejiang provinces anchoring integrated fiber-to-fabric operations for domestic Chinese EV specialists. Raw material dependencies rest on polypropylene and polyester resins, plus castor oil-derived PA11 and PA610 polymers for high-temperature applications. Tariff exposure on petrochemical feedstocks compounds margin pressure for converters. Distribution runs through OEM direct material passports that disintermediate traditional Tier-2 nonwoven distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH MDR framework amendments on chemical migration limits erect barrier-to-entry moats for filtration media suppliers with validated alternative wet-laid binder systems.
For Market Incumbents: Cement spunbond technology leadership through backward integration into recycled PET fiber production, defending against emerging domestic Chinese suppliers with integrated Jiangsu operations. Invest in technical center expansion in Stuttgart to compress KBA type-approval timelines for new acoustic constructions. Prioritize ERP system upgrades to extract granular carbon footprint data for OEM material passport compliance. For New Entrants and Emerging Players: Begin with underpenetrated acoustic insulation specifications for Indian domestic OEMs localizing cabin trim production under PLI scheme incentives in Pune and Chennai. Target vehicle-to-grid thermal management applications where battery conditioning systems require engineered nonwoven separators that conventional HVAC suppliers lack capacity to produce. Pursue qualification partnerships with NIO and XPeng through Zhejiang production bases. For Investors and Strategic Acquirers: Volkswagen Group and Stellantis mandating supplier-of-record status for recycled-content certification is the leading indicator that consolidation acceleration lies ahead. Position for five-to-ten-year viability by targeting spunbond technology specialists with captive fiber production and established OEM qualification pathways. Watch for extended KBA type-approval timelines compressing competitive windows for unvalidated filtration entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Production | Captive PET supply secures margin control against crude oil benchmark volatility for converters. |
| Technical Center Expansion in Stuttgart | Proximity to Volkswagen Group and Stellantis procurement accelerates KBA type-approval cycles. |
| Alternative Binder System Validation | REACH MDR compliance for wet-laid filtration media opens German supply chain access. |
| Integrated Fiber-to-Fabric Operations in Zhejiang | Domestic Chinese qualification pathways favor Jiangsu producers with captive polymer supply. |
| Bio-Based Polyamide Feedstock Qualification | Castor oil-derived PA11 offers quantified carbon intensity advantages for EU CSRD reporting. |
Methodological Framework
Trade association filings, customs and import-export databases, and OEM sustainability report disclosures formed the secondary backbone, cross-referenced with primary interviews spanning Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and technical directors at spunbond converters. Bottom-up modeling of content-per-vehicle metrics and top-down triangulation against vehicle production databases ensured segmentation integrity across product type, application, and material grade dimensions.
Historical trendline analysis of spunbond and meltblown capacity deployment patterns informed projection assumptions across the analysis window, with segmentation modeling spanning propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from weighted average growth contributions across these dimensions incorporated battery-electric platform penetration curves and circularity mandate implementation timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; air filtration and acoustic insulation carry tighter precision than emerging vehicle-to-grid thermal management applications given established KBA type-approval protocols. Forecasts reflect assumptions around ECHA restriction timelines, OEM sustainability scorecard weightings, and petrochemical feedstock price trajectories that could revise materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Nonwoven Polyester Fabric Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market