
 Non Woven Printing Machine Market | 2026-2036
Non Woven Printing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Non Woven Printing Machine Market Insights
Software-defined color management and remote diagnostics is rebalancing how OEMs monetize non woven printing equipment, shifting revenue from hardware sales to recurring service contracts. Koenig & Bauer AG leverages its legacy press architecture to anchor premium retrofit programs for existing flexographic installations. Bobst Group SA competes through integrated workflow platforms that synchronize die-cutting with inline printing operations. Heidelberg Druckmaschinen AG differentiates by extending its Prinect ecosystem into narrow-web non woven substrates.
A non woven printing machine applies pigmented or functional coatings onto bonded fiber webs without weaving, typically handling basis weights from 15 to 150 gsm at speeds exceeding 300 meters per minute for hygiene and packaging applications. Flexographic systems dominate volume production for diaper backsheets and surgical gown labeling due to fast changeovers and water-based ink compatibility. Digital printing occupies the fastest-expanding margin pool in personalized medical packaging and short-run promotional bags, where UV curing technology eliminates solvent emissions and reduces drying energy. Gravure retains share in wallpaper and industrial filter applications requiring fine-line reproduction on textured spunbond surfaces.
FDA oversight of medical-grade printed non wovens shapes ink biocompatibility testing protocols for surgical drape manufacturers targeting US hospital procurement. ECHA REACH restrictions on aromatic amines in textile colorants force European converters to validate water-based pigment systems through notified body assessment. China's SAMR enforces GB standards for food-contact packaging that extend to printed non woven tote bags, creating compliance barriers for imported equipment. Stakeholders must monitor how fragmented national chemical regulations fragment equipment specification sheets and complicate cross-border aftermarket parts strategies.
Market Dynamics
Software-defined color management is compressing hardware margins while expanding recurring service revenue pools for non woven printing equipment vendors. OEMs now bundle predictive maintenance subscriptions with flexographic press sales, fundamentally altering how capital expenditure converts to lifetime value.
Growth Catalysts
- REACH aromatic amine restrictions:ECHA mandates on textile colorants force European converters toward water-based pigment validation, accelerating equipment replacement cycles for compliant ink delivery systems.
- India technical textile corridor expansion:Ahmedabad and Surat clusters upgrade from manual to automated flexographic lines, creating concentrated demand for narrow-web non woven printing capacity.
- UV curing technology maturation:Medical packaging converters adopt instant-dry digital systems to eliminate solvent emissions and reduce energy intensity in cleanroom environments.
Market Restraints
- Gravure cylinder supply concentration:Fine-line engraving capacity for wallpaper and industrial filter applications concentrates among specialized European suppliers, creating bottleneck risks for textured spunbond reproduction.
- China GB standards compliance costs:SAMR food-contact packaging requirements extend to printed non woven tote bags, forcing equipment specification changes that fragment cross-border aftermarket parts strategies.
- Digital inkjet head replacement economics:UV-curable ink systems require frequent piezoelectric nozzle maintenance, elevating total cost of ownership versus flexographic anilox roller refurbishment.
Strategic Opportunities
- Personalized medical packaging white space:Hospital procurement departments seek lot-specific surgical drape labeling with patient identifiers, opening short-run digital production niches.
- Remote diagnostics platform penetration:Cloud-based color calibration and press monitoring enables OEMs to capture service revenue from installed base retrofits without geographic technician deployment.
- PLI scheme leverage in technical textiles:India's production-linked incentive framework subsidizes capital equipment for domestic non woven converters, reducing payback periods for automated printing investments.
Industry Challenges
- Flexographic platemaking skill scarcity:Water-based ink formulation expertise and photopolymer sleeve mounting competence concentrate among aging technician cohorts, constraining converter expansion timelines.
- FDA biocompatibility validation timelines:Surgical drape manufacturers face extended ink migration testing protocols before US hospital procurement approval, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non Woven Printing Machine Market |
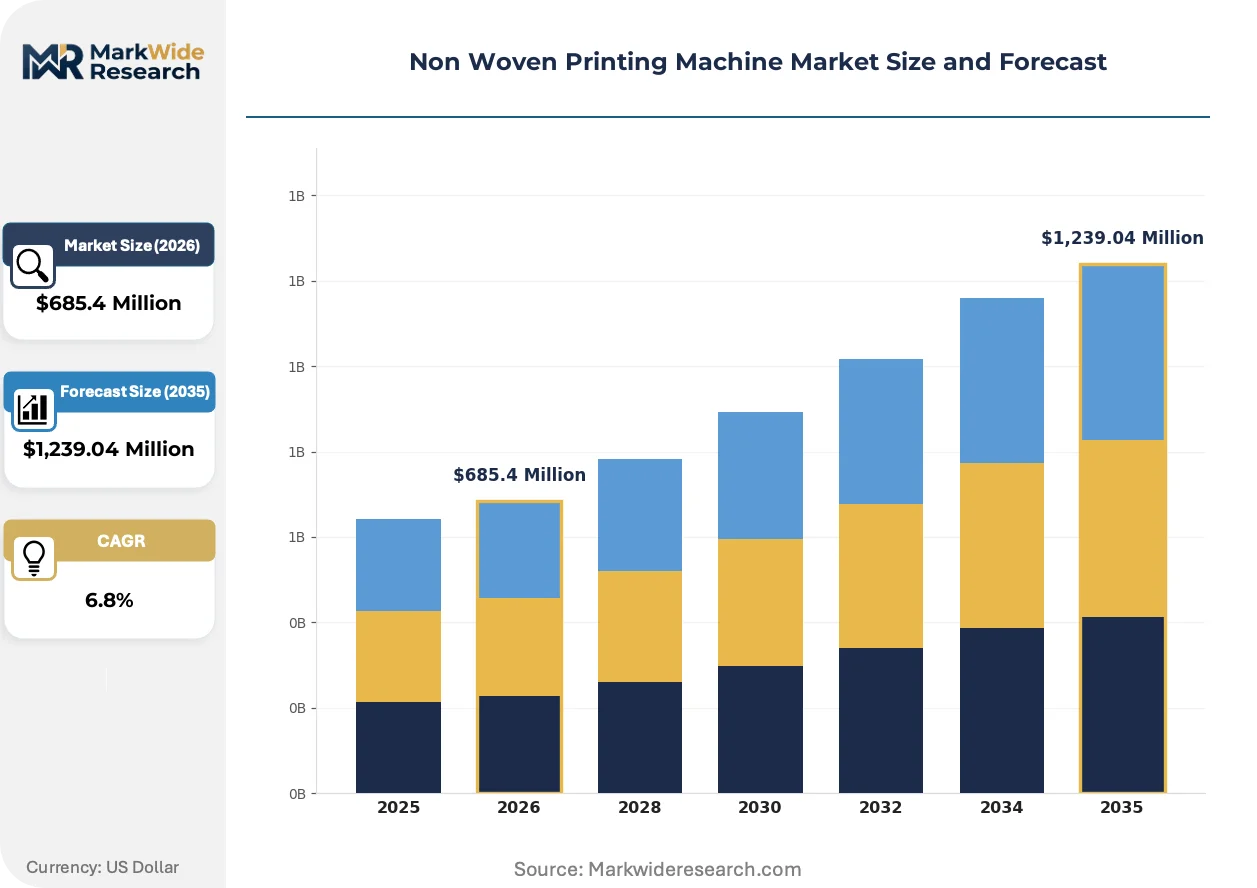
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Offset, Flexographic, Digital, Gravure Technology: UV Curing, Water-based, Solvent-based, Eco-solvent End User: Textile, Packaging, Automotive, Medical Application: Label Printing, Wallpaper, Bags, Industrial Uses |
| Companies Covered | KP TECH MACHINE, NCM Nonwoven Converting Machinery, A.Celli Nonwovens, Oyang, Bobst Group SA, Koenig & Bauer AG, Heidelberg Druckmaschinen AG, Sahil Graphics, Favourite Fab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non Woven Printing Machine Market Trends and Innovations
Digital printing architectures are fragmenting the traditional volume-margins tradeoff that favored flexographic dominance in hygiene applications. Convergence between inline finishing and color management software is compressing job changeover economics.
Single-pass UV inkjet systems are expanding into diaper backheet and wet wipe label production, displacing flexographic workflows for runs below fifty thousand linear meters. Asian hygiene manufacturers pilot these configurations for seasonal promotional variants requiring rapid graphic turnaround. The technology is expanding into territory previously reserved for rotary screen and flexographic equipment, forcing OEMs to reposition hardware portfolios around job-size thresholds rather than substrate categories.
China's GB standards for food-contact packaging safety are tightening pigment migration limits for printed non woven tote bags, compelling equipment redesigns for ink curing temperature control. SAMR enforcement extends compliance obligations to imported machinery, creating specification divergence between domestic and export-oriented production lines. European converters serving multinational brand owners now demand dual-certification capability as standard equipment configuration.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, treating color management subscriptions as separate operational expenditures. This shift compresses upfront hardware margins while extending vendor revenue visibility across press lifecycles. The pattern is most visible in North American surgical drape manufacturing, where group purchasing organizations negotiate multi-site predictive maintenance agreements independent of initial machine acquisition.
Non Woven Printing Machine Market Segmentation
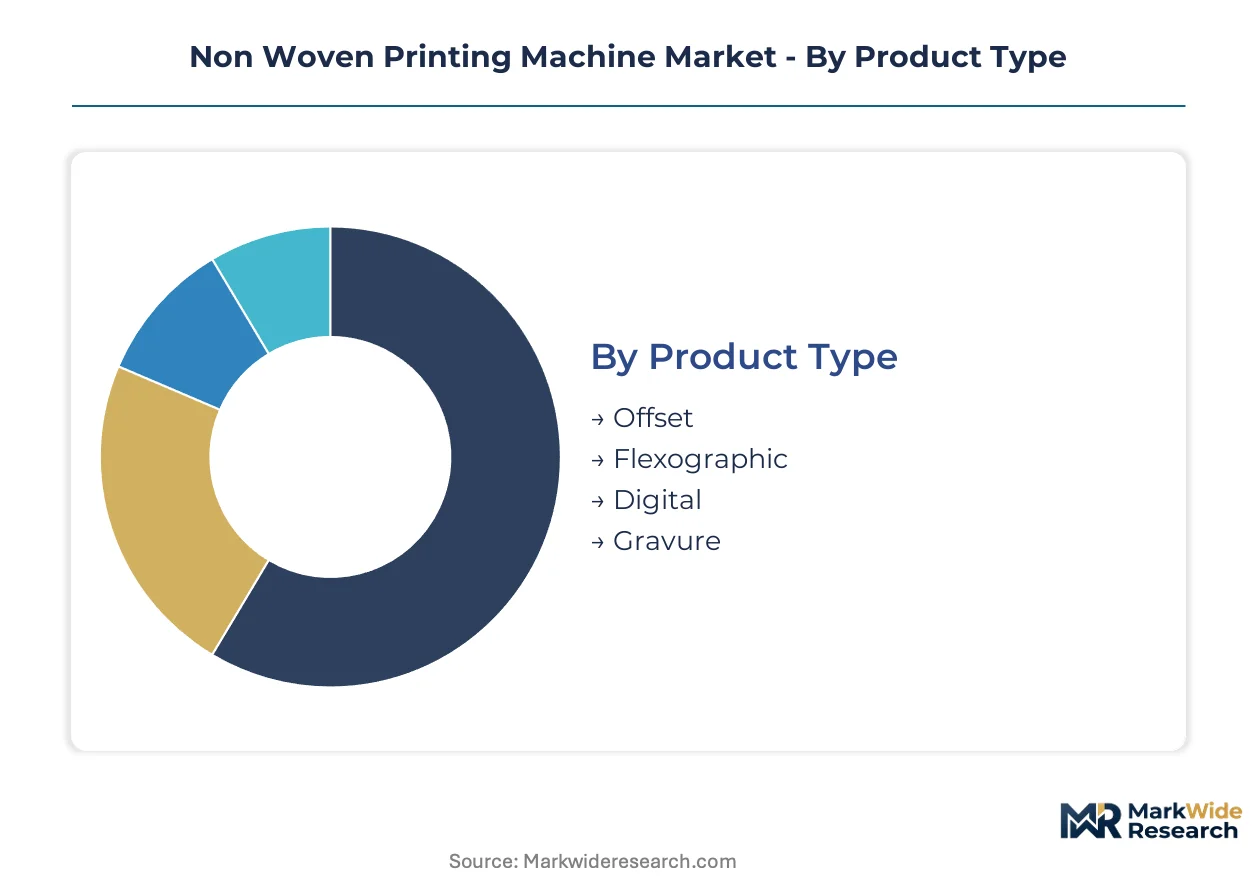
Non woven printing equipment selection hinges on substrate basis weight, production volume thresholds, and regulatory compliance requirements specific to end-use applications. Buyers prioritize different performance vectors: hygiene manufacturers chase changeover speed, medical converters demand biocompatibility validation, and packaging specialists balance ink migration limits against graphic complexity.
Product Type:
Equipment buyers differentiate primarily by run-length economics and graphic reproduction requirements rather than capital outlay alone.
- Flexographic:Rotary letterpress systems with photopolymer plates dominate diaper backsheet and surgical gown labeling. Ahmedabad and Surat converters upgrade manual lines to automated narrow-web flexographic configurations for wet wipe production.
- Digital:Single-pass UV inkjet architectures eliminate solvent emissions and enable lot-specific medical packaging with patient identifiers. Hospital procurement departments unbundle these systems for short-run surgical drape applications where changeover speed trumps unit economics.
- Offset:Lithographic transfer methods suit high-volume spunbond wallpaper requiring fine-line reproduction on textured surfaces. European suppliers concentrate engraving capacity for cylinder-dependent workflows.
- Gravure:Intaglio cylinder systems retain industrial filter and decorative wallcovering applications where ink film thickness and durability specifications exceed flexographic capabilities.
Flexographic systems lead volumes today; Digital is gaining share fastest.
Technology:
Ink curing chemistry determines compliance pathways across divergent regulatory regimes and cleanroom requirements.
- Water-based:Pigment dispersions in aqueous carriers serve diaper backsheet and food-contact tote bag applications. ECHA REACH aromatic amine restrictions force European converters toward validated water-based pigment systems with notified body assessment.
- UV Curing:Photoinitiator-triggered polymerization enables instant-dry processing in medical packaging cleanrooms. China's SAMR enforces GB standards for food-contact packaging that extend curing temperature control specifications to imported equipment.
- Solvent-based:Volatile organic compound carriers retain wallpaper and industrial filter segments where substrate compatibility and adhesion properties outweigh emissions constraints.
- Eco-solvent:Reduced-VOC formulations bridge regulatory gaps in promotional bag applications requiring outdoor durability without full UV infrastructure investment.
Water-based formulations dominate installed base; UV Curing shows the steepest expansion trajectory.
End User:
Vertical application requirements fragment equipment specifications across hygiene, healthcare, and industrial durability standards.
- Medical:Surgical drape and gown manufacturers face FDA biocompatibility validation timelines for ink migration testing before US hospital procurement approval. Digital systems capture lot-specific labeling demand from group purchasing organizations.
- Packaging:Food-contact and promotional bag converters navigate China's GB standards for pigment migration limits. Dual-certification capability becomes standard equipment configuration for European suppliers serving multinational brand owners.
- Textile:Technical textile corridors in India leverage PLI scheme subsidies for automated flexographic investments in domestic non woven converter operations.
- Automotive:Interior trim and filtration applications require gravure-class fine-line reproduction on spunbond substrates with thermal and abrasion resistance specifications.
Packaging commands the largest equipment installed base; Medical is climbing the fastest.
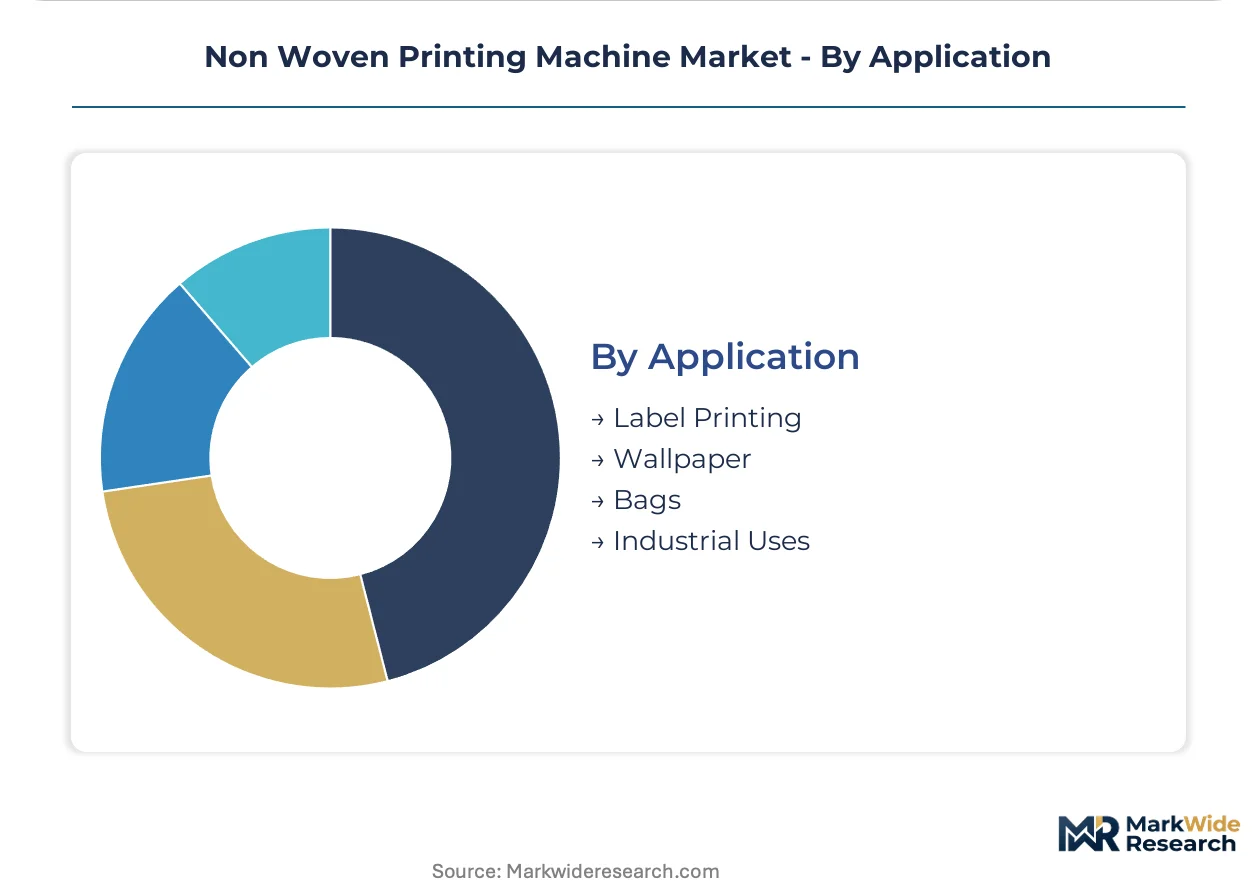
Application:
Job size thresholds and graphic complexity determine technology matching more than substrate category alone.
- Label Printing:Wet wipe and hygiene product branding requires rapid changeover capability for seasonal promotional variants. Asian manufacturers pilot single-pass UV inkjet for runs below fifty thousand linear meters.
- Industrial Uses:Filter media and technical textile applications demand gravure-class cylinder engraving for fine-line reproduction on textured spunbond surfaces.
- Wallpaper:Decorative wallcovering segments retain offset and gravure workflows for high-volume, complex graphic reproduction.
- Bags:Non woven tote production for retail and food-contact applications faces China's SAMR enforcement extending compliance obligations to imported machinery.
Label Printing leads current equipment deployment; Industrial Uses are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed base of non woven printing equipment, while India posts the fastest capacity expansion as technical textile corridors automate legacy manual lines.
China
SAMR enforces GB standards for food-contact packaging that extend to printed non woven tote bags, compelling equipment redesigns for ink curing temperature control. The Yangtze River Delta hosts concentrated converter operations upgrading flexographic lines for export-compliant production.
India
Ahmedabad and Surat technical textile clusters drive concentrated demand as domestic converters transition from manual to automated narrow-web flexographic systems. The PLI scheme subsidizes capital equipment for non woven printing investments, shortening payback periods for automated lines.
Germany
ECHA REACH aromatic amine restrictions force converters toward water-based pigment validation with notified body assessment. Baden-Württemberg and North Rhine-Westphalia house specialized gravure cylinder engraving capacity serving wallpaper and industrial filter segments.
United States
FDA biocompatibility validation timelines for surgical drape ink migration testing compress product launch windows for medical converters. Group purchasing organizations in the Midwest and Southeast negotiate multi-site predictive maintenance agreements independent of initial equipment acquisition.
Italy
Lombardy and Emilia-Romagna maintain legacy offset and gravure workflows for high-volume decorative wallcovering production. CE marking requirements under EU machinery directives shape equipment specification sheets for export-oriented manufacturers serving multinational brand owners.
Non Woven Printing Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated workflow providers capturing premium positioning in medical and hygiene applications while regional fabricators serve price-sensitive packaging converters. The vendor base organizes into three strategic archetypes: European precision engineering houses with legacy press architectures, Asian equipment specialists leveraging cost-advantaged manufacturing, and integrated solutions providers bundling software-defined color management. Dominant competitive moves include predictive maintenance subscription bundling and geographic expansion through distributor partnerships in emerging technical textile corridors.
Among European precision engineering houses, Koenig & Bauer AG and Heidelberg Druckmaschinen AG occupy positions anchored in legacy press architectures and extended ecosystem platforms. Bobst Group SA exemplifies the integrated solutions archetype through workflow platforms that synchronize inline finishing operations. These three represent distinct strategic postures: retrofit program anchoring, ecosystem extension, and workflow integration.
| Leading Market Players |
|---|
| KP TECH MACHINE |
| NCM Nonwoven Converting Machinery |
| A.Celli Nonwovens |
| Oyang |
| Bobst Group SA |
| Koenig & Bauer AG |
| Heidelberg Druckmaschinen AG |
| Sahil Graphics |
| Favourite Fab |
| Others |
Pricing and Supply Chain Analysis
Single-pass UV inkjet adoption in Asian hygiene manufacturing is compressing unit economics for short-run production while redistributing margin capture toward digital ink suppliers and remote service platforms. This technology transition simultaneously elevates capital requirements for converters and fragments pricing power across equipment tiers.
Pricing Analysis
Capacity additions in India are reshaping price floors for narrow-web flexographic configurations as PLI-subsidized domestic production undercuts imported European systems. Three-tier pricing structure across premium, standard, and economy levels separates Heidelberg-Koenig & Bauer retrofit programs from mid-tier Asian specialists and regional fabricators. Pricing pressure stems from software-defined color management subscriptions unbundling from hardware sales. Mid-tier packaging converters in China exhibit highest price sensitivity; medical-grade system buyers prioritize FDA validation over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Mumbai anchor hub-and-spoke patterns for spare parts and consumables. Component sourcing concentrates in Germany for precision press architectures, China for UV curing modules, and Japan for piezoelectric inkjet heads. Raw material dependencies include photopolymer plate resins, anilox roller ceramics, and UV-curable ink photoinitiators. Single-source vulnerability runs through gravure cylinder engraving capacity concentrated among Baden-Württemberg specialists. Distribution runs through authorized dealer networks with direct OEM relationships for medical-grade installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hospital procurement unbundling of service contracts and FDA biocompatibility validation requirements favor incumbents with installed base scale and regulatory dossiers.
For Market Incumbents: Anticipate margin compression from Asian digital specialists by accelerating predictive maintenance subscription penetration among existing flexographic installations. Defensive consolidation through gravure cylinder engraving capacity acquisition in Germany addresses bottleneck risks. Certification investment in dual GB-REACH compliance capability captures multinational brand owner specification requirements. For New Entrants and Emerging Players: The price-point gap between premium European retrofit programs and economy-tier regional fabricators opens white-space targeting of mid-tier Indian technical textile converters upgrading from manual lines. Short-run digital medical packaging for hospital group purchasing organizations represents the most penetrable application segment. Go-to-market leverage through PLI scheme qualification advisory services accelerates customer acquisition in Ahmedabad-Surat corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among Asian equipment specialists lacking software-defined color management platforms but possessing cost-advantaged manufacturing footprints. Long-term viability over the next decade hinges on recurring service revenue capture rather than hardware shipment volumes. Acquisition target archetype: regional fabricators with established dealer networks and pending UV curing technology partnerships. The signal to watch is unbundling penetration rates in North American surgical drape manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Captures recurring revenue from Heidelberg and Koenig & Bauer installed bases without geographic technician deployment. |
| Dual-Certification Equipment Configuration | Enables European suppliers to serve multinational brand owners navigating both REACH and GB standards compliance. |
| Gravure Cylinder Engraving Acquisition | Secures bottlenecked fine-line reproduction capacity for wallpaper and industrial filter applications in Germany. |
| PLI Scheme Partnership Structuring | Accelerates capital equipment sales to Indian technical textile converters in Ahmedabad and Surat corridors. |
| UV Curing Technology Licensing | Bridges regulatory gaps for mid-tier Asian manufacturers seeking medical packaging cleanroom qualification. |
Research Methodology
Multiple input streams — equipment OEM technical directors, converter plant managers in hygiene and medical segments, aftermarket service heads, and regulatory compliance officers — were reconciled against secondary validation. Primary interviews with Heidelberg, Koenig & Bauer, and Bobst Group product strategists supplemented field conversations with Ahmedabad flexographic operators and Midwest surgical drape manufacturers. Secondary sources included ECHA REACH substance restriction databases, FDA 510(k) premarket notification filings for medical-grade inks, SAMR GB standard compliance bulletins, and Indian PLI scheme technical textile disbursement records. Bottom-up equipment shipment tallies and top-down addressable market sizing were triangulated for convergence.
Historical capacity installation patterns were cross-referenced against panel input from GPO procurement managers and hospital biomedical engineering directors to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include printing technology type, ink curing chemistry, end-use vertical, and geographic production cluster. CAGRs were derived from equipment replacement cycle analysis and regulatory-driven upgrade elasticity estimates. Industry-specific forecast inputs incorporated UV curing technology maturation curves and REACH aromatic amine restriction implementation timelines.
Caveats apply where FDA biocompatibility validation timeline extensions or SAMR GB standards enforcement intensity could materially shift the outlook for medical and food-contact packaging equipment demand. Forecasts reflect documented assumptions regarding PLI scheme continuity and ECHA restriction scope. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Nonwoven Fabric Production Line Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
Absorbable Nonwoven Textiles Market
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Nonwoven Blanket Market