
 Cellulose Fiber Market | 2026-2036
Cellulose Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Fiber Market Analysis
Subscription-based fiber certification and traceability software is restructuring how cellulose fiber value gets captured and communicated downstream. Lenzing AG leverages its TENCEL branded fiber platform to sustain premium positioning across European and Asian textile supply chains. Grasim Industries anchors large-scale viscose staple capacity in India, while Sateri competes through integrated dissolving pulp operations in China.
Cellulose fiber comprises regenerated and purified carbohydrate chains derived from wood pulp, cotton linters, or agricultural residues, typically exhibiting tenacities of 2.0–3.5 g/denier and moisture regain near 13%, serving primarily as renewable feedstock for textiles, absorbents, and engineered composites. Viscose staple fiber still occupies the largest volume share across global production, though lyocell variants are gaining share where closed-loop solvent recovery meets stricter effluent rules. Filament fiber forms command higher unit values in luxury apparel applications, while nonwoven formats are expanding fastest in hygiene and medical end uses.
EU REACH restrictions on carbon disulfide emissions and the EU Green Deal deforestation-free supply chain rules are reshaping import eligibility for Asian viscose producers selling into European textile markets. China's MEE enforces wastewater discharge limits on dissolving pulp mills that feed domestic rayon complexes. The US EPA monitors air emissions from specialty cellulose acetate operations used in cigarette filters and plastics compounding. Stakeholders must track evolving chemical process standards and verify chain-of-custody documentation before committing to multi-year pulp supply agreements.
Market Dynamics
Closed-loop solvent recovery systems are compressing capital cycles for lyocell producers while EU REACH carbon disulfide limits force viscose operators into costly effluent retrofits. This dual pressure is splitting competitive advantage between integrated pulp-fiber complexes and standalone spinners.
Growth Catalysts
- EU Green Deal deforestation-free rules:Import verification mandates are filtering non-compliant Asian viscose from European textile supply chains, rewarding certified producers with preferential offtake terms.
- Hygiene nonwoven expansion:Flushable wipes and medical-grade absorbents are pulling lyocell staple into spunlace lines previously dominated by petroleum-based fibers.
- China's MEE wastewater standards:Tighter dissolved organic carbon limits on dissolving pulp mills are accelerating consolidation toward integrated pulp-to-rayon complexes.
Market Restraints
- Dissolving pulp price volatility:Hardwood pulp feedstock swings of 20-40% annually compress viscose margins for non-integrated spinners lacking captive pulp supply.
- Carbon disulfide regulatory friction:EU REACH emission caps and China's MEE air quality rules impose dual compliance burdens on conventional viscose producers without closed-loop chemistry.
- Polyester substitution threat:Recycled PET fiber pricing below virgin lyocell is capturing share in mass-market apparel where moisture management is secondary.
Strategic Opportunities
- India textile cluster penetration:Tiruppur and Surat apparel hubs are scaling lyocell blends for EU export orders seeking sustainable fiber content credentials.
- Automotive interior applications:Seat upholstery and headliner substrates represent an emerging offtake channel as OEMs specify renewable fiber content for scope 3 reporting.
- Textile-to-textile recycling convergence:Chemical depolymerization of cotton-lyocell blends is creating circular feedstock loops that qualify for EU Green Deal circular economy incentives.
Industry Challenges
- Closed-loop engineering talent scarcity:N-methylmorpholine-N-oxide solvent recovery system design and operation requires specialized chemical engineering expertise concentrated in Austrian and Chinese engineering centers.
- FSC and PEFC chain-of-custody certification timelines:Multi-year audit cycles for forest stewardship documentation delay market access for new pulp suppliers seeking European textile qualification.
- Legacy viscose asset retrofit complexity:Converting aging carbon disulfide-based spinning lines to lyocell-capable equipment demands extended shutdown periods and parallel production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Fiber Market |
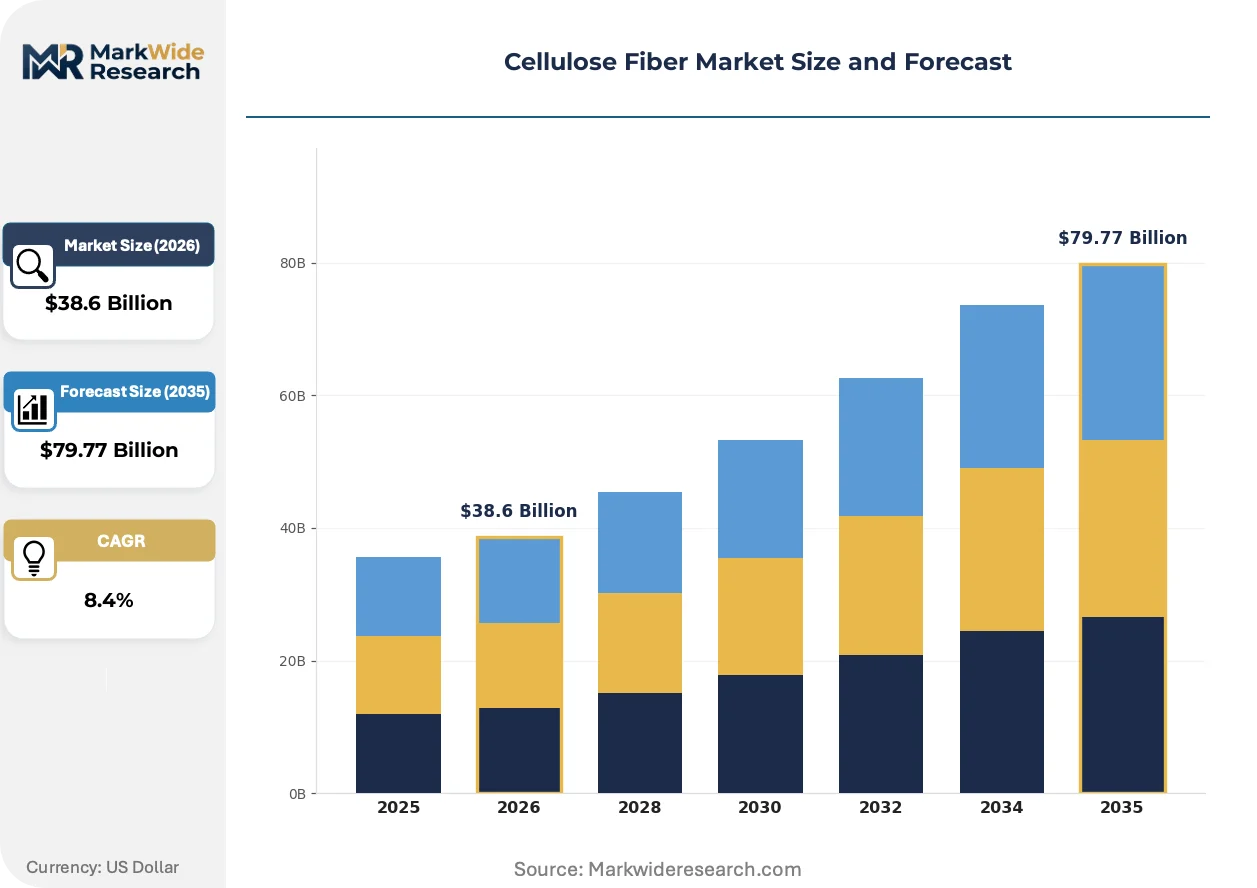
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscose, Lyocell, Acetate, Microfiber End Use Industry: Textiles, Paper, Plastics, Composites Form: Staple Fiber, Filament Fiber, Sheet, Nonwoven Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Sappi Limited, Fulida Group Holding Co. Ltd, Lenzing AG, Rayonier Advanced Materials, Kelheim Fibres GmbH, Sateri, Grasim Industries, Aditya Birla Group, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Fiber Market Emerging Trajectories
Digital fiber passport systems and blockchain traceability are restructuring how cellulose fiber provenance gets verified and monetized downstream. These technologies are compressing information asymmetries between pulp sources and finished goods brands.
Lyocell production technology is modularizing around smaller-scale, containerized solvent recovery units that slash minimum efficient scale thresholds. Regional textile clusters in Vietnam and Bangladesh are piloting these compact systems for 10,000-tonne annual capacity rather than 100,000-tonne legacy installations. This distributed model is compressing capital barriers and enabling faster geographic diversification away from concentrated Chinese supply.
EU REACH restrictions on carbon disulfide emissions are forcing viscose producers into emission control retrofits or process abandonment. The regulation's industrial consequence is a bifurcation between European market access and exclusion. Asian viscose spinners serving EU apparel brands are responding with closed-loop chemistry investments or pivoting toward lyocell conversion.
Brand-led fiber certification is displacing generic commodity procurement in premium apparel channels. European fashion houses are mandating CanopyStyle and FSC documentation as standard purchase order terms, bypassing traditional spot-market purchasing. This specification shift is most visible in German and Nordic retail supply chains where scope 3 emission accounting drives material selection.
Cellulose Fiber Market Segmentation
Cellulose fiber procurement patterns diverge sharply across product chemistries and end-use specifications, with integrated pulp-fiber complexes capturing margin from standalone spinners unable to meet EU Green Deal chain-of-custody requirements.
Product Type:
Equipment replacement cycles and chemistry retrofits are splitting competitive advantage between legacy viscose assets and lyocell-capable installations.
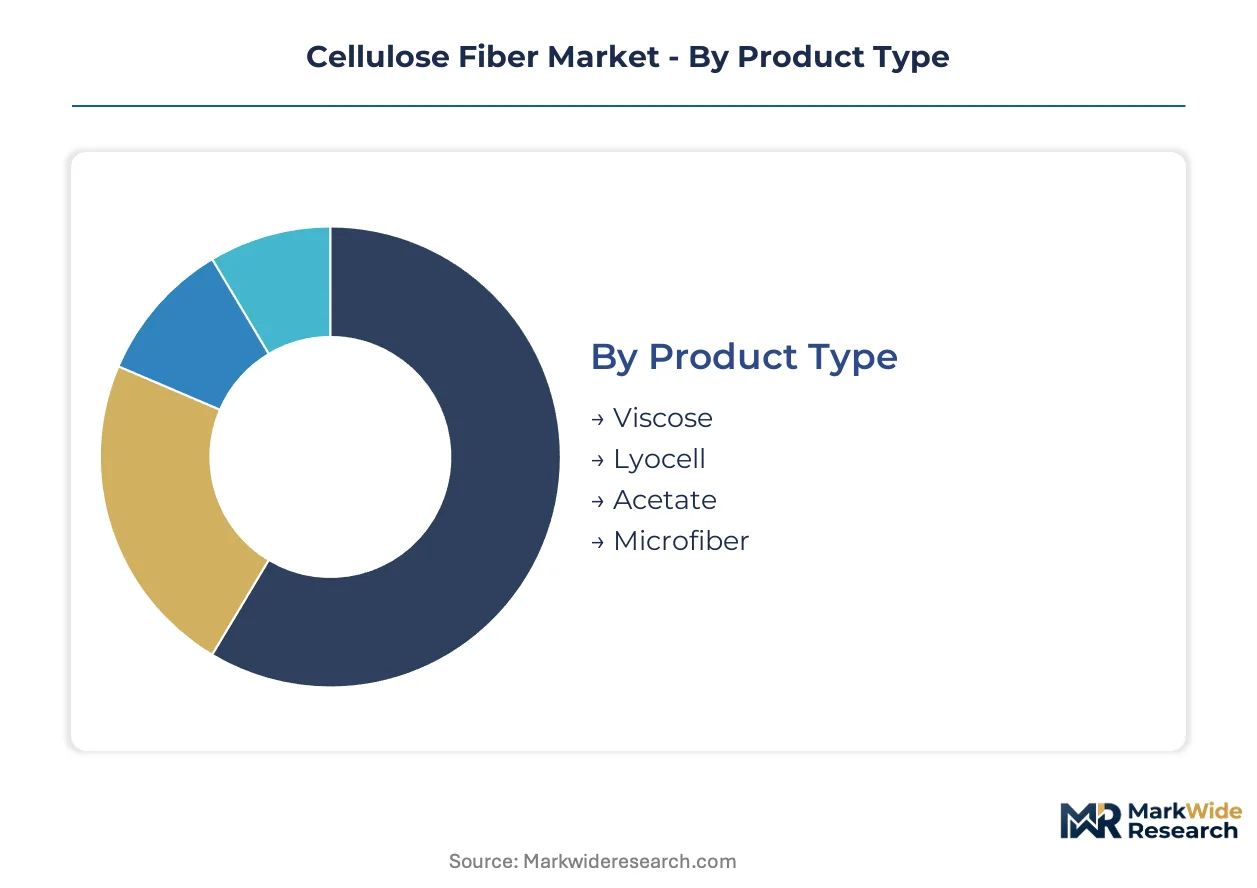
- Viscose:Regenerated fiber produced through carbon disulfide xanthation of alkali cellulose, yielding tenacities of 2.0–2.5 g/denier. Indian and Indonesian textile mills consume the largest volumes for mass-market apparel, though EU REACH emission caps now force costly effluent retrofits or market exclusion.
- Lyocell:Solvent-spun fiber manufactured via direct cellulose dissolution in N-methylmorpholine-N-oxide with closed-loop recovery rates exceeding 99%. German and Austrian engineered systems supply premium European apparel brands seeking deforestation-free certification under EU Green Deal rules.
- Acetate:Esterified cellulose fiber with thermoplastic properties enabling cigarette filter and spectacle frame applications.
- Microfiber:Ultra-fine denier variants below 1.0 dtex serving technical wiping and filtration media.
Viscose sits at the top of the volume ranking, with lyocell climbing the fastest.
End Use Industry:
Application-specific performance requirements create tiered pricing structures that separate commodity absorbent grades from certified textile feedstocks.
- Textiles:Apparel, home furnishing, and technical fabric applications demanding moisture regain near 13% and controlled dye uptake. Tiruppur and Surat clusters in India scale lyocell blends for EU export orders requiring CanopyStyle documentation.
- Paper:Specialty grades including currency substrate and filter papers requiring high alpha-cellulose purity.
- Plastics:Cellulose acetate compounds for biodegradable packaging and consumer goods.
- Composites:Natural fiber reinforcement in automotive interior panels and construction materials.
Textile offtake commands the dominant revenue share, while composites gain share fastest in automotive scope 3 reporting applications.
Form:
Physical format determines processing equipment compatibility and downstream value capture, with nonwoven lines requiring distinct staple specifications versus filament throwing operations.
- Staple Fiber:Cut lengths of 38–51 mm for cotton-system spinning and airlaid nonwoven formation. Chinese integrated complexes supply both domestic spun yarn mills and export-oriented hygiene producers.
- Filament Fiber:Continuous filament yarns for luxury apparel and industrial sewing threads commanding premium unit values.
- Sheet:Regenerated cellulose films and membranes for dialysis and filtration applications.
- Nonwoven:Spunlace and needlepunch formats for medical absorbents, wet wipes, and geotextiles.
Staple fiber maintains volume leadership, with nonwoven formats expanding most quickly in flushable wipes and medical-grade absorbents.
Distribution Channel:
Supply chain configuration separates bulk commodity flows from certified specialty channels requiring documented chain-of-custody handoffs.
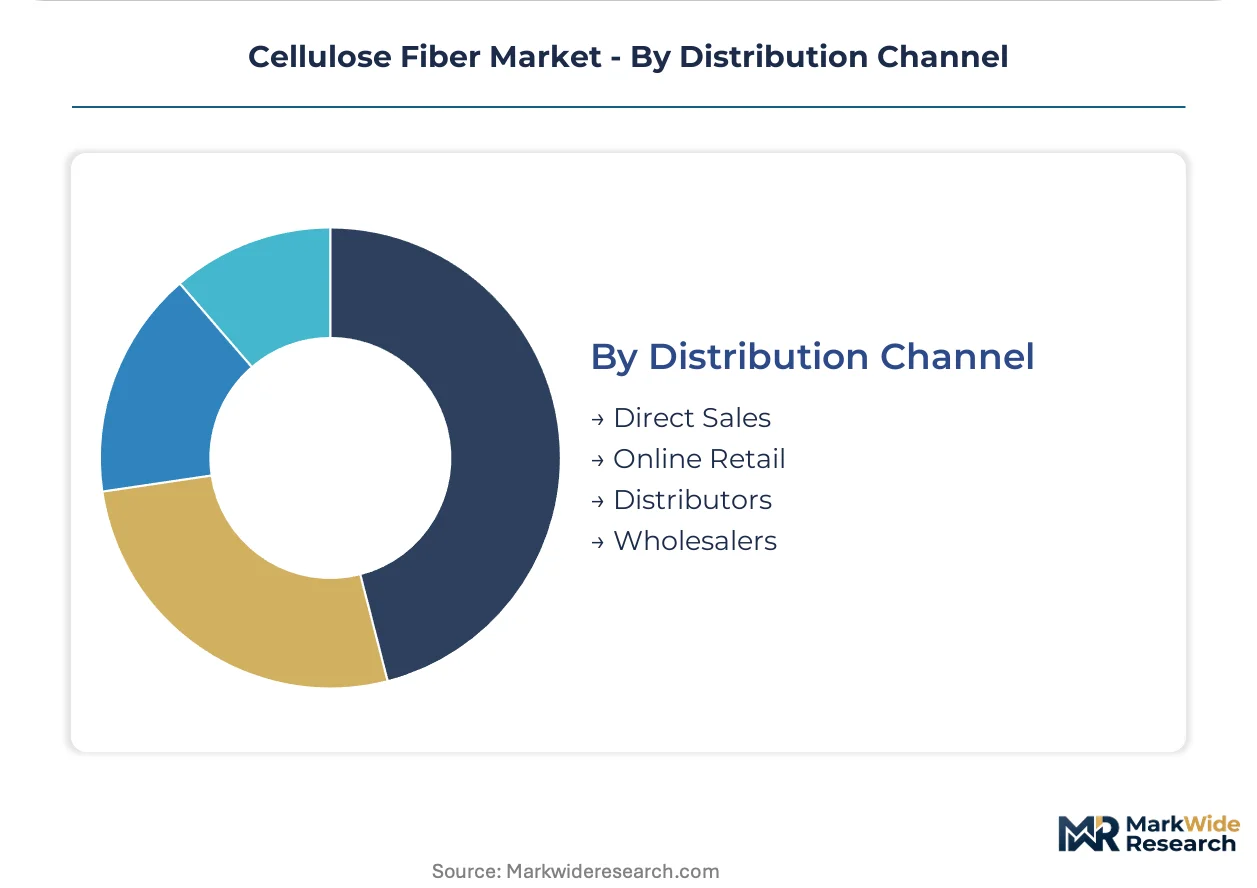
- Direct Sales:Mill-to-mill contracts for dissolving pulp and viscose staple securing volume commitments and quality specifications. Grasim Industries and Sateri anchor large-scale direct supply relationships with integrated textile producers.
- Distributors:Regional stocking points serving mid-scale spinners and nonwoven converters lacking captive pulp supply.
- Wholesalers:Aggregated spot-market purchasing for commodity grades with relaxed certification requirements.
- Online Retail:Digital platforms for specialty microfiber and small-lot acetate compounds.
Direct sales channels capture the largest transaction value, with distributor networks penetrating fastest among Vietnam and Bangladesh textile clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's integrated pulp-to-fiber complexes outproduce India's dispersed viscose spinners by an order of magnitude, yet German and Austrian engineering houses supply the closed-loop lyocell technology that commands European premium pricing.
China
Dissolving pulp mills in Shandong and Fujian provinces feed captive rayon complexes serving domestic textile mills and export-oriented nonwoven producers. MEE wastewater discharge limits on dissolved organic carbon are accelerating consolidation toward integrated pulp-to-fiber operations. Sateri anchors large-scale viscose staple capacity across coastal provinces.
India
Tiruppur and Surat apparel clusters scale lyocell blends for EU export orders requiring CanopyStyle and FSC documentation. BIS textile standards and DGFT export incentive schemes shape fiber procurement patterns for integrated spinners. Grasim Industries anchors viscose staple supply relationships across Maharashtra and Gujarat textile belts.
Germany
EU REACH carbon disulfide emission caps filter non-compliant Asian viscose from European supply chains, rewarding certified producers with preferential offtake terms. ECHA chemical safety protocols tighten feedstock verification requirements for wood-pulp-derived fibers. Engineering firms in Baden-Württemberg supply closed-loop solvent recovery systems to global lyocell operators.
Austria
Lenzing AG leverages its TENCEL branded fiber platform to sustain premium positioning across European and Asian textile supply chains. EU Green Deal deforestation-free supply chain rules mandate chain-of-custody documentation for pulp sourcing. The country's chemical engineering expertise concentrates in specialized N-methylmorpholine-N-oxide solvent recovery system design.
Indonesia
Mass-market apparel mills consume large viscose staple volumes for domestic garment production and re-export to ASEAN trade partners. The country's national environmental regulator enforces industrial effluent standards on dissolving pulp imports. Java-based textile clusters are piloting lyocell conversion projects to meet EU buyer sustainability specifications.
Cellulose Fiber Market Vendor Landscape
Top-tier vendors anchor integrated pulp-fiber complexes, while mid-scale spinners compete on regional certification compliance and specialty blend formulations. The vendor base stratifies across three tiers: Austrian and German engineering-technology licensors, Asian integrated producers with captive pulp supply, and regional converters dependent on spot-market dissolving pulp. Two dominant competitive moves are reshaping positioning: backward integration into dissolving pulp assets to hedge feedstock volatility, and technology licensing partnerships to access closed-loop lyocell chemistry without proprietary R&D investment.
Within the branded specialty fiber tier, Lenzing AG exemplifies premium positioning through certification-linked fiber platforms. Among Asian integrated producers, Sateri and Grasim Industries occupy positions as scale-driven suppliers of viscose staple to regional textile clusters. Rayonier Advanced Materials represents the North American dissolving pulp archetype, supplying hardwood pulp feedstock to global rayon complexes without downstream fiber spinning operations.
| Leading Market Players |
|---|
| Sappi Limited |
| Fulida Group Holding Co. Ltd |
| Lenzing AG |
| Rayonier Advanced Materials |
| Kelheim Fibres GmbH |
| Sateri |
| Grasim Industries |
| Aditya Birla Group |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
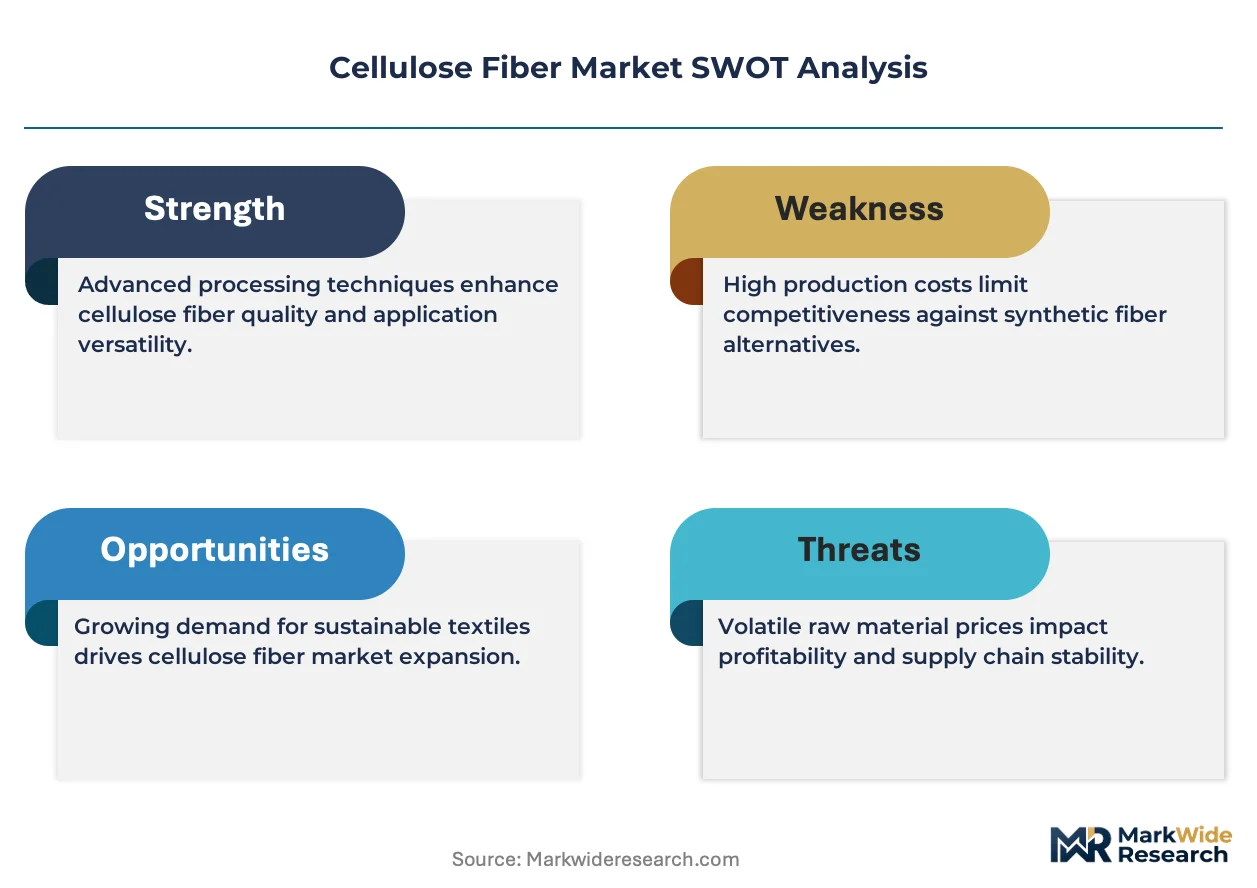
EU apparel brand procurement offices in Germany and Scandinavia command deforestation-free certification premiums, anchoring a contract-based long-term offtake model that rewards verified chain-of-custody documentation with preferential pricing tiers.
Pricing Analysis
Capacity additions in Indonesia and Vietnam are reshaping price floors for standard viscose staple, compressing margins for non-integrated spinners. Three-tier pricing structure across premium certified, standard compliant, and economy commodity levels separates Lenzing's TENCEL-branded lyocell from Indian mass-market viscose. Cost compression in the standard tier is intensifying because China's MEE wastewater rules force retrofit investments. Mass-market apparel mills in Tiruppur exhibit highest price sensitivity, while German luxury houses accept substantial premiums for CanopyStyle-verified fiber.
Supply Chain Analysis
Direct-to-textile-mill channels handle hyperscale dissolving pulp demand from Grasim and Sateri's integrated complexes. Geographic supply concentrates in China, India, and Indonesia, where hardwood pulp feedstock draws from Brazilian and Indonesian plantation sources. The chain rests on dissolving pulp, carbon disulfide or N-methylmorpholine-N-oxide solvents, and caustic soda inputs. Single-source vulnerability around Austrian-engineered lyocell solvent recovery systems creates bottleneck risk. Distribution runs through mill-direct contracts for integrated producers and regional distributors for standalone spinners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellulose fiber market compounds steadily as EU Green Deal deforestation-free mandates harden import eligibility requirements across European textile supply chains.
For Market Incumbents: Acquire captive dissolving pulp assets in Brazil or Indonesia to hedge hardwood feedstock volatility threatening viscose margins. Invest in closed-loop lyocell conversion technology licensed from Austrian engineering houses before EU REACH carbon disulfide caps force asset retirement. Consolidate regional distribution networks in Vietnam and Bangladesh to defend against modular Chinese competitors. For New Entrants and Emerging Players: EU Green Deal chain-of-custody rules in Germany and France open a window for certified lyocell producers to capture premium apparel offtake. Target automotive interior nonwoven applications where OEM scope 3 reporting requirements specify renewable fiber content. Pursue textile-to-textile recycling partnerships with European fashion houses as a circular economy go-to-market angle. For Investors and Strategic Acquirers: Integrated textile conglomerates are the most active acquirer in this space, seeking backward control over pulp supply. The long-term viability window favors producers with verified FSC/PEFC documentation and lyocell conversion capability. Watch for MEE enforcement actions against Shandong dissolving pulp mills as an inflection signal for Chinese supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Captive hardwood supply from Brazilian plantations insulates Grasim and Sateri from feedstock volatility. |
| Lyocell Technology Licensing | Austrian engineering partnerships enable Indonesian and Vietnamese spinners to bypass proprietary R&D investment. |
| Chain-of-Custody Certification | CanopyStyle and FSC documentation unlocks preferential EU apparel brand offtake terms. |
| Automotive Interior Partnership | OEM scope 3 reporting requirements specify renewable fiber content for seat upholstery applications. |
| Textile-to-Textile Recycling Convergence | Chemical depolymerization of cotton-lyocell blends qualifies for EU Green Deal circular economy incentives. |
Methodological Framework
Multiple input streams — dissolving pulp procurement managers, textile mill technical directors, EU regulatory affairs specialists, and nonwoven converter operations heads — were reconciled against customs trade data, REACH compliance filings, and forest stewardship audit records. Bottom-up capacity assessments across Chinese and Indian integrated complexes were triangulated with top-down demand modeling from apparel export statistics and automotive interior specifications.
Data-stream reconciliation anchored volume and value projections across the analysis window. Segmentation dimensions modeled include fiber chemistry type, end-use application, physical form specification, and regional regulatory cluster. CAGRs were derived from capacity expansion pipelines, substitution elasticity estimates between viscose and lyocell, and EU import compliance trajectories. Forecast inputs incorporated MEE wastewater enforcement intensity and EU Green Deal implementation timelines.
Revisions become necessary when EU REACH carbon disulfide limits tighten beyond current trajectories or when Chinese environmental enforcement triggers unexpected mill closures. Forecasts reflect assumptions regarding certification adoption rates and solvent recovery technology diffusion. Periodic stress-testing of base assumptions against actual EU import verification outcomes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Cellulose Market
Natural Fibers
Green Fibers Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Silk Fabric Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
Woolen Textiles Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
North America Cotton Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Natural Fiber Reinforced Composites Market