
 Nonwoven Cotton Market | 2026-2036
Nonwoven Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Cotton Market Analytics
Asset-light contract manufacturing and third-party spunlace tolling is reconfiguring competitive entry in nonwoven cotton, allowing mid-scale brands to bypass capital-intensive carding and hydroentanglement lines. Suominen Corporation leverages its European and Americas spunlace platforms to serve private-label hygiene customers without owning downstream converting. Freudenberg & Co. KG anchors its position through backward integration into cotton fiber preparation and proprietary bonding chemistry. Kimberly-Clark Corporation controls retail shelf access in North American baby and adult hygiene, competing on brand equity rather than manufacturing scale alone.
Nonwoven cotton consists of fibrous webs manufactured from natural cotton fibers or cotton blends, bonded through mechanical, thermal, or chemical means to achieve specified basis weights, tensile strengths, and absorbency rates for disposable or limited-use applications. The material serves primarily as a breathable, biodegradable alternative to synthetic spunbond and meltblown media in applications where skin contact, wicking performance, or environmental disposal constraints matter. Medical textiles dominate value generation given stringent FDA and CE marking requirements that limit supplier pools and sustain premium pricing. Hygiene products represent the volume base, though margin compression from private-label competition and pulp-based alternatives is accelerating. Industrial wipes occupy a stable niche where oil absorbency and solvent compatibility specifications favor cotton's natural lipophilicity over synthetic competitors.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and testing budgets for medical-grade nonwoven cotton entrants. India's BIS certification for technical textiles and the PLI scheme for man-made fiber and technical textiles segments are redirecting capital toward domestic spunlace capacity. REACH restrictions on formaldehyde-based crosslinkers and emerging state-level extended producer responsibility frameworks in the United States are forcing reformulation of durable-press finishes and end-of-life disposal protocols. Stakeholders must monitor how biodegradable certification schemes and fiber traceability standards reshape procurement specifications and supplier qualification criteria across healthcare and consumer channels.
Market Dynamics
Spunlace hydroentanglement capacity concentration in India is compressing lead times for medical-grade cotton webs and forcing European converters to reposition around regulatory proximity rather than fiber sourcing economies.
Growth Catalysts
- EU MDR biocompatibility documentation:Surgical drape manufacturers face elevated sterilization validation requirements that favor established cotton nonwoven suppliers with ISO 13485 histories over synthetic entrants.
- India PLI scheme for technical textiles:Domestic spunlace investment is absorbing regional demand for hygiene substrates that previously imported from European toll converters.
- Cotton fiber lipophilicity:Industrial wipe specifications for solvent compatibility and oil absorbency sustain natural fiber preference over polypropylene in MRO and aerospace maintenance channels.
Market Restraints
- Raw cotton price volatility:Basis risk on New York ICE futures transfers directly to nonwoven rollstock converters lacking backward integration into ginning operations.
- REACH formaldehyde restrictions:Durable-press finish chemistry for reusable medical textiles requires reformulation, extending qualification timelines for EU hospital laundry contracts.
- Viscose and lyocell substitution:Regenerated cellulose competitors achieve comparable absorbency at lower basis weights in baby wipe and cosmetic pad applications.
Strategic Opportunities
- Extended producer responsibility frameworks:US state-level packaging mandates create first-mover advantage for biodegradable-certified cotton nonwovens in single-use hygiene.
- Spunlace-airlace hybrid lines:Technology convergence enables dual-product flexibility between high-loft cotton wipes and denser surgical barrier fabrics on shared asset bases.
- Third-party toll manufacturing:Asset-light contract spunlace access allows mid-scale hygiene brands to bypass capital-intensive hydroentanglement without surrendering formulation control.
Industry Challenges
- FDA 510(k) clearance timelines:Medical device classification for cotton-based wound care substrates stretches development cycles and consumes testing budgets before revenue recognition.
- ISO 13485 auditor scarcity:Qualified quality management certification for medical textile manufacturing concentrates in European notified bodies, creating bottlenecks for Asian facility qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Cotton Market |
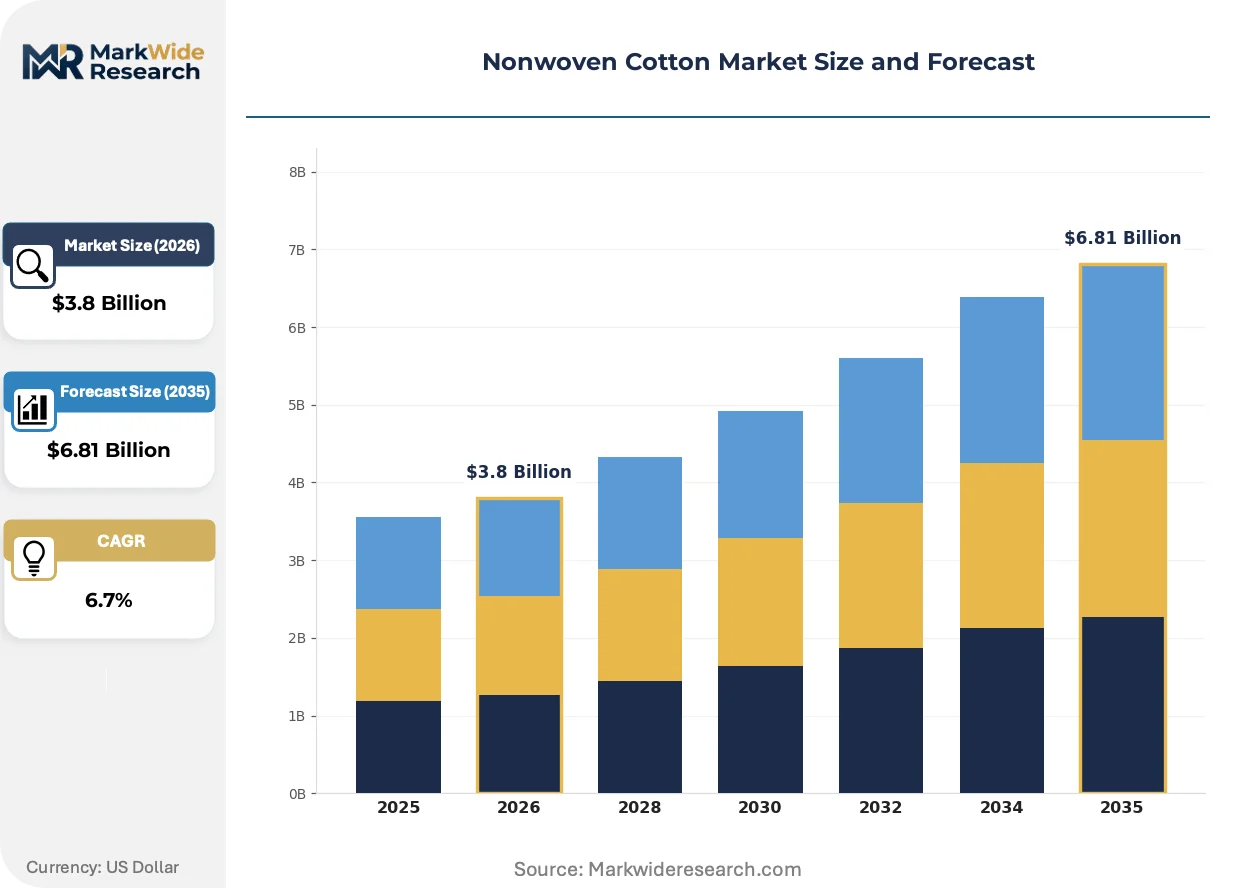
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Textiles, Industrial Wipes, Geotextiles, Hygiene Products End User: Healthcare, Automotive, Agriculture, Consumer Goods Application: Surgical Drapes, Cleaning Cloths, Personal Care, Landscaping Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | Suominen Corporation, Ahlstrom-Munksjö Oyj, Freudenberg & Co. KG, Berry Global Group, Inc., Kimberly-Clark Corporation, Pegas Nonwovens a.s., Toray Industries, Inc., Sandler AG, Fitesa S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Cotton Market Evolving Landscape
Active restructuring of bonding chemistry, regulatory documentation, and procurement specifications is compressing traditional competitive moats while opening white space for certified sustainable alternatives.
Bio-based binders derived from chitosan and starch derivatives are hybridizing with conventional latex systems to maintain wet strength in medical-grade cotton nonwovens without synthetic polymer content. European surgical drape manufacturers are piloting these formulations to preempt EU Green Deal procurement preferences. The technology is hybridizing product positioning—enabling suppliers to claim biodegradability without sacrificing the tensile performance required for sterile barrier applications.
REACH restrictions on formaldehyde-releasing crosslinkers are forcing reformulation of durable-press finishes for reusable surgical gowns and hospital linens. Cotton nonwoven converters serving EU healthcare laundries must validate alternative resin systems that maintain dimensional stability through industrial sterilization cycles. German and French hospital purchasing consortiums are now requiring full material disclosure documentation that traces crosslinker chemistry through the supply chain.
Certification-driven preference shifts are displacing undifferentiated commodity sourcing in North American baby care and adult hygiene. Retailers and contract manufacturers are demanding OEKO-TEX and GOTS fiber traceability credentials that synthetic competitors cannot replicate. This pattern concentrates procurement leverage among spunlace operators with established organic cotton supply relationships, particularly in private-label channels where shelf placement depends on sustainability claims verification.
Nonwoven Cotton Market Segmentation
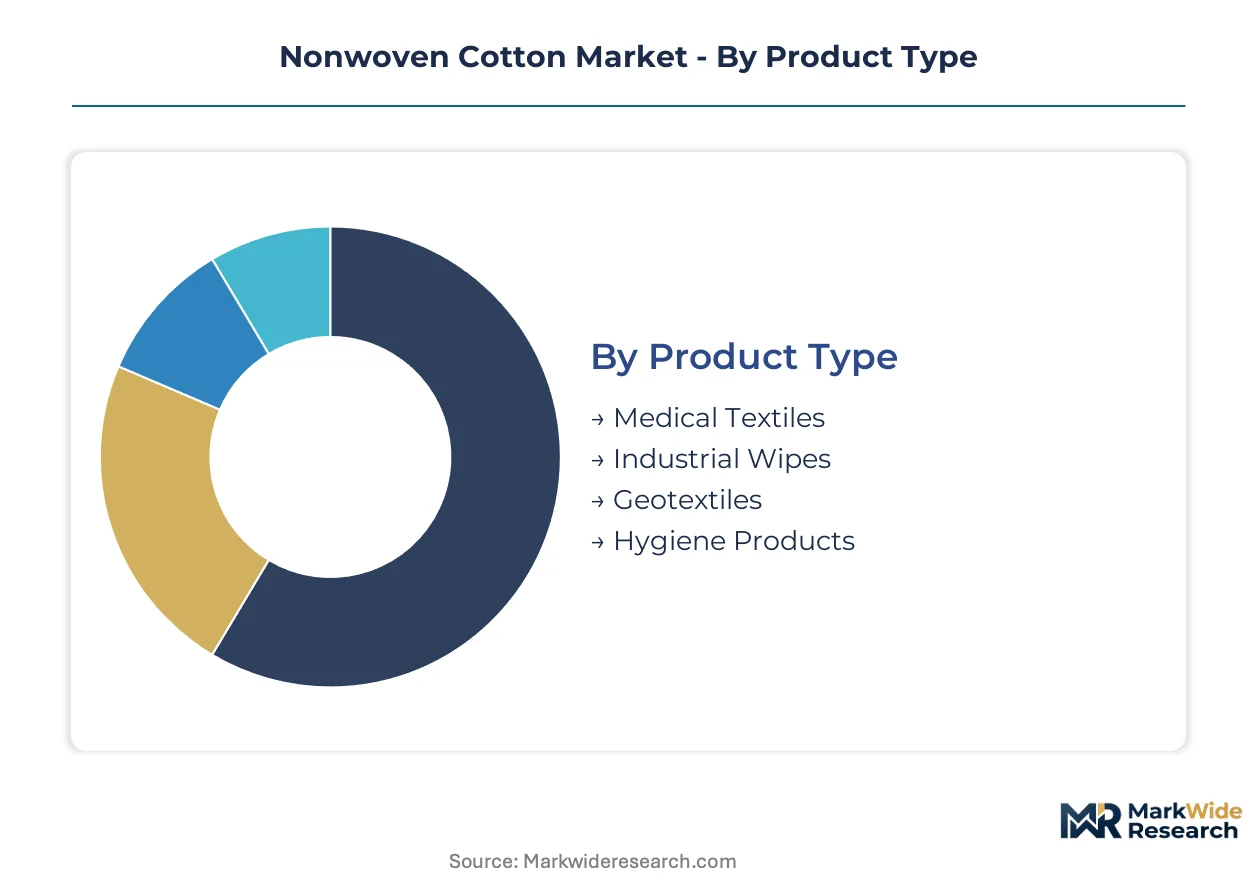
Nonwoven cotton segmentation reveals how fiber specifications, sterilization requirements, and disposal constraints fragment demand across incompatible use cases. Manufacturers configure bonding chemistry and basis weight differently for each vertical, creating specialized supplier ecosystems that resist cross-selling.
Product Type:
Medical textiles command premium positioning through biocompatibility certification, while hygiene products compete on absorbent capacity and skin-contact safety across infant and adult care applications.
- Medical Textiles:Spunlace webs bonded for sterile barrier performance serve surgical drape and wound care applications where FDA 510(k) clearance requirements limit qualified suppliers. Demand concentrates in US and German hospital systems prioritizing single-use infection control protocols over reusable alternatives.
- Hygiene Products:Lower-basis-weight cotton webs target baby wipes, cosmetic pads, and adult incontinence substrates where OEKO-TEX certification drives retailer procurement decisions. Indian domestic spunlace capacity is absorbing regional volume that previously imported from European toll converters.
- Industrial Wipes:High-loft cotton structures exploit natural lipophilicity for MRO solvent cleaning and aerospace maintenance where oil absorbency specifications favor natural fibers over polypropylene.
- Geotextiles:Heavier cotton nonwovens provide biodegradable erosion control and drainage applications where environmental disposal constraints prohibit synthetic alternatives.
The dominant share belongs to Medical Textiles, while Hygiene Products is closing the gap fastest.
End User:
Customer procurement sophistication varies sharply — healthcare systems demand ISO 13485 quality documentation while agricultural buyers prioritize unit cost and biodegradability certification.
- Healthcare:Hospital purchasing consortiums and surgical device OEMs specify cotton nonwovens for sterile barriers, wound contact layers, and patient positioning products. EU MDR technical documentation requirements and FDA biocompatibility protocols sustain premium pricing for qualified suppliers.
- Consumer Goods:Private-label hygiene brands and baby care retailers drive volume through OEKO-TEX and GOTS-certified organic cotton sourcing that synthetic competitors cannot replicate.
- Automotive:Tier-1 suppliers specify cotton-based cleaning substrates for paint preparation and interior finishing where lint-free performance and solvent compatibility matter.
- Agriculture:Nursery operations and landscaping contractors adopt biodegradable crop covers and erosion mats where disposal regulations prohibit polyethylene sheeting.
Healthcare captures the highest margin concentration, with Consumer Goods expanding most quickly through private-label shelf placement.
Application:
Functional requirements dictate fiber preparation — surgical applications demand pharmaceutical-grade purity while landscaping tolerates broader specification ranges.
- Surgical Drapes:Multi-layer cotton-polymer composites provide sterile barriers with controlled MVTR (moisture vapor transmission rate) for operating room environments. EU MDR sterilization validation requirements favor established suppliers with notified body relationships.
- Personal Care:Cosmetic pads and facial wipes require ultra-soft surface finishes achieved through specialized hydroentanglement patterns that minimize fiber shedding during use.
- Cleaning Cloths:Industrial maintenance and food service channels specify cotton wipes for grease absorption and solvent compatibility where synthetic meltblown media fail.
- Landscaping:Biodegradable weed suppression and moisture retention fabrics serve municipal and residential gardening where end-of-life composting is mandated.
Surgical Drapes maintains the revenue leadership position, though Personal Care demonstrates the steepest expansion trajectory through premium cosmetic segmentation.
Distribution Channel:
Channel selection reflects order scale and technical service intensity — direct relationships dominate medical qualification while wholesale aggregates fragmented hygiene demand.
- Distributors:Regional medical and industrial supply houses aggregate demand from mid-scale healthcare facilities and MRO operations, providing inventory buffering and technical specification support.
- Direct Sales:Major hygiene and medical device OEMs negotiate mill-direct contracts for volume certainty and formulation customization, bypassing distribution markups.
- Online Retail:E-commerce platforms serve small-lot buyers and specialized applications where standard specifications suffice and technical consultation is minimal.
- Wholesalers:Bulk aggregators supply private-label converters and export traders with undifferentiated rollstock for downstream finishing and packaging.
Distributors hold the established volume position, while Direct Sales is gaining share fastest through OEM consolidation and qualification-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortiums and private-label hygiene brands concentrate demand in markets with strong technical textile infrastructure and regulatory proximity to end-use certification bodies.
United States
FDA 510(k) clearance requirements for surgical drape applications sustain premium positioning for domestic converters serving hospital systems in Texas and Ohio. The EPA's emerging state-level extended producer responsibility frameworks are reshaping disposal protocols for single-use hygiene products. North Carolina's Research Triangle anchors spunlace R&D activity where medical-grade bonding chemistry receives qualification support.
Germany
EU MDR sterilization validation protocols favor established suppliers with notified body relationships serving surgical device OEMs in Bavaria and Baden-Württemberg. REACH restrictions on formaldehyde-based crosslinkers are forcing reformulation of durable-press finishes for reusable medical textiles. The Rhine-Ruhr industrial corridor concentrates hospital laundry contract manufacturing where dimensional stability through industrial sterilization cycles commands specification priority.
India
Domestic spunlace capacity expansion is absorbing regional hygiene substrate demand previously served by European toll converters. The BIS certification framework for technical textiles and PLI scheme incentives are redirecting capital toward Gujarat and Maharashtra. Tamil Nadu's Coimbatore-Tiruppur belt is emerging as a spunlace manufacturing cluster where government incentives intersect with cotton fiber sourcing proximity.
China
GB standards for medical textiles and dual carbon policy targets are pressuring converters toward biodegradable binder systems in Yangtze River Delta manufacturing zones. The NMPA's medical device classification requirements create qualification bottlenecks for wound care substrate entrants. Zhejiang province's Shaoxing cluster specializes in cosmetic pad and baby wipe exports where OEKO-TEX certification drives retailer procurement decisions.
Japan
METI's technical textile promotion programs and aging demographics sustain adult incontinence substrate demand for domestic spunlace operators. PMDA medical device regulations limit qualified supplier pools for surgical applications, preserving premium pricing. The Chubu region around Nagoya maintains precision hydroentanglement capabilities serving automotive interior cleaning specifications.
Nonwoven Cotton Market Competitive Landscape
Channel-controlling players compete with product-specialist players across medical, hygiene, and industrial wipe verticals where regulatory qualification histories create defensible positioning. The vendor base organizes around three archetypes: backward-integrated fiber processors, asset-light toll manufacturers, and brand-equity retailers controlling shelf access. Dominant competitive moves include third-party spunlace tolling partnerships and proprietary bonding chemistry development.
Among European-based operators, Suominen Corporation and Freudenberg & Co. KG exemplify divergent strategic positions. Suominen represents the asset-light toll manufacturing archetype leveraging regional spunlace platforms for private-label service without captive downstream converting. Freudenberg anchors the backward-integrated fiber preparation segment where proprietary bonding chemistry sustains medical-grade qualification histories. Sandler AG occupies a mid-scale specialist position within German technical textile manufacturing.
| Leading Market Players |
|---|
| Suominen Corporation |
| Ahlstrom-Munksjö Oyj |
| Freudenberg & Co. KG |
| Berry Global Group, Inc. |
| Kimberly-Clark Corporation |
| Pegas Nonwovens a.s. |
| Toray Industries, Inc. |
| Sandler AG |
| Fitesa S.A. |
| Others |
Value Network & Pricing Analysis
Raw cotton price volatility on New York ICE futures determines both tiered pricing spreads across medical-grade and hygiene substrates and the geographic shape of nonwoven cotton supply chains, pushing converters toward backward integration or toll manufacturing partnerships to manage basis risk.
Pricing Analysis
Cost-plus contracts with New York ICE cotton indexation dominate medical-grade rollstock agreements, insulating qualified suppliers from fiber volatility while exposing hygiene converters to spot market swings. Pricing stratifies across FDA 510(k)-cleared surgical barriers, ISO 13485-certified medical grades, and undifferentiated hygiene substrates where private-label competition drives cost compression. Price differentiation hinges on sterilization validation documentation and OEKO-TEX certification tier. Margins are tightening in standard hygiene grades due to Indian domestic spunlace capacity expansion. Consumer goods brands exhibit highest price sensitivity; hospital purchasing consortiums prioritize qualification history over unit cost.
Supply Chain Analysis
Tariff exposure between India and European Union markets dominates supply chain risk planning for nonwoven cotton converters serving medical device OEMs. Manufacturing gravity centers on India, Germany, and the United States, with Gujarat and Maharashtra absorbing regional hygiene demand previously served by European toll converters. Raw material dependencies include pharmaceutical-grade cotton fiber, chitosan-derived bio-binders, and latex emulsion systems. Single-source vulnerability concentrates in notified body relationships for EU MDR sterilization validation. Distribution runs through regional medical supply houses aggregating hospital demand alongside direct mill contracts for volume certainty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital purchasing consortiums and private-label hygiene retailers, with consolidation among European surgical drape OEMs and North American baby care retailers compressing supplier margins and demanding certified sustainable sourcing.
For Market Incumbents: Insulate qualification moats by deepening ISO 13485 auditor relationships with European notified bodies and securing exclusive toll manufacturing partnerships with Indian spunlace operators. Threats from viscose and lyocell substitution in cosmetic pad applications demand proprietary bonding chemistry R&D investment. Backward integration into organic cotton fiber preparation in India anchors supply security. For New Entrants and Emerging Players: Mid-scale hygiene brands in Southeast Asia lacking captive spunlace capacity represent the most penetrable entry point, particularly for biodegradable-certified baby wipe substrates where OEKO-TEX traceability credentials command shelf placement. US state-level extended producer responsibility frameworks create first-mover positioning for compostable industrial wipe alternatives. Go-to-market leverage rests on third-party toll manufacturing partnerships with established hydroentanglement platforms. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light toll manufacturers with established regulatory qualification histories over capital-intensive greenfield capacity. Long-term viability hinges on dual-product flexibility between medical-grade barriers and high-loft hygiene substrates. Acquisition targets should demonstrate notified body relationships and organic cotton supply chain traceability. Watch for shifts in FDA 510(k) clearance timelines as inflection indicators for medical-grade entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Fiber Preparation | Captures margin from ginning operations while securing pharmaceutical-grade purity for FDA submissions. |
| Third-Party Toll Manufacturing Partnerships | Enables mid-scale brands to access spunlace capacity without capital-intensive hydroentanglement investment. |
| Bio-Based Binder Formulation Development | Preempts EU Green Deal procurement preferences by replacing synthetic latex with chitosan derivatives. |
| ISO 13485 Certification Investment | Unlocks hospital purchasing consortium contracts requiring sterilization validation documentation. |
| Extended Producer Responsibility Compliance | Positions biodegradable-certified substrates for US state-level single-use hygiene mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with surgical drape procurement managers at German hospital systems, technical textile R&D directors at Indian spunlace operators, quality assurance leads at notified bodies, and private-label category buyers at North American retailers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, BIS technical textile certification records, and customs trade data for cotton nonwoven rollstock. Bottom-up demand modeling across surgical drape, hygiene, and industrial wipe applications was triangulated against top-down capacity assessments for hydroentanglement lines.
Calibration against historical capacity utilization rates and sterilization validation timeline data informed volume projections across the analysis window. Segmentation dimensions modeled include product type tier, end-user procurement sophistication, application functional requirements, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating fiber price volatility and certification penetration rates. Industry-specific inputs encompassed PLI scheme incentive disbursement patterns and REACH restriction implementation timelines for formaldehyde crosslinkers.
Stress conditions across New York ICE cotton futures bands, EU MDR auditor availability bottlenecks, and Indian spunlace capacity ramp schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sterilization validation acceptance rates and biodegradable certification adoption curves. Material shifts in FDA biocompatibility protocol revisions or extended producer responsibility framework rollouts would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Nonwoven Polyester Fabric Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market
Nonwoven Materials
Absorbable Nonwoven Textiles Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Nonwoven Dust Cover Market