
 Meltblown Fabrics Market | 2026-2036
Meltblown Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Meltblown Fabrics Market Foresight
Single-source reliance on Asian polypropylene resin suppliers is decoupling as European and North American converters build regional feedstock buffers. Kimberly-Clark leverages captive resin contracts to sustain margin stability across its hygiene portfolio. Freudenberg Performance Materials anchors its filtration dominance through backward integration into polymer compounding in Germany. Berry Global competes on medical-grade capacity, operating dedicated cleanroom lines that serve hospital procurement consortiums.
Meltblown fabrics are nonwoven textiles produced by extruding molten thermoplastic polymers through fine capillaries and attenuating the filaments with high-velocity hot air, yielding fiber diameters of 0.5 to 10 microns with high surface area for filtration and absorption. Medical Materials command premium positioning due to FDA and CE marking requirements for biocompatibility and viral barrier performance, while Filters face margin compression from commoditization in HVAC retrofit markets. Polypropylene dominates the Material dimension by cost and process compatibility, though Polyester gains traction in high-temperature industrial filtration where thermal stability exceeds 150 degrees Celsius.
FDA 21 CFR Part 177 sets polymer migration limits for food-contact and medical applications, while the EU MDR tightens clinical evidence requirements for surgical masks and drapes sold in Europe. OSHA respiratory protection standards in the United States and China's GB 2626-2019 filtration efficiency benchmarks collectively shape product certification roadmaps and factory audit protocols. Stakeholders must monitor evolving polymer purity specifications and regional qualification timelines as procurement teams rebalance inventory geography against total landed cost.
Market Dynamics
Automotive OEMs face escalating filtration mandates under the EU's F-Gas Regulation, forcing rapid migration toward higher-efficiency media while resin supply geography undergoes forced regionalization away from Asian concentration.
Growth Catalysts
- F-Gas Regulation tightening:The EU's phasedown of hydrofluorocarbon refrigerants compels mobile air conditioning system redesigns, directly expanding demand for advanced cabin and powertrain filtration media in Germany's industrial corridor.
- Medical-grade certification requirements:FDA 21 CFR Part 177 and EU MDR biocompatibility standards create structural demand for validated cleanroom production capacity that commodity converters cannot replicate.
- Polypropylene process compatibility:The polymer's melt rheology enables sub-micron fiber formation at commercial throughputs, sustaining cost positioning against emerging alternatives in high-volume hygiene applications.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins and regional refinery utilization rates transmit directly to converter cost structures, compressing operating leverage during energy price spikes.
- Asian resin concentration:Historical reliance on Korean and Saudi Arabian polypropylene suppliers exposes European converters to freight cost surges and customs processing delays during supply shocks.
- Thermal ceiling in polypropylene:The polymer's 130-degree Celsius service limit excludes it from industrial hot-gas filtration, ceding share to polyester and polyphenylene sulfide in steel and cement applications.
Strategic Opportunities
- India's PLI scheme for technical textiles:Production-linked incentives for nonwoven manufacturing attract capacity relocation from China's eastern seaboard, creating first-mover advantages in South Asian medical supply chains.
- Bio-based polypropylene development:Neste and Braskem fermentation-derived propylene pathways offer carbon accounting benefits for European automotive procurement teams facing CSRD scope 3 disclosure requirements.
- Electrospinning-meltblowing hybrid processes:Convergence of solution-based nanofiber deposition with meltblown substrate formation enables graded pore structures for next-generation HVAC and liquid filtration without lamination steps.
Industry Challenges
- Cleanroom validation timelines:FDA 510(k) and CE marking processes for surgical mask and drape applications extend 18-24 months, freezing capital deployment until regulatory clearance confirms.
- Skilled extrusion engineering scarcity:Die design and air knife optimization for sub-micron fiber distributions require polymer rheology expertise concentrated among retired DuPont and Hills specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meltblown Fabrics Market |
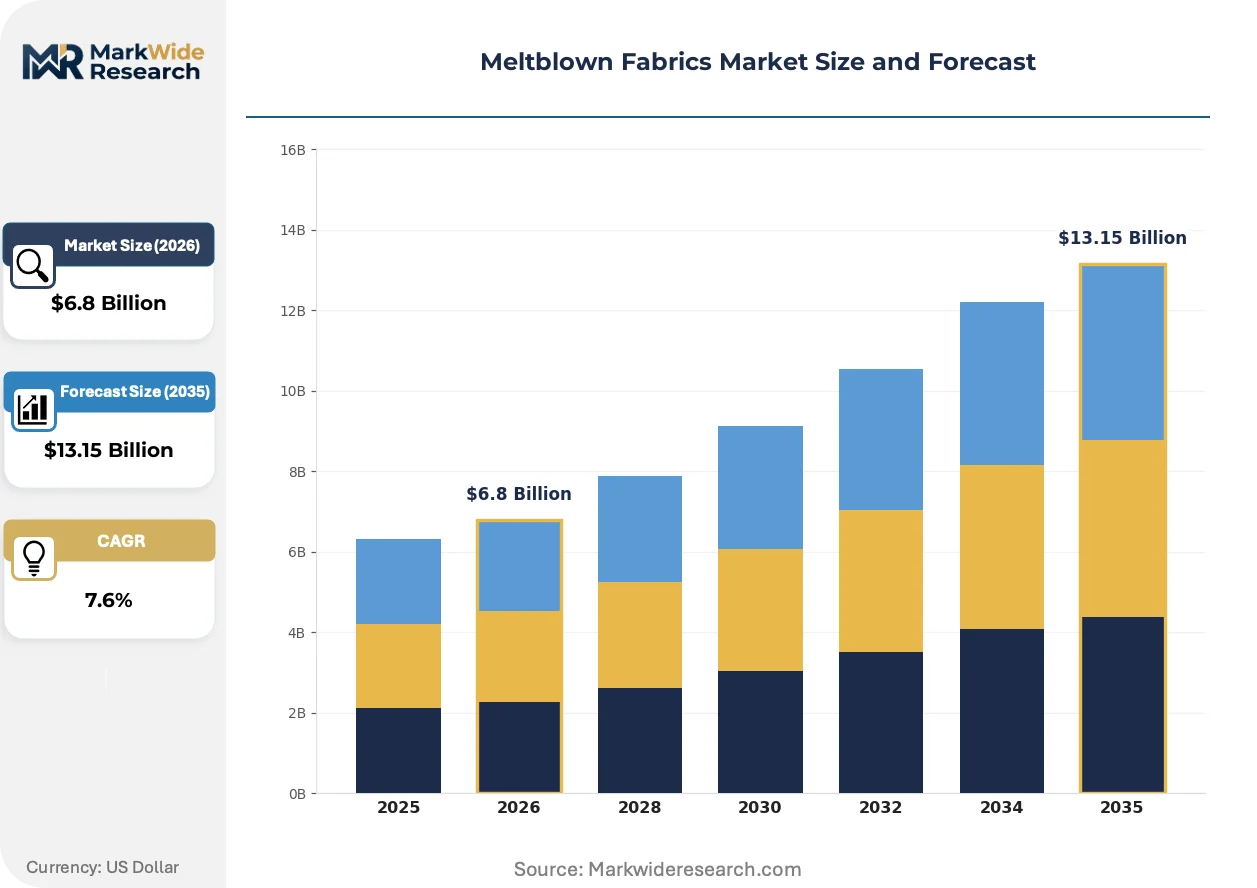
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Woven Fabrics, Filters, Absorbents, Medical Materials End Use Industry: Medical, Automotive, Filtration, Consumer Goods Application: Surgical Masks, Air Filters, Oil Absorption, Diapers Material: Polypropylene, Polyethylene, Polyester, Others |
| Companies Covered | Kimberly-Clark, 3M, Freudenberg Performance Materials, Atex SpA, Ahlstrom, Toray Industries, Berry Global, Mitsui Chemicals, JOFO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meltblown Fabrics Market Shifts & Advancements
Electrostatic charging protocols and multi-layer lamination techniques are redefining performance benchmarks across filtration and medical barrier applications, compressing product development cycles.
Multi-component meltblowing with in-situ charge injection is overtaking standard corona treatment for respirator media. Automotive cabin air filter specifications in Germany and the United States now mandate 95% NaCl efficiency at 0.3 microns, forcing Tier-1 suppliers to adopt bicomponent sheath-core configurations that retain electret performance across humidity cycling. This technology is overtaking commodity monolayer constructions in premium vehicle platforms.
The EU MDR's 2021 implementation tightened clinical evidence requirements for surgical drapes and gowns, elevating barrier testing from AATCC 42 spray ratings to ASTM F1670 blood penetration protocols. German converters near Stuttgart have consolidated validation laboratories to share bioburden testing costs, while Italian medical textile producers delay CE mark renewals pending notified body capacity expansion.
Hospital procurement consortiums in France and the United States now mandate lot-level bacterial filtration efficiency documentation, displacing spot-check quality acceptance. Group purchasing organizations extract 15-20% price concessions for two-year sole-source commitments, concentrating volume among validated suppliers with redundant cleanroom lines. This consolidation is most visible in the Midwestern United States, where Premier and Vizient contracts cover 45% of acute care beds.
Meltblown Fabrics Market Segmentation
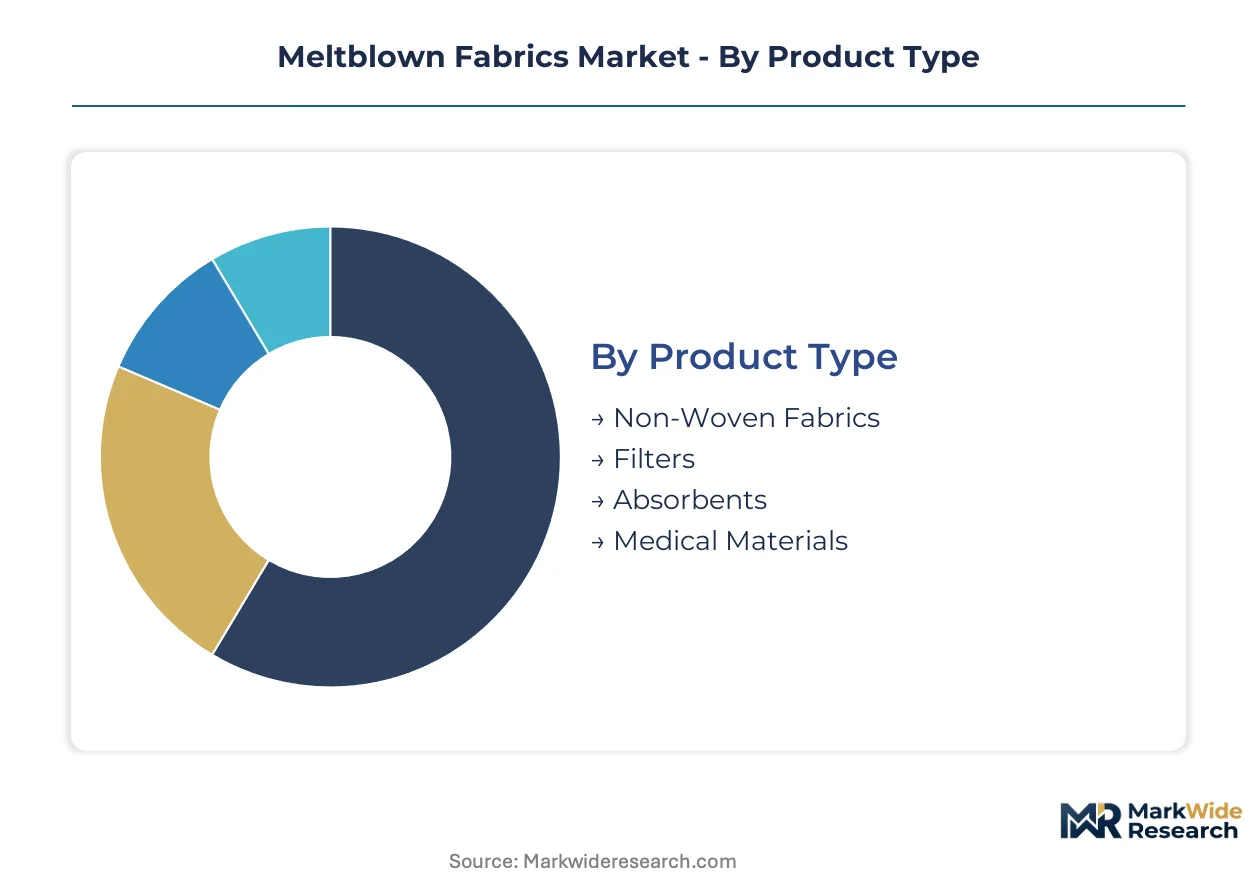
Meltblown fabric specifications diverge sharply across end-use applications, with medical-grade certification and filtration efficiency ratings driving discrete procurement channels. Polymer selection and fiber diameter distributions lock converters into distinct margin tiers that resist cross-selling.
Product Type:
Buyers prioritize performance certification tiers over unit economics when specifying meltblown constructions for regulated applications.
- Medical Materials:FDA 21 CFR Part 177 and EU MDR biocompatibility standards mandate sub-micron fiber distributions with validated viral barrier performance. Demand concentrates in German cleanroom corridors near Stuttgart, where Tier-1 surgical drape suppliers cluster around centralized sterilization logistics.
- Filters:Electret-charged polypropylene media achieve 95% NaCl efficiency at 0.3 microns for automotive cabin air specifications. OEM procurement teams in Germany's industrial corridor extract multi-year volume commitments in exchange for platform qualification.
- Non-Woven Fabrics:General-purpose hygiene substrates compete on throughput scale and resin cost pass-through mechanics.
- Absorbents:Oil-spill remediation and industrial wipe applications prioritize bulk absorption capacity over fiber fineness.
Volume sits with Non-Woven Fabrics; growth tilts toward Medical Materials.
End Use Industry:
Regulatory exposure and qualification timelines separate defensible margin pools from commodity conversion economics.
- Medical:Hospital procurement consortiums in the United States and France mandate lot-level bacterial filtration efficiency documentation. CE marking timelines extend 18-24 months for surgical mask applications, freezing capital deployment until notified body clearance confirms.
- Automotive:EU F-Gas Regulation tightening compels mobile air conditioning system redesigns, expanding specification for advanced cabin and powertrain filtration media. German OEMs around Munich and Stuttgart anchor regional converter capacity.
- Filtration:HVAC retrofit markets face margin compression from commoditized meltblown supply, while industrial hot-gas applications cede share to polyester and polyphenylene sulfide above 130 degrees Celsius.
- Consumer Goods:Diaper and feminine hygiene manufacturers leverage scale procurement to extract 15-20% price concessions for two-year sole-source commitments.
Automotive commands the steepest specification escalation; Medical offers the most durable margin protection.
Application:
Functional performance requirements and replacement frequency determine resin grade selection and electret treatment protocols.
- Surgical Masks:ASTM F1670 blood penetration protocols displaced AATCC 42 spray ratings under EU MDR implementation. Italian producers delay CE mark renewals pending notified body capacity expansion.
- Air Filters:Bicomponent sheath-core configurations retain electret performance across humidity cycling, overtaking monolayer constructions in premium German vehicle platforms.
- Oil Absorption:Hydrophobic polypropylene fiber matrices selectively absorb petroleum derivatives while rejecting aqueous phases.
- Diapers:Acquisition distribution layers balance fluid transport velocity against backsheet breathability in ultrathin constructions.
Diapers generate the highest unit volumes; Surgical Masks carry the most stringent validation burden.
Material:
Thermal service limits and melt rheology characteristics partition addressable applications across polymer families.
- Polypropylene:Dominant cost positioning and process compatibility enable sub-micron fiber formation at commercial throughputs. Melt rheology sustains high-volume hygiene applications where thermal ceilings below 130 degrees Celsius pose no constraint.
- Polyester:Thermal stability exceeding 150 degrees Celsius captures industrial hot-gas filtration in steel and cement applications where polypropylene degrades.
- Polyethylene:Lower melting point and softer hand feel suit select hygiene liner applications with reduced barrier requirements.
- Others:Polyphenylene sulfide and polyimide fibers address extreme temperature and chemical resistance niches.
Polypropylene anchors current volume; Polyester gains share fastest in high-temperature industrial filtration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene feedstock availability in the US Gulf Coast and Germany's industrial corridor anchors regional converter capacity. German automotive OEM procurement teams extract multi-year volume commitments for cabin air filtration media. Chinese resin suppliers face forced regionalization as European and North American converters build buffer inventories.
United States
Hospital procurement consortiums in the Midwest mandate lot-level bacterial filtration efficiency documentation for surgical mask suppliers. OSHA respiratory protection standards shape factory audit protocols for medical-grade capacity. Berry Global operates dedicated cleanroom lines serving Premier and Vizient contracts covering 45% of acute care beds.
Germany
EU F-Gas Regulation tightening compels mobile air conditioning system redesigns, expanding demand for advanced cabin filtration. Freudenberg Performance Materials anchors filtration dominance through backward integration into polymer compounding near Stuttgart. Tier-1 suppliers cluster around Munich for centralized sterilization logistics.
China
GB 2626-2019 filtration efficiency benchmarks drive respirator media certification roadmaps. MIIT technical textile directives accelerate domestic nonwoven capacity expansion. JOFO Group and regional converters concentrate along the eastern seaboard, though India's PLI scheme attracts relocation interest.
Japan
METI industrial standards for high-temperature filtration applications favor polyester and polyphenylene sulfide above polypropylene's thermal ceiling. Toray Industries exemplifies polymer diversification for steel and cement sector demand. Chubu region converters serve automotive OEMs with bicomponent sheath-core configurations.
India
Production-linked incentives for technical textiles attract meltblown capacity from China's eastern seaboard. BIS polymer purity specifications and CDSCO medical device rules create qualification timelines for surgical drape applications. Maharashtra and Gujarat host first-mover cleanroom investments for South Asian medical supply chains.
Meltblown Fabrics Market Competitive Landscape
Backward integration into polymer compounding dominates the current landscape as converters seek margin stability against resin volatility. The vendor base separates into three tiers: multinational hygiene conglomerates with captive resin contracts, European filtration specialists with in-house compounding capabilities, and Asian scale players competing on throughput. Strategic archetypes include electret-charging technology owners, medical-grade cleanroom operators, and regional feedstock integrators. M&A activity targets validated cleanroom assets, while capacity expansion concentrates in India and Southeast Asia to escape Chinese supply concentration.
Among US-based hygiene conglomerates, Kimberly-Clark occupies a position exemplifying captive resin contract structures. Freudenberg Performance Materials represents the European filtration specialist archetype with German polymer compounding integration. Toray Industries anchors the diversified polymer technology tier, occupying a position that reflects thermal stability capabilities beyond commodity polypropylene.
| Leading Market Players |
|---|
| Kimberly-Clark |
| 3M |
| Freudenberg Performance Materials |
| Atex SpA |
| Ahlstrom |
| Toray Industries |
| Berry Global |
| Mitsui Chemicals |
| JOFO Group |
| Others |
Supply & Pricing Matrix
Hospital procurement consortiums in the United States and France anchor pricing power through multi-year sole-source contracts that extract volume commitments in exchange for lot-level bacterial filtration efficiency documentation. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated cleanroom production from commodity hygiene substrates, with electret-charged bicomponent media commanding sustained premiums in automotive cabin air specifications.
Pricing Analysis
Warranty and validation documentation bundling distinguishes premium medical-grade supply from unbundled commodity filtration media. Price differentiation rests on FDA 21 CFR Part 177 compliance tiers and cleanroom certification status rather than resin cost pass-through mechanics. Cost compression in standard-grade HVAC retrofit markets is intensifying because Asian scale players compete on throughput without electret performance guarantees. Consumer goods manufacturers represent the most price-sensitive segment, while hospital procurement consortiums accept premium pricing for redundant cleanroom capacity.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs and US hospital procurement consortiums require converters to qualify secondary resin suppliers and redundant production lines. Geographic supply concentrates in Saudi Arabia, South Korea, and the US Gulf Coast for polypropylene feedstock, with compounding capabilities clustering in Germany's industrial corridor. Raw material dependencies center on naphtha-cracking margins, refinery utilization rates, and polymer-grade propylene availability. Single-source vulnerability persists in sub-micron die design expertise concentrated among retired Hills and DuPont specialists. Distribution runs through Tier-1 supplier networks near Stuttgart and centralized sterilization logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Meltblown Fabrics Market operates as a cost-of-compliance story where EU MDR biocompatibility standards and FDA 21 CFR Part 177 polymer migration limits erect barrier-to-entry moats that protect validated cleanroom operators from commodity competition.
For Market Incumbents: To counter Asian scale players competing on unvalidated hygiene throughput, secure captive resin contracts with US Gulf Coast and Saudi Arabian suppliers while consolidating validation laboratory access near Stuttgart to share bioburden testing costs across Tier-1 surgical drape suppliers. For New Entrants and Emerging Players: Begin with India's PLI scheme for technical textiles to capture first-mover positioning in South Asian medical supply chains before notified body capacity constraints tighten, targeting Maharashtra and Gujarat cleanroom investments with BIS polymer purity qualification as the entry pathway. For Investors and Strategic Acquirers: Distressed-cycle entries favor European filtration specialists with in-house compounding capabilities in Germany's industrial corridor during propylene feedstock volatility spikes. Long-term viability hinges on electret-charging technology ownership and medical-grade cleanroom asset scarcity. Watch FDA 510(k) clearance timelines as the inflection indicator for capital deployment efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Freudenberg Performance Materials anchors margin stability through captive resin supply near Stuttgart. |
| Cleanroom Capacity Expansion | Berry Global's dedicated lines serve Premier and Vizient contracts covering Midwestern US acute care beds. |
| Electrospinning-Meltblowing Hybrid Process Development | Graded pore structures enable next-generation HVAC filtration without lamination cost penalties. |
| Bio-based Polypropylene Supply Agreement | Neste and Braskem fermentation pathways address CSRD scope 3 disclosure requirements for European automotive procurement. |
| Regional Feedstock Buffer Inventory Build | European converters decouple from Korean and Saudi Arabian concentration to mitigate freight cost surges. |
Research Methodology
Trade association filings, customs and import-export databases, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with meltblown converter plant managers, Tier-1 automotive supplier procurement leads, hospital GPO contracts managers, and polymer compounding technical directors. Bottom-up capacity utilization estimates and top-down end-use demand aggregation were triangulated to reconcile volume figures.
Historical trendline analysis of resin cost pass-through mechanics and cleanroom capacity deployment patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product certification tier, end-use industry regulatory exposure, polymer thermal service limit, and regional feedstock availability cluster. CAGRs were derived from elasticity-adjusted demand curves and substitution threat assessments for polyester in high-temperature industrial filtration.
Underlying measurement precision varies by segment; medical-grade cleanroom production carries tighter precision than commodity hygiene substrates due to validated throughput documentation. Forecasts reflect assumptions about EU MDR notified body capacity expansion and F-Gas Regulation implementation timelines. Deviation in propylene feedstock volatility or FDA 510(k) clearance durations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Nonwoven Polyester Fabric Market