
 Nonwoven Protective Clothing Market | 2026-2036
Nonwoven Protective Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Protective Clothing Market Intelligence
Margin capture from specialized, high-barrier fabrics for hazardous environments is rewriting the value proposition away from commodity polypropylene materials. DuPont leverages its portfolio of proprietary materials to dominate chemical and biological protection segments. 3M competes through innovation in breathable films integrated into its coveralls, while Berry Global sustains its position via massive production scale in spunbond fabrics.
Nonwoven protective clothing comprises garments engineered from fibers bonded chemically, thermally, or mechanically rather than being woven. These fabrics, such as spunbond polypropylene, are designed with specific basis weights and layering to create a barrier against particulates and biological contaminants. Coveralls for industrial safety and gowns for medical procedures constitute the largest product categories. Polypropylene spunbond remains the volume leader, but demand for multi-layered composite fabrics is accelerating in high-risk healthcare and cleanroom applications.
Product performance and market access are governed by stringent standards, including CE marking requirements in Europe and specific device classifications by the US FDA for medical apparel. Global benchmarks like ISO 16603 define resistance to penetration by blood-borne pathogens, directly influencing material selection. Future material development will need to balance enhanced protection and comfort with circular economy principles for disposal and recycling.
Market Dynamics
The market’s trajectory is defined by the need to reconcile high-barrier performance requirements, particularly in healthcare and cleanrooms, with emerging circular economy mandates that challenge the single-use model of polypropylene-based garments and their environmental impact.
Growth Catalysts
- Stringent Safety Mandates:Regulations from bodies like the US Occupational Safety and Health Administration (OSHA) and requirements for CE marking in Europe compel employers in industrial sectors to provide certified protective apparel against workplace hazards.
- Healthcare Infection Control:Heightened protocols in hospitals to prevent hospital-acquired infections (HAIs) drive consistent demand for single-use surgical gowns and drapes that comply with standards for viral penetration resistance, such as ISO 16603.
- Material Science Advances:The development of multi-layer composite fabrics like SMS (spunbond-meltblown-spunbond) offers superior barrier properties against pathogens while improving breathability for user comfort in demanding pharmaceutical cleanroom environments.
Market Restraints
- Polypropylene Price Volatility:As the primary raw material, polypropylene's price is directly linked to fluctuating petrochemical markets, creating significant cost instability and margin pressure for manufacturers of spunbond and meltblown fabrics.
- Reusable Garment Competition:Woven, launderable protective garments present a substitution threat in less critical industrial applications where total cost of ownership and sustainability concerns can favor reusables over single-use nonwoven alternatives.
- Complex Certification Pathways:The lengthy and expensive process of achieving medical device classification from regulators like the US FDA or notified body approval for CE marking in Europe creates a substantial barrier to entry for new manufacturers.
Strategic Opportunities
- Emerging Pharmaceutical Hubs:Expanding pharmaceutical manufacturing and clinical trial activities in countries like India and Brazil are creating new, localized demand for specialized cleanroom apparel, lab coats, and other protective garments.
- Bio-based and Recyclable Polymers:Developing nonwovens from polylactic acid (PLA) or creating circular systems for recycled polypropylene can address environmental regulations and corporate sustainability goals, unlocking new market segments.
- Food Processing Applications:Underpenetrated demand exists for specialized nonwoven coveralls and aprons in the food processing industry to prevent cross-contamination, driven by stricter food safety standards from agencies like the FSSAI in India.
Industry Challenges
- End-of-Life Waste Management:The logistical and environmental burden of managing large volumes of contaminated, single-use polypropylene garments from hospitals and industrial sites, which are typically incinerated or landfilled, remains a primary operational hurdle.
- Inconsistent Global Standards:Manufacturers face complexity navigating differing regional performance standards, such as the variations between US AAMI levels and European EN 13795 for surgical gowns, which complicates global product design and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Protective Clothing Market |
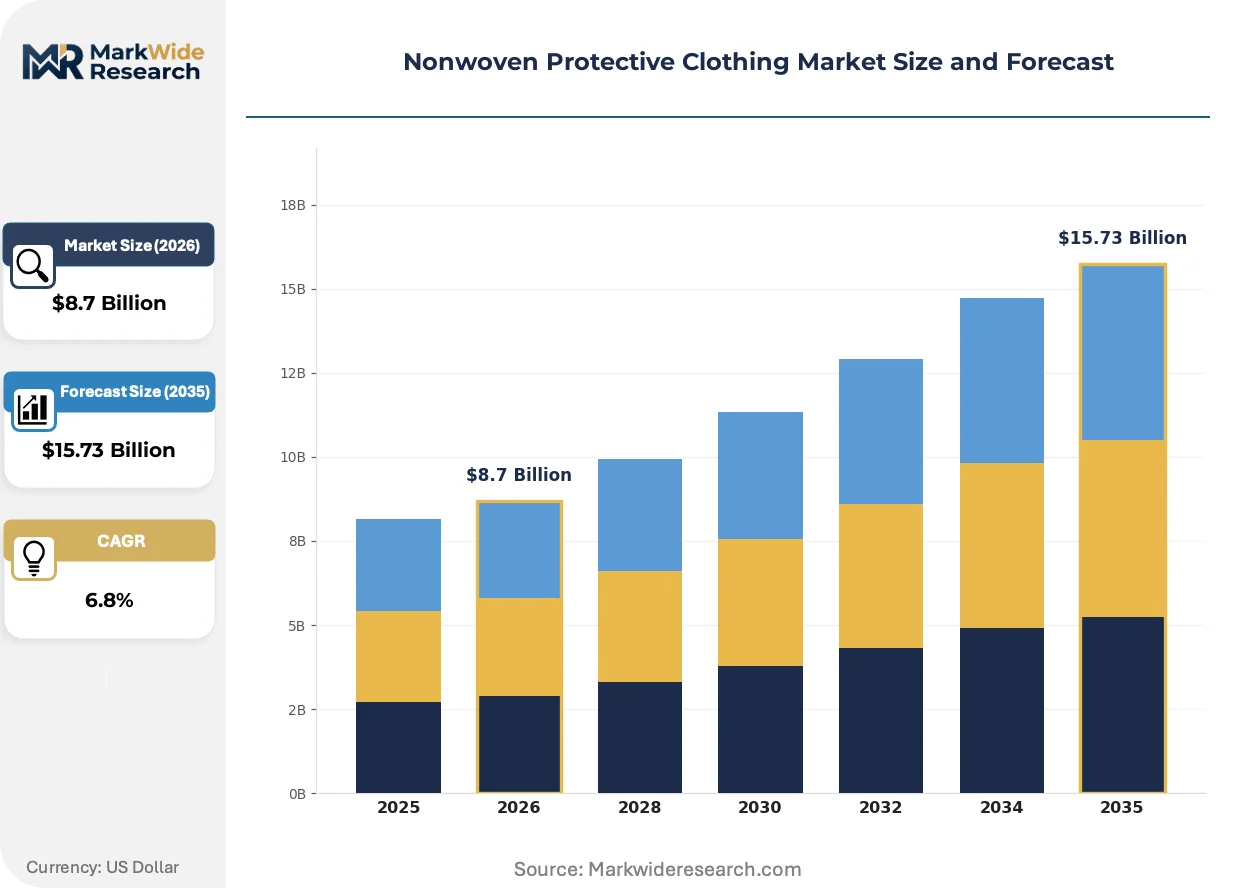
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coveralls, Gowns, Aprons, Hoods Material: Polypropylene, Polyester, Nylon, Spunbond End User: Healthcare, Food Processing, Construction, Laboratories Application: Hazardous Waste, Medical Procedures, Cleanrooms, Industrial Safety |
| Companies Covered | DuPont, Kimberly-Clark, Berry Global, Ahlstrom, Freudenberg SE, 3M, Asahi Kasei Corporation, Suominen Corporation, Johns Manville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Protective Clothing Market Strategic Shifts & Innovations
Material innovation is converging with advanced manufacturing techniques to create next-generation protective apparel. This shift prioritizes balancing enhanced barrier efficacy against complex hazards with significant improvements in wearer comfort and thermal management, moving beyond traditional single-material solutions.
Multi-material composite fabrics integrate different nonwoven layers to achieve specific performance characteristics. High-risk sectors like biopharmaceutical manufacturing and hazardous material response teams are rapidly adopting these advanced garments. This technology is hybridizing barrier protection with breathability, combining microporous films with spunbond layers to block viral penetration while allowing moisture vapor to escape, directly addressing user heat stress.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is compelling large companies to disclose the environmental impact of their supply chains. This mandate creates commercial pressure on manufacturers of single-use protective clothing to provide data on product lifecycle, from raw material sourcing to end-of-life disposal. The medical device and pharmaceutical sectors are most affected, prompting a search for nonwovens with lower carbon footprints or viable recycling pathways.
A notable behavioral shift involves buyers specifying protective garments based on task-specific risk assessments rather than using a one-size-fits-all approach. This is disrupting the traditional channel reliance on high-volume, general-purpose coveralls, creating demand for a more segmented product portfolio. This trend is most visible in large industrial manufacturing and healthcare networks, where safety managers use data to match garment protection levels to specific workplace hazards.
Nonwoven Protective Clothing Market Segmentation
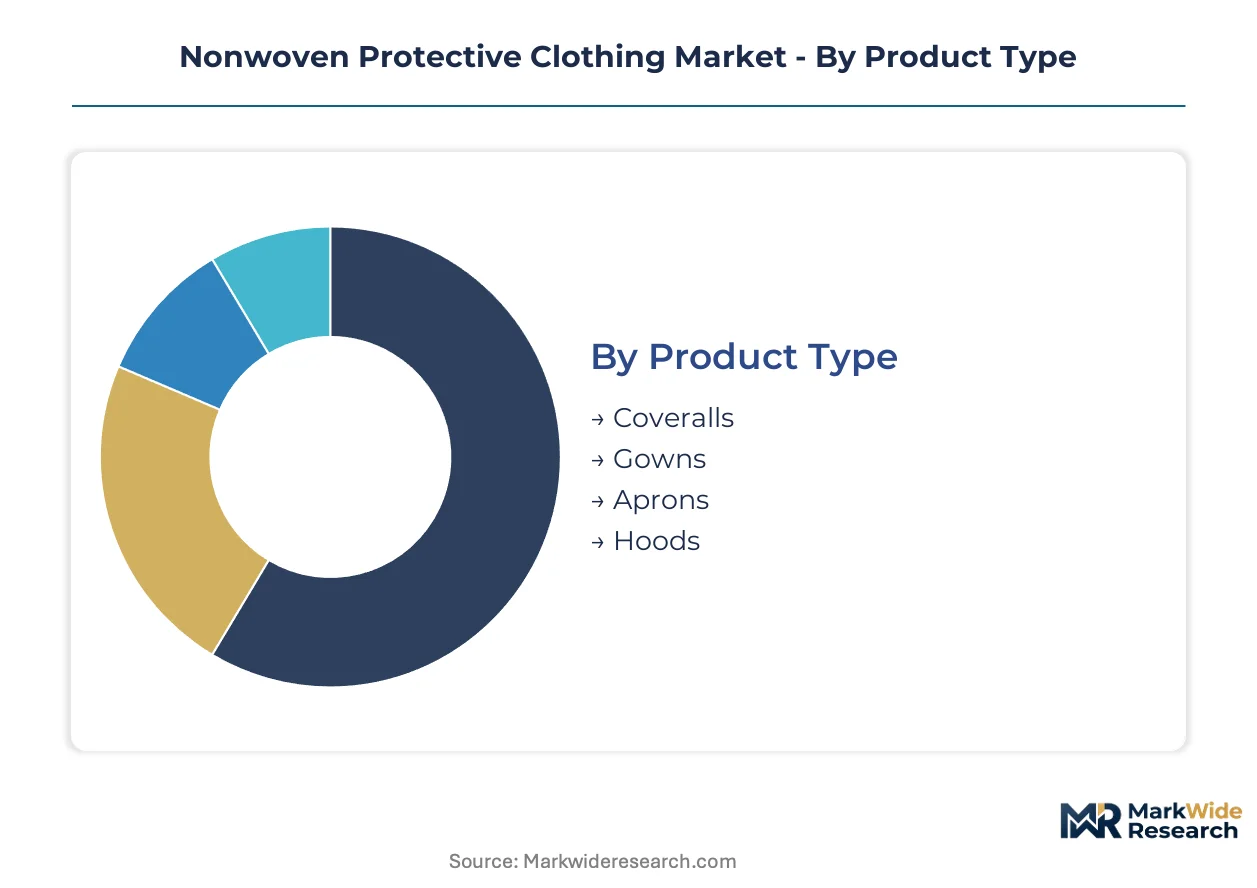
Segmentation within the nonwoven protective clothing market illuminates critical differences in product design, material requirements, and regulatory compliance. Understanding these distinct segments allows manufacturers to tailor product offerings and sales strategies effectively. Each segment responds to unique end-user demands and performance specifications.
Product Type:
The after-sales-service intensity for nonwoven protective clothing varies significantly across product types, influencing procurement strategies and inventory management for end-users.
- Coveralls:These full-body garments provide comprehensive barrier protection against particulates, liquids, and biological agents. Demand concentrates in industrial safety applications, particularly in chemical processing facilities and hazardous waste management in Germany.
- Gowns:Designed primarily for medical and cleanroom environments, gowns offer barrier protection for healthcare workers and patients during procedures. The US healthcare sector drives significant demand for sterile surgical gowns meeting AAMI levels of protection.
- Aprons:Simple protective garments covering the front of the body, aprons are used for splash protection in food processing and light industrial tasks. Food safety regulations from agencies like India's FSSAI influence apron specifications.
- Hoods:Head coverings designed to protect against particulate contamination or splashes, frequently used in conjunction with other PPE. Cleanroom operations in pharmaceutical manufacturing in China utilize specialized hoods.
Coveralls holds the largest share; momentum sits with Gowns.
Material:
Supply concentration within the raw material segment dictates pricing power and strategic sourcing for nonwoven protective clothing manufacturers.
- Polypropylene:This thermoplastic polymer forms the backbone of the nonwoven protective clothing market, valued for its cost-effectiveness and versatility in spunbond and meltblown forms. Its widespread use in single-use garments creates significant demand from medical and industrial sectors globally.
- Spunbond:A manufacturing process that extrudes molten polymer into continuous filaments, which are then randomly laid into a web and bonded. Spunbond polypropylene fabrics provide strength and durability, forming the outer layers of multi-layer composites used in high-performance coveralls.
- Polyester:Offers good strength, chemical resistance, and dimensional stability, making it suitable for certain specialized nonwoven applications. Some cleanroom garments incorporate polyester for specific lint-free properties.
- Nylon:Known for its high tensile strength and abrasion resistance, nylon nonwovens are used in niche applications requiring enhanced durability. This material sees limited use compared to polypropylene due to higher costs.
Polypropylene dominates volume, while demand for Spunbond composites is expanding rapidly.
End User:
Application complexity drives differentiated demand across end-user segments, requiring tailored protective solutions.
- Healthcare:This segment includes hospitals, clinics, and emergency medical services, requiring a wide range of sterile and non-sterile protective apparel for infection control. Stringent standards from the US FDA and European CE marking drive specific product requirements.
- Laboratories:Research facilities, pharmaceutical development, and diagnostic labs require protective clothing to prevent contamination and protect personnel from chemical or biological hazards. Cleanroom protocols in biopharmaceutical manufacturing in Switzerland exemplify this demand.
- Food Processing:The food and beverage industry uses nonwoven clothing to prevent product contamination and maintain hygiene standards. Regulations from agencies like the FSSAI in India mandate specific protective apparel.
- Construction:Workers in construction and infrastructure projects utilize protective clothing for dust, debris, and chemical splash protection. OSHA regulations in the United States influence the adoption of durable nonwoven garments.
Healthcare represents the largest end-user segment, with Food Processing showing significant growth potential.
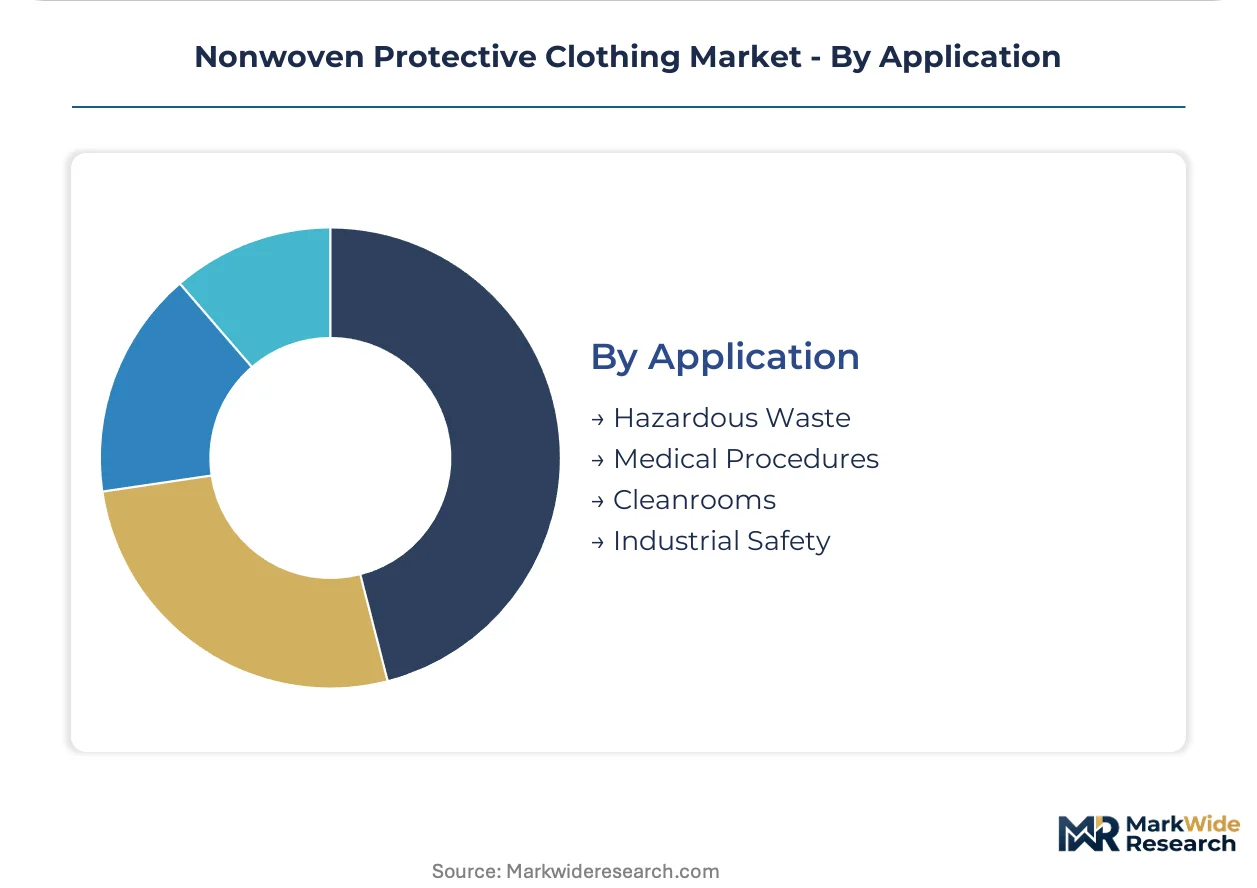
Application:
Regulatory stringency directly impacts material selection and product design across various application areas for nonwoven protective clothing.
- Medical Procedures:This critical application encompasses surgical operations, patient care, and emergency medical response, necessitating garments with high barrier protection against pathogens. Compliance with ISO 16603 for viral penetration is paramount for gowns used in these settings.
- Cleanrooms:Environments with controlled levels of particulate contamination, such as those in semiconductor manufacturing or pharmaceutical production, demand specialized lint-free and high-barrier nonwoven clothing. China's expanding pharmaceutical industry drives demand for advanced cleanroom attire.
- Hazardous Waste:Workers handling hazardous materials or waste require robust protective clothing offering chemical and biological resistance. Regulations from environmental protection agencies in Canada influence material specifications for these garments.
- Industrial Safety:This broad category includes manufacturing, automotive, and other industrial settings where workers need protection from dust, chemicals, and light splashes. European CE marking requirements guide the selection of appropriate industrial safety wear.
Medical Procedures drive substantial demand, as Cleanrooms applications require specialized high-performance garments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global nonwoven protective clothing market exhibits a supply-side concentration in key manufacturing hubs, particularly for raw material production. This concentration influences global pricing dynamics and strategic sourcing decisions across the value chain. Manufacturers often locate production near major end-use sectors.
United States
The United States healthcare sector drives substantial demand for sterile surgical gowns and coveralls. OSHA regulations mandate protective apparel in various industrial settings for worker safety. Major medical device manufacturing clusters in states like California and Massachusetts require specialized cleanroom garments.
China
China's expanding pharmaceutical manufacturing industry fuels significant demand for advanced cleanroom attire. The country's stringent industrial safety requirements, guided by GB standards, compel usage of protective coveralls. Large-scale production facilities in the Yangtze River Delta region serve both domestic and export markets for nonwoven materials.
Germany
German industrial safety standards, including CE marking requirements, necessitate high-barrier protective clothing for chemical processing. The country's robust automotive and manufacturing sectors consistently require nonwoven garments. Industrial clusters in North Rhine-Westphalia drive demand for specialized chemical splash protection.
India
India's emerging pharmaceutical hubs are creating localized demand for specialized cleanroom apparel and lab coats. Food safety regulations from the FSSAI influence apron specifications in the growing food processing industry. Manufacturing zones around Hyderabad and Bengaluru are seeing increased adoption of protective garments.
Switzerland
Switzerland's advanced biopharmaceutical manufacturing sector requires highly specialized cleanroom protocols and protective garments. Swissmedic regulations ensure stringent quality and safety standards for medical apparel. Innovation clusters in Basel and Zurich drive demand for cutting-edge nonwoven solutions.
Nonwoven Protective Clothing Market Key Industry Players
Specialized high-barrier fabric producers and large-scale commodity material suppliers split the nonwoven protective clothing market. Innovation-focused integrators also occupy a strategic tier, emphasizing advanced material science. Companies pursue portfolio diversification and strategic partnerships to enhance their market positions.
Within the specialized protection tier, DuPont leverages its proprietary materials for chemical and biological segments. 3M, known for its innovation, competes through breathable films integrated into coveralls. Berry Global, a major US-based manufacturer, sustains its position via massive production scale in spunbond fabrics.
| Leading Market Players |
|---|
| DuPont |
| Kimberly-Clark |
| Berry Global |
| Ahlstrom |
| Freudenberg SE |
| 3M |
| Asahi Kasei Corporation |
| Suominen Corporation |
| Johns Manville |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta's substantial production capacity for nonwoven materials significantly influences global pricing dynamics, particularly for commodity polypropylene fabrics. This regional concentration of manufacturing capability establishes a baseline for cost structures, impacting downstream pricing power across the entire value chain.
Pricing Analysis
CE marking requirements dictate the pricing tier structure for nonwoven protective clothing, especially for medical-grade products. Pricing is transactional, often governed by long-term contracts for high-volume orders, with a value-based approach for specialized, high-barrier composites. Price differentiation stems from certification level, such as AAMI levels or ISO 16603 compliance, and the complexity of multi-layer material compositions. Pricing pressure stems from polypropylene's cost instability due to fluctuating petrochemical markets. Less critical industrial applications exhibit higher price sensitivity compared to high-risk healthcare and cleanroom segments.
Supply Chain Analysis
Stringent medical device regulations, such as those from the US FDA and European CE marking, indirectly control the flow of specialized nonwoven protective clothing into regulated markets. Geographic supply concentrates in China, particularly for base nonwoven fabrics, and the United States for advanced medical device manufacturing. The supply chain relies heavily on polypropylene and specialized multi-layer composite fabrics. Commodity price volatility for polypropylene represents a significant structural risk. Distribution runs through specialized distributors and direct procurement by large end-users in healthcare and industrial sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat story, primarily due to regulatory entrenchment that creates significant barriers to entry and ensures consistent demand for certified products.
For Market Incumbents: Build regulatory compliance moats by investing continuously in R&D for advanced material science and securing certifications like ISO 16603 for viral penetration. Expand production capacity in strategic, regulated markets such as the US and Europe to mitigate supply chain risks and counter the threat from reusable garment competition. Leverage existing channel control and relationships with large healthcare networks to reinforce market position against emerging entrants.
For New Entrants and Emerging Players: Pursue niche market opportunities, particularly in underpenetrated segments like food processing applications or emerging pharmaceutical hubs in India and Brazil. Focus on developing sustainable, bio-based nonwovens to align with circular economy mandates, offering a differentiated go-to-market angle. Target less stringently regulated industrial applications initially to build market presence before tackling high-barrier segments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized material science innovators with proprietary multi-layer composite fabrics. Long-term viability over the next decade is strong, driven by persistent demand for infection control and industrial safety. Seek acquisition targets with established regulatory expertise and proven capabilities in developing recyclable polypropylene solutions or alternative bio-based polymers. A key signal to watch is the adoption rate of advanced circular economy solutions in major healthcare systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Europe | Addresses regional demand and mitigates geopolitical supply chain risks for critical medical apparel. |
| R&D in Bio-based Polymers | Unlocks new market segments and aligns with emerging corporate sustainability goals and regulations. |
| Certification Pathway Investment | Secures market access and strengthens competitive positioning in highly regulated healthcare and cleanroom sectors. |
| Strategic Partnerships with Healthcare Networks | Ensures consistent demand and facilitates product innovation tailored to specific infection control protocols. |
| Vertical Integration into Meltblown Fabric Production | Enhances supply chain resilience and captures additional margin for critical barrier material components. |
Research Approach
Operator-level perspectives from safety managers, procurement leads, R&D directors, and regulatory specialists anchored the qualitative base of this study. Primary interviews with industry stakeholders were triangulated with extensive secondary validation from sources including ISO standards documents, US FDA filings, CE marking databases, and petrochemical market reports. A robust bottom-up and top-down approach ensured comprehensive data collection and analysis across the nonwoven protective clothing market.
The forecast framework utilizes scenario-bracketing to project market trajectory across the analysis window. Segmentation dimensions modeled include product type, material, end-user, application, and regional regulatory frameworks. Compound annual growth rates were derived through a proprietary analytical model integrating historical trends and future projections. Key forecast inputs included raw material price forecasts and global healthcare expenditure trends.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or industrial output would shift the trajectory. Forecasts reflect assumptions documented through this rigorous process. Material shifts in regulatory enforcement or unforeseen technological disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Absorbable Nonwoven Textiles Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Global Wet Laid Nonwovens Market