
 HDPE Nonwoven Market | 2026-2036
HDPE Nonwoven Market Size, Share, and Industry Trends Forecast 2026-2036
HDPE Nonwoven Market Analysis
Asset-light leasing models for spunbond production lines is tilting competitive entry toward mid-scale regional converters. Berry Global leverages its North American manufacturing footprint to sustain bulk supply contracts for hygiene-grade material. Freudenberg Performance Materials anchors European technical nonwoven demand through filtration and automotive specialization. Fibertex Nonwovens competes in geotextile segments where project-scale procurement favors localized supply.
HDPE nonwoven refers to sheet or web structures manufactured from high-density polyethylene fibers bonded through thermal, mechanical, or chemical means, typically achieving basis weights between 8 and 150 grams per square meter. These materials resist moisture, chemicals, and UV degradation while maintaining tensile strength, serving primary functions in barrier protection, separation, and filtration across industrial and consumer applications. Spunbond dominates volume output due to its continuous filament construction suited for high-speed medical and hygiene converting. Meltblown commands premium positioning in fine-filtration media where fiber diameters below 5 microns determine particle capture efficiency. Geotextile applications under the Application segment occupy durable infrastructure margin pools driven by civil engineering specifications for separation and reinforcement layers.
The EPA regulates industrial nonwoven manufacturing emissions under Clean Air Act standards, while REACH compliance in Europe governs chemical inputs and recyclability declarations for HDPE-based products. FDA oversight of medical-grade nonwovens enforces biocompatibility and sterility assurance levels for surgical drapes and protective apparel. Stakeholders must monitor evolving extended producer responsibility frameworks that will reshape material formulation decisions and end-of-life recovery economics.
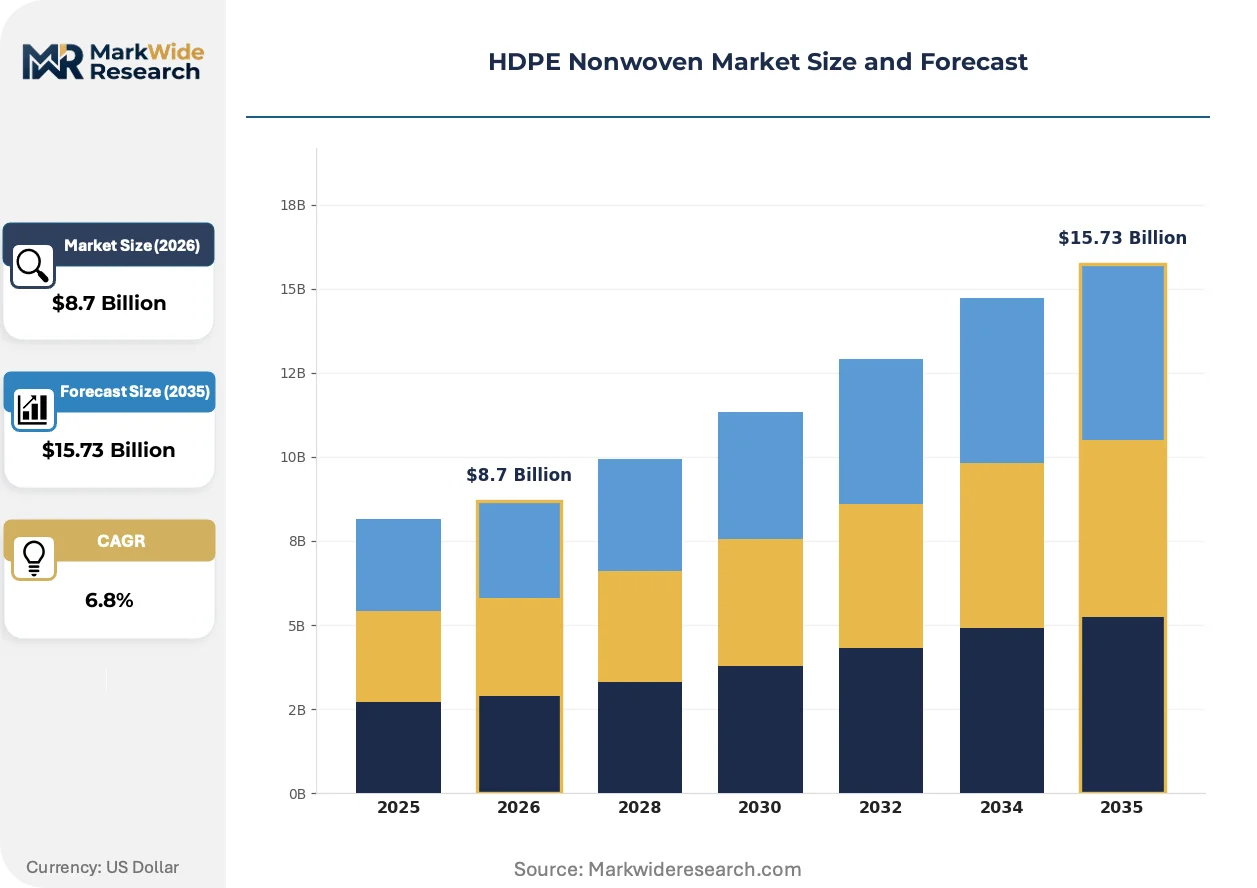
Market Dynamics
Asset-light leasing models for spunbond production lines are tilting competitive entry toward mid-scale regional converters, fragmenting supply concentration that previously favored integrated multinationals with captive resin sourcing.
Growth Catalysts
- EU Green Deal plastic circularity mandates:These frameworks redirect manufacturer investment toward recyclability and closed-loop feedstock integration, accelerating R&D spend on mono-material HDPE constructions.
- Technical nonwoven demand in Germany's industrial corridor:Civil engineering specifications for separation and reinforcement layers are concentrating procurement volume in specialized geotextile grades.
- Spunbond continuous filament construction:This process technology enables high-speed medical and hygiene converting at basis weights between 8 and 50 grams per square meter, capturing volume from carded thermal-bond alternatives.
Market Restraints
- Ethylene feedstock price volatility:Naphtha-cracker output fluctuations in the US Gulf Coast and Northwest Europe transmit directly to HDPE resin contract pricing, compressing converter margins during upstream tightness.
- Spunbond line supply concentration:German and Italian equipment builders control 70 percent of global installed capacity for high-output spunbeam systems, creating delivery bottlenecks for new market entrants.
- Polypropylene substitution in hygiene applications:Lower-density PP nonwovens achieve comparable fluid management at reduced freight cost per unit area, displacing HDPE in diaper backsheet and feminine hygiene markets.
Strategic Opportunities
- Underpenetrated Indian medical nonwoven demand:CDSCO enforcement of biocompatibility standards for surgical drapes is creating first-mover advantage for ISO-certified HDPE suppliers establishing local converting partnerships.
- Dual carbon goals in China's infrastructure pipeline:MEE specifications for 30-year design-life geotextiles in high-speed rail and landfill capping are specifying UV-stabilized HDPE over polyester alternatives.
- REACH recyclability declaration requirements:ECHA's evolving end-of-life data obligations favor mono-polymer HDPE constructions over multi-layer competitors in European technical applications.
Industry Challenges
- Meltblown microfiber process engineering talent scarcity:The specialized skill set for achieving sub-5-micron fiber diameters at commercial scale concentrates in a handful of technical textile programs in Germany and the United States.
- FDA 510(k) sterilization validation timelines:Biocompatibility and sterility assurance level documentation for surgical drape applications extends product commercialization cycles by 18-24 months.
- Legacy carded thermal-bond line retrofit complexity:Existing European installed base requires substantial capital reconfiguration to process continuous filament HDPE feedstocks, stranding depreciated assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDPE Nonwoven Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond, Meltblown, Needlepunch, Chemical Bonded Application: Medical, Filtration, Geotextiles, Agriculture End User: Healthcare, Construction, Automotive, Hygiene Distribution Channel: Direct Sales, Online, Wholesalers, Retail |
| Companies Covered | DuPont, Toray Industries, Berry Global, Freudenberg Performance Materials, Fitesa, Fibertex Nonwovens, Kimberly-Clark, Asahi Kasei, Thrace Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDPE Nonwoven Market Emerging Trajectories
Bicomponent spunbond technology is rendering obsolete single-polymer constructions across barrier-sensitive medical applications, while regulatory pressure on carbon intensity reshapes resin sourcing geography.
Bicomponent core-sheath fiber architectures combining HDPE core with polyethylene terephthalate or polypropylene sheath layers are rendering obsolete monocomponent spunbond in surgical gown applications. Tier-one medical converters in the United States and Germany are qualifying these structures for AAMI Level 3 and 4 barrier performance. The technology is compressing demand for separately laminated film layers, reducing bill-of-material complexity and end-of-life sorting burden.
REACH Article 33 disclosure requirements for Substances of Very High Concern are forcing reformulation of UV stabilizer packages in geotextile-grade HDPE nonwovens. ECHA's 2024 candidate list expansion to include certain hindered amine light stabilizers is disrupting established additive supply relationships. European civil engineering contractors are responding by specifying stabilizer systems with full material passport documentation, privileging suppliers with in-house compounding capabilities.
Project-scale procurement for infrastructure geotextiles is consolidating specification authority among engineering procurement construction firms with centralized technical departments. Regional nonwoven converters in France and Poland are losing direct access to municipal buyers as EPCs standardize on pre-approved vendor lists with pan-European quality assurance protocols. This concentration is most visible in German federal highway and landfill remediation contracts, where Fibertex and Freudenberg anchor approved supplier status through captive technical service teams.
HDPE Nonwoven Market Segmentation
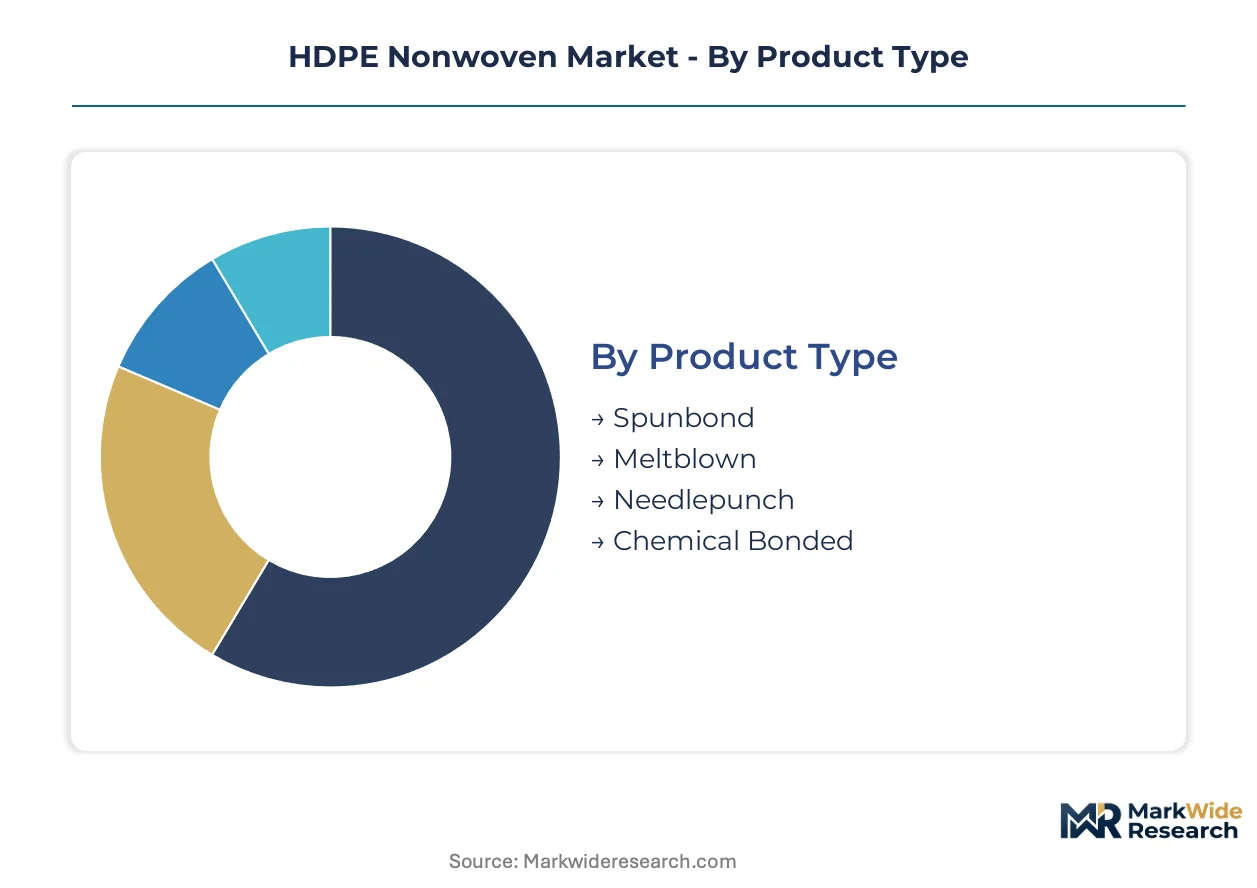
HDPE nonwoven segmentation reveals stark divergences in production velocity and margin architecture. Spunbond lines achieve full capacity utilization within months of commissioning, while needlepunch operations amortize equipment over decades of civil engineering contracting cycles.
Product Type:
Spunbond turns inventory fastest with continuous filament output suited for medical converting contracts. Meltblown commands extended qualification timelines for FDA 510(k) submissions. Needlepunch and chemical bonded processes anchor longer-term infrastructure procurement cycles with multi-year amortization horizons.
- Spunbond:Continuous filament construction achieves basis weights between 8 and 50 grams per square meter through thermal point-bonding of extruded HDPE streams. High-speed hygiene and medical converting in Germany's industrial corridor absorbs volume as Berry Global and Freudenberg anchor supply contracts.
- Meltblown:Sub-5-micron fiber diameters deliver fine-filtration efficiency for surgical masks and liquid barrier media. Process engineering talent scarcity in Germany and the United States constrains capacity expansion despite premium pricing for AAMI Level 3 and 4 barrier applications.
- Needlepunch:Mechanical entanglement of staple fibers produces durable geotextile structures for separation and reinforcement layers in civil engineering specifications.
- Chemical Bonded:Latex or resin bonding systems serve specialized industrial applications where thermal sensitivity precludes melt-based consolidation methods.
Spunbond dominates installed base. Meltblown is where expansion concentrates.
Application:
Medical applications command shortest sales cycles with spot purchasing for pandemic response stockpiles. Geotextile contracts extend across multi-year infrastructure development timelines with milestone-based delivery schedules.
- Medical:Surgical drapes, gowns, and sterile barrier systems require biocompatibility validation under FDA and CDSCO frameworks. Indian hospital procurement is accelerating as enforcement of ISO-certified standards creates first-mover advantage for qualified suppliers.
- Filtration:HVAC, liquid filtration, and industrial dust collection media specify HDPE for chemical resistance and moisture immunity. REACH Article 33 disclosure requirements for Substances of Very High Concern are forcing reformulation of additive packages in European supply.
- Geotextiles:Separation, reinforcement, and drainage layers in road construction, landfill capping, and erosion control. MEE specifications for 30-year design-life materials in China's high-speed rail pipeline specify UV-stabilized grades.
- Agriculture:Crop protection fabrics, greenhouse shading, and soil stabilization membranes serve seasonal planting cycles with price-sensitive procurement patterns.
Medical commands premium pricing tiers. Geotextiles anchor volume throughput.
End User:
Healthcare procurement operates on emergency response timelines with compressed vendor qualification. Construction sector purchasing follows project finance disbursement schedules with extended payment terms.
- Healthcare:Hospital systems and surgical centers demand sterile barrier assurance with documented sterility assurance levels. FDA oversight enforces 18-24 month validation timelines for new product commercialization.
- Construction:Engineering procurement construction firms consolidate specification authority for infrastructure geotextiles. Fibertex and Freudenberg anchor approved supplier status through captive technical service teams.
- Automotive:Interior trim, insulation, and filtration components specify HDPE for lightweighting and chemical resistance against fluid exposure.
- Hygiene:Diaper backsheet and feminine hygiene applications face displacement pressure from lower-density polypropylene alternatives achieving comparable fluid management at reduced freight cost per unit area.
Healthcare drives specification intensity. Construction concentrates procurement volume.
Distribution Channel:
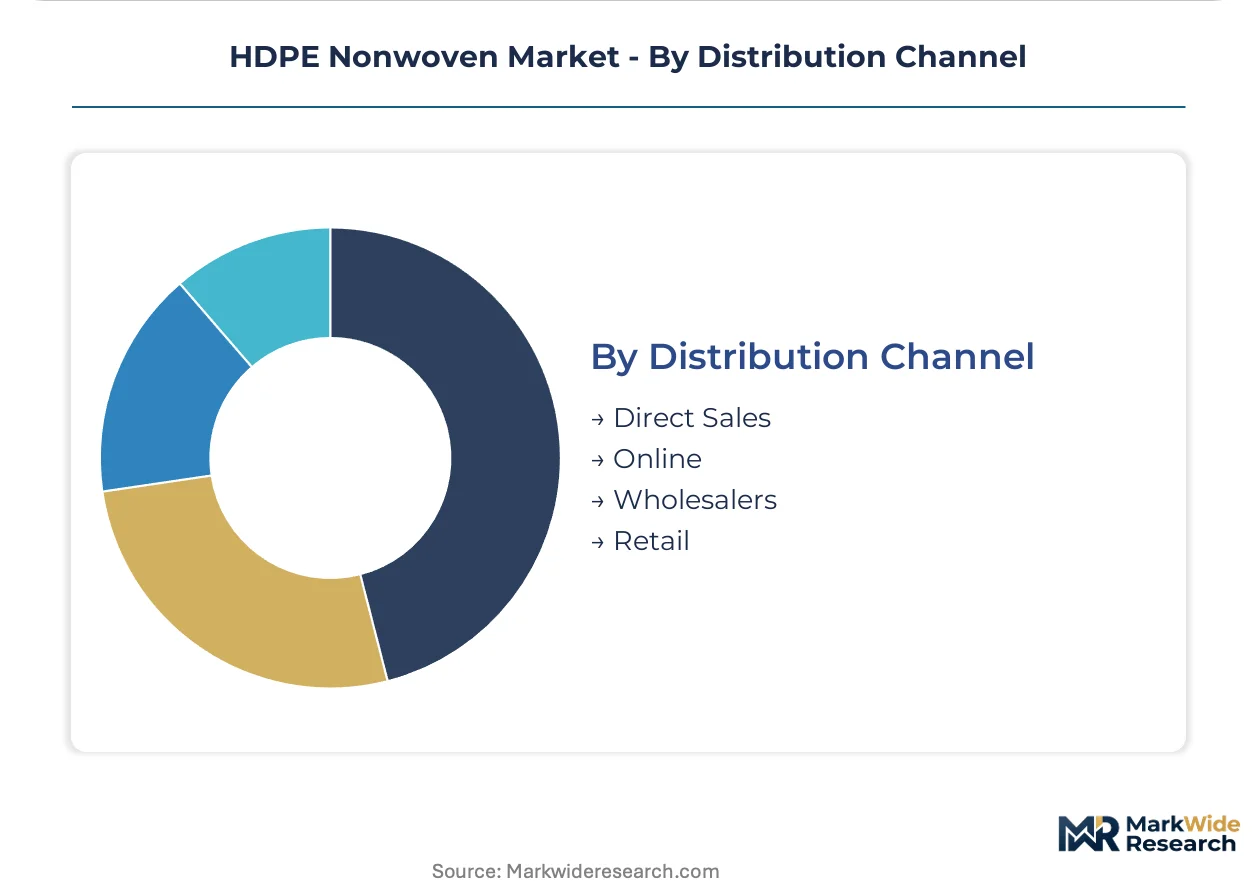
Direct sales relationships with tier-one converters minimize margin leakage for technical grades. Online channels serve spot purchasing for standardized hygiene materials with compressed lead times.
- Direct Sales:Long-term supply agreements with medical converters and automotive tier suppliers lock in volume commitments with price adjustment clauses tied to ethylene feedstock indices.
- Online:E-commerce platforms serve mid-scale regional converters and maintenance-repair-operations purchasing for non-critical applications.
- Wholesalers:Inventory aggregation for construction and agriculture segments with seasonal demand patterns requiring buffer stock positioning.
- Retail:Consumer-facing channels for DIY geotextile and agricultural fabric applications with limited technical support requirements.
Direct sales capture margin concentration. Online channels are climbing the fastest for standardized grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal circularity mandates are redirecting capital toward recyclability infrastructure across multiple jurisdictions. Germany's industrial corridor concentrates technical nonwoven demand. India's CDSCO enforcement creates new compliance thresholds for medical-grade suppliers.
United States
FDA 510(k) sterilization validation timelines extend product commercialization cycles for surgical drape applications. EPA Clean Air Act standards regulate industrial nonwoven manufacturing emissions. The US Gulf Coast naphtha-cracker corridor transmits ethylene feedstock price volatility directly to HDPE resin contract pricing.
Germany
Technical nonwoven demand concentrates in civil engineering specifications for separation and reinforcement layers. REACH Article 33 disclosure requirements for Substances of Very High Concern force reformulation of UV stabilizer packages. Freudenberg Performance Materials anchors approved supplier status for federal highway contracts through captive technical service teams.
China
Dual carbon goals in the infrastructure pipeline specify UV-stabilized HDPE for 30-year design-life geotextiles. MEE regulations govern high-speed rail and landfill capping material specifications. The Yangtze River Delta hosts spunbond line installations serving domestic hygiene and medical converting demand.
India
CDSCO enforcement of biocompatibility standards for surgical drapes accelerates hospital procurement of ISO-certified materials. First-mover advantage accrues to HDPE suppliers establishing local converting partnerships. Maharashtra's industrial belt concentrates regional converter activity for medical-grade nonwoven distribution.
HDPE Nonwoven Market Vendor Landscape
On the supply side, the industry is consolidating around integrated multinationals with captive resin sourcing and technical service capabilities. Asset-light leasing models for spunbond production lines are fragmenting entry barriers toward mid-scale regional converters. Three archetypes dominate: integrated resin-to-fabric multinationals, regional technical specialists, and hygiene-focused volume producers. Competitive moves center on backward integration into polymer compounding and geographic expansion through engineering procurement construction firm vendor list approvals.
Among integrated multinationals, Berry Global represents the North American volume producer archetype with broad hygiene-grade supply capabilities. Freudenberg Performance Materials occupies the European technical specialist position anchored in filtration and automotive applications. DuPont exemplifies the materials science conglomerate model with cross-polymer technology platforms serving medical barrier specifications.
| Leading Market Players |
|---|
| DuPont |
| Toray Industries |
| Berry Global |
| Freudenberg Performance Materials |
| Fitesa |
| Fibertex Nonwovens |
| Kimberly-Clark |
| Asahi Kasei |
| Thrace Group |
| Others |
Supply Flow & Price Mechanics
Ethylene feedstock price volatility in the US Gulf Coast and Northwest Europe determines both pricing tier spreads and supply chain shape across the HDPE nonwoven market. Naphtha-cracker output fluctuations transmit directly to resin contract pricing, compressing converter margins during upstream tightness and forcing geographic sourcing diversification.
Pricing Analysis
Certification level creates the primary spread across pricing tiers, with FDA-grade medical materials commanding substantial premiums over industrial geotextile grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO certification status, UV stabilizer package quality, and volume commitment scale. Cost compression in hygiene-grade spunbond is intensifying because polypropylene substitutes achieve comparable fluid management at reduced freight cost per unit area. Healthcare procurement committees exhibit lowest price sensitivity due to sterility assurance requirements, while municipal geotextile buyers operate under rigid project-budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for equipment-dependent capacity expansion. German and Italian equipment builders control the majority of global installed capacity for high-output spunbeam systems, creating delivery bottlenecks for new market entrants. Raw material sourcing draws from Saudi Arabian and US Gulf Coast ethylene derivatives, with compounding operations concentrated in Belgium and the Netherlands. Single-source vulnerability for sub-5-micron meltblown process engineering talent in Germany and the United States constrains premium filtration-grade output. Distribution runs through direct sales relationships with tier-one medical converters and engineering procurement construction firms for technical grades, supplemented by wholesaler aggregation for construction and agriculture segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and sterilization validation capabilities represent a service-attach opportunity expanding faster than base material supply, as hospital systems outsource biocompatibility documentation and sterility assurance testing to qualified suppliers.
For Market Incumbents: Pre-empt polypropylene substitution in hygiene applications by accelerating bicomponent spunbond qualification for AAMI Level 3 and 4 barrier performance. Secure backward integration into polymer compounding to control UV stabilizer package reformulation under REACH Article 33 requirements. Capacity addition in India's Maharashtra industrial belt captures first-mover advantage as CDSCO enforcement tightens. For New Entrants and Emerging Players: India's underpenetrated medical nonwoven demand offers the most penetrable white-space target, with ISO-certified surgical drape supply gaps widening as hospital procurement accelerates. Target geotextile segments in China's high-speed rail pipeline where MEE specifications for 30-year design-life materials privilege UV-stabilized HDPE over polyester alternatives. Establish local converting partnerships as the primary go-to-market angle, bypassing direct competition with integrated multinationals for virgin resin supply. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resin-to-fabric multinationals with captive technical service capabilities. Long-term viability over the projection horizon hinges on recyclability infrastructure investment aligned with EU Green Deal circularity mandates. Acquisition target archetype: regional technical specialists with approved vendor status on engineering procurement construction firm lists. Monitor ECHA candidate list expansions for Substances of Very High Concern as the inflection indicator for additive package disruption and reformulation-driven supplier switching.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | In-house additive formulation secures REACH compliance and stabilizes margin capture against resin price volatility. |
| Local Converting Partnership Establishment | CDSCO-compliant sterilization capabilities in India unlock first-mover positioning in accelerating hospital procurement. |
| Bicomponent Spunbond Technology Qualification | Core-sheath fiber architectures displace separately laminated film layers in AAMI Level 3 and 4 surgical gown applications. |
| Engineering Procurement Construction Vendor List Approval | Pre-approved supplier status on Fibertex and Freudenberg-anchored lists secures multi-year infrastructure contract access. |
| Recyclability Infrastructure Investment | Closed-loop feedstock integration aligns with EU Green Deal mandates and privileges mono-material HDPE constructions. |
Methodological Framework
Cross-validation between primary interviews with plant managers at spunbond and meltblown facilities and secondary validation through customs trade data, SEC filings from integrated resin producers, and ECHA regulatory filings anchors the qualitative findings. Conversations with procurement leads at hygiene converters, technical R&D directors at geotextile compounders, and distribution channel partners in Germany's industrial corridor informed capacity utilization and qualification timeline assessments. Bottom-up and top-down triangulation reconciles equipment installation databases with resin consumption patterns across medical, filtration, and infrastructure end-uses.
Calibration against historical capacity expansion cycles and feedstock price correlation patterns shapes the analytical framework across the analysis window. Segmentation dimensions modeled include product type (spunbond, meltblown, needlepunch), application (medical, filtration, geotextiles, agriculture), and end user (healthcare, construction, automotive, hygiene), with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derive from elasticity-adjusted demand projections tied to civil engineering specification evolution and hospital procurement enforcement timelines. Industry-specific forecast inputs incorporate spunbond line delivery backlogs from German and Italian equipment builders and CDSCO inspection cadence for ISO-certified medical material facilities.
Practitioners should monitor ethylene feedstock contract volatility, REACH candidate list expansions, and engineering procurement construction firm vendor list revisions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market