
 Global Hemp Fiber Market | 2026-2036
Global Hemp Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemp Fiber Market Foresight
Project finance tied to sustainable agriculture infrastructure is reconfiguring competitive entry barriers for hemp fiber producers. HempFlax Group B.V. leverages vertical integration across cultivation and decortication in the Netherlands. Ecofibre Ltd. anchors its position through pharmaceutical-grade hemp expertise that extends into technical fiber applications. Panda Biotech controls large-scale processing capacity in Texas, competing on volume against European specialists.
Hemp fiber consists of cellulose-rich bast strands extracted from Cannabis sativa stalks, typically measuring 1-2 meters in length with tensile strength comparable to glass fiber at lower density. The material primarily serves as a renewable reinforcement in polymer composites and a sustainable textile feedstock. Decorticated fibers dominate current output volumes due to established supply chains serving automotive tier-one suppliers. Tow fibers represent the fastest-expanding category as paper producers seek pulping alternatives to virgin wood. Processed fibers command premium positioning where chemical treatment enables thermoplastic compatibility for injection-molded biocomposites.
The EU Green Deal and REACH chemical standards shape material qualification pathways for hemp fiber entering European automotive and construction supply chains. The USDA hemp cultivation framework and state-level processing permits in the United States determine feedstock availability for domestic manufacturers. China's GB standards for natural fiber composites influence export specifications for Asian-market biocomposite producers. Stakeholders must track evolving carbon-accounting methodologies that will determine which fiber processing techniques qualify for green procurement mandates.
Market Dynamics
The EU Green Deal's material qualification mandates are compressing automotive supply chains toward certified natural fiber reinforcements, forcing tier-one suppliers to requalify polymer composite feedstocks under REACH-compliant carbon-accounting protocols.
Growth Catalysts
- REACH chemical standards:European automotive manufacturers must substitute glass fiber with low-carbon bast fibers to meet EU Green Deal procurement thresholds, creating immediate qualification demand for decorticated hemp.
- Water retting technology upgrades:French processors deploying controlled enzymatic retting achieve fiber quality consistency previously unattainable with field retting, unlocking premium textile applications.
- German automotive sector:BMW and Mercedes-Benz integration of natural fiber composites into interior paneling establishes volume offtake contracts that stabilize processor margins.
Market Restraints
- Flax fiber substitution:Established European flax supply chains offer comparable mechanical properties with existing automotive qualification status, limiting hemp fiber pricing power in composite applications.
- Seasonal input volatility:Bast fiber yields depend on specific humidity windows during field retting; weather anomalies in Romania and Poland disrupt raw material availability for Central European decortication facilities.
- USDA cultivation framework:Interstate hemp transportation restrictions and state-level THC testing inconsistencies fragment North American feedstock aggregation, raising procurement costs for Texas-based processors.
Strategic Opportunities
- India technical textile expansion:BIS certification pathways for natural fiber geotextiles in railway and highway construction create import demand for long-bast hemp varieties currently unmet by domestic jute production.
- Construction sector biocomposites:Hemp-lime insulation panels gain traction in French and Belgian building codes as operators seek carbon-negative envelope materials to satisfy CSRD reporting requirements.
- Pharmaceutical-grade fiber crossover:Dual-use cultivation licenses allow processors to extract CBD from floral biomass while converting stalks to technical fibers, improving per-hectare economics.
Industry Challenges
- Decortication equipment specialization:Bast fiber separation requires precision-engineered roller systems with limited supplier base; maintenance downtime at French and Dutch facilities creates order backlogs.
- Carbon-accounting methodology divergence:Competing ISO and EU PEF standards for biogenic carbon calculation generate client-specific documentation requirements that extend sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemp Fiber Market |
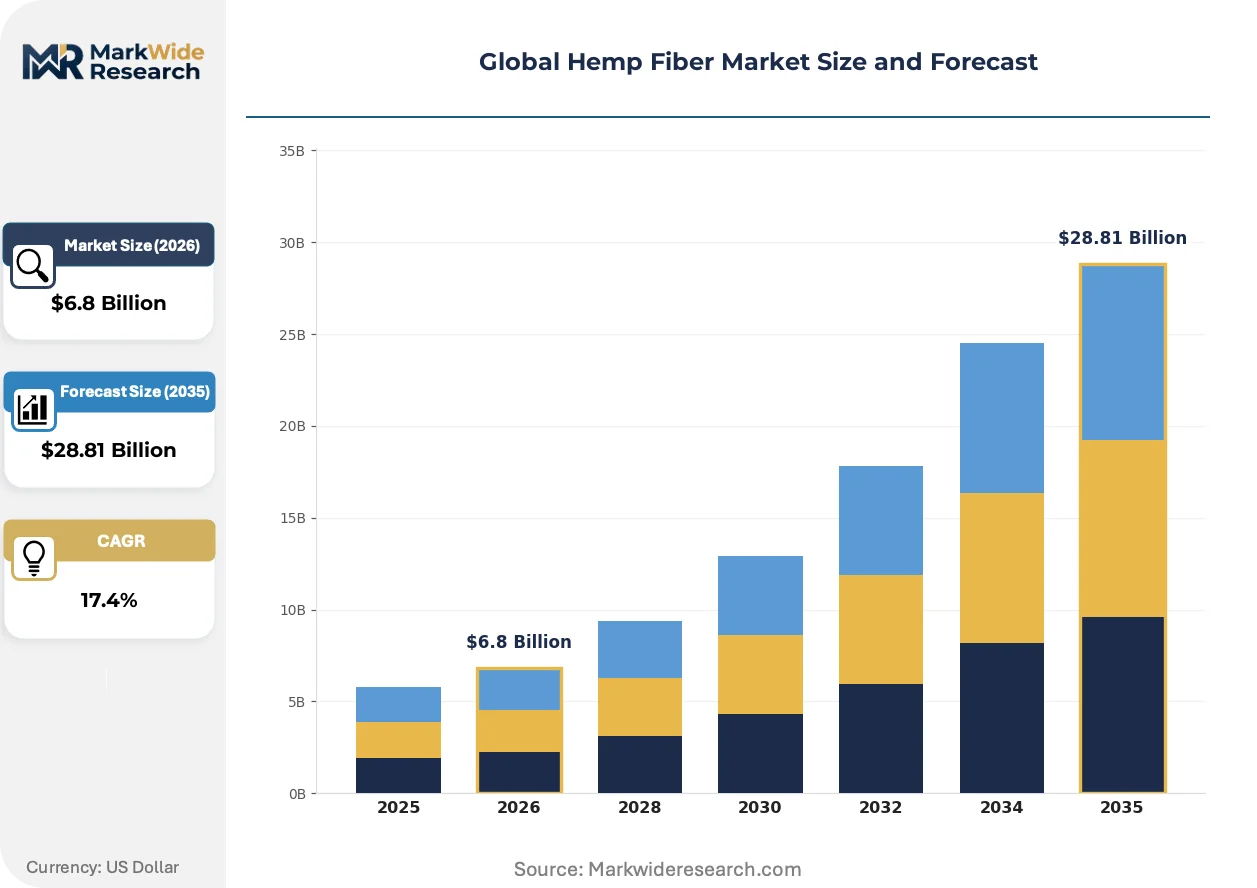
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Hemp Fibers, Decorticated Fibers, Tow Fibers, Processed Fibers Application: Textiles, Automotive Components, Paper, Construction Materials, Biocomposites End User: Textile Manufacturers, Auto Parts Suppliers, Paper Producers, Building Contractors Processing Technique: Retting, Decortication, Mechanical Processing, Chemical Treatment |
| Companies Covered | HempFlax Group B.V., Dun Agro Hemp Group, Ecofibre Ltd., Panda Biotech, IND HEMP, Konoplex LLC, Hemp Inc., Bast Fibre Technologies, La Chanvrière, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemp Fiber Market Shifts & Advancements
Mechanical processing automation and enzymatic fiber modification are collapsing quality variance in bast fiber output, enabling hemp to compete with synthetic reinforcements on specification consistency rather than sustainability narrative alone.
Steam explosion pretreatment combined with alkali surface modification is rendering obsolete conventional chemical retting for thermoplastic composite compatibility. German automotive compounders at BASF and Lanxess now specify explosion-treated hemp fiber for injection-molded interior components. The technology eliminates the 14-21 day field retting cycle, compressing raw material-to-pellet lead times from months to days.
China's GB standards for natural fiber composites are mandating flame-retardant performance thresholds that European hemp fiber currently fails without additive treatment. Domestic Chinese processors are blending hemp with basalt fiber to achieve GB 8624 classification, creating a hybrid material category that reshapes export specifications for Asian-market biocomposite producers. European suppliers must reformulate surface chemistry or cede construction applications to modified domestic supply.
Automotive buyers are consolidating supplier rosters from twelve-plus regional fiber traders to three vertically integrated processors with captive decortication and compounding capabilities. BMW's natural fiber procurement now routes exclusively through HempFlax and two certified French cooperatives, eliminating spot-market purchasing. The concentration shifts price discovery from commodity indexes to bilateral frame contracts indexed to polypropylene futures.
Global Hemp Fiber Market Segmentation
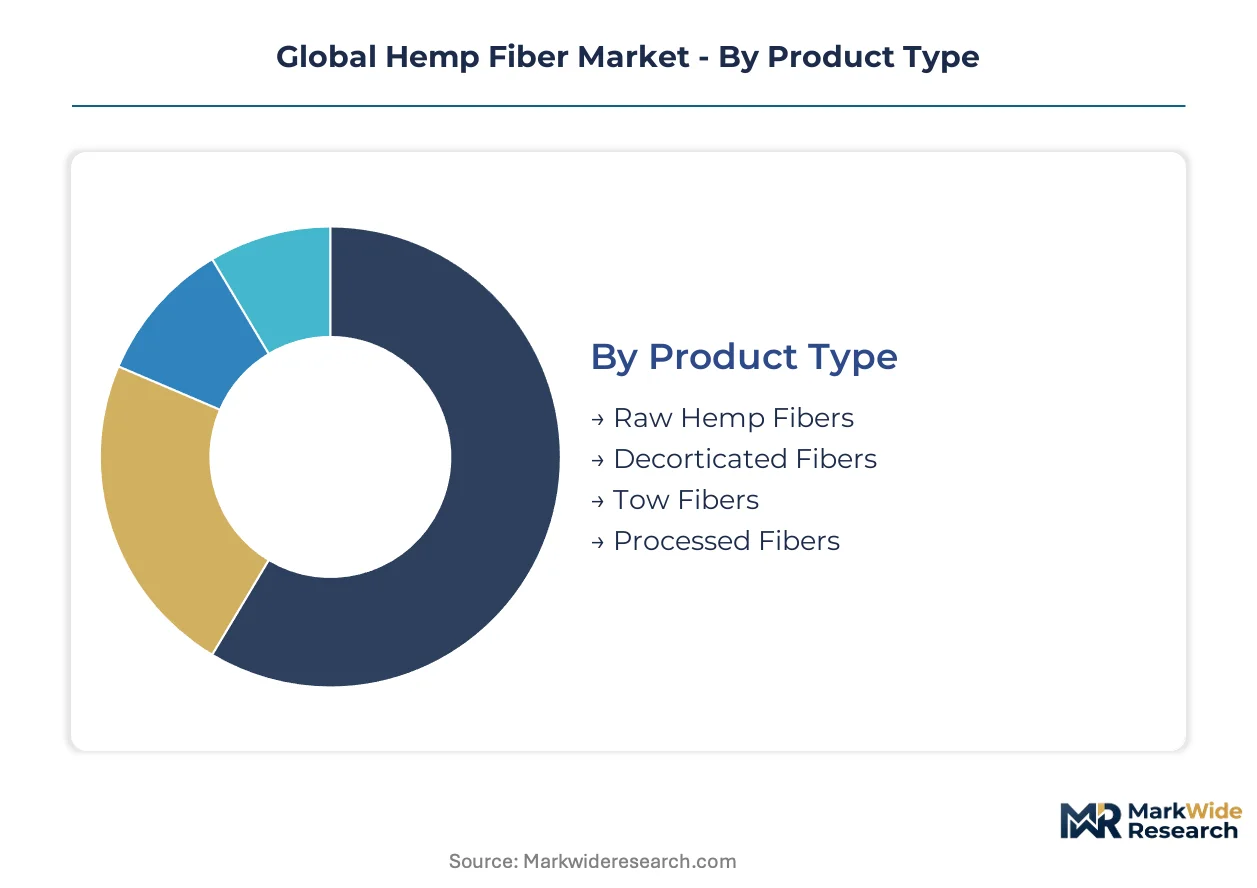
Hemp fiber segmentation reflects divergent maturity across processing stages and end-use qualification requirements. Product type categories separate commodity feedstocks from value-added technical materials, while application segments track automotive adoption against traditional textile demand.
Product Type:
Mature industrial grades dominate volume flows, with emerging processed variants capturing specification-sensitive niches in polymer compounding.
- Decorticated Fibers:Bast strands mechanically separated from hemp stalks after retting, retaining 15-25% shive content suitable for non-woven mats and composite preforms. BMW and Mercedes-Benz procurement contracts in Germany absorb the majority of European decorticated output under EU Green Deal material mandates. Decorticated fibers handle the majority of throughput; tow fibers are the fastest mover on share.
- Tow Fibers:Short, tangled fiber bundles collected during hackling and scutching operations, historically treated as waste stream. French paper producers at Smurfit Kappa and Norske Skog now specify hemp tow for specialty pulp blends to reduce virgin wood dependence, with import demand rising from Indian technical textile compounders seeking geotextile feedstock.
- Raw Hemp Fibers:Unprocessed stalk bundles delivered directly from field retting operations, requiring downstream decortication.
- Processed Fibers:Chemically modified or steam-explosion treated fibers engineered for thermoplastic compatibility and injection molding applications.
Decorticated fibers handle the majority of throughput; tow fibers are expanding most quickly on share.
Application:
Cost tier differentiation separates established commodity applications from emerging premium segments commanding qualification-intensive supply relationships.
- Automotive Components:Natural fiber reinforced polymer composites for interior door panels, seat backs, and parcel shelves, typically loaded at 30-50% fiber weight fraction. German OEM qualification protocols under REACH carbon-accounting standards have locked in three-year supply frames with Dutch and French processors, freezing out spot-market traders. Automotive components command the highest margin tier; construction materials are climbing the fastest.
- Biocomposites:Hemp fiber combined with bio-based or recycled polymer matrices for consumer goods and industrial packaging applications. Lanxess and BASF compounding facilities in Germany now specify explosion-treated hemp fiber for polypropylene hybrid pellets, displacing short glass fiber in non-structural automotive parts and appliance housings.
- Textiles:Long bast fibers spun into yarn for apparel, home furnishings, and cordage applications.
- Paper:Tow fiber and shive fractions pulped for specialty printing papers and cigarette paper substitutes.
- Construction Materials:Hemp-lime composite panels and insulation batts for carbon-negative building envelopes.
Automotive components command the highest margin tier; construction materials are climbing the fastest.
End User:
Customer type concentration reflects procurement capability divergence between multinational tier-one suppliers and fragmented regional processors.
- Auto Parts Suppliers:Tier-one compounders and molders serving BMW, Mercedes-Benz, and Volkswagen with qualified natural fiber composite supply. Continental and Faurecia have consolidated hemp fiber procurement to three vertically integrated European processors, eliminating twelve regional traders from approved vendor lists.
- Textile Manufacturers:Spinners and weavers processing long bast fiber for apparel and technical fabric production.
- Paper Producers:Pulp mills integrating hemp tow as hardwood pulp extender in specialty paper grades.
- Building Contractors:French and Belgian construction firms specifying hemp-lime panels for CSRD-compliant building envelope retrofits.
Auto parts suppliers concentrate the highest procurement volumes; building contractors are gaining share fastest.
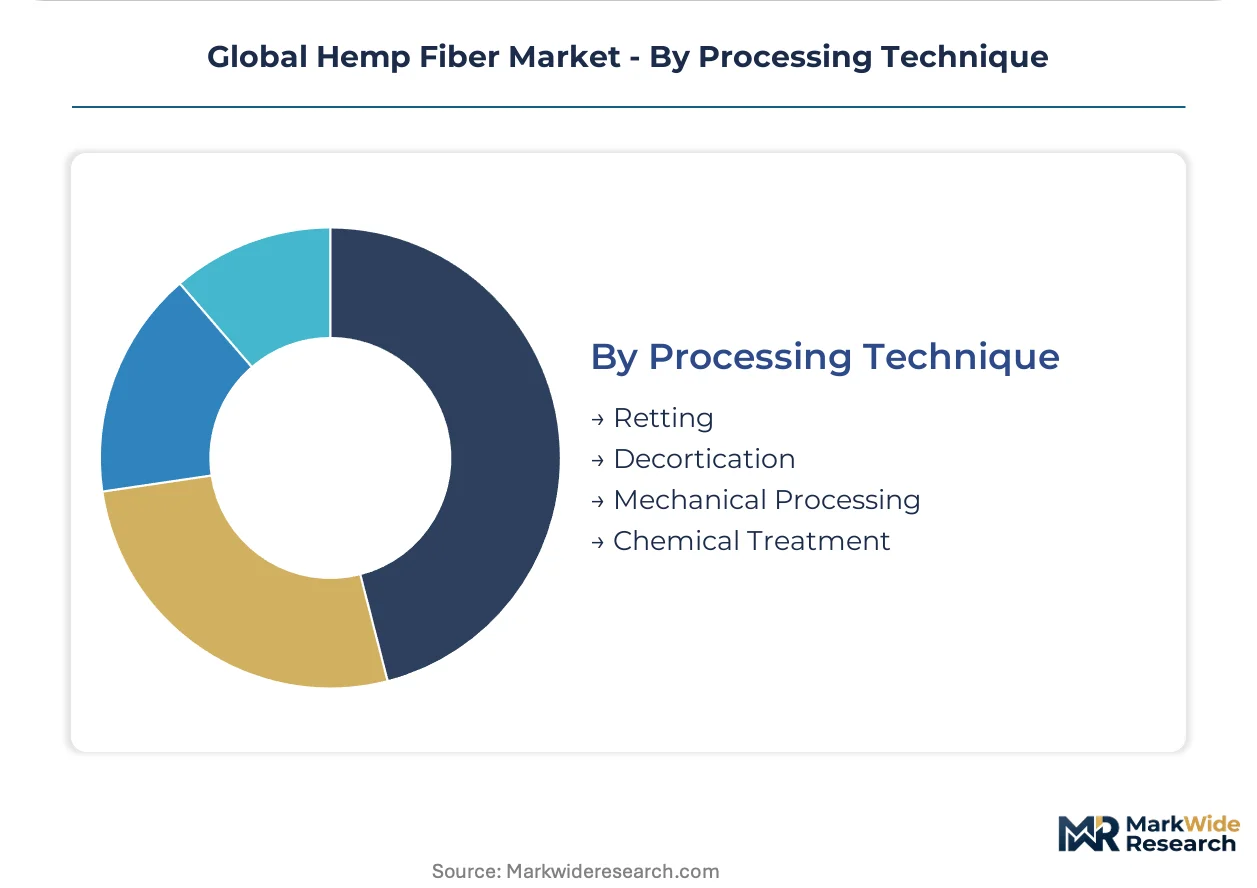
Processing Technique:
Technology maturity splits field-dependent traditional methods from capital-intensive controlled processes enabling specification consistency.
- Water Retting:Controlled enzymatic decomposition of pectin binders in tank or river environments, achieving fiber quality consistency unattainable with field retting. French processors in Picardy and Normandy have retrofitted tank retting infrastructure with temperature and pH monitoring, unlocking premium textile applications previously reserved for flax.
- Steam Explosion:High-pressure steam pretreatment combined with rapid decompression to separate fiber bundles and modify surface chemistry for thermoplastic compatibility. German automotive compounders specify explosion-treated fiber for injection-molded interior components, compressing raw material-to-pellet lead times from months to days.
- Decortication:Mechanical roller and breaker systems separating bast fiber from woody core.
- Chemical Treatment:Alkali or silane surface modification rendering fibers compatible with hydrophobic polymer matrices.
Water retting handles the majority of throughput; steam explosion is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement mandates and carbon-accounting protocols are redrawing competitive boundaries for hemp fiber suppliers across major industrial economies.
Germany
BMW and Mercedes-Benz qualification protocols for natural fiber composites absorb the majority of premium European hemp output. REACH-compliant carbon-accounting standards under the EU Green Deal lock processors into three-year supply frames. Stuttgart and Munich automotive clusters drive specification requirements that cascade through Dutch and French upstream suppliers.
France
Picardy and Normandy processors deploy controlled enzymatic water retting to achieve fiber quality consistency matching flax benchmarks. EU Green Deal material mandates accelerate automotive qualification timelines for French cooperatives. The Hauts-de-France region concentrates tank retting infrastructure retrofitted with temperature and pH monitoring systems.
United States
Texas-based processors compete on volume against European specialists despite USDA interstate transportation restrictions fragmenting feedstock aggregation. State-level THC testing inconsistencies raise procurement costs for domestic manufacturers. The Texas Panhandle hosts large-scale decortication capacity serving automotive compounders seeking North American supply alternatives.
China
GB standards for natural fiber composites mandate flame-retardant performance thresholds that European hemp currently fails without additive treatment. Domestic processors blend hemp with basalt fiber to achieve GB 8624 classification for construction applications. Yangtze River Delta biocomposite producers reshape export specifications for Asian-market supply.
India
BIS certification pathways for natural fiber geotextiles in railway and highway construction create import demand for long-bast hemp varieties. Domestic jute production cannot meet technical textile specifications for infrastructure applications. Gujarat and Maharashtra textile compounders source hemp tow for geotextile feedstock currently unmet by local supply.
Global Hemp Fiber Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around vertically integrated processors with captive decortication and compounding capabilities. Automotive buyers have compressed approved vendor lists from twelve-plus regional traders to three frame-contract suppliers. Two strategic archetypes dominate: European cooperatives with EU Green Deal certification and North American volume processors with state-level cultivation permits. Competitive moves center on backward integration into cultivation and enzymatic retting technology licensing.
Among European specialists, HempFlax Group B.V. and La Chanvrière occupy positions exemplifying the certified-integration archetype, while Panda Biotech represents the scale-driven North American model. These three anchors illustrate how qualification-intensive automotive supply chains favor processors with controlled upstream supply and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| HempFlax Group B.V. |
| Dun Agro Hemp Group |
| Ecofibre Ltd. |
| Panda Biotech |
| IND HEMP |
| Konoplex LLC |
| Hemp Inc. |
| Bast Fibre Technologies |
| La Chanvrière |
| Others |
Supply & Pricing Matrix
Picardy and Normandy processing clusters anchor European hemp fiber supply, with controlled water retting infrastructure creating quality premiums that cascade into automotive procurement contracts. Tank retting investments by French cooperatives compress field-to-fiber lead times, shifting pricing power toward processors with enzymatic capability and EU Green Deal certification.
Pricing Analysis
Certification level (EU Green Deal/REACH-compliant vs. standard industrial grade) creates the primary spread between premium and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects decortication precision, shive content, and thermoplastic compatibility after steam explosion treatment. Price differentiation stems from automotive qualification status and captive cultivation control. Cost compression in standard-grade decorticated fiber is intensifying because Romanian field retting disruptions force spot-market buyers toward premium French supply. Building contractors exhibit highest price sensitivity due to unstandardized hemp-lime application protocols, while German tier-one auto parts suppliers accept premium positioning for frame-contract security.
Supply Chain Analysis
Export-control restrictions on precision decortication roller systems limit technology transfer to Asian processors, preserving European equipment specialization. Supply concentrates in France, the Netherlands, and Germany for high-grade bast fiber, with Texas-based volume processors competing on North American feedstock aggregation. Raw material flows draw from Romanian and Polish cultivation zones, enzymatic retting tank infrastructure, and German automotive compounding facilities. Single-source vulnerability sits with French roller equipment suppliers whose maintenance backlogs cascade into order delays. Distribution runs through vertically integrated processors with captive decortication, bypassing the twelve-plus regional traders previously serving spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hemp fiber markets reward processors bundling fiber supply with carbon-accounting documentation and qualification support services, as automotive buyers seek turnkey compliance solutions rather than commodity procurement. Recurring revenue from certification maintenance and batch traceability systems expands faster than raw fiber tonnage.
For Market Incumbents: Build regulatory compliance moats by securing dual-use cultivation licenses that capture CBD extraction value alongside technical fiber output. Deepen backward integration into enzymatic retting technology licensing to lock out equipment-dependent challengers. Defend against flax fiber substitution by accelerating steam explosion treatment adoption for thermoplastic compatibility. Capacity addition in Hauts-de-France tank retting infrastructure reinforces quality consistency advantages. For New Entrants and Emerging Players: Pursue Indian technical textile white space where BIS certification gaps in geotextile supply create import demand for long-bast varieties. Target construction sector biocomposites in French and Belgian markets where CSRD reporting requirements drive hemp-lime specification but domestic processing capacity remains thin. Agricultural equipment leasing partnerships with regional hemp cooperatives offer lower-capital entry than greenfield decortication investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with proven automotive qualification and captive cultivation control over pure-play equipment operators. Long-term viability hinges on carbon-accounting methodology convergence that rewards early ISO 14067 adopters. Acquisition candidates include French cooperatives with EU Green Deal certification infrastructure and Indian compounders with BIS geotextile approval. Watch for REACH carbon-accounting protocol revisions as inflection signal that reshapes qualified supplier rosters.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Retting Technology Licensing | French processors monetize process IP while constraining competitor equipment access. |
| Dual-Use Cultivation License Expansion | CBD extraction from floral biomass improves per-hectare economics for fiber-dedicated operations. |
| Automotive Frame Contract Consolidation | BMW procurement compression from twelve traders to three suppliers locks in volume offtake. |
| Steam Explosion Treatment Scale-Up | German compounders at Lanxess and BASF specify explosion-treated fiber for injection-molded components. |
| Indian BIS Geotextile Certification | Railway and highway construction import demand opens for long-bast hemp varieties. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Green Deal implementation documents, REACH chemical standards filings, and automotive procurement database entries. Primary interviews engaged decortication plant managers, tier-one auto parts supplier procurement leads, French cooperative technical directors, and German automotive compounder R&D heads. Secondary validation drew from ECHA substance registrations, EU PEF methodological guidance, customs trade flows for hemp fiber HS codes, and SEC filings of publicly traded hemp processors. Bottom-up volume modeling triangulated against top-down market sizing from agricultural cultivation statistics and automotive natural fiber composite content estimates.
Forecast inputs span processing technique adoption curves, EU Green Deal material mandate phase-in schedules, and automotive platform standardization timelines across the projection horizon. Segmentation dimensions include product type maturity, application margin tier, end-user procurement capability, and processing technology capital intensity. CAGRs derive from fitted adoption curves for steam explosion treatment and enzymatic retting infrastructure deployment. Industry-specific inputs incorporate REACH carbon-accounting protocol revision probability and BIS geotextile certification pipeline status.
Macroeconomic conditions sit as an overlay; deviation in automotive production cycles, agricultural commodity input costs, or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on technology adoption rates and certification timeline adherence. Material shifts in EU PEF biogenic carbon calculation methodology or USDA interstate hemp transportation framework would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Silk Stocking Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
North America Cotton Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Silk Market
Natural Fibers
Silk Mask Market
Natural Fibers
Fenugreek Fiber Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Modal Fiber Market
Natural Fibers
Jute Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Natural Fibers and Sisal Market