
 Barrier Nonwoven Fiber for Breathable Surgical Gowns Market | 2026-2036
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market Insights
Buyer concentration among hospital procurement networks is broadening as group purchasing organizations aggregate demand across multi-hospital systems. Ahlstrom leverages its European manufacturing footprint to serve these consolidated buyers with consistent meltblown capacity. Cardinal Health sustains competitive position through deep distribution relationships with integrated delivery networks. Freudenberg Performance Materials differentiates via specialized composite structures that balance viral barrier properties with moisture vapor transmission.
Barrier nonwoven fiber for breathable surgical gowns comprises engineered polymeric webs, typically polypropylene or polyethylene layered through spunbond-meltblown-spunbond (SMS) architecture, achieving bacterial filtration efficiency above 95% while maintaining air permeability below 25 cfm. These materials function as the critical fluid and microbial barrier in personal protective equipment for operating room environments. Spunbond-meltblown composites command the dominant share of fabric technology demand due to their proven balance of protection and breathability, while spunlace alternatives are gaining traction in isolation gown applications where softer drape characteristics matter. Polypropylene fibers anchor the bulk of volume consumption given cost efficiency and thermal bonding compatibility, though polyethylene blends are expanding in procedure gown segments requiring enhanced liquid repellency.
FDA 510(k) clearance requirements and AAMI PB70 liquid barrier classification standards shape product development priorities and market access thresholds for domestic suppliers. The EPA's emerging scrutiny of per- and polyfluoroalkyl substances in textile treatments is pressuring manufacturers to reformulate durable water repellent chemistries used in premium gown grades. Stakeholders must monitor evolving AAMI level designations and state-level hospital sustainability mandates to align R&D investments with forthcoming procurement specifications.
Market Dynamics
Hospital procurement alliances are consolidating volume toward certified suppliers, compressing vendor margins while elevating compliance thresholds for AAMI PB70 liquid barrier classifications across North American healthcare networks.
Growth Catalysts
- AAMI PB70 Level 4 adoption:Ambulatory surgical centers are upgrading gown specifications to meet enhanced liquid barrier protocols, driving meltblown-spunbond composite demand.
- Spunbond-meltblown-spunbond architecture:SMS fabric technology delivers bacterial filtration efficiency above 95% while maintaining surgical drape breathability below 25 cfm.
- United States hospital consolidation:Integrated delivery networks aggregate purchasing power across multi-hospital systems, favoring suppliers with validated FDA 510(k) clearances.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings compress margin stability for meltblown fiber producers dependent on petrochemical supply chains.
- European manufacturing concentration:Ahlstrom's dominant continental capacity creates single-source vulnerability for buyers seeking SMS composite consistency.
- Per- and polyfluoroalkyl substance regulatory friction:EPA scrutiny of durable water repellent chemistries forces reformulation of premium gown-grade treatments without performance degradation.
Strategic Opportunities
- Spunlace technology convergence:Softer drape characteristics in isolation gown applications create entry points for hydroentangled nonwovens competing against traditional SMS structures.
- State-level hospital sustainability mandates:California and New York procurement specifications favor recyclable or reduced-carbon-footprint barrier fabrics, rewarding early reformulators.
- Direct-to-facility distribution channels:Bypassing traditional medical supply distributors allows specialized composite manufacturers to capture margin from consolidated IDN buyers.
Industry Challenges
- FDA 510(k) clearance timelines:Extended regulatory review periods delay product launches for modified meltblown fiber specifications, freezing R&D investment returns.
- Legacy sterilization compatibility:Gamma and ethylene oxide validation requirements for new composite structures add eighteen-month certification cycles before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Nonwoven Fiber for Breathable Surgical Gowns Market |
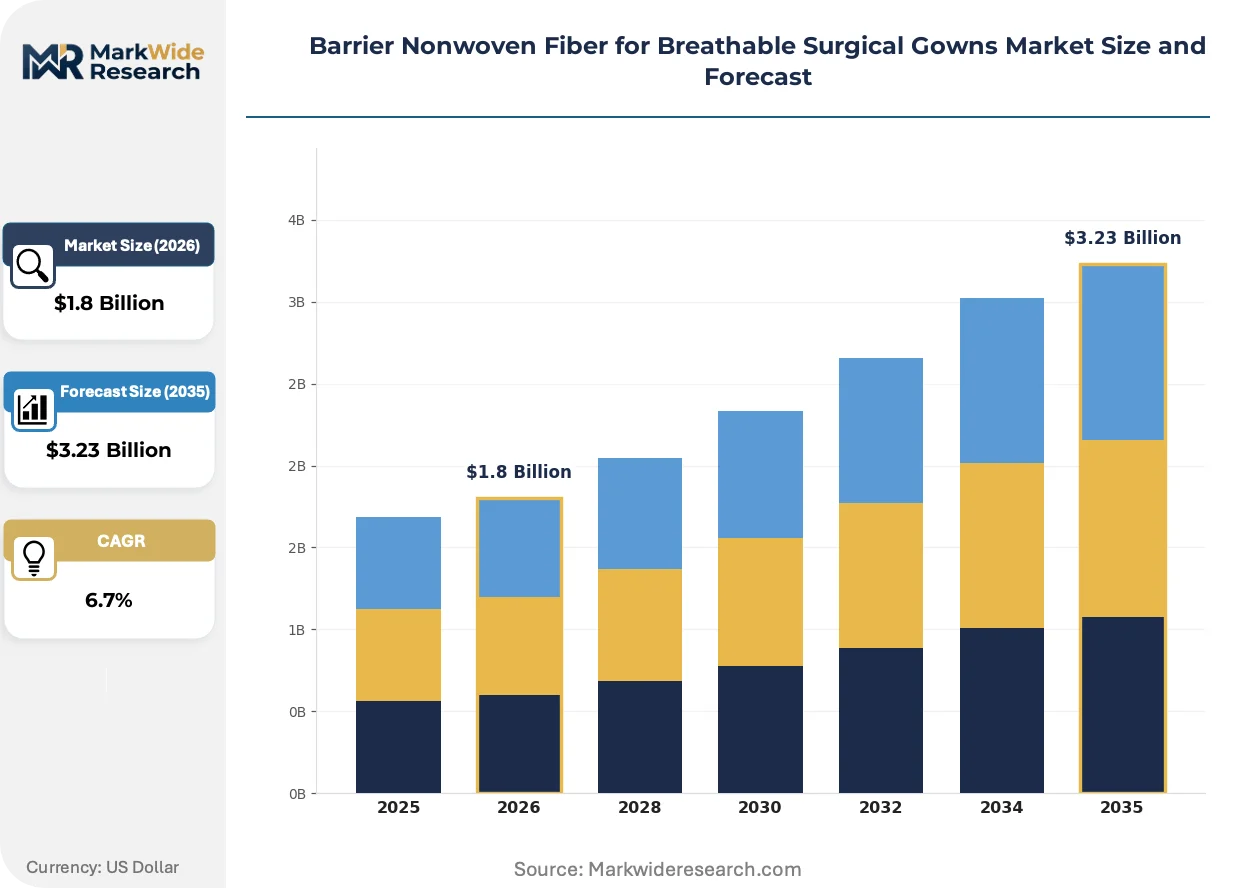
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fiber Type: Polypropylene, Polyester, Polyethylene, Rayon, Nylon, Acrylic Fabric Technology: Spunbond, Meltblown, Spunlace, Airlaid, Needle Punch Application: Disposable Surgical Gowns, Isolation Gowns, Endoscopy Gowns, Procedure Gowns, Sterile Drapes End User: Hospitals, Ambulatory Surgical Centers, Clinics, Long-term Care Facilities, Diagnostic Centers |
| Companies Covered | Berry Global, Ahlstrom, Freudenberg Performance Materials, Avgol, Mitsui Chemicals Asahi Life Materials, Fitesa, Mogul, Medline Industries, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market Trends and Innovations
Barrier fabric engineering is pivoting toward multi-layer composite optimization as infection control protocols tighten and breathability specifications harden across surgical environments.
Spunbond-meltblown-spunbond architecture is consolidating as the dominant fabrication method for high-performance surgical gowns. Major hospital procurement networks specify SMS construction for Level 3 and Level 4 barrier protection. This consolidation is compressing demand for single-layer spunbond alternatives in operating room applications.
EPA scrutiny of per- and polyfluoroalkyl substances is forcing durable water repellent chemistry reformulation across premium gown grades. Manufacturers must eliminate long-chain fluorinated compounds without sacrificing liquid strike-through resistance. United States suppliers face the steepest compliance curve as state-level chemical disclosure laws proliferate ahead of federal rulemaking.
Group purchasing organizations are aggregating demand across multi-hospital systems, compressing vendor counts and elevating certification requirements. Traditional medical supply distributors lose volume share to direct manufacturer relationships with integrated delivery networks. This concentration is most visible in the United States, where three major GPOs control over sixty percent of acute care facility spending on personal protective equipment.
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market Segmentation
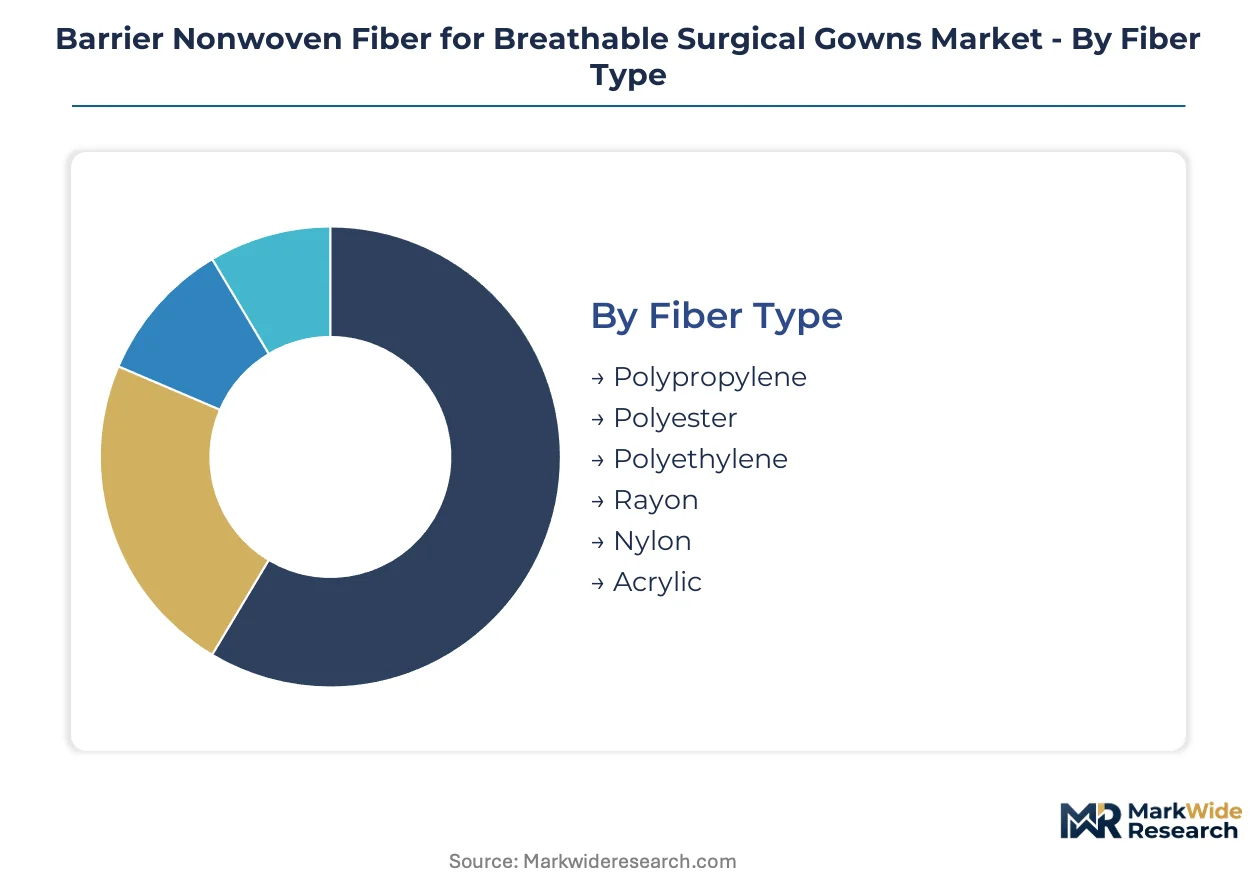
Surgical gown performance hinges on fiber selection, fabric architecture, and sterilization compatibility. Procurement networks evaluate segments against AAMI PB70 liquid barrier tiers and FDA 510(k) validation status. Manufacturers optimize formulations across these dimensions to secure integrated delivery network contracts.
Fiber Type:
Polypropylene dominates standalone applications where thermal bonding and meltblown compatibility matter most, while polyester and polyethylene embed into composite systems requiring specialized liquid repellency.
- Polypropylene:This thermoplastic polymer enables cost-efficient thermal bonding and seamless integration with meltblown layers in SMS architectures. Hospital procurement networks in the United States specify polypropylene for bulk Level 3 gown contracts due to validated sterilization performance and supply chain reliability.
- Polyethylene:Blended formulations enhance liquid strike-through resistance for procedure gowns requiring extended fluid exposure protection. Ambulatory surgical centers in California favor polyethylene-enhanced composites as state chemical disclosure laws pressure fluorinated repellent alternatives.
- Polyester:Superior tensile strength suits reusable gown systems and industrial laundering cycles.
- Rayon:Cellulosic base provides softness in isolation gown applications where patient contact duration extends.
- Nylon:Abrasion resistance serves reinforced zones in high-movement surgical procedures.
- Acrylic:Limited penetration restricted to specialized thermal barrier applications in extended procedures.
Volume placements concentrate in polypropylene; the faster expansion belongs to polyethylene.
Fabric Technology:
Spunbond and meltblown layers anchor high-volume production, while spunlace and airlaid alternatives penetrate niches demanding textile-like hand feel or rapid fluid absorption.
- Spunbond:Continuous filament extrusion creates the structural scaffold in SMS composites, providing tensile integrity for surgical drape applications. United States integrated delivery networks mandate spunbond-meltblond-spunbond construction for Level 4 barrier certification in open-heart and orthopedic procedures.
- Meltblown:Microfiber webs deliver bacterial filtration efficiency above 95% through tortuous path architecture. FDA 510(k) clearance requirements for modified meltblown specifications extend certification timelines, freezing capacity expansion plans for domestic producers.
- Spunlace:Hydroentangled structures compete in isolation gown segments where drape softness influences clinician preference.
- Airlaid:Pulp-synthetic composites absorb fluids rapidly in procedural drape applications.
- Needle Punch:Mechanical bonding suits reusable surgical textile substrates with industrial laundering requirements.
Production scale tilts toward spunbond-meltblown integration; spunlace gains share fastest in non-operating-room settings.
Application:
Disposable surgical gowns command integrated specification workflows, while isolation and procedure gowns follow divergent regulatory and comfort priorities.
- Disposable Surgical Gowns:Single-use SMS construction eliminates cross-contamination risks in invasive procedures. Group purchasing organizations aggregate acute care demand across multi-hospital systems, compressing vendor counts toward suppliers with validated gamma and ethylene oxide sterilization protocols.
- Isolation Gowns:Lower barrier requirements permit spunlace and lighter SMS alternatives where extended wear comfort matters. Ambulatory surgical centers in New York specify recyclable isolation gown grades under state sustainability procurement mandates.
- Endoscopy Gowns:Fluid exposure patterns favor targeted liquid barrier zones rather than full-coverage protection.
- Procedure Gowns:Polyethylene-enhanced composites address brief high-fluid interventions in emergency departments.
- Sterile Drapes:Large-format SMS sheets require specialized folding and packaging for operating room efficiency.
Contract value pools deepest in disposable surgical gowns; isolation gown volume expands most quickly amid outpatient migration.
End User:
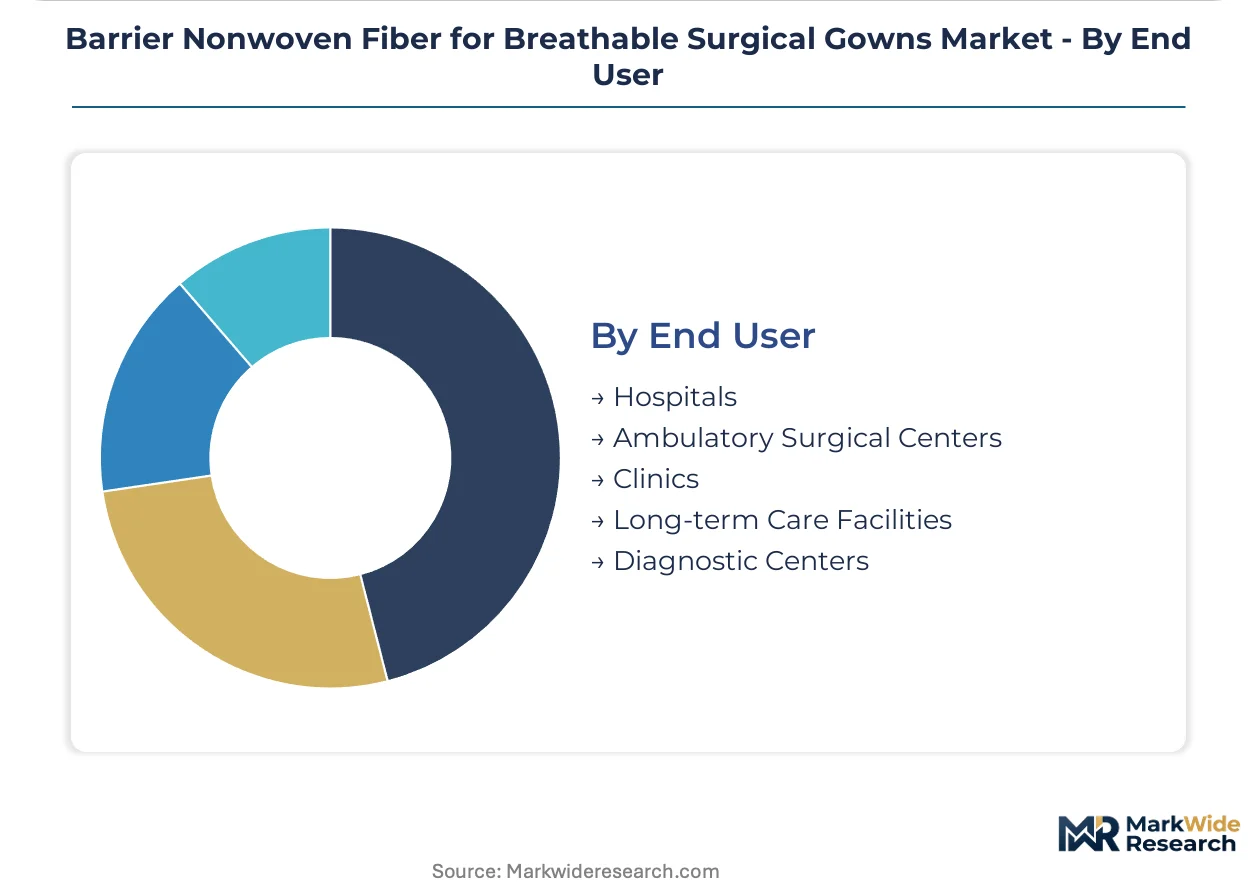
Hospitals anchor certification-heavy procurement, while ambulatory surgical centers and clinics pursue streamlined supplier relationships with lighter compliance burdens.
- Hospitals:Acute care facilities enforce AAMI PB70 Level 3 and Level 4 specifications across operating room and intensive care applications. Three major group purchasing organizations control over sixty percent of United States hospital personal protective equipment spending, concentrating volume toward FDA-cleared manufacturers.
- Ambulatory Surgical Centers:Outpatient settings upgrade barrier protocols as infection control standards tighten, driving meltblown-spunbond composite demand for same-day procedures. These facilities prioritize direct manufacturer relationships over traditional medical supply distributors to capture margin.
- Clinics:Lower-acuity settings accept Level 1 and Level 2 alternatives for minor procedure applications.
- Long-term Care Facilities:Isolation gown demand dominates amid resident infection containment protocols.
- Diagnostic Centers:Imaging and laboratory settings require limited barrier protection for brief patient interactions.
Purchasing authority concentrates in hospital systems; ambulatory surgical centers restructure procurement fastest toward direct manufacturer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin production clusters in the US Gulf Coast anchor raw material flows for breathable barrier fabric manufacturing. Hospital procurement consolidation and regulatory tightening shape demand geography across major healthcare markets.
United States
Integrated delivery networks in Texas and Louisiana aggregate purchasing power across multi-hospital systems, compressing vendor counts toward FDA-cleared suppliers. The FDA's updated 510(k) guidance on liquid barrier performance elevates compliance thresholds for domestic manufacturers. Houston-area petrochemical corridors supply feedstock to meltblown fiber producers serving Level 4 gown contracts.
Germany
Baden-Württemberg textile engineering clusters develop specialized SMS composite structures balancing viral barrier properties with moisture vapor transmission. The EU Medical Device Regulation (MDR) imposes stricter conformity assessment procedures for surgical gown suppliers accessing European hospital networks. Freudenberg Performance Materials anchors composite R&D in Weinheim, driving regional innovation in breathable barrier architectures.
China
Yangtze River Delta manufacturing bases scale spunbond-meltblown capacity to serve domestic hospital procurement and export markets. The National Medical Products Administration (NMPA) aligns barrier fabric standards with international AAMI PB70 classifications. Zhejiang Province hosts concentrated nonwoven production zones supplying both standard and premium gown grades.
Japan
Kanto region medical device manufacturers source high-grade meltblown fibers for domestic surgical gown production. The Ministry of Economy, Trade and Industry (METI) promotes advanced material innovation through its healthcare technology initiatives. Osaka-based textile engineering centers refine SMS laminates for precision surgical applications requiring validated sterilization protocols.
India
Gujarat chemical processing hubs supply polypropylene feedstock to emerging nonwoven fabric producers targeting cost-sensitive hospital segments. The Bureau of Indian Standards (BIS) develops domestic barrier fabric specifications aligned with international liquid barrier benchmarks. Maharashtra's pharmaceutical manufacturing corridors drive ancillary demand for procedure-grade breathable gowns in clinical research settings.
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized composite niches and direct-to-facility distribution channels. The vendor base organizes around three archetypes: diversified healthcare conglomerates with deep GPO relationships, specialized nonwoven material engineers with proprietary SMS architectures, and regional fabricators competing on feedstock proximity and turnaround speed. Consolidation pressure from hospital procurement alliances favors scale players with validated sterilization protocols, while sustainability mandates create openings for reformulators of water-repellent chemistries.
Among diversified healthcare suppliers, Cardinal Health and Medline Industries exemplify archetypes with established distribution infrastructure and integrated delivery network relationships. Berry Global represents the material science-focused tier with substantial nonwoven manufacturing scale. Ahlstrom and Freudenberg Performance Materials occupy positions as European-based composite specialists serving premium barrier fabric segments with technical differentiation strategies.
| Leading Market Players |
|---|
| Berry Global |
| Ahlstrom |
| Freudenberg Performance Materials |
| Avgol |
| Mitsui Chemicals Asahi Life Materials |
| Fitesa |
| Mogul |
| Medline Industries |
| Cardinal Health |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement alliance consolidation across United States integrated delivery networks is compressing vendor counts and elevating AAMI PB70 certification requirements, forcing supply response toward validated meltblown capacity and pressuring margin structures for non-compliant producers.
Pricing Analysis
Warranty and sterilization validation bundling separates premium-tier suppliers from unbundled commodity competitors in contract negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects AAMI certification grade and FDA 510(k) clearance status as primary differentiation drivers. Pricing pressure stems from group purchasing organization volume aggregation favoring certified incumbents. Ambulatory surgical centers exhibit highest price sensitivity due to direct manufacturer procurement mandates, while Level 4 gown contracts for open-heart procedures show lowest elasticity.
Supply Chain Analysis
Domestic-content requirements in United States federal healthcare procurement are reshaping sourcing patterns toward North American meltblown capacity. Polypropylene resin feedstock concentrates in United States Gulf Coast petrochemical corridors, with Germany and China anchoring specialized SMS composite manufacturing. Supply chains draw from propylene monomer, spunbond extrusion equipment, and gamma sterilization infrastructure as critical inputs. Single-source vulnerability runs through European meltblown specialists serving premium gown grades. Distribution runs through group purchasing organization contracts to integrated delivery networks, bypassing traditional medical supply distributors in fastest-growing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Meltblown microfiber capacity scarcity props pricing power for validated suppliers as FDA 510(k) clearance timelines freeze expansion for unqualified entrants.
For Market Incumbents: Acquire sterilization validation assets to compress eighteen-month certification cycles for new composite structures. Backward integration into polypropylene resin supply secures margin stability against petrochemical volatility. Spunlace technology substitution in isolation gown segments threatens SMS dominance, requiring R&D investment in hydroentangled barrier architectures. Channel control through direct IDN relationships defends position against distributor disintermediation. For New Entrants and Emerging Players: Begin with California and New York state sustainability procurement mandates as entry points for recyclable barrier fabric formulations. Isolation gown applications in ambulatory surgical centers represent most penetrable segment due to lower AAMI certification thresholds. Direct-to-facility distribution bypassing GPO intermediaries captures margin from price-sensitive outpatient settings. EPA PFAS scrutiny creates white-space for fluorine-free water repellent chemistry specialists. For Investors and Strategic Acquirers: The window for entry favors specialized composite engineers with proprietary SMS architectures over diversified healthcare conglomerates. Long-term viability hinges on sterilization protocol validation and state-level chemical compliance capabilities. Acquisition targets should demonstrate captive meltblown capacity or validated gamma/ethylene oxide sterilization partnerships. Watch for FDA guidance updates on liquid barrier performance as inflection signal for certification investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Investment | Validates meltblown fiber specifications for Level 4 gown contracts in United States hospital systems. |
| Spunlace Technology Development | Captures isolation gown volume where softer drape characteristics influence clinician preference. |
| PFAS-Free Chemistry Reformulation | Aligns premium gown grades with EPA scrutiny and California chemical disclosure mandates. |
| Direct IDN Distribution Channel | Bypasses GPO intermediaries to capture margin from consolidated United States hospital procurement. |
| Backward Resin Integration | Secures polypropylene feedstock stability against Gulf Coast petrochemical price volatility. |
Research Methodology
Document review covered FDA 510(k) filings, AAMI PB70 test reports, and hospital GPO contract databases, complemented by interviews with meltblown fiber production managers, biomedical engineers at integrated delivery networks, GPO contracts managers, and regulatory affairs specialists at surgical gown manufacturers. Secondary validation drew from EPA chemical disclosure records, state procurement mandate repositories, and customs trade data for polypropylene resin flows. Bottom-up capacity modeling triangulated against top-down hospital spending aggregation.
Segment-level outputs across fiber type, fabric technology, and end-user categories were generated through projection horizon modeling. Analytical framework incorporated AAMI barrier level tiering, sterilization protocol compatibility, and state-level sustainability mandate adoption curves as industry-specific inputs. CAGRs were derived from volume-weighted capacity expansion trajectories and procurement alliance consolidation patterns.
Underlying measurement precision varies by segment; disposable surgical gown and SMS technology categories carry tighter precision than emerging spunlace alternatives. Forecasts reflect assumptions about FDA review timeline stability, resin price volatility, and state mandate proliferation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
Nonwoven Flanging Market