
 United States Non-Woven Fabric Market | 2026-2036
United States Non-Woven Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
United States Non-Woven Fabric Market Analytics
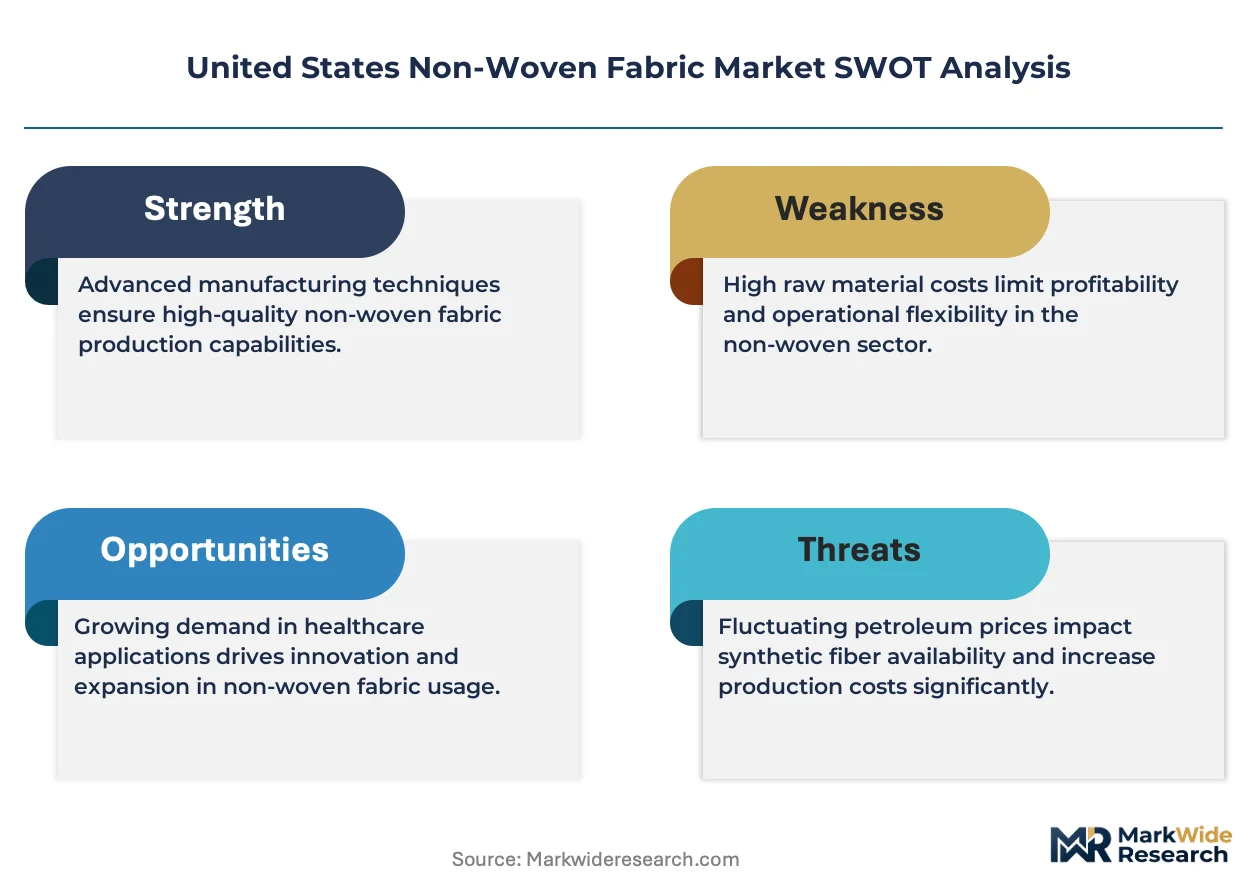
A capital-intensity divergence between integrated resin-to-roll producers and commodity converters is redrawing competitive boundaries in the United States non-woven fabric industry. Berry Global Inc. leverages backward integration into polypropylene resin to control input costs across its spunbond operations. Kimberly-Clark Corporation anchors its position through captive demand from hygiene and medical end-uses. Freudenberg Performance Materials differentiates via technical non-wovens for filtration and automotive applications.
Non-woven fabric consists of sheet or web structures bonded together by entangling fiber or filaments mechanically, thermally, or chemically, typically achieving basis weights between 10 and 400 grams per square meter; these engineered materials serve as barriers, filters, absorbents, and reinforcements across healthcare, construction, and consumer sectors. Spunbond and meltblown technologies dominate volume production due to their scalability in hygiene and medical applications, while hydroentangled fabrics command premium positioning in wipes and cosmetic substrates where softness and drape matter. Polypropylene retains cost leadership across most end-uses, though polyester gains traction in geotextiles and durable industrial applications requiring UV stability.
The EPA oversees emissions and chemical safety in non-woven manufacturing facilities, while OSHA sets workplace exposure limits for respirable fibers and thermal bonding byproducts; FDA regulations govern medical-grade non-wovens used in surgical drapes, gowns, and sterilization wraps, creating compliance moats around validated suppliers. The Federal Trade Commission's Green Guides constrain environmental marketing claims, pressuring producers to substantiate biodegradability assertions. Stakeholders must monitor evolving state-level extended producer responsibility legislation and its potential to reshape material recovery economics.
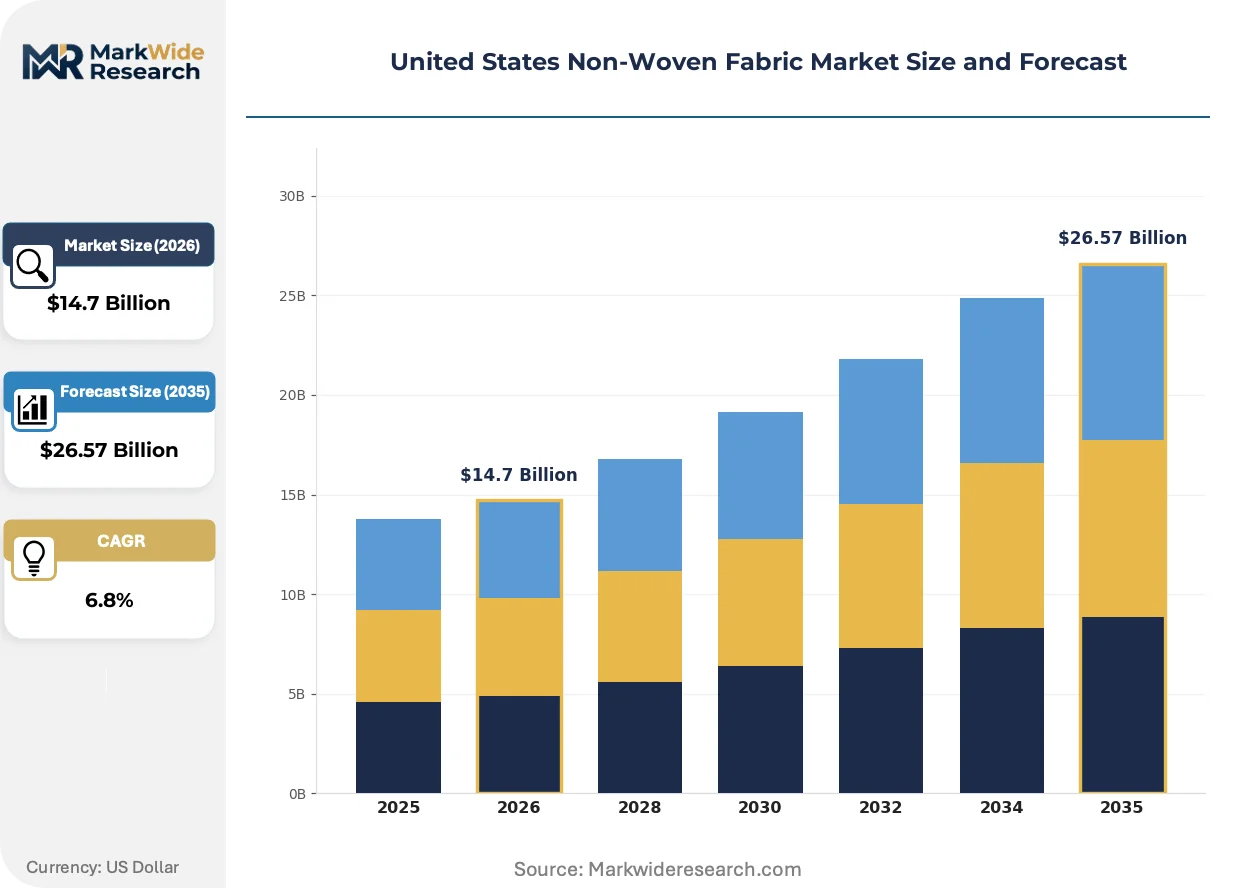
Market Dynamics
Capital redeployment toward bio-based polymer R&D is compressing traditional polypropylene reliance as EPA microfiber filtration standards harden and medical sterilization demand concentrates in the southeastern manufacturing corridor.
Growth Catalysts
- Spunbond-meltblown hybrid lines:Medical device manufacturers are expanding sterilization wrap and surgical gown programs, pulling capacity additions toward FDA-validated supply chains.
- Georgia-South Carolina-North Carolina corridor:Demand concentrates in this southeastern manufacturing belt where resin access, logistics infrastructure, and non-woven conversion expertise overlap.
- EPA single-use plastics framework:The agency's evolving rules on microfiber filtration are redirecting capital toward bio-based polymer research and next-generation filtration substrates.
Market Restraints
- Propylene feedstock volatility:Integrated resin-to-roll producers control input costs through backward integration, leaving commodity converters exposed to spot resin swings.
- Polypropylene lock-in:Polyester gains traction in geotextiles and durable industrial applications, but polypropylene retains cost leadership across hygiene and medical end-uses, slowing material substitution.
- OSHA respirable fiber limits:Thermal bonding byproducts trigger workplace exposure compliance costs and line retrofit requirements for older meltblown facilities.
Strategic Opportunities
- Hydroentangled cosmetic substrates:Wipes and personal care applications where softness and drape command premium positioning remain underpenetrated by domestic spunbond specialists.
- State-level extended producer responsibility:Emerging legislation in California and New York creates first-mover advantages for producers with validated material recovery economics and biodegradability substantiation.
- Geotextile UV stability demand:Polyester non-wovens with enhanced UV resistance are displacing traditional woven alternatives in infrastructure and civil engineering applications across Texas and Florida.
Industry Challenges
- FDA 510(k) sterilization wrap validation:Medical-grade non-woven certification timelines stretch 18-24 months, freezing out new entrants from surgical drape and gown supply chains.
- Thermal bonding line retrofit capex:OSHA compliance for respirable fiber exposure requires six-figure capital outlays per production line, pressuring mid-tier converters with aged asset bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Non-Woven Fabric Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond, Meltblown, Needlepunched, Hydroentangled End Use: Medical, Hygiene, Geotextiles, Automotive Material: Polypropylene, Polyethylene, Rayon, Polyester Technology: Thermal Bonding, Chemical Bonding, Mechanical Bonding, Airlaid |
| Companies Covered | Berry Global Inc., Kimberly-Clark Corporation, Freudenberg Performance Materials, Ahlstrom, First Quality Enterprises, Inc., Johns Manville, Glatfelter, DuPont, 3M Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Non-Woven Fabric Market Evolving Landscape
Process intensification and regulatory compliance automation are reshaping competitive economics, while demand-side specification tightening separates validated suppliers from commodity producers.
Bicomponent sheath-core fibers are fragmenting monomaterial spunbond economics in hygiene applications. Diaper and feminine hygiene manufacturers are adopting these structures for enhanced fluid management and surface softness. The technology is fragmenting volume concentration among legacy polypropylene specialists by enabling regional converters to compete on performance tiers previously reserved for integrated producers.
EPA Green Guides enforcement is constraining environmental marketing claims across the non-woven sector. The FTC's substantiation requirements for biodegradability assertions are forcing producers to invest in third-party certification and lifecycle documentation. Medical and consumer wipes segments face the steepest compliance costs as brand owners demand defensible sustainability credentials for private-label positioning.
Hospital procurement consolidation is compressing supplier rosters for surgical drapes and sterilization wraps. Integrated delivery networks in Texas and Ohio are centralizing non-woven purchasing through sole-source agreements with FDA-validated producers. This concentration is visible most acutely in the Midwest, where health system mergers have halved active vendor counts for infection prevention products since 2022.
United States Non-Woven Fabric Market Segmentation
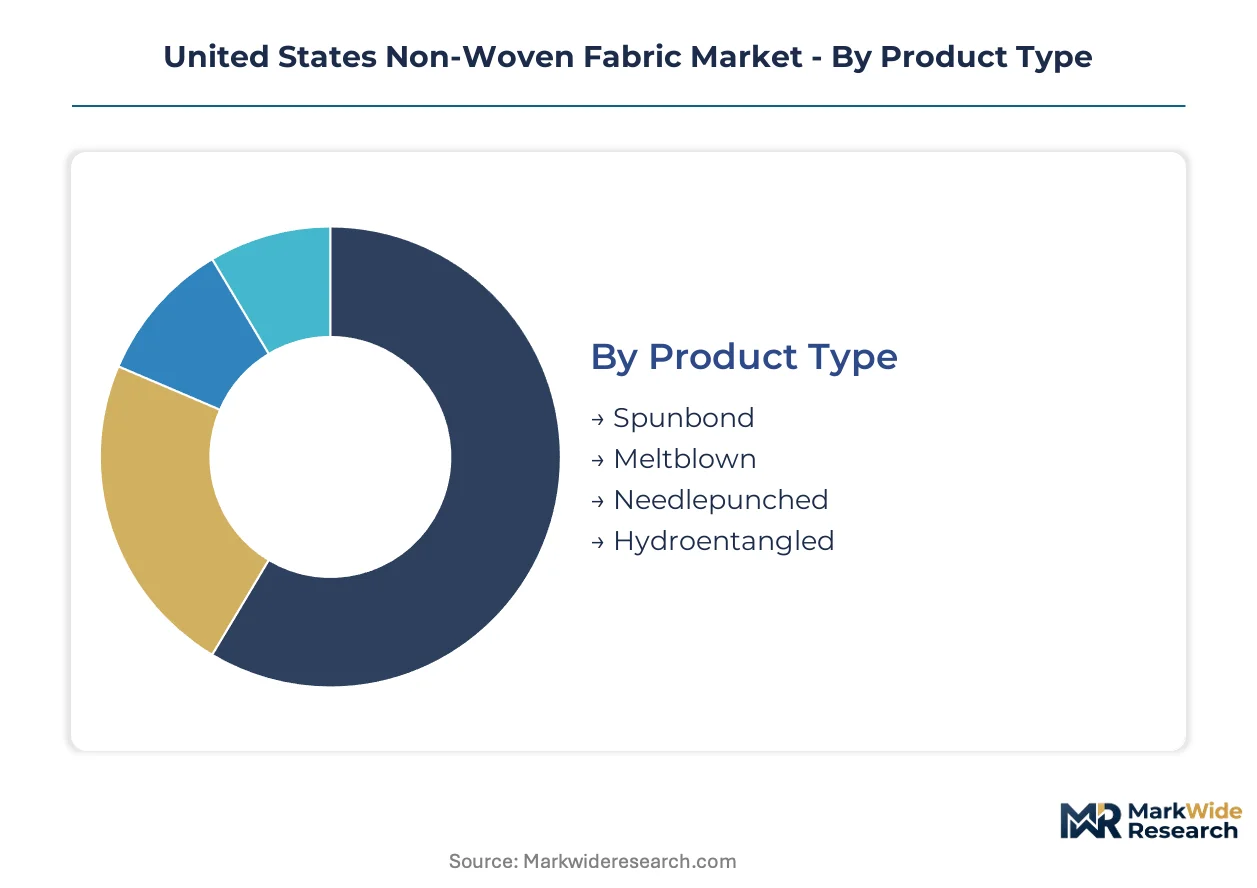
Segmentation in the United States non-woven fabric market reveals where substitution pressures and regulatory compliance intersect to reshape supplier economics. Distinct technology and material combinations face divergent paths as EPA microfiber rules and FDA sterilization standards harden.
Product Type:
Spunbond and meltblown face the most acute substitution threat from hydroentangled alternatives in premium wipes and cosmetic applications where surface softness commands price premiums.
- Spunbond:Continuous filaments extruded and bonded thermally deliver tensile strength at 10-150 gsm basis weights. Demand concentrates in Georgia and South Carolina surgical gown programs where FDA 510(k) validation creates supply moats around integrated producers.
- Meltblown:Microfiber webs with sub-micron filtration capability serve sterilization wrap and N95 respirator applications. North Carolina medical device corridors anchor capacity additions as hospital procurement consolidation favors validated regional suppliers.
- Needlepunched:Mechanical entanglement of staple fibers produces durable geotextile and automotive carpet substrates without thermal bonding emissions.
- Hydroentangled:High-pressure water jets bond cellulose and synthetic blends for premium wet wipes and cosmetic pads in California personal care manufacturing.
Spunbond anchors the volume base while hydroentangled gains share at the steepest rate.
End Use:
Cost tier stratification separates commodity hygiene from premium medical applications where validation timelines and sterilization performance justify supplier premiums.
- Medical:Surgical drapes, gowns, and sterilization wraps require FDA-validated barrier properties against blood and viral penetration. Texas and Ohio integrated delivery networks have halved vendor counts through sole-source agreements since 2022.
- Hygiene:Diaper and feminine hygiene manufacturers in the Southeast adopt bicomponent sheath-core fibers for fluid management. The segment fragments volume concentration by enabling regional converters to compete on performance tiers.
- Geotextiles:Infrastructure applications across Texas and Florida favor polyester non-wovens with enhanced UV stability over traditional woven alternatives.
- Automotive:Interior trim and filtration substrates from Freudenberg Performance Materials supply Detroit-area assembly plants with technical non-woven specifications.
Hygiene commands the widest volume footprint while medical delivers the highest margin per square meter.
Material:
Supply concentration in Gulf Coast propylene production locks in polypropylene cost leadership despite bio-based polymer R&D acceleration.
- Polypropylene:Dominant resin for spunbond and meltblown with lowest unit cost across hygiene and medical end-uses. Berry Global's backward integration into resin production controls input volatility across southeastern manufacturing.
- Polyethylene:Lower melting point suits thermal bonding applications in disposable protective apparel with reduced energy processing requirements.
- Rayon:Cellulosic fibers from domestic pulp sources serve biodegradable wipe substrates facing FTC Green Guides substantiation requirements.
- Polyester:UV-stable grades displace woven geotextiles in Florida civil engineering and gain traction where durability exceeds polypropylene limits.
Polypropylene retains the dominant share position while polyester climbs the fastest in infrastructure applications.
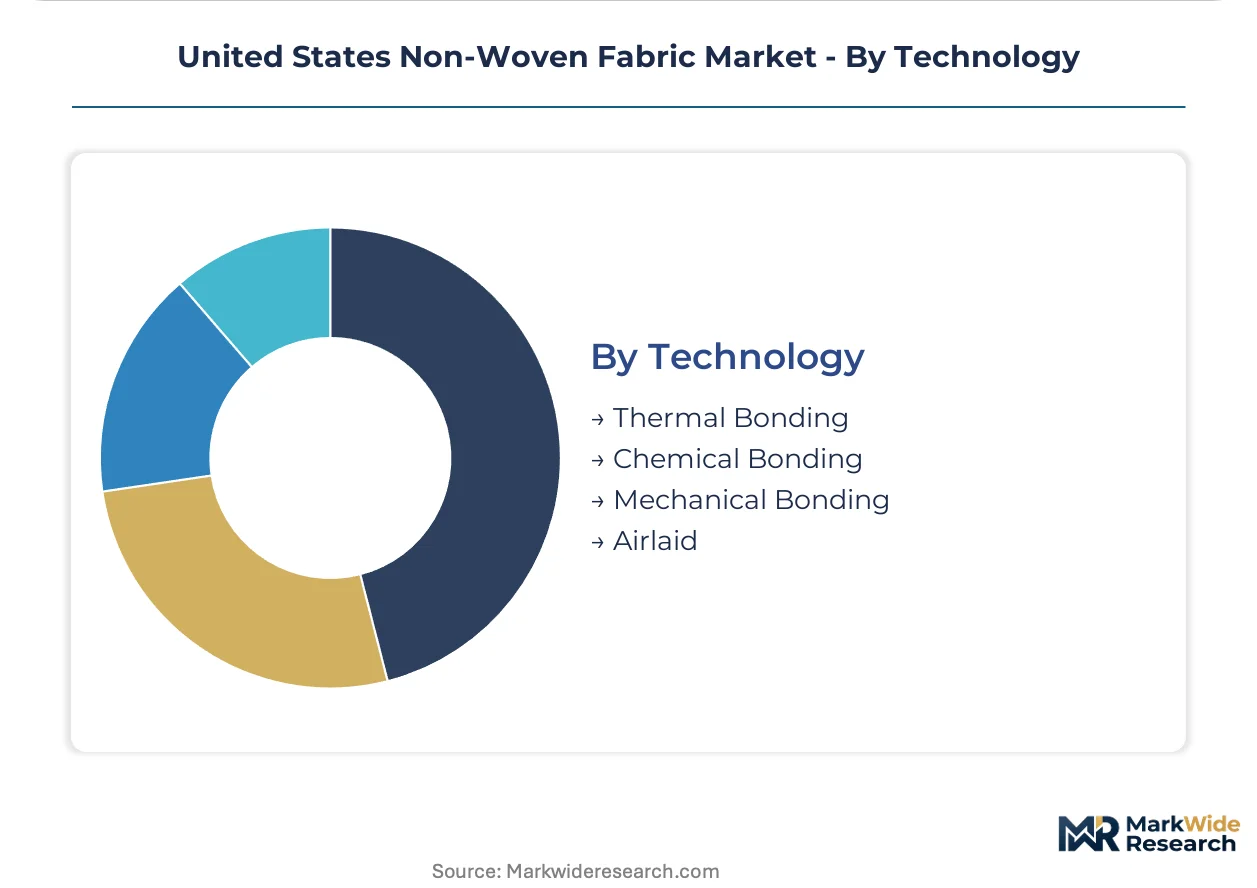
Technology:
OSHA respirable fiber exposure limits are forcing capital redeployment away from legacy thermal bonding toward mechanical and airlaid alternatives.
- Thermal Bonding:Calendered heat fusion of thermoplastic fibers faces six-figure line retrofit costs for OSHA compliance at aged meltblown facilities.
- Chemical Bonding:Latex and acrylic binders enable high-loft structures in furniture and bedding applications with reduced workplace fiber exposure.
- Mechanical Bonding:Needlepunch and hydroentanglement avoid thermal byproducts entirely, attracting capital as EPA and OSHA standards tighten.
- Airlaid:Air-formed pulp and superabsorbent polymer composites serve incontinence and food pad applications with distinct absorbency profiles.
Thermal bonding holds the largest installed base while hydroentanglement expands most quickly in premium personal care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States non-woven fabric market runs a modest trade surplus in medical-grade sterilization wraps and surgical gowns, though commodity spunbond for hygiene applications faces import pressure from Southeast Asian converters. Export strength concentrates in FDA-validated supply chains serving Canadian and Mexican health systems under USMCA provisions.
Southeast (Georgia-South Carolina-North Carolina)
Medical device corridors in this belt anchor domestic meltblown capacity for N95 respirators and sterilization wraps. FDA 510(k) validation requirements lock in regional supplier relationships with hospital procurement networks. Berry Global's backward-integrated resin operations in Georgia control input costs across spunbond surgical gown programs.
Texas
Infrastructure investment and oilfield services drive geotextile consumption for erosion control and secondary containment. The Texas Department of Transportation specifications favor polyester non-wovens with enhanced UV stability over traditional woven alternatives. Dallas-Fort Worth integrated delivery networks have consolidated surgical drape purchasing through sole-source agreements since 2022.
California
Personal care manufacturing clusters in Los Angeles and Orange Counties pull hydroentangled substrates for premium wet wipes and cosmetic pads. The state's extended producer responsibility legislation creates compliance moats around producers with validated biodegradability substantiation. FTC Green Guides enforcement pressures brand owners to demand third-party certification from domestic suppliers.
Midwest (Ohio-Michigan-Illinois)
Automotive assembly plants in Detroit and Chicago source technical non-wovens for interior trim and cabin filtration. Hospital system mergers across Ohio and Michigan have halved active vendor counts for infection prevention products. OSHA respirable fiber exposure limits trigger six-figure retrofit costs at aged thermal bonding facilities in the region.
Florida
Civil engineering applications across coastal counties favor UV-stable polyester non-wovens for shoreline protection and drainage systems. The Florida Department of Environmental Protection specifications accelerate displacement of woven geotextiles in infrastructure projects. Tampa and Miami logistics hubs distribute medical-grade materials throughout the Caribbean and Latin American markets.
United States Non-Woven Fabric Market Competitive Landscape
Concentration sits with integrated resin-to-roll producers who control polypropylene input costs across southeastern manufacturing corridors. Mid-tier commodity converters without backward integration face margin compression from spot resin volatility and OSHA compliance retrofit requirements. Three archetypes dominate: integrated petrochemical-to-fabric producers, hygiene-specialized converters with captive end-use demand, and technical non-woven specialists serving filtration and automotive specifications. Competitive dynamics center on FDA validation timelines for medical-grade supply chains and capital redeployment toward bio-based polymer R&D.
Within the integrated producer tier, Berry Global Inc. anchors capacity across Georgia and the Carolinas with captive resin supply. Kimberly-Clark Corporation exemplifies the hygiene-specialized archetype through end-use integration into diaper and feminine care markets. Freudenberg Performance Materials occupies the technical specialist position for filtration and automotive applications supplying Detroit-area assembly plants.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Kimberly-Clark Corporation |
| Freudenberg Performance Materials |
| Ahlstrom |
| First Quality Enterprises, Inc. |
| Johns Manville |
| Glatfelter |
| DuPont |
| 3M Co. |
| Others |
Value Network & Pricing Analysis
FDA 510(k) sterilization wrap validation gates both supply qualification and price differentiation simultaneously, creating tiered supplier economics where validated producers command premiums while commodity converters compete on resin pass-through costs. This certification moat concentrates pricing power among southeastern integrated producers with captive polypropylene supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the United States non-woven fabric market. Price differentiation stems from FDA certification tier and volume scale, with hospital procurement consolidation intensifying cost compression in commodity hygiene grades. Margins are tightening due to propylene feedstock volatility, leaving regional converters most price-sensitive while integrated resin-to-roll producers maintain pricing flexibility through backward integration.
Supply Chain Analysis
Strategic stockpiling of polypropylene resin dominates inventory strategy among southeastern spunbond producers facing Gulf Coast propylene supply concentration. Raw material flows draw from Texas and Louisiana petrochemical corridors, with mechanical bonding equipment and meltblown dies sourced from Germany and Japan. Tariff exposure on European thermal bonding machinery creates supply chain risk. Distribution runs through Atlanta and Charlotte logistics hubs serving medical device corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States non-woven fabric market is entering a cyclical recovery phase as hospital capital expenditure cycles normalize and infrastructure stimulus accelerates geotextile consumption across Texas and Florida.
For Market Incumbents: Secure FDA-validated sterilization wrap supply agreements with consolidating integrated delivery networks in Texas and Ohio before 510(k) timelines freeze out competitors. Deepen backward integration into bio-based polymer R&D to preempt EPA microfiber filtration standards. Channel control through sole-source hospital contracts remains the critical defensive lever against regional converter fragmentation. For New Entrants and Emerging Players: Post-consumer wipe collection and recycling infrastructure represents a service-layer gap where incumbents under-serve California's extended producer responsibility compliance demands. Hydroentangled cosmetic substrates for Los Angeles personal care manufacturing offer the most penetrable white space. A go-to-market angle anchored on third-party biodegradability certification bypasses spunbond capital barriers. For Investors and Strategic Acquirers: EPA's evolving single-use plastics framework reshapes the acquisition landscape toward producers with validated material recovery economics. Long-term viability over the next decade hinges on bio-based polymer transition readiness rather than commodity scale. Target mid-tier converters with aged thermal bonding assets facing OSHA retrofit costs as distressed acquisition candidates. The signal to watch is state-level extended producer responsibility legislation crossing implementation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin | EPA microfiber rules redirect capital toward polymer R&D with biodegradability substantiation. |
| FDA 510(k) Validation Investment | Hospital procurement consolidation favors validated suppliers with 18-24 month certification moats. |
| Hydroentanglement Capacity Addition | California personal care clusters pull premium substrates where softness commands price premiums. |
| OSHA Compliance Retrofit Program | Thermal bonding line upgrades address respirable fiber exposure at aged meltblown facilities. |
| State EPR Partnership Development | California and New York legislation creates first-mover advantages for material recovery economics. |
Research Methodology
A spread of perspectives from plant managers at southeastern spunbond facilities, procurement leads at medical device OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EPA regulatory dockets, SEC 10-K disclosures, and customs trade data established baseline supply and demand parameters. Bottom-up capacity assessments and top-down end-use consumption estimates were triangulated to cross-verify volume assumptions.
Segmentation dimensions modeled span product technology, end-use application, material resin type, and bonding process across the projection horizon. CAGRs were derived from production capacity expansion timelines, hospital procurement contract durations, and infrastructure spending patterns. Industry-specific forecast inputs include propylene feedstock price trajectories and OSHA compliance implementation schedules.
Underlying assumptions cover resin price stability, FDA validation timeline continuity, and state EPR legislative progression, with deviation risk concentrated in feedstock volatility and regulatory acceleration. Revision becomes warranted when EPA microfiber filtration standards or OSHA exposure limits cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market