
 Global Nonwoven Materials and Products Market | 2026-2036
Global Nonwoven Materials and Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nonwoven Materials and Products Market Analysis
Modular hygiene kit configurations is decoupling bulk roll purchasing from finished goods sourcing across hospital supply chains. Kimberly-Clark Corporation leverages its captive meltblown capacity to secure input cost stability for surgical apparel lines. Freudenberg Group anchors European filtration demand through backward integration into needlepunch and spunlace platforms. Berry Global Inc. dominates North American geotextile rolls by controlling extrusion-to-fabrication throughput across multiple resin grades.
Nonwoven materials and products comprise engineered sheet or web structures bonded by mechanical, thermal, or chemical means rather than weaving or knitting, with basis weights typically spanning 10 to 250 grams per square meter depending on end-use load requirements. These materials function as barriers, absorbents, filters, or reinforcements across applications demanding disposability, breathability, or controlled permeability. Polypropylene dominates material volume due to its processability in spunbond and meltblown systems, though biodegradable fibers are gaining formulation share where compostability mandates apply. Filtration applications command premium positioning because regulatory certification cycles create sticky supplier relationships and limit substitution. Medical supplies within hygiene applications sustain volume leadership through institutional procurement contracts, while geotextiles in construction generate project-based revenue with higher margin volatility.
FDA biocompatibility standards for patient-contact nonwovens shape product development timelines and testing budgets for US market entrants. REACH chemical restrictions and the EU Medical Device Regulation impose substance disclosure and clinical evaluation burdens that favor large manufacturers with dedicated regulatory affairs teams. China's GB standards and NMPA oversight for medical-grade materials require in-country testing partnerships that complicate direct export strategies. Stakeholders must monitor evolving extended producer responsibility frameworks for single-use nonwovens, as polymer traceability and end-of-life collection obligations will reshape cost structures and regional sourcing decisions.
Market Dynamics
Spunbond and meltblown capacity concentration in China's Yangtze River Delta is compressing input costs for hygiene and filtration converters while forcing European and North American producers to defend position through specialty certification and regional supply chain proximity.
Growth Catalysts
- EU Medical Device Regulation biocompatibility mandates:Tighter testing protocols for patient-facing materials are locking in supplier relationships with certified manufacturers and extending contract durations across German and French hospital procurement.
- Single-use surgical drape demand in Japan:Healthcare system expansion is accelerating procurement of disposable barrier fabrics for operating theater standardization.
- Spunlace platform adoption in premium wipes:Hydroentanglement technology is displacing airlaid and carded thermal-bond alternatives in North American consumer hygiene applications demanding softness and flushability.
Market Restraints
- Propylene monomer price volatility:Feedstock cost swings tied to naphtha-cracker margins in Northeast Asia are compressing spunbond converter margins and destabilizing contract pricing.
- NMPA testing partnership requirements:China's in-country certification mandates for medical-grade nonwovens create structural barriers to direct export without local joint venture or licensing arrangements.
- Reusable textile substitution in industrial filtration:Cleanable membrane and woven cartridge systems are capturing share in heavy-duty liquid filtration where lifecycle cost analysis favors durability over disposability.
Strategic Opportunities
- Compostability mandates in France and Italy:Extended producer responsibility frameworks for single-use hygiene products are creating certified biodegradable fiber demand that commands 15-30% price premiums.
- Geotextile specification in Indian infrastructure:National highway and railway expansion projects are specifying needlepunch stabilization fabrics where local capacity remains underdeveloped relative to demand scale.
- Needlepunch-spunlace hybrid platforms:Convergence of mechanical and hydroentanglement bonding is enabling single-line flexibility across automotive interior, filtration, and construction applications.
Industry Challenges
- Meltblown microfiber electrostatic charging expertise:Qualified process engineers capable of optimizing charge retention for N95-equivalent filtration media command scarcity premiums and constrain capacity ramp speed.
- FDA 510(k) pathway timelines:Biocompatibility documentation and clinical evaluation cycles for novel surgical barrier materials extend product launch windows by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nonwoven Materials and Products Market |
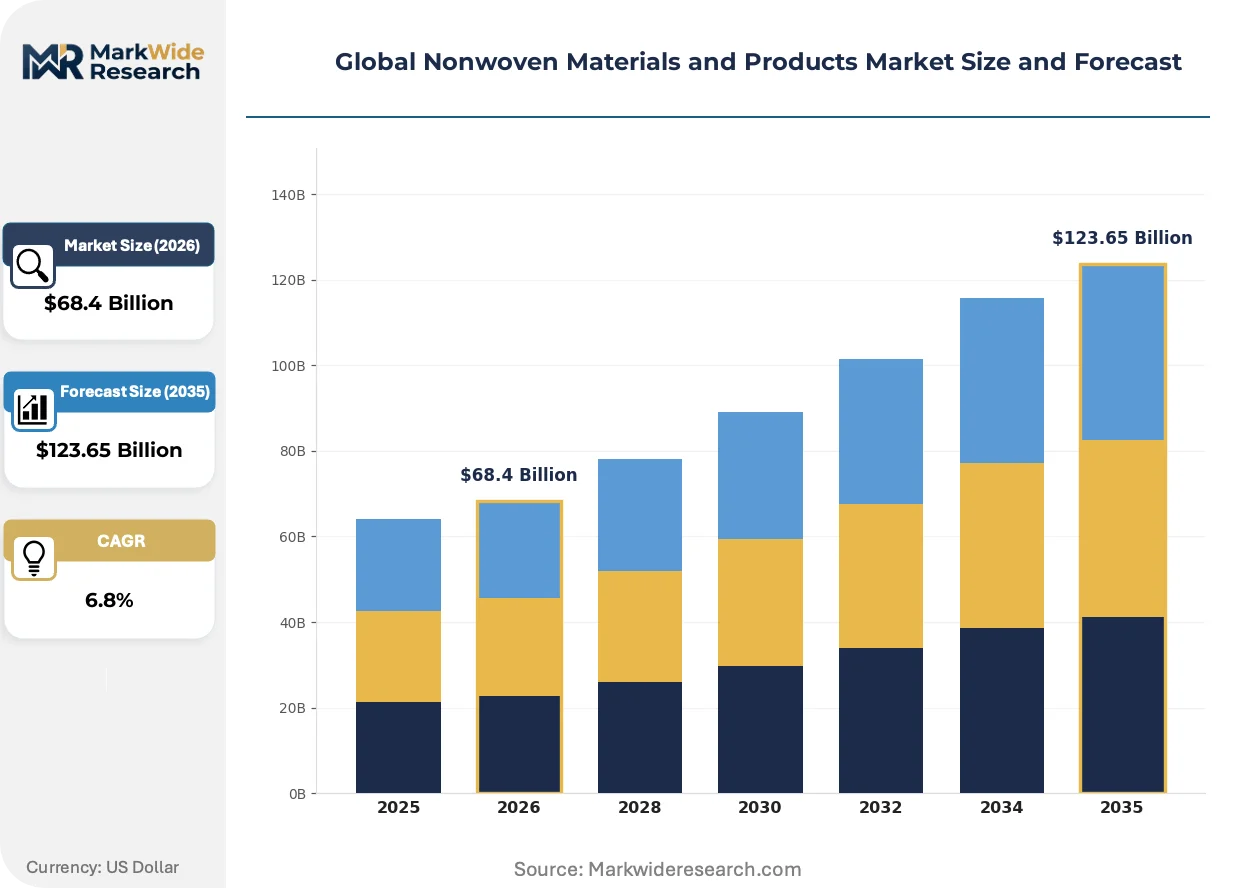
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Medical Supplies, Geotextiles, Filters End User: Healthcare, Automotive, Construction, Consumer Goods Material: Polypropylene, Polyester, Rayon, Biodegradable Fibers Application: Filtration, Hygiene, Packaging, Home Textiles |
| Companies Covered | Berry Global Inc., Freudenberg Group, DuPont Inc., Kimberly-Clark Corporation, Ahlstrom, Fitesa S.A., Toray Industries, Inc., Johns Manville, First Quality Enterprises, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nonwoven Materials and Products Market Emerging Trajectories
Bicomponent fiber technology, regulatory substance restrictions, and hospital supply chain restructuring are converging to reshape competitive positioning across material grades and geographic markets.
Bicomponent sheath-core spunbond is integrating polypropylene-polyethylene configurations to deliver thermal bonding versatility without sacrificing mechanical strength. Surgical apparel manufacturers in Germany and the United States are qualifying these structures for steam sterilization compatibility. The technology is integrating previously separate spunbond and thermal-bond production steps, compressing capital requirements for mid-scale converters.
REACH chemical restrictions on per- and polyfluoroalkyl substances are eliminating durable water repellent chemistries from hygiene and medical nonwoven specifications. ECHA substance evaluation timelines are forcing reformulation of spunlace wipes and surgical drapes ahead of sunset dates. European converters are responding by accelerating bio-based fluorine-free repellent qualification programs with fiber suppliers.
Modular kit configurations are decoupling bulk roll purchasing from finished goods sourcing across hospital supply chains. Group purchasing organizations in the United States are consolidating vendor panels and demanding consolidated delivery of sterilized surgical packs rather than component rolls. This pattern is most visible in the Southeast and Midwest hospital networks where inventory carrying cost reduction targets exceed 20%.
Global Nonwoven Materials and Products Market Segmentation
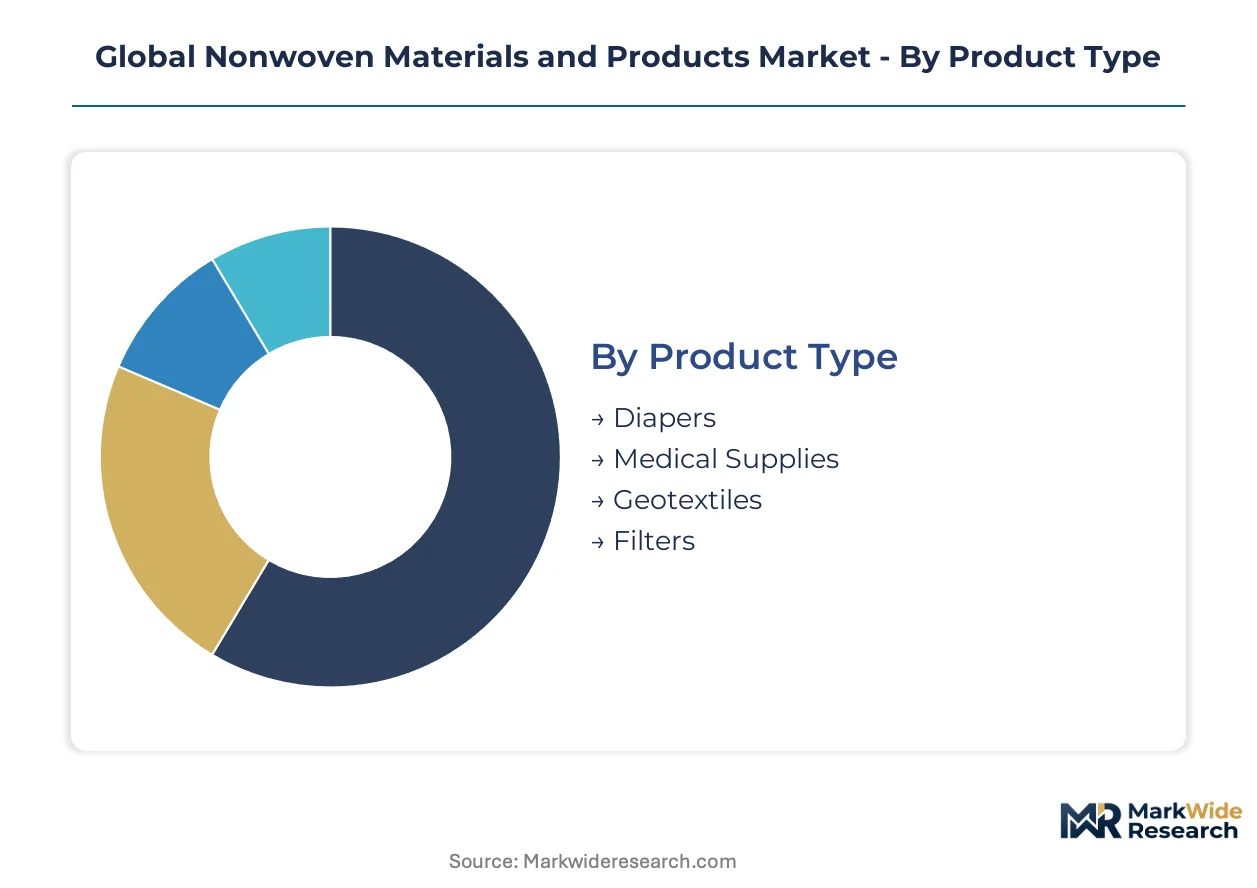
Nonwoven materials exhibit divergent margin profiles and capital requirements across product configurations, forcing converters to prioritize segments where bonding technology and resin specifications align with installed equipment. Material selection and end-use certification requirements create distinct competitive moats that shape strategic positioning.
Product Type:
Capital intensity varies dramatically across product categories, with meltblown filtration media requiring electrostatic charging infrastructure that multiplies upfront investment versus commodity hygiene rolls.
- Diapers:Spunbond-meltblown-spunbond laminates dominate absorbent core acquisition layers and backsheet barriers. China's Yangtze River Delta cluster supplies the bulk of global hygiene substrate volume, though EU compostability mandates are fragmenting specifications between conventional and certified biodegradable variants.
- Medical Supplies:Surgical drapes and gowns demand biocompatibility certification under FDA 510(k) or EU MDR pathways, creating sticky supplier relationships with hospital procurement. German and Japanese healthcare systems are expanding single-use barrier fabric procurement for operating theater standardization.
- Geotextiles:Needlepunch stabilization fabrics serve roadbed and landfill containment applications.
- Filters:N95-equivalent respirator media commands premium positioning through electrostatic charge retention requirements.
Diapers absorb the bulk of installed capacity; medical supplies are expanding most quickly.
End User:
Customer concentration patterns separate institutional procurement with long contract cycles from fragmented consumer demand with rapid specification turnover.
- Healthcare:Group purchasing organizations in the United States are consolidating vendor panels and demanding sterilized surgical pack delivery rather than component rolls. FDA biocompatibility standards and EU MDR substance disclosure requirements favor large manufacturers with dedicated regulatory affairs teams.
- Automotive:Interior trim and acoustic insulation applications favor needlepunch-spunlace hybrid platforms for substrate versatility.
- Construction:Project-based revenue with higher margin volatility characterizes geotextile demand tied to infrastructure spending cycles.
- Consumer Goods:Premium wipes adoption of hydroentanglement technology is displacing airlaid alternatives in North American markets.
Healthcare commands the steepest certification barriers; consumer goods is gaining share fastest.
Material:
Resin selection determines process compatibility and end-of-life compliance burden, with polypropylene's spunbond-meltblown versatility contrasting against biodegradable alternatives' compostability premiums.
- Polypropylene:Dominates material volume through processability in spunbond and meltblown systems. Feedstock cost swings tied to naphtha-cracker margins in Northeast Asia compress converter margins and destabilize contract pricing.
- Polyester:Higher tenacity and thermal stability suit filtration and geotextile load-bearing requirements.
- Rayon:Cellulosic origin delivers absorbency and flushability for premium hygiene applications.
- Biodegradable Fibers:PLA and PBS formulations command price premiums where France and Italy extended producer responsibility frameworks mandate compostability certification.
Polypropylene holds the majority of production assets; biodegradable fibers is climbing the fastest.
Application:
Functional requirements separate barrier and absorbent applications from filtration's regulatory certification intensity.
- Filtration:Regulatory certification cycles create sticky supplier relationships and limit substitution. Meltblown microfiber electrostatic charging expertise constrains capacity ramp speed for N95-equivalent media.
- Hygiene:Institutional procurement contracts sustain volume leadership through medical supplies and diaper demand.
- Packaging:Nonwoven alternatives to woven polypropylene bags serve agricultural and industrial bulk transport.
- Home Textiles:Furniture backing and mattress components utilize staple fiber needlepunch constructions.
Hygiene consumes the greatest output volume; filtration maintains the highest margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of spunbond and meltblown substrates while Germany, Japan, and the United States absorb premium medical and filtration grades. This production-consumption divide shapes trade flows and certification strategies across major economies.
China
Yangtze River Delta mills supply global hygiene converters with polypropylene spunbond and meltblown rolls at compressed input costs. NMPA medical-grade certification mandates require in-country testing partnerships that complicate direct export strategies for foreign suppliers. Zhejiang and Jiangsu provinces host capacity clusters where filtration media output has scaled dramatically since 2020.
Germany
Hospital procurement expansion for single-use surgical drapes and gowns drives demand for biocompatible barrier fabrics. EU Medical Device Regulation substance disclosure requirements favor domestic converters with dedicated regulatory affairs teams. North Rhine-Westphalia anchors European filtration demand through backward integration into needlepunch and spunlace platforms.
United States
Group purchasing organizations consolidate vendor panels and demand sterilized surgical pack delivery rather than component rolls. FDA 510(k) biocompatibility pathways extend product launch windows for novel barrier materials by 18-36 months. Southeast and Midwest hospital networks target 20% inventory carrying cost reductions through modular kit configurations.
Japan
Healthcare system standardization accelerates procurement of disposable surgical drapes and gowns for operating theater hygiene protocols. METI industrial policy supports domestic meltblown capacity for strategic filtration autonomy. Osaka and Nagoya manufacturing clusters specialize in high-tenacity spunbond for automotive acoustic insulation applications.
India
National highway and railway expansion projects specify needlepunch geotextile stabilization fabrics where local capacity remains underdeveloped. BIS certification requirements for construction-grade materials create compliance barriers for imported rolls. Gujarat and Maharashtra industrial corridors attract investment in spunlace platforms for premium hygiene wipe production.
Global Nonwoven Materials and Products Market Vendor Landscape
The competitive structure tilts toward vertically integrated resin-to-fabric converters with captive meltblown capacity. Tier-one players combine regulatory certification depth with multi-continent production footprints, while mid-scale specialists occupy niche bonding technology segments. Strategic archetypes separate hygiene volume leaders, filtration certification holders, and geotextile project contractors. Dominant competitive moves include backward integration into resin extrusion and geographic licensing arrangements to bypass NMPA and FDA testing barriers.
Among North American fabricators, Berry Global Inc. and Kimberly-Clark Corporation occupy positions within the integrated converter archetype, with the latter leveraging captive meltblown supply for surgical apparel cost stability. Freudenberg Group represents the European filtration-focused tier, anchoring regional demand through in-house needlepunch and spunlace capacity. Toray Industries, Inc. exemplifies the Asia-Pacific diversified materials conglomerate model, spanning industrial filament and medical-grade nonwoven segments.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Freudenberg Group |
| DuPont Inc. |
| Kimberly-Clark Corporation |
| Ahlstrom |
| Fitesa S.A. |
| Toray Industries, Inc. |
| Johns Manville |
| First Quality Enterprises, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up hygiene converters in North America and Europe are consolidating purchasing power across spunbond and meltblown roll contracts, compressing supplier margins while reinforcing volume-based pricing discipline through multi-year offtake commitments. This ownership concentration amplifies procurement leverage against Yangtze River Delta producers and shapes regional sourcing arbitrage decisions.
Pricing Analysis
Margin tightening in commodity hygiene substrates reflects propylene monomer volatility tied to Northeast Asian naphtha-cracker economics. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-certified surgical barrier fabrics from uncertified industrial grades. Price differentiation hinges on biocompatibility certification tier and captive meltblown integration depth. Healthcare procurement through US group purchasing organizations exhibits lowest price sensitivity due to sterilized pack bundling, while construction geotextile buyers demonstrate highest elasticity to resin cost swings.
Supply Chain Analysis
Skilled process engineers for electrostatic charging infrastructure remain scarce in Zhejiang and Jiangsu provinces despite capacity expansion. Raw material flows draw from Saudi Arabian and South Korean propylene supply, US specialty resin additives, and German precision charging equipment. Single-source vulnerability concentrates in meltblown microfiber expertise for N95-equivalent filtration media. Distribution runs through converter networks in Germany, Japan, and the United States for medical-grade finished goods, with direct mill relationships dominating bulk hygiene roll procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Meltblown electrostatic charging expertise constrains filtration media capacity expansion, propping premium pricing for certified suppliers across the analysis window.
For Market Incumbents: Acquire captive resin extrusion assets to insulate surgical apparel margins from propylene monomer swings. Secure FDA 510(k) and EU MDR certification depth ahead of biocompatibility mandate tightening. Expand spunlace platform flexibility in North Rhine-Westphalia to offset Yangtze River Delta cost compression through regional proximity and specialty qualification. For New Entrants and Emerging Players: Direct-to-converter digital procurement platforms offer low-friction entry for certified biodegradable fiber supply to French and Italian hygiene manufacturers. Target underdeveloped needlepunch geotextile capacity in Gujarat and Maharashtra industrial corridors for Indian infrastructure project capture. Qualify compostability certification early to command price premiums under extended producer responsibility frameworks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European filtration specialists with EU MDR regulatory dossiers and backward integration into needlepunch or spunlace platforms. Five-to-ten year viability rests on certification moat durability and resin cost pass-through mechanics. Watch NMPA testing partnership formation rates as inflection signal for China market access feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Extrusion | Kimberly-Clark's captive polypropylene supply stabilizes input costs for surgical apparel against naphtha-cracker volatility. |
| EU MDR Certification Investment | Freudenberg's regulatory dossier depth locks in German hospital procurement for biocompatible barrier fabrics. |
| Needlepunch-Spunlace Hybrid Platform Deployment | Toray's mechanical-hydroentanglement convergence enables single-line flexibility across automotive and filtration applications. |
| Compostability Certification Program | Biodegradable fiber qualification under France's extended producer responsibility framework commands 15-30% price premiums. |
| NMPA Testing Partnership Formation | Joint venture structures bypass China's in-country certification barriers for medical-grade nonwoven direct export. |
Methodological Framework
Document review covered SEC 10-K filings, EU MDR substance disclosure databases, and customs trade records, complemented by interviews with plant managers at spunbond and meltblown converters, procurement leads at US group purchasing organizations, regulatory affairs directors navigating FDA 510(k) pathways, and technical R&D heads at filtration media specialists. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Segment-level outputs across the analysis window reflect discrete modeling of bonding technology, resin specification, end-use certification tier, and geographic production cluster. CAGRs derived from elasticity-adjusted demand projections incorporating propylene feedstock cost scenarios and regulatory mandate implementation timelines. Industry-specific inputs included hospital procurement contract duration patterns and infrastructure project pipeline visibility for geotextile demand.
The model holds under stable naphtha-cracker margin regimes and gradual EU MDR enforcement; deviation in propylene price volatility spikes or accelerated biocompatibility sunset dates would shift capacity investment timing and regional sourcing decisions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market