
 Polywoven Bags Market | 2026-2036
Polywoven Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Polywoven Bags Market Analysis
Asian petrochemical hub capacity is shifting toward higher-tenacity PP grades suited for heavy-duty woven applications. Berry Global leverages vertical integration from resin extrusion through finished bag conversion to sustain margin control across North American agricultural channels. Mondi Group anchors European supply through certified food-contact FIBC production, while Xifa Group dominates domestic Chinese distribution via direct mill relationships with state grain reserves. LC Packaging competes on sustainability credentials with closed-loop recycling programs for post-industrial PP scrap.
Polywoven bags are fabricated from interlaced polypropylene or polyethylene tapes, typically woven at 8×8 to 14×14 threads per inch and laminated with 20-40 micron coextruded films for moisture barrier performance, serving as reusable bulk containers for powders, granules, and agricultural commodities. Bulk Bags and FIBC formats occupy the deepest margin pools due to technical certification requirements for safe working loads and UN dangerous-goods transport compliance. Biodegradable Polymers represent the fastest-evolving material segment as European food processors seek compostable alternatives to conventional PP under packaging waste directives.
REACH registration requirements in Europe restrict certain phthalate plasticizers in woven PP formulations, while India's BIS certification mandates dimensional stability testing for grain-storage sacks distributed through Food Corporation of India tenders. China's GB standards specify tensile strength thresholds for domestic fertilizer packaging, creating technical barriers for uncertified imports. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in regional certification infrastructure or concentrate supply in jurisdictions with mutual recognition agreements.
Market Dynamics
India's BIS certification mandates for grain-storage packaging are forcing converters to upgrade resin grades and testing infrastructure, compressing margins for uncertified suppliers while rewarding quality-standardized producers with Food Corporation of India tender access.
Growth Catalysts
- REACH Registration:European chemical safety protocols under ECHA are phasing out restricted phthalate plasticizers in woven PP formulations, creating certified-supplier premiums for compliant converters.
- Petrochemical Feedstock Clustering:China's Shandong province concentrates converter operations near integrated refineries, reducing resin logistics costs and enabling just-in-time tape extrusion for agricultural sack orders.
- Heavy-Duty Format Certification:UN dangerous-goods transport compliance requirements for Bulk Bags and FIBC formats are deepening technical barriers that protect incumbent specialists with established testing protocols.
Market Restraints
- Propylene Price Volatility:Naphtha-cracker feedstock costs swing with crude oil benchmarks, compressing converter margins when resin prices spike faster than finished bag contract escalators.
- Single-Country Supply Concentration:China's dominance in both PP resin production and woven bag conversion creates geographic risk concentration for buyers seeking supply diversification.
- Mechanical Recycling Limitations:Post-consumer PP tape degradation through repeated melt processing restricts closed-loop content ratios in food-contact applications below brand sustainability targets.
Strategic Opportunities
- Compostable Polymer Formulations:European packaging waste directives are mandating biodegradable alternatives to conventional PP for food-contact woven sacks, opening certified compostable resin supply contracts.
- Direct Mill Relationships:State grain reserve procurement in China is consolidating toward converters with captive relationships to provincial storage facilities, bypassing distributor markups.
- Coextruded Barrier Films:Lamination technology convergence with 20-40 micron multilayer films is enabling moisture-sensitive fertilizer and chemical packaging applications previously served by multiwall paper.
Industry Challenges
- Certification Timeline Compression:India's BIS dimensional stability testing requirements demand 12-18 month validation cycles that delay new product launches for Food Corporation of India tenders.
- High-Tenacity PP Talent Scarcity:Specialized polymer engineering expertise for heavy-duty woven applications concentrates among legacy petrochemical engineers nearing retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polywoven Bags Market |
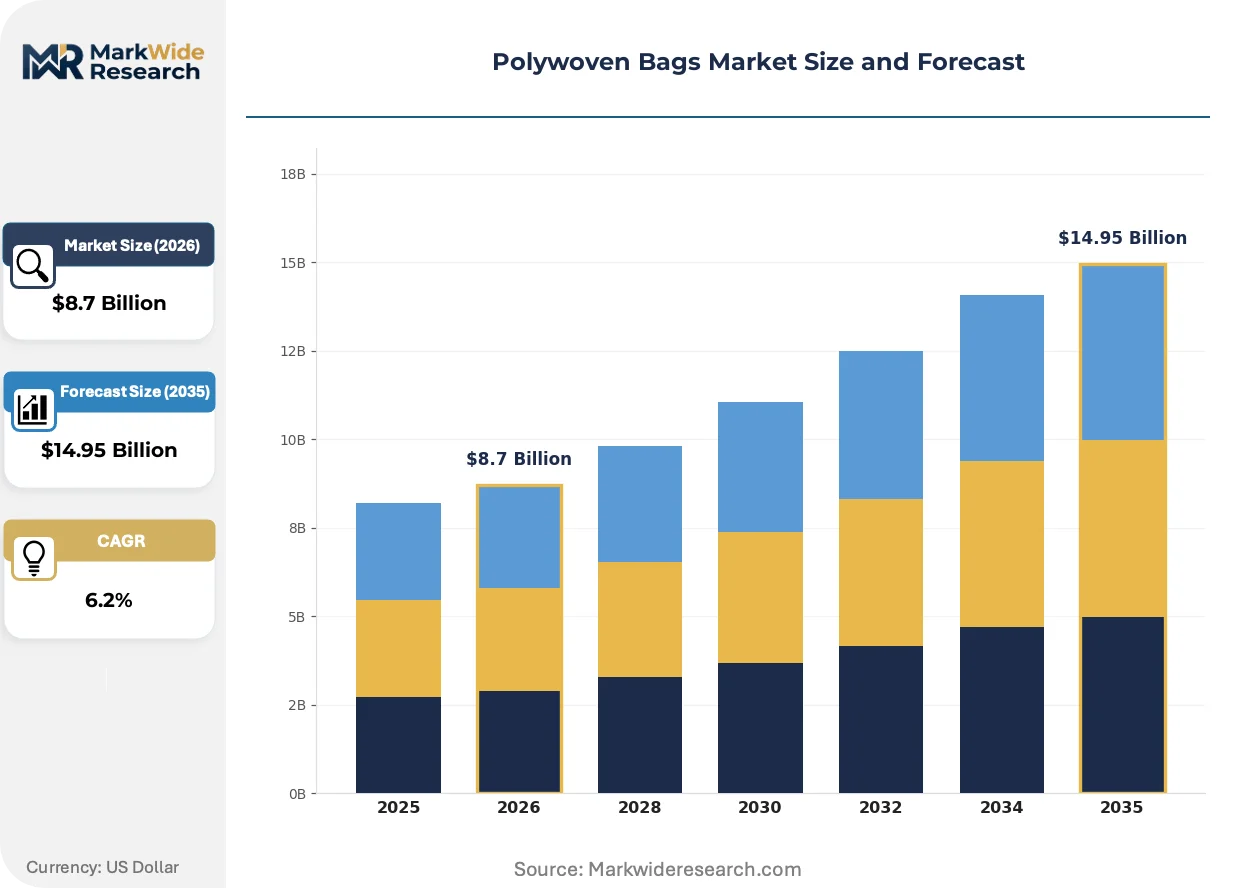
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Bags, Shopping Bags, Sandbags, FIBC End User: Agriculture, Retail, Construction, Food & Beverages Material: PP, HDPE, LDPE, Biodegradable Polymers Distribution Channel: Online, Wholesalers, Retail Stores, Direct Sales |
| Companies Covered | Uflex Ltd, Muscat Polymers, Berry Global, Global-Pak, Manyan, Mondi Group, United Bags, Xifa Group, LC Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polywoven Bags Market Emerging Trajectories
Digital printing and smart coding technologies are displacing conventional flexographic methods on woven surfaces, while regulatory fragmentation across major economies is fragmenting certification requirements and forcing multi-asset compliance investments.
Multilayer coextrusion is unifying moisture barrier and print surface functions into single-pass lamination operations. Agricultural cooperatives in Brazil and Argentina are adopting these unified structures for treated seed packaging. The technology is compressing converter capital requirements by eliminating separate coating lines.
REACH authorization procedures under ECHA are tightening scrutiny of polymer additives in food-contact woven applications. Converter operations serving European food processors must now document full substance inventories through supply chains. Small-scale Asian exporters without EU-established importers face market exclusion.
Grain procurement officers at state reserves are consolidating supplier lists toward vertically integrated converters with captive resin extrusion and in-house tape weaving. Direct contracting is displacing layered distributor networks in China and India. This concentration is most visible in Shandong province and Punjab state tenders.
Polywoven Bags Market Segmentation
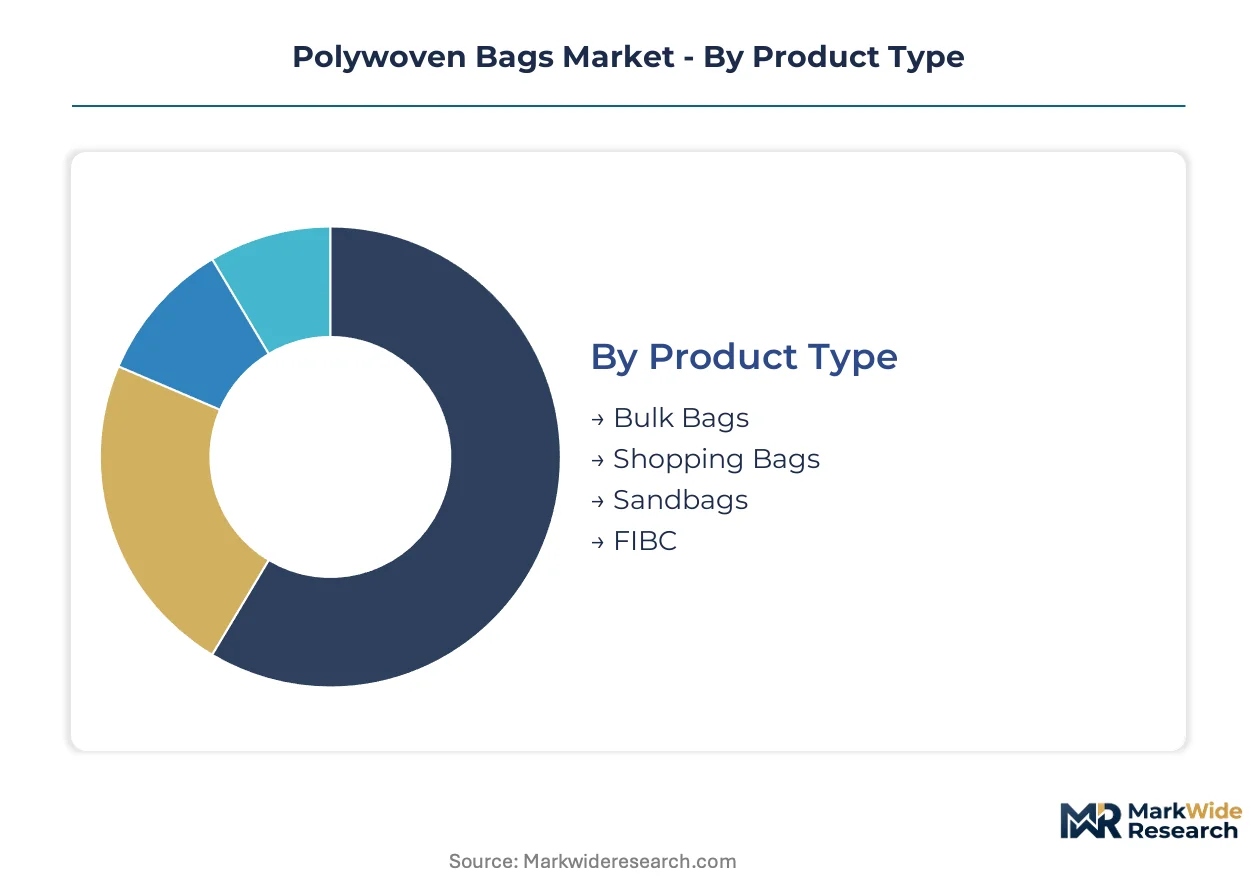
Segmentation in polywoven bags reveals how resin grade specifications and certification tiers create distinct margin pools. Upgrade cycles in agricultural procurement and shifting retail sustainability mandates are redefining competitive positioning across each dimension.
Product Type:
Replacement cycles vary sharply across formats, with UN-certified heavy-duty bags demanding longer validation timelines than commodity shopping sacks.
- Bulk Bags:Woven PP constructions rated for 500-2000 kg safe working loads serve grain handling and mineral transport. Demand concentrates in China's Shandong province, where petrochemical feedstock access enables just-in-time tape extrusion for state grain reserve tenders.
- FIBC:Flexible intermediate bulk containers require UN dangerous-goods transport compliance for chemical and fertilizer applications. European food processors drive specification upgrades toward certified food-contact grades under EFSA frameworks.
- Shopping Bags:Lightweight laminated formats for retail carryout face displacement from non-woven alternatives in urban Indian markets.
- Sandbags:UV-stabilized woven PE constructions for flood control and military applications follow government procurement cycles with multi-year inventory horizons.
Bulk Bags sits at the top of the volume ranking, with FIBC climbing the fastest on chemical-industry compliance requirements.
End User:
Cost-tier stratification separates specification-intensive agricultural tenders from price-sensitive retail channels.
- Agriculture:Grain storage and seed packaging drive heavy-duty woven sack demand. India's BIS certification mandates for Food Corporation of India tenders force resin grade upgrades and compress margins for uncertified suppliers.
- Food & Beverages:FIBC formats for powdered ingredients and sugar require laminated moisture barriers and food-contact compliance. REACH registration under ECHA restricts certain phthalate plasticizers in European supply chains.
- Construction:Cement and aggregate packaging favors cost-optimized PP grades with standard UV stabilization.
- Retail:Reusable shopping bags compete with non-woven PP and paper alternatives on unit economics and consumer perception.
Agriculture captures the dominant revenue share, while Food & Beverages gains ground fastest on compostable polymer adoption.
Material:
Supply concentration in Asian petrochemical hubs shapes regional grade availability and converter sourcing strategies.
- PP:Polypropylene tapes woven at 8×14 threads per inch dominate bulk applications. China's integrated refineries in Shandong province cluster converter operations near resin extrusion capacity.
- Biodegradable Polymers:Compostable alternatives to conventional PP are mandated under European packaging waste directives for food-contact woven sacks. Certified resin supply contracts command premium positioning.
- HDPE:High-density polyethylene offers superior chemical resistance for fertilizer and agrochemical packaging.
- LDPE:Low-density polyethylene serves lamination layers and lightweight retail formats with lower tensile requirements.
PP holds the volume leadership position, with Biodegradable Polymers expanding most quickly on regulatory pressure in European markets.
Distribution Channel:
Customer-type stratification separates large-volume agricultural tenders from fragmented retail procurement.
- Direct Sales:Converters with captive resin extrusion and in-house tape weaving contract directly with state grain reserves in China and India. Punjab state tenders and Shandong provincial procurement favor vertically integrated suppliers.
- Wholesalers:Distributor networks serve mid-scale agricultural cooperatives and regional construction suppliers with standardized sack specifications.
- Online:E-commerce channels penetrate small-lot retail and customized printing segments with shorter lead times.
- Retail Stores:Point-of-sale distribution for consumer-facing shopping bags faces margin compression from private-label competition.
Direct Sales dominates agricultural volume, with Online channels gaining share fastest in customized short-run applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as converters migrate toward jurisdictions with streamlined certification timelines and lower compliance costs. Shandong province's integrated petrochemical infrastructure offers cost advantages that European REACH-registered suppliers struggle to match.
China
State grain reserve procurement drives bulk-format woven sack demand through Shandong province's converter cluster. GB standards specify tensile strength thresholds for domestic fertilizer packaging, creating technical barriers for uncertified imports. Qingdao and Yantai host tape extrusion operations that supply agricultural cooperatives across North China Plain grain belts.
India
Food Corporation of India tenders mandate BIS-certified dimensional stability testing for grain-storage packaging. Punjab state procurement officers consolidate supplier lists toward vertically integrated converters with captive resin extrusion. Ludhiana and Amritsar operations face 12-18 month validation cycles that delay new product launches.
Germany
EFSA food-contact compliance requirements and ECHA REACH registration restrict phthalate plasticizers in woven PP formulations. Bavarian and North Rhine-Westphalia converters command certified-supplier premiums for compliant European supply chains. Stuttgart-area technical centers develop high-tenacity PP grades for heavy-duty FIBC applications.
United States
Midwest agricultural cooperatives drive seasonal demand spikes for UV-stabilized bulk bags. EPA and OSHA frameworks govern workplace exposure during tape extrusion and lamination operations. Iowa and Illinois converter networks serve corn and soybean handling infrastructure with just-in-time fulfillment.
Brazil
ANVISA regulations govern food-contact woven sack applications for sugar and coffee exports. São Paulo state and Paraná agricultural belts adopt multilayer coextruded barriers for treated seed packaging. Campinas-area operations leverage Mercosur trade access to supply Argentine grain handlers.
Polywoven Bags Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue compostable polymer niches and digital printing customization. The vendor base stratifies across three maturity tiers: legacy petrochemical-integrated converters, regional specialists with captive tape weaving, and technology-focused entrants targeting sustainability credentials. Two dominant competitive moves define current positioning: backward integration into resin extrusion to secure margin control, and geographic expansion through regional certification infrastructure investments.
Among North American fabricators, Berry Global exemplifies the vertically integrated archetype with operations spanning resin through finished bag conversion. LC Packaging represents the sustainability-focused tier through closed-loop recycling program positioning. Xifa Group anchors the China-domestic specialist segment with direct mill relationships to state grain reserves.
| Leading Market Players |
|---|
| Uflex Ltd |
| Muscat Polymers |
| Berry Global |
| Global-Pak |
| Manyan |
| Mondi Group |
| United Bags |
| Xifa Group |
| LC Packaging |
| Others |
Supply Flow & Price Mechanics
Food Corporation of India tender consolidation toward BIS-certified suppliers forces converters to absorb certification costs and upgrade resin grades, compressing margins for uncertified players while rewarding quality-standardized producers with procurement access.
Pricing Analysis
Distributor markups in layered agricultural supply chains face compression as state grain reserves in China and India consolidate toward direct mill relationships. Three-tier pricing structure across premium certified, standard compliant, and economy uncertified levels separates Food Corporation of India tender winners from spot-market suppliers. Price differentiation rests on BIS dimensional stability certification and captive resin extrusion capability. Pricing pressure stems from propylene feedstock volatility, with naphtha-cracker cost swings outpacing finished bag contract escalators. Small-scale regional wholesalers exhibit highest price sensitivity; vertically integrated converters with Shandong province petrochemical access demonstrate lowest.
Supply Chain Analysis
Dual-sourcing mandates from European food processors and state grain reserve procurement officers are fragmenting supplier lists toward qualified converters with redundant tape extrusion capacity. Supply concentrates in China, India, and Germany, with Shandong province and Punjab state anchoring Asian converter operations. Raw material dependencies center on polypropylene resin, high-tenacity PP grades, and coextruded barrier films. Single-country concentration risk runs through China's dominance in both PP resin production and woven bag conversion. Distribution runs through direct sales to state reserves, wholesaler networks for agricultural cooperatives, and e-commerce channels for customized short-run retail applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polywoven bags market functions as a stable compounder, with agricultural grain storage demand and regulatory certification mandates providing steady replacement-cycle revenue visibility.
For Market Incumbents: Anticipate margin compression from biodegradable polymer entrants by securing exclusive supply contracts with European compostable resin producers before certification thresholds harden. Invest in captive tape weaving capacity in Punjab state and Shandong province to defend Food Corporation of India tender share against emerging regional specialists. Prioritize BIS and EFSA compliance infrastructure as the primary barrier to entry. For New Entrants and Emerging Players: Mid-scale agricultural cooperatives in Brazil and Argentina seeking multilayer coextruded seed packaging represent the most penetrable buyer archetype underserved by incumbent distributors. Target certified compostable FIBC formats for European food processors facing packaging waste directive mandates. Establish direct mill relationships with state grain reserves as the go-to-market angle, bypassing layered distributor markups entirely. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated converters with captive resin extrusion and established BIS or EFSA certification infrastructure. The five-to-ten year viability window favors producers with backward integration into petrochemical feedstock clusters. Target acquisition archetype: regional specialists with direct state reserve relationships and underutilized tape weaving capacity. Watch for inflection in European compostable polymer adoption rates as the signal to accelerate sustainability-focused consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Extrusion | Captive PP supply from Shandong province refineries secures margin control against feedstock volatility. |
| Certification Infrastructure Investment | BIS laboratory accreditation unlocks Food Corporation of India tender participation and pricing premiums. |
| Compostable Polymer Formulation Partnership | Exclusive European resin supply contracts position converters ahead of packaging waste directive enforcement. |
| Direct Mill Relationship Development | State grain reserve procurement consolidation rewards converters bypassing distributor networks with volume commitments. |
| Multilayer Coextrusion Technology Adoption | Unified barrier and print surface functions displace separate coating lines and compress capital requirements. |
Methodological Framework
Direct dialogue with converter operations managers, agricultural cooperative procurement officers, petrochemical resin sales directors, and food-contact compliance consultants grounded qualitative insights. Secondary validation drew from BIS certification registries, Food Corporation of India tender documentation, ECHA REACH substance inventories, and customs trade data for PP tape and woven sack shipments. Bottom-up and top-down triangulation cross-checked regional production capacity estimates against end-use demand segmentation.
Bottom-up modeling built segment-level forecasts from individual converter capacity, utilization rates, and product mix assumptions, while top-down validation anchored projections against petrochemical feedstock supply and agricultural commodity handling volumes. Segmentation dimensions spanned product format, end-use industry, material grade tier, and distribution channel structure. CAGRs were derived from regression analysis of historical replacement cycles and procurement pattern shifts. Industry-specific inputs included state grain reserve tender volumes and European compostable polymer adoption curves.
Underlying measurement precision varies by segment; BIS-certified bulk bag volumes carry tighter precision than uncertified spot-market transactions. Forecasts reflect assumptions around propylene price stability, certification timeline durations, and agricultural procurement consolidation patterns. Deviation in European packaging waste directive enforcement timelines or Food Corporation of India tender frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Nonwoven Flanging Market