
 Global Wet Laid Nonwovens Market | 2026-2036
Global Wet Laid Nonwovens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wet Laid Nonwovens Market Foresight
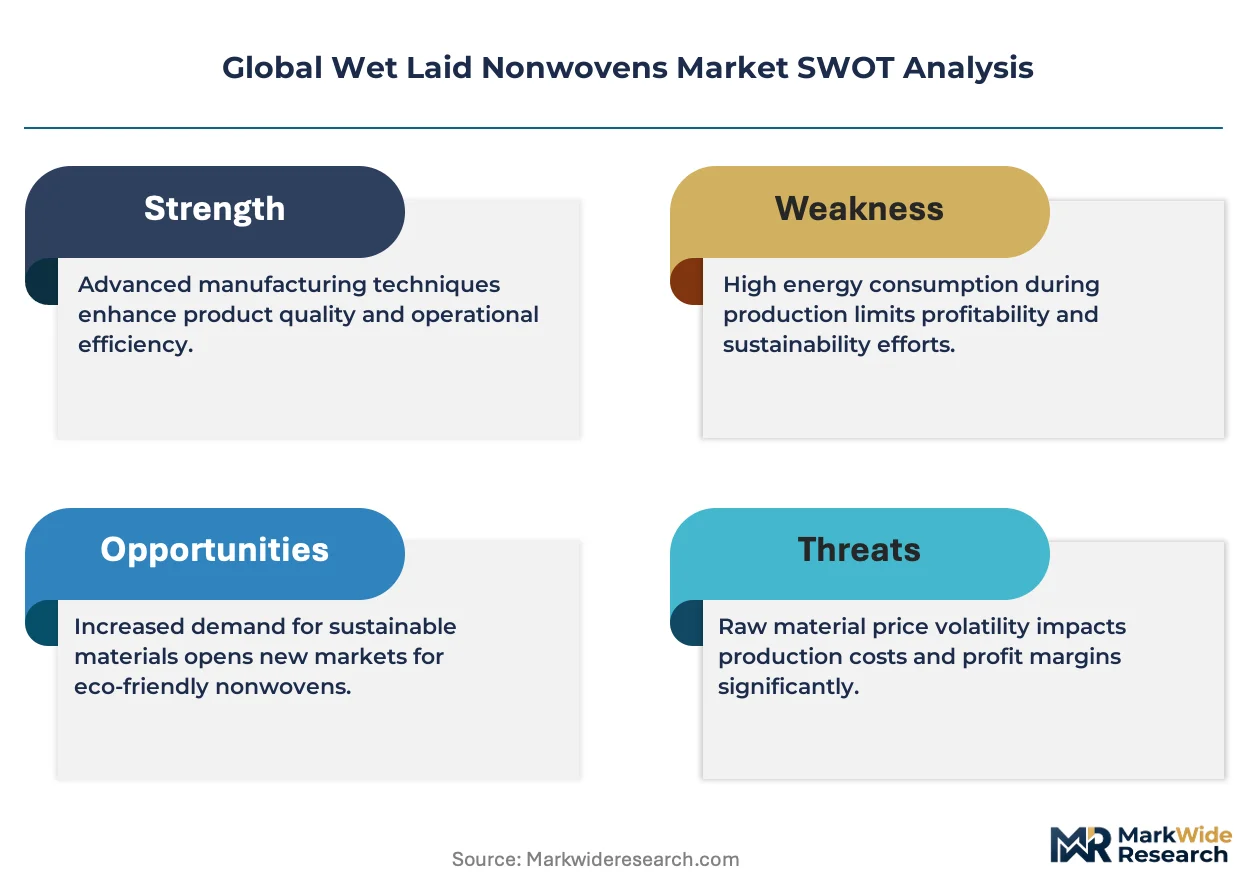
European specialty paper producers is repositioning wet laid capacity toward technical nonwoven grades. Ahlstrom-Munksjo Oyj leverages its Finnish pulp integration to dominate filtration media supply. Glatfelter Corporation anchors North American output through controlled specialty fiber sourcing. Kimberly-Clark Corporation differentiates via hydroentangled medical substrates for surgical applications.
Wet laid nonwovens are sheet structures manufactured by suspending cellulose, synthetic, or blended fibers in water, then depositing them on a forming wire to create uniform webs with basis weights typically ranging from 10 to 200 gsm, primarily serving filtration, hygiene, and industrial reinforcement functions. Cellulose-based grades retain the largest volume share due to cost parity with airlaid alternatives in wipes and food pads. Synthetic fiber segments command premium positioning in automotive fuel filtration where thermal stability exceeds 150°C. Hydroentangling technology is displacing chemical bonding in medical dressing applications as saline compatibility requirements tighten.
EPA effluent guidelines constrain fiber processing discharge in US mill operations, while REACH chemical restrictions in Europe limit formaldehyde-based wet strength resins. FDA biocompatibility standards for Class II medical devices directly shape product development timelines for healthcare-facing suppliers. ISO 10993 testing protocols increasingly determine market access for wound care substrates. Stakeholders must monitor evolving single-use plastic directives across multiple jurisdictions to anticipate fiber substitution mandates.
Market Dynamics
EU Green Deal mandates on fiber recyclability are compressing product development cycles while hydroentangling technology restructures bonding preferences across medical and filtration grades. Suppliers face simultaneous pressure to eliminate formaldehyde-based wet strength chemistry and certify saline-compatible substrates for Class II devices.
Growth Catalysts
- EU Green Deal fiber mandates:Binding sustainability targets under the European Commission's circular economy action plan are forcing substrate substitution toward recycled cellulose and bio-based synthetics in hygiene applications.
- Fuel filtration thermal requirements:Automotive OEM specifications exceeding 150°C thermal stability are pulling synthetic wet laid grades into fuel filter media, displacing meltblown alternatives in underhood applications.
- Germany's industrial corridor concentration:Technical nonwoven demand from automotive and chemical processing clusters in North Rhine-Westphalia and Baden-Württemberg is anchoring specialty grade consumption.
Market Restraints
- Specialty pulp supply concentration:Dissolving pulp availability for high-purity cellulose grades remains concentrated among Nordic and Brazilian suppliers, exposing converters to freight volatility and currency fluctuation.
- REACH chemical restrictions:ECHA limitations on formaldehyde-based wet strength resins are forcing reformulation investments without immediate performance-equivalent alternatives for high-wet-strength industrial papers.
- Spunlace substitution in wipes:Hydroentangled spunlace structures from carded-pulp blends are capturing premium wipe segments where wet laid cellulose historically dominated on cost.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO serialization requirements and cold-chain expansion are creating demand for sterile, fiber-based barrier substrates in vaccine packaging and diagnostic kit components.
- Carbon capture filtration media:Direct air capture and post-combustion carbon capture projects are specifying synthetic wet laid substrates with controlled pore distribution for amine solvent contactors.
- US IRA clean manufacturing credits:Section 45X advanced manufacturing production credits are incentivizing domestic wet laid capacity for battery separator and filtration applications.
Industry Challenges
- ISO 10993-5 cytotoxicity testing backlog:Contract laboratory capacity constraints are extending medical substrate certification timelines from 12 to 18 months, delaying product launches for wound care and surgical drape applications.
- Multi-jurisdiction plastic directive fragmentation:Divergent single-use plastic definitions across EU member states, US state-level legislation, and emerging Asian regulations are complicating product platform standardization for hygiene suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wet Laid Nonwovens Market |
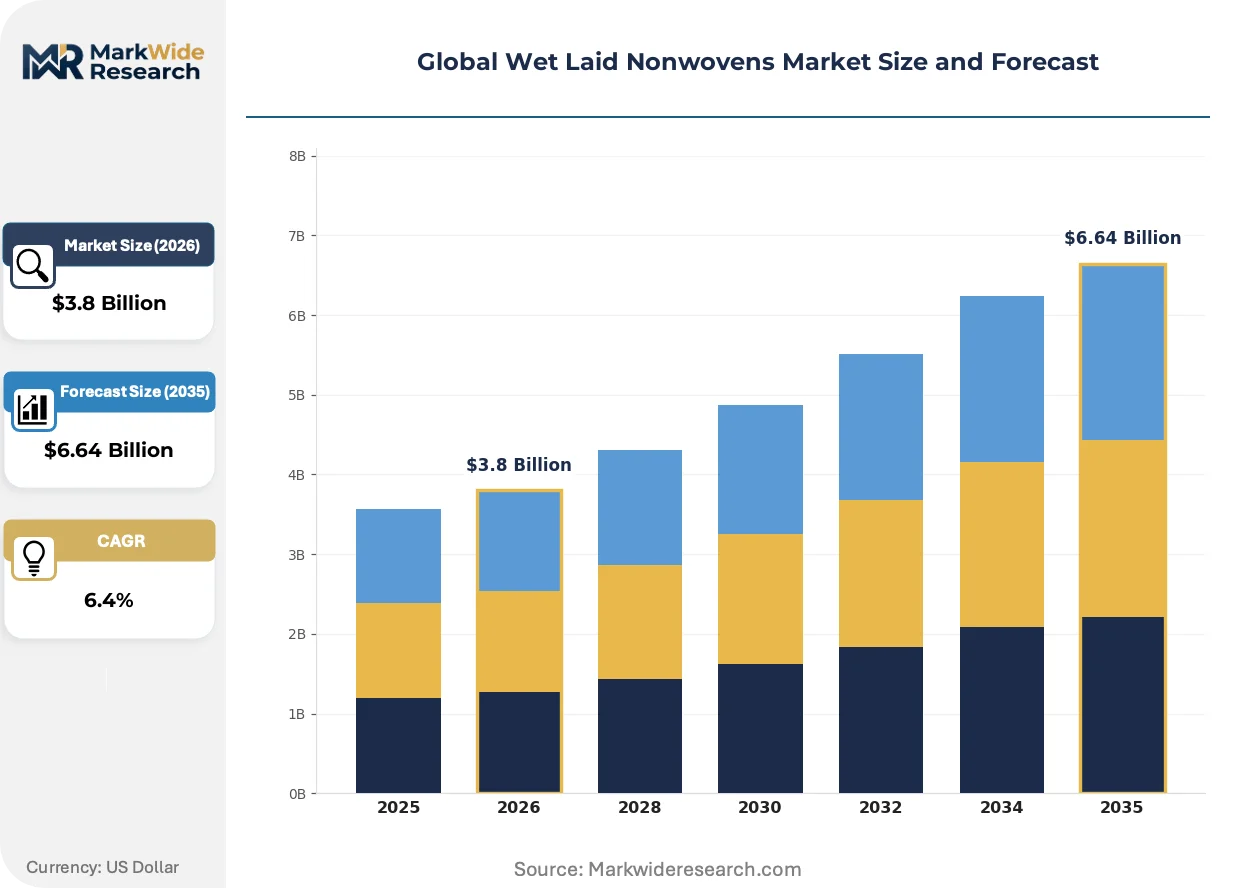
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose-Based, Synthetic Fibers, Blend Fibers, Recycled Fibers Application: Filtration Media, Medical Dressings, Automotive Components, Household Wipes End User: Healthcare Providers, Industrial Manufacturers, Consumer Goods Producers, Transportation OEMs Technology: Wet Pressing, Hydroentangling, Thermal Bonding, Chemical Bonding |
| Companies Covered | Ahlstrom-Munksjo Oyj, Glatfelter Corporation, Kimberly-Clark Corporation, DuPont de Nemours Inc., Toray Industries Inc., Berry Global Group Inc., Fitesa S.A., Johns Manville Corporation, Freudenberg & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wet Laid Nonwovens Market Shifts & Advancements
Water-based bonding chemistry and mechanical entanglement processes are displacing thermal and chemical fixation methods across medical and filtration segments. Equipment suppliers are retrofitting existing Fourdrinier and inclined wire machines for hydroentangling integration.
Hydroentangling is consolidating its position as the dominant bonding technology for medical-grade wet laid substrates. Surgical drape and wound dressing manufacturers are specifying hydroentangled structures for saline compatibility and lint-free performance. This transition is compressing demand for chemically bonded grades and forcing resin suppliers to reformulate or exit medical segments.
EPA effluent guideline updates under the Clean Water Act are tightening total suspended solids limits for fiber processing discharge. Mill operators in the US Southeast are investing in dissolved air flotation and membrane bioreactor systems to meet NPDES permit conditions. Capital allocation toward wastewater infrastructure is diverting funds from product development programs.
Hospital procurement consortiums are consolidating supplier panels and demanding consolidated SKU portfolios with standardized biocompatibility documentation. Group purchasing organizations in the US and NHS Supply Chain in the UK are reducing approved vendor lists from 12-15 to 3-5 per substrate category. This concentration is favoring wet laid producers with in-house ISO 10993 testing capabilities and multi-site manufacturing redundancy.
Global Wet Laid Nonwovens Market Segmentation
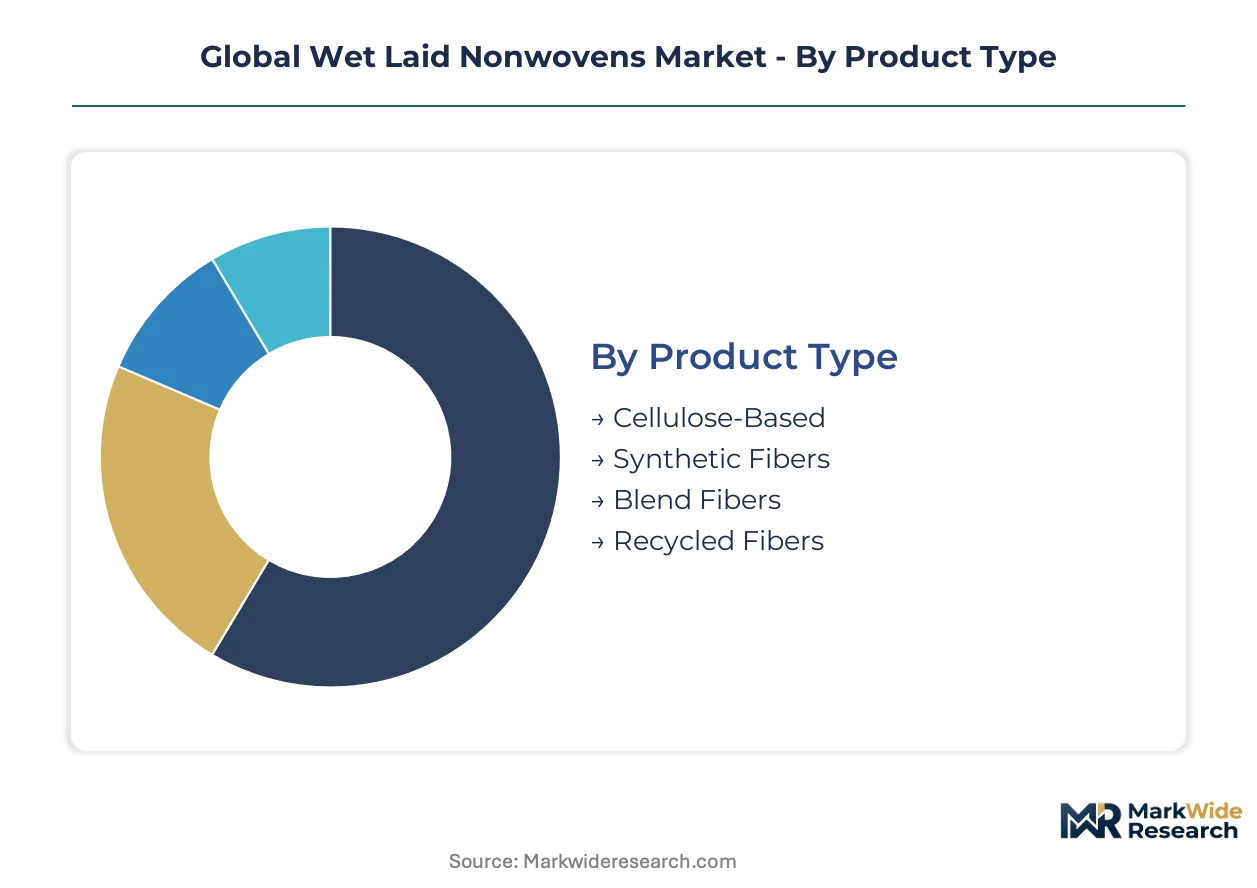
Wet laid nonwoven producers configure asset bases around fiber handling capabilities and bonding technologies, with capital allocation decisions locking in served markets for 10-15 year equipment lifecycles. Segment boundaries increasingly blur as hydroentangling retrofits enable grade migration between medical and filtration applications.
Product Type:
Capital intensity peaks with synthetic fiber processing lines requiring precision extrusion and controlled denier cutting, while cellulose-based operations leverage lower-cost pulp integration.
- Cellulose-Based:Structures manufactured from wood pulp suspensions achieve basis weights between 10-200 gsm with natural absorbency profiles. Demand concentrates in Germany's North Rhine-Westphalia corridor where food pad and industrial wipe converters cluster near Ahlstrom-Munksjo's Finnish pulp supply chain.
- Synthetic Fibers:Polyester, polypropylene, and aramid grades deliver thermal stability exceeding 150°C for automotive fuel filtration. Automotive OEM specifications in Baden-Württemberg pull premium synthetic volumes into underhood applications where meltblown alternatives fail.
- Blend Fibers:Cellulose-synthetic composites balance cost and performance in hygiene substrates.
- Recycled Fibers:Post-consumer and post-industrial reclaimed cellulose streams face EU Green Deal fiber recyclability mandates.
Most installed capacity flows through cellulose-based grades. Expansion is steepest in synthetic fibers.
Application:
Application segments diverge sharply by certification burden, with medical and filtration grades requiring ISO 10993 and EPA compliance investments that wipe producers avoid.
- Filtration Media:Synthetic wet laid substrates with controlled pore distribution serve direct air capture and post-combustion carbon capture amine contactors. German chemical processing clusters in Ludwigshafen and Leverkusen anchor technical filtration demand.
- Medical Dressings:Hydroentangled structures meet FDA biocompatibility standards for Class II devices including surgical drapes and wound care substrates. NHS Supply Chain consolidation in the UK favors suppliers with in-house ISO 10993-5 cytotoxicity testing.
- Automotive Components:Fuel filter media and battery separator substrates leverage thermal stability specifications.
- Household Wipes:Cellulose grades compete with spunlace carded-pulp blends in premium segments.
Filtration media commands the highest capacity utilization rates. Medical dressings are gaining share fastest.
End User:
End user concentration determines contract structure, with healthcare procurement consortiums demanding multi-site manufacturing redundancy that industrial buyers rarely require.
- Healthcare Providers:Hospital group purchasing organizations in the US and NHS Supply Chain in the UK reduce approved vendor lists from 12-15 to 3-5 per substrate category. Suppliers must maintain ISO 10993 documentation and saline-compatible substrate portfolios.
- Industrial Manufacturers:Chemical processing and food packaging converters in Germany's industrial corridor specify high-wet-strength grades for process reliability.
- Consumer Goods Producers:Wipe and hygiene product manufacturers face divergent single-use plastic definitions across EU member states.
- Transportation OEMs:Automotive fuel filtration specifications exceed 150°C thermal stability requirements.
Healthcare providers concentrate the most stringent certification requirements. Industrial manufacturers absorb the greatest volume tonnage.
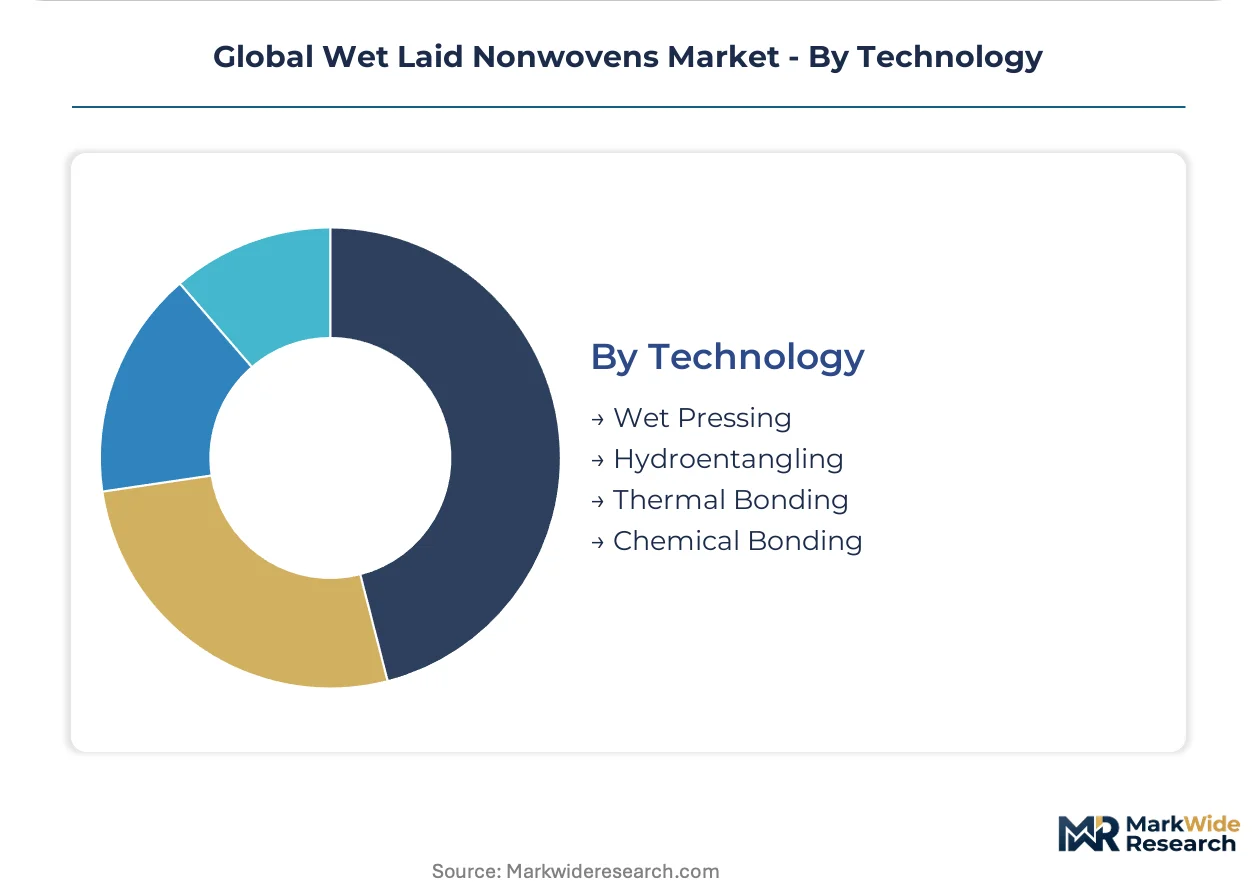
Technology:
Technology choice determines chemical exposure profiles, with hydroentangling eliminating formaldehyde-based wet strength resins that REACH restrictions now constrain.
- Wet Pressing:Traditional Fourdrinier and inclined wire forming with mechanical dewatering produces uniform webs at high speeds. US Southeast mills face EPA effluent guideline updates requiring dissolved air flotation and membrane bioreactor investments.
- Hydroentangling:High-pressure water jets mechanically entangle fibers without chemical binders, achieving saline compatibility for medical applications. Equipment suppliers retrofit existing machines for hydroentangling integration as hospital procurement demands lint-free performance.
- Thermal Bonding:Synthetic fiber activation through calendering or through-air ovens.
- Chemical Bonding:Latex and wet strength resin fixation faces ECHA limitations on formaldehyde chemistry.
Wet pressing retains the largest installed base. Hydroentangling is climbing the fastest as medical grade requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs more wet laid nonwoven tonnage than the United States, though American producers retain tighter control over specialty fiber supply chains. This geographic split shapes competitive positioning across filtration, medical, and industrial wipe applications.
United States
Fuel filtration media demand from Detroit-area automotive clusters and battery separator substrates for electric vehicle production anchor domestic consumption. EPA effluent guideline updates under the Clean Water Act force Southeast mills to invest in dissolved air flotation and membrane bioreactor systems. The US Southeast pulp processing corridor faces capital diversion from product development toward wastewater infrastructure compliance.
Germany
North Rhine-Westphalia's chemical processing clusters in Ludwigshafen and Leverkusen specify synthetic wet laid substrates for carbon capture amine contactors. EU Green Deal circular economy mandates accelerate fiber recyclability requirements for hygiene applications. Baden-Württemberg automotive OEMs pull premium synthetic grades into underhood fuel filtration exceeding 150°C thermal stability specifications.
China
Domestic pharmaceutical packaging expansion and cold-chain infrastructure buildout drive sterile barrier substrate demand. NMPA biocompatibility standards for Class II medical devices shape product development timelines for wound care suppliers. Yangtze River Delta converters concentrate capacity for industrial wipe and food pad applications serving domestic consumer goods producers.
India
CDSCO serialization requirements for pharmaceutical packaging and vaccine cold-chain expansion create demand for fiber-based barrier substrates. Maharashtra's pharmaceutical manufacturing corridor anchors sterile packaging consumption for diagnostic kit components. Gujarat textile processors explore wet laid capacity for technical nonwoven grades serving domestic hygiene markets.
United Kingdom
NHS Supply Chain consolidation reduces approved vendor lists for surgical drape and wound dressing substrates from 12-15 to 3-5 suppliers. ISO 10993-5 cytotoxicity testing documentation requirements favor producers with in-house certification capabilities. Midlands-based converters face margin pressure from hospital procurement consortiums demanding multi-site manufacturing redundancy.
Global Wet Laid Nonwovens Market Competitive Landscape
Finnish and Nordic producers anchor the integrated pulp-to-substrate tier; American specialists hold positions in controlled fiber sourcing and medical-grade hydroentangling. The market structures around three strategic archetypes: vertically integrated pulp owners with captive cellulose supply, specialty fiber converters leveraging synthetic polymer expertise, and diversified hygiene conglomerates with brand channel access. Competitive moves concentrate on hydroentangling retrofits of existing Fourdrinier capacity and backward integration into dissolving pulp supply.
Among Nordic integrated producers, Ahlstrom-Munksjo Oyj exemplifies the pulp-captive archetype through Finnish supply chain control. Glatfelter Corporation occupies a position among North American specialty fiber converters with structured raw material sourcing. Kimberly-Clark Corporation represents the diversified hygiene conglomerate tier with established medical substrate channels. These three anchors illustrate how geographic fiber access and end-market certification capabilities determine competitive positioning across filtration, medical, and industrial segments.
| Leading Market Players |
|---|
| Ahlstrom-Munksjo Oyj |
| Glatfelter Corporation |
| Kimberly-Clark Corporation |
| DuPont de Nemours Inc. |
| Toray Industries Inc. |
| Berry Global Group Inc. |
| Fitesa S.A. |
| Johns Manville Corporation |
| Freudenberg & Co. KG |
| Others |
Supply & Pricing Matrix
Hospital group purchasing organizations in the United States and NHS Supply Chain in the United Kingdom anchor demand concentration, forcing contract-based long-term offtake pricing with volume-tier discounts and ISO 10993 certification premiums. This buyer consolidation shifts pricing power toward procurement consortiums demanding multi-site manufacturing redundancy and standardized biocompatibility documentation.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for cellulose-based grades while German automotive OEMs sustain premium positioning for synthetic substrates exceeding 150°C thermal stability. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical grades from industrial filtration media and commodity wipe substrates. Cost compression in cellulose grades intensifies because spunlace substitution erodes wet laid share in premium wipe segments. Industrial manufacturers absorb the greatest volume tonnage and exhibit highest price sensitivity, while healthcare providers prioritize certification compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and US IRA Section 45X credits are reshaping sourcing patterns for battery separator and pharmaceutical packaging substrates. Dissolving pulp availability draws from Finnish and Brazilian suppliers, while synthetic fiber extrusion centers on Germany, China, and the United States. Single-source vulnerability in Nordic dissolving pulp exposes converters to freight volatility and currency fluctuation. Distribution runs through converter networks clustered near automotive OEMs in Baden-Württemberg, chemical processing hubs in Ludwigshafen, and pharmaceutical corridors in Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal fiber recyclability mandates compress margins in Europe while US IRA clean manufacturing credits and Indian PLI incentives attract capacity investment toward lower-regulatory-cost jurisdictions.
For Market Incumbents: Acquire hydroentangling equipment assets and retrofit existing Fourdrinier capacity to defend medical-grade positioning against spunlace substitution in surgical drape applications. Secure captive dissolving pulp supply through backward integration into Finnish or Brazilian pulp operations to mitigate specialty pulp supply concentration risk. Prioritize in-house ISO 10993-5 cytotoxicity testing capabilities to compress certification timelines and meet NHS Supply Chain vendor consolidation requirements. For New Entrants and Emerging Players: Hydroentangling technology retrofits offer a technology-first wedge into medical dressing segments where saline compatibility requirements tighten and established suppliers face 18-month certification backlogs. Target Indian pharmaceutical packaging substrates where CDSCO serialization requirements and vaccine cold-chain expansion create sterile barrier demand without entrenched incumbent control. Pursue carbon capture filtration media specifications for direct air capture projects as a go-to-market angle leveraging controlled pore distribution capabilities. For Investors and Strategic Acquirers: Diversified hygiene conglomerates with established medical substrate channels are the most active acquirer in this space, seeking synthetic fiber processing capabilities and FDA-cleared product portfolios. Mid-cap specialty fiber converters with structured raw material sourcing and hydroentangled medical-grade capacity represent the optimal acquisition target archetype. Watch for ISO 10993 testing laboratory capacity expansion announcements as the inflection indicator signaling compressed certification timelines and accelerated product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hydroentangling Equipment Retrofit | Enables migration from chemical bonding to saline-compatible medical substrates meeting FDA Class II standards. |
| Backward Integration into Dissolving Pulp | Captures Finnish or Brazilian pulp supply to secure high-purity cellulose grades for filtration media. |
| In-House ISO 10993 Certification | Compresses 18-month cytotoxicity testing timelines to meet NHS Supply Chain vendor consolidation demands. |
| Synthetic Fiber Capacity Expansion | Serves Baden-Württemberg automotive OEM specifications exceeding 150°C thermal stability for fuel filtration. |
| Carbon Capture Media Development | Positions suppliers for direct air capture and post-combustion amine contactor projects in Ludwigshafen clusters. |
Research Methodology
Bottom-up medical dressing and filtration media modeling reconciled against top-down pulp processing and synthetic fiber capacity tracking forms the analytical core. Primary interviews with wet laid nonwoven plant managers, hospital GPO contracts managers, biomedical engineers at wound care manufacturers, and automotive Tier 1 procurement specialists combined with secondary validation from EPA effluent guideline filings, ECHA REACH restriction updates, FDA 510(k) submission databases, and EU Green Deal circular economy action plan documentation. Triangulation across stakeholder input and regulatory filings ensures demand-side and supply-side estimates converge.
Input-output matrices map fiber suspension throughput to finished substrate tonnage across product type, application, end user, and technology segmentation dimensions throughout the forecast period. CAGRs derive from capacity utilization trends, substitution elasticity between wet laid and spunlace structures, and regulatory-driven fiber mandate compliance costs. Industry-specific forecast inputs include hydroentangling retrofit investment cycles, ISO 10993 testing laboratory capacity constraints, and EU Green Deal fiber recyclability implementation timelines.
The model holds under stable regulatory enforcement timelines and intact specialty pulp supply chains; deviation in REACH chemical restriction acceleration or Nordic dissolving pulp supply disruption would shift capacity expansion trajectories and pricing tier boundaries. Forecasts reflect documented assumptions regarding hospital procurement consolidation velocity and automotive thermal specification stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Airlaid Textile Market