
 PP Nonwovens Market | 2026-2036
PP Nonwovens Market Size, Share, and Industry Trends Forecast 2026-2036
PP Nonwovens Market Intelligence
Expansion of manufacturing capacity in China is rewriting the supply dynamics for polypropylene nonwovens. Berry Global Group leverages its extensive scale to serve multinational hygiene product manufacturers. Freudenberg Group differentiates through its focus on high-performance materials for automotive and filtration applications. Toray Industries, Inc. competes with advanced spunbond and meltblown technologies developed in Japan.
PP nonwovens are engineered fabrics produced from polypropylene fibers bonded together through thermal, mechanical, or chemical processes. These materials are valued for properties like liquid repellency, breathability, and filtration efficiency. The hygiene application, driven by demand for diapers and sanitary products, constitutes the largest volume segment. Geotextiles represent a value-added category, where material strength and durability are critical for construction and civil engineering projects.
Regulatory frameworks such as the US FDA's requirements for skin-contact materials in medical devices directly influence material selection. In Europe, the ECHA's REACH regulation governs the chemical substances used in manufacturing, impacting the entire supply chain. Key decisions for producers now revolve around balancing investment in high-volume, commoditized spunbond lines against developing specialized meltblown capacity for high-margin filtration media.
Market Dynamics
A structural divergence now defines the market. Producers must choose between investing in high-volume spunbond lines for the commoditized hygiene segment or developing specialized meltblown capacity to meet stringent filtration and medical application standards under increasing regulatory pressure.
Growth Catalysts
- EU Medical Device Regulation:This framework mandates higher quality and safety standards for nonwovens in medical applications like surgical gowns and drapes, creating demand for premium, certified materials.
- Indian PLI Scheme:Government incentives for domestic manufacturing are accelerating investment in new PP nonwoven capacity in India, particularly to serve the expanding domestic hygiene and healthcare markets.
- Geotextile Engineering:The use of PP nonwovens in civil engineering for soil stabilization and drainage is expanding due to their durability and cost-effectiveness compared to traditional construction materials.
Market Restraints
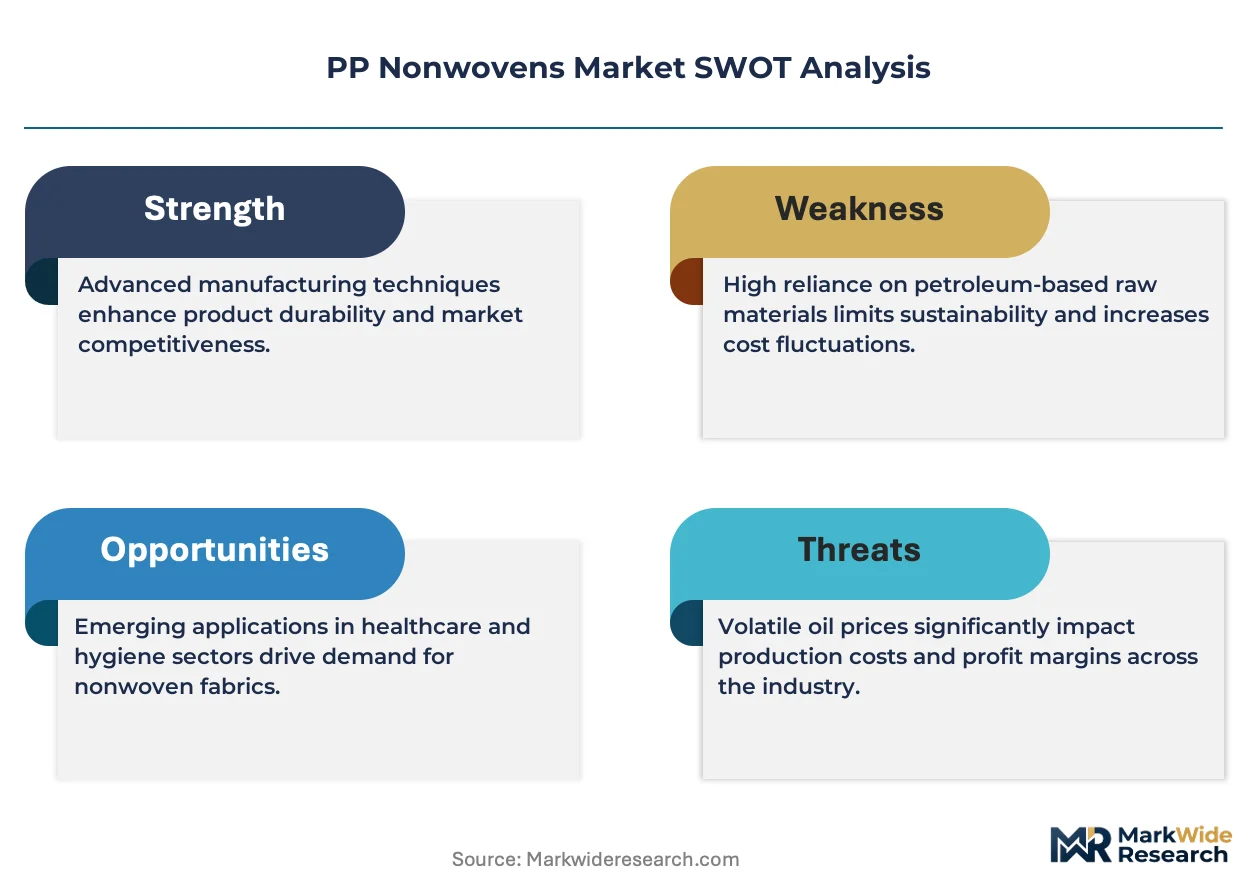
- Polypropylene Resin Volatility:As the primary raw material, fluctuating prices for polypropylene, tied to petrochemical markets, directly impact production costs and compress margins for nonwoven manufacturers.
- Substitution by Natural Fibers:In certain consumer applications like wipes, demand for sustainable alternatives is creating a substitution threat from materials like cotton, viscose, and other cellulosic fibers.
- Meltblown Production Complexity:Achieving consistent sub-micron fiber diameters for high-efficiency filtration media requires precise process control, representing a significant technical barrier for new entrants.
Strategic Opportunities
- Automotive Sound Insulation:The shift toward electric vehicles, which require enhanced cabin quietness, opens opportunities for advanced PP nonwovens as lightweight acoustic insulation materials in door panels and headliners.
- Advanced Filtration in Southeast Asia:Rising air quality concerns and industrialization in countries like Vietnam and Indonesia create an underpenetrated market for high-performance meltblown filter media.
- Circular Economy Mandates:European regulations promoting recyclability are driving innovation in mono-material PP nonwoven products, designed for easier recycling streams compared to multi-material composites.
Industry Challenges
- High Capital Expenditure:The acquisition and installation of modern, high-speed spunbond and meltblown production lines require substantial upfront capital investment, posing a significant hurdle for smaller producers.
- Navigating Global Chemical Regulations:Manufacturers face complexity in ensuring products comply with a patchwork of substance regulations, such as Europe's REACH and California's Proposition 65, across different export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PP Nonwovens Market |
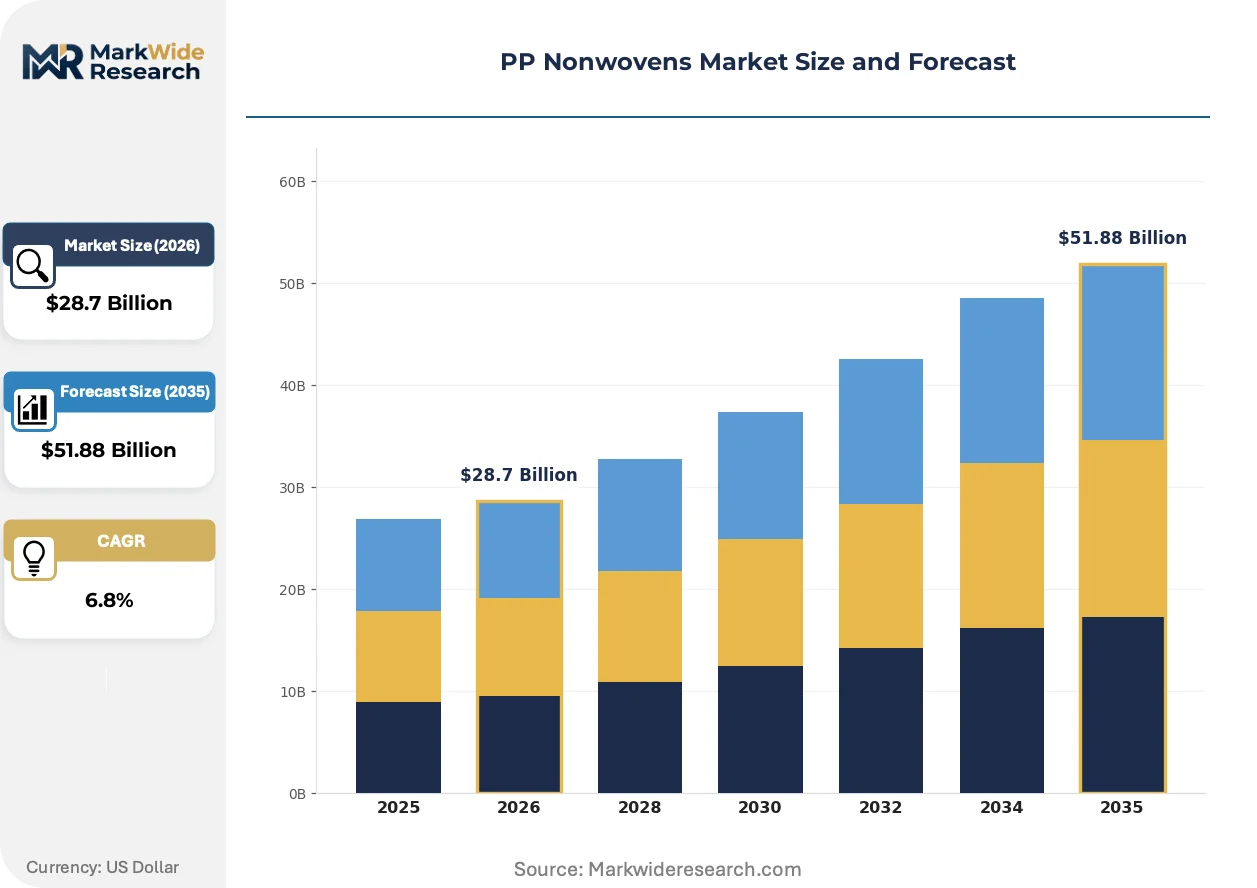
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond, Meltblown, Needle Punch, Thermobonded Application: Medical, Hygiene, Geotextiles, Filtration End User: Healthcare, Agriculture, Automotive, Construction Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Berry Global Group, Inc, Kimberly-Clark Corporation, DuPont de Nemours, Inc., Freudenberg Group, Ahlstrom-Munksjo Oyj, Avgol Nonwovens, Toray Industries, Inc, Fibertex Nonwovens A/S, Suominen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PP Nonwovens Market Strategic Shifts & Innovations
Material science advancements are intersecting with sustainability mandates to alter product design and manufacturing processes. The industry is moving beyond simple material properties toward engineered systems that balance performance, cost, and end-of-life considerations across the value chain.
Advanced process simulation software models the meltblowing process to predict fiber distribution and filtration efficiency. Leading producers of high-end filtration media are rapidly adopting this technology to accelerate product development cycles. This software-driven approach is virtualizing the costly and time-consuming physical trial-and-error process, enabling faster creation of materials optimized for specific applications like HEPA filters.
The EU's Corporate Sustainability Reporting Directive (CSRD) expands disclosure requirements for large companies. This regulation is forcing nonwoven producers and their customers to provide detailed, audited data on their supply chain's environmental and social impact. The hygiene segment, in particular, now prioritizes suppliers who can provide transparent lifecycle assessment data to meet the reporting obligations of their multinational clients.
A shift from transactional purchasing to strategic supplier partnerships is evident in the medical and hygiene sectors. Large consumer goods and medical device manufacturers are reducing their number of suppliers, favoring those who can offer supply chain security and joint product development. This trend is most visible in North America and Europe, where hygiene product giants seek to de-risk supply chains for critical components.
PP Nonwovens Market Segmentation
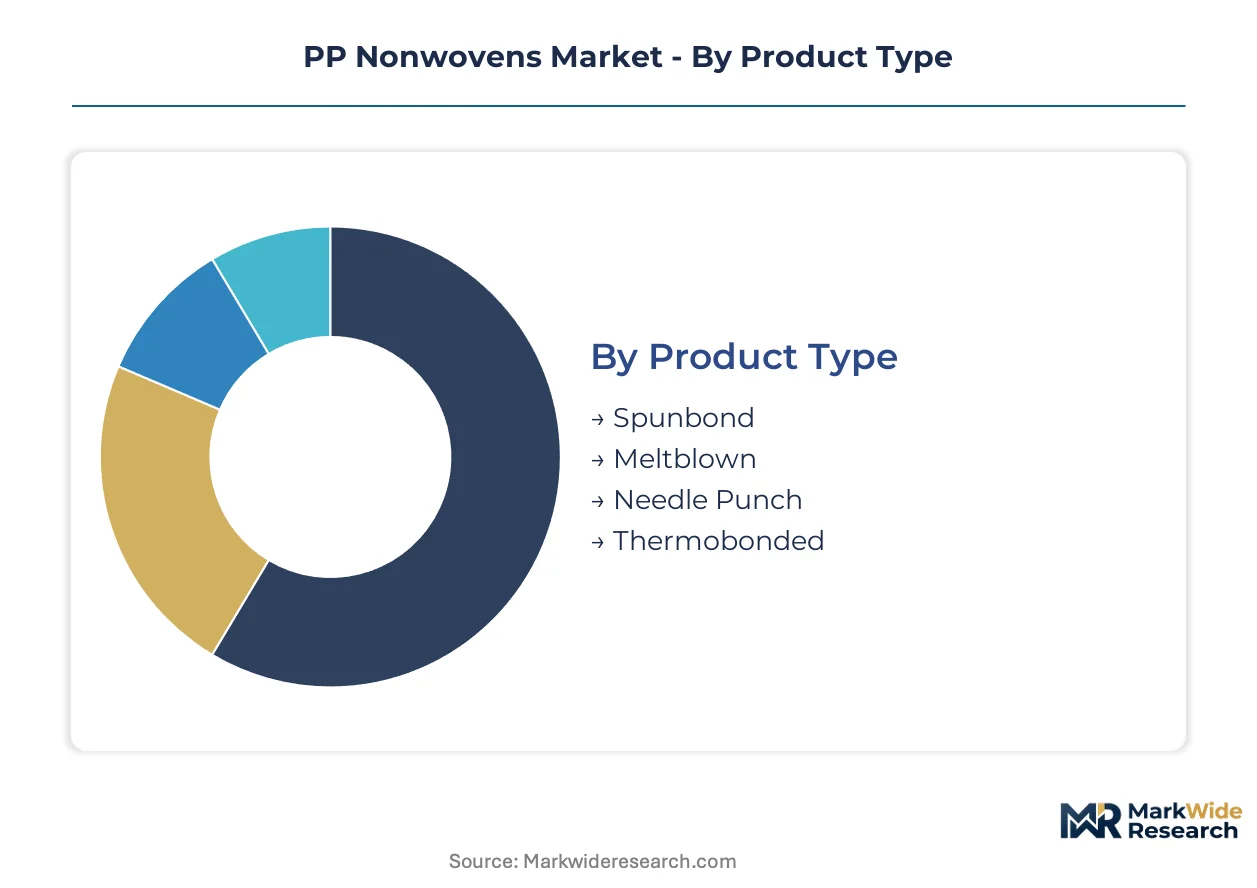
Segmenting the PP nonwovens market reveals the intricate interplay of material science, application demands, and supply chain structures. This analysis highlights specific areas of strategic focus for producers, guiding investment in specialized capacities or high-volume production lines.
Product Type:
The market's product type segmentation highlights the diverse manufacturing processes that impart specific material characteristics to polypropylene nonwovens.
- Spunbond:This widely adopted method produces strong, durable, and cost-effective fabrics, often favored for high-volume applications. Demand concentrates in the hygiene sector, driven by the need for soft, yet resilient materials in products like diapers and feminine care items.
- Meltblown:Characterized by extremely fine fibers, meltblown nonwovens deliver superior filtration efficiency and excellent barrier properties. Demand is concentrating in high-performance filtration media, driven by rising air quality concerns in countries like Vietnam and Indonesia.
- Needle Punch:Mechanically bonded fibers create robust, durable fabrics primarily used in geotextiles and specific automotive interior applications.
- Thermobonded:Heat-bonded fibers offer enhanced softness and bulk, finding applications in hygiene top sheets and various medical dressings.
Spunbond holds installed capacity. Meltblown is rotating up the share rankings.
Application:
The application segments delineate the primary end-uses that leverage polypropylene nonwovens' diverse functional properties across various industries.
- Hygiene:This segment represents the largest volume consumption, requiring nonwovens with properties like absorbency, softness, and liquid repellency. Demand is concentrating in emerging markets like India, fueled by expanding domestic personal care and healthcare markets.
- Filtration:Nonwovens are critical for air and liquid purification systems, demanding materials capable of high-efficiency particle capture. Demand is concentrating in industrial and HVAC systems, driven by stricter environmental regulations in Europe.
- Medical:PP nonwovens provide sterile barriers for surgical gowns, drapes, and masks, adhering to stringent regulatory standards like the EU's MDR.
- Geotextiles:Durable polypropylene nonwovens are essential for soil stabilization, drainage, and erosion control in large-scale civil engineering projects.
The hygiene segment continues to drive significant volume. Filtration applications exhibit the steepest expansion trajectory.
End User:
Customer type segmentation reveals the specific industries that integrate PP nonwovens into their products and services, reflecting distinct material requirements.
- Healthcare:This sector consumes nonwovens for medical devices, protective apparel, and wound care products, prioritizing sterility and barrier performance. Demand concentrates in regions with aging populations and robust healthcare infrastructure, such as Germany and Japan.
- Construction:Utilizes geotextiles for infrastructure development, including roads, railways, and landfills, requiring high strength and durability. Demand is concentrating in large-scale public works projects, driven by government infrastructure spending.
- Agriculture:Nonwovens are employed for crop covers, weed control, and protective fabrics, enhancing yield and protecting produce.
- Automotive:PP nonwovens contribute to interior components, sound insulation, and various filtration systems within vehicles.
Healthcare and construction sectors represent the largest consumption bases. Automotive applications are gaining traction due to lightweighting trends.
Distribution Channel:
The distribution channel analysis outlines the primary pathways through which polypropylene nonwovens reach their diverse end-users, influencing market access and pricing.
- Direct Sales:This channel is favored by large manufacturers for high-volume orders and specialized product requirements, fostering close supplier-customer relationships. Demand concentrates for multinational hygiene product manufacturers, ensuring supply chain security and joint product development.
- Distributors:These intermediaries provide regional market access and inventory management, serving a broad base of smaller and mid-sized customers. Demand is concentrating in fragmented markets with diverse customer bases, such as construction and agriculture.
- Wholesalers:These entities aggregate products from multiple manufacturers for bulk resale, primarily to smaller businesses and retailers.
- Online Retail:An emerging channel for specialized products and smaller quantities, offering convenience and broader market reach, particularly for niche applications.
Direct sales remain critical for strategic partnerships. Online retail is expanding its footprint for niche products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side dynamics for polypropylene nonwovens are undergoing significant shifts, with manufacturing capacity increasingly concentrating in specific geographies. This concentration reflects strategic investments driven by government incentives and evolving application demands. Key regions are now positioning themselves as major production hubs for various PP nonwoven product types.
India
Demand for hygiene products and healthcare applications drives significant investment in India's PP nonwovens sector. The Indian PLI scheme actively supports domestic manufacturing, accelerating capacity expansion. This government initiative positions states like Gujarat as emerging centers for high-volume spunbond production.
China
China's manufacturing capacity expansion is fundamentally reshaping global supply dynamics for polypropylene nonwovens. The government's industrial policies prioritize advanced material production and export. Coastal provinces like Jiangsu and Zhejiang are seeing rapid development of both spunbond and meltblown facilities.
Germany
Germany's healthcare sector demands premium PP nonwovens for medical devices and high-performance filtration. The EU's Medical Device Regulation (MDR) mandates stringent quality and safety standards for these critical materials. Specialist producers in regions like North Rhine-Westphalia focus on advanced meltblown media for demanding applications.
United States
The United States market requires high-performance nonwovens for medical devices and specialized industrial applications. US FDA requirements for skin-contact materials directly influence material selection for healthcare products. Manufacturers in the Southeast, particularly around North Carolina, focus on advanced materials for automotive and filtration end-uses.
Vietnam
Vietnam experiences rising demand for advanced filtration media due to industrialization and air quality concerns. The country's trade policies encourage foreign direct investment in manufacturing. Industrial zones near Ho Chi Minh City are attracting investment in specialized meltblown capacity to serve regional markets.
PP Nonwovens Market Key Industry Players
Global-scale manufacturers and specialized technical producers broadly split the PP nonwovens market. This market structure reflects a clear divergence between high-volume commoditized segments and high-value niche applications. Companies pursue competitive advantages through either extensive capacity expansion for cost leadership or targeted product differentiation for performance. Strategic partnerships and technology licensing are common competitive moves to secure supply chains and accelerate innovation.
At the scale-driven end of the market, Berry Global Group, Inc. exemplifies a multinational player leveraging extensive capacity for hygiene product manufacturers. Germany-based Freudenberg Group occupies a position as a specialist in high-performance materials for automotive and filtration applications, showcasing differentiation through technical expertise. Toray Industries, Inc., a Japan-based corporation, represents an archetype of advanced material science, utilizing its spunbond and meltblown technologies for diverse industrial applications.
| Leading Market Players |
|---|
| Berry Global Group, Inc |
| Kimberly-Clark Corporation |
| DuPont de Nemours, Inc. |
| Freudenberg Group |
| Ahlstrom-Munksjo Oyj |
| Avgol Nonwovens |
| Toray Industries, Inc |
| Fibertex Nonwovens A/S |
| Suominen Corporation |
| Others |
Cost & Logistics Intelligence
Polypropylene resin volatility, a core risk vector, dictates both pricing tier spreads and the overall supply chain shape for PP nonwovens. This fundamental commodity fluctuation influences material costs for all producers, from high-volume spunbond to specialized meltblown manufacturers.
Pricing Analysis
The EU's Medical Device Regulation (MDR) dictates the pricing tier structure for medical-grade PP nonwovens. Pricing operates on a hybrid model, combining contract-based long-term offtake for large hygiene manufacturers with commodity spot pricing for smaller, less specialized orders. Price differentiation stems from certification level, particularly for materials requiring MDR compliance, and volume scale. Pricing pressure intensifies in the commoditized spunbond segment due to raw material volatility. The hygiene segment exhibits the highest price sensitivity, while medical and high-performance filtration applications demonstrate lower sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage working capital across the PP nonwovens value chain. Geographic supply concentration centers on China, India, and Germany for varied product types. The industry relies heavily on polypropylene resin as its primary raw material. Commodity price volatility in petrochemical markets remains a structural risk, impacting production costs and profitability. Downstream channels include direct sales to multinational hygiene brands and distributors serving fragmented construction and agriculture markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment, particularly in medical and high-performance applications, frames the PP nonwovens market as a defensive-moat story. This structural advantage creates significant barriers to entry for new competitors.
For Market Incumbents:Harden core positions by investing in specialized meltblown capacity, particularly for advanced filtration media. Secure long-term polypropylene resin contracts to mitigate commodity price volatility, a persistent threat to margins. Prioritize certification investments to meet evolving regulatory standards like the EU MDR. Expand R&D efforts into mono-material PP nonwovens for circular economy mandates, leveraging existing technical expertise.
For New Entrants and Emerging Players:Pursue niche applications like automotive sound insulation or advanced filtration in Southeast Asia. The underpenetrated Southeast Asian market offers specific growth opportunities for high-performance meltblown filter media. A viable go-to-market angle involves strategic partnerships with local distributors or technology licensing from established players. Focus on specialized, high-margin segments where technical barriers to entry are higher, avoiding direct competition in commoditized spunbond production.
For Investors and Strategic Acquirers:The EU Medical Device Regulation reshapes the acquisition landscape, favoring companies with established compliance and certified production. Long-term viability in this market remains strong, driven by consistent demand from hygiene and medical sectors. Acquisition targets should include mid-sized producers possessing specialized meltblown capabilities or a strong regional presence in growth markets like India. The consolidation within the high-performance meltblown segment serves as a key signal to watch for strategic investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Specialized Meltblown Capacity | Expands product portfolio into high-margin filtration and medical applications, aligning with EU MDR standards. |
| Secure Long-Term Raw Material Contracts | Mitigates polypropylene resin price volatility, stabilizing production costs for Berry Global Group. |
| Develop Mono-Material PP Nonwovens | Addresses European circular economy mandates, positioning Freudenberg Group for sustainable growth. |
| Expand into Southeast Asian Filtration | Captures underpenetrated market demand for advanced filter media in Vietnam and Indonesia. |
| Form Strategic Partnerships in India | Leverages government incentives like the PLI scheme to accelerate capacity expansion for Toray Industries. |
Research Approach
Desk research of industry association reports, company annual filings, government trade databases, and academic journals preceded structured interviews with nonwoven manufacturers, raw material suppliers, hygiene product brands, and medical device producers. This approach combined primary insights with secondary validation. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and market coverage.
Assumptions regarding stable macroeconomic conditions and consistent technological progression were held fixed across the analysis window. The forecast framework integrated quantitative modeling to project market growth across key segmentation dimensions, including product type, application, end-user, distribution channel, and fiber diameter. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included polypropylene resin prices and evolving regulatory changes like the EU MDR.
Sensitivities concentrate around unforeseen shifts in raw material supply and rapid technological disruptions. Forecasts reflect a comprehensive set of assumptions, but are not immutable. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Absorbable Nonwoven Textiles Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Meltblown Fabrics Market