
 Global Vinyl Flooring Market | 2026-2036
Global Vinyl Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vinyl Flooring Market Foresight
Market Context
Southeast Asia's manufacturing corridor is fragmenting as new vinyl flooring capacity comes online across Vietnam, Thailand, and Malaysia. Mohawk Industries leverages its integrated supply chain to sustain cost leadership in rigid core production. Tarkett anchors European sustainability positioning through bio-attributed PVC sourcing and closed-loop recycling infrastructure. Shaw Industries Group competes on domestic manufacturing scale, operating multiple facilities across the southeastern United States.
Technical Definition and Segments
Vinyl flooring comprises synthetic polymer-based surfacing materials, typically formulated from polyvinyl chloride resin combined with plasticizers, stabilizers, and mineral fillers, then calendered or extruded into sheets, tiles, or planks with wear-layer thicknesses ranging from 6 mil to 40 mil for commercial durability. Its primary commercial purpose spans cost-effective, moisture-resistant surfacing for high-traffic interior environments where maintenance simplicity and design versatility outweigh natural material premiums. Luxury vinyl tile commands the dominant margin pool due to superior realism and installation flexibility, while vinyl plank extends fastest across residential channels propelled by click-lock floating systems. Sheet vinyl occupies mature institutional segments where seamless hygiene and budget constraints govern procurement decisions.
Regulatory Environment
REACH in Europe and California's Proposition 65 in the United States restrict ortho-phthalate plasticizer content, compelling reformulation toward terephthalate or bio-based alternatives that reshape raw material sourcing strategies. The EU Green Deal and associated CSRD reporting obligations pressure manufacturers to document recycled content percentages and end-of-life recovery pathways. China's GB standards and evolving MEE enforcement on PVC production emissions add compliance layers for suppliers serving Asian markets. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized or regionalized product portfolios minimize certification burden.
Market Dynamics
REACH compliance deadlines and California's Proposition 65 enforcement are forcing simultaneous reformulation of plasticizer chemistry across all major production regions, compressing margins while opening first-mover advantages for bio-attributed material suppliers.
Growth Catalysts
- Residential renovation intensity:North American homeowners are replacing worn hardwood and carpet with luxury vinyl tile formats that offer superior moisture resistance and installation speed.
- MEE emission controls:China's Ministry of Ecology and Environment enforcement is accelerating consolidation toward integrated producers capable of captive PVC resin and captive plasticizer production.
- Click-lock floating systems:Mechanical installation technology eliminates adhesive labor costs and subfloor preparation, expanding vinyl plank adoption among DIY renovators and multifamily developers.
Market Restraints
- Ortho-phthalate substitution costs:Terephthalate and bio-based plasticizers carry 15-40% raw material premiums versus legacy DINP formulations, compressing compounder margins.
- Vietnam-Thailand capacity fragmentation:New extrusion lines across Southeast Asia are dispersing volume concentration that previously anchored pricing power with integrated multinationals.
- Ceramic tile price competition:Glazed porcelain from Spanish and Italian producers retains specification preference in premium commercial segments where lifecycle cost analysis governs procurement.
Strategic Opportunities
- India commercial real estate corridors:Bangalore, Hyderabad, and Pune office construction is generating specification demand for 20+ mil wear-layer products with acoustic underlayment integration.
- EU Green Deal circularity mandates:CSRD reporting obligations and recycled content targets are creating premium positioning for producers with closed-loop collection infrastructure.
- Digital print convergence:High-definition inkjet decoration combined with embossed-in-register texture is narrowing the realism gap with natural stone and wood at one-third the installed cost.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise in bio-plasticizer compatibility and stabilizer synergy is concentrating among retiring specialists at legacy PVC compounders.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of FloorScore, Greenguard, and EU Ecolabel approvals extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vinyl Flooring Market |
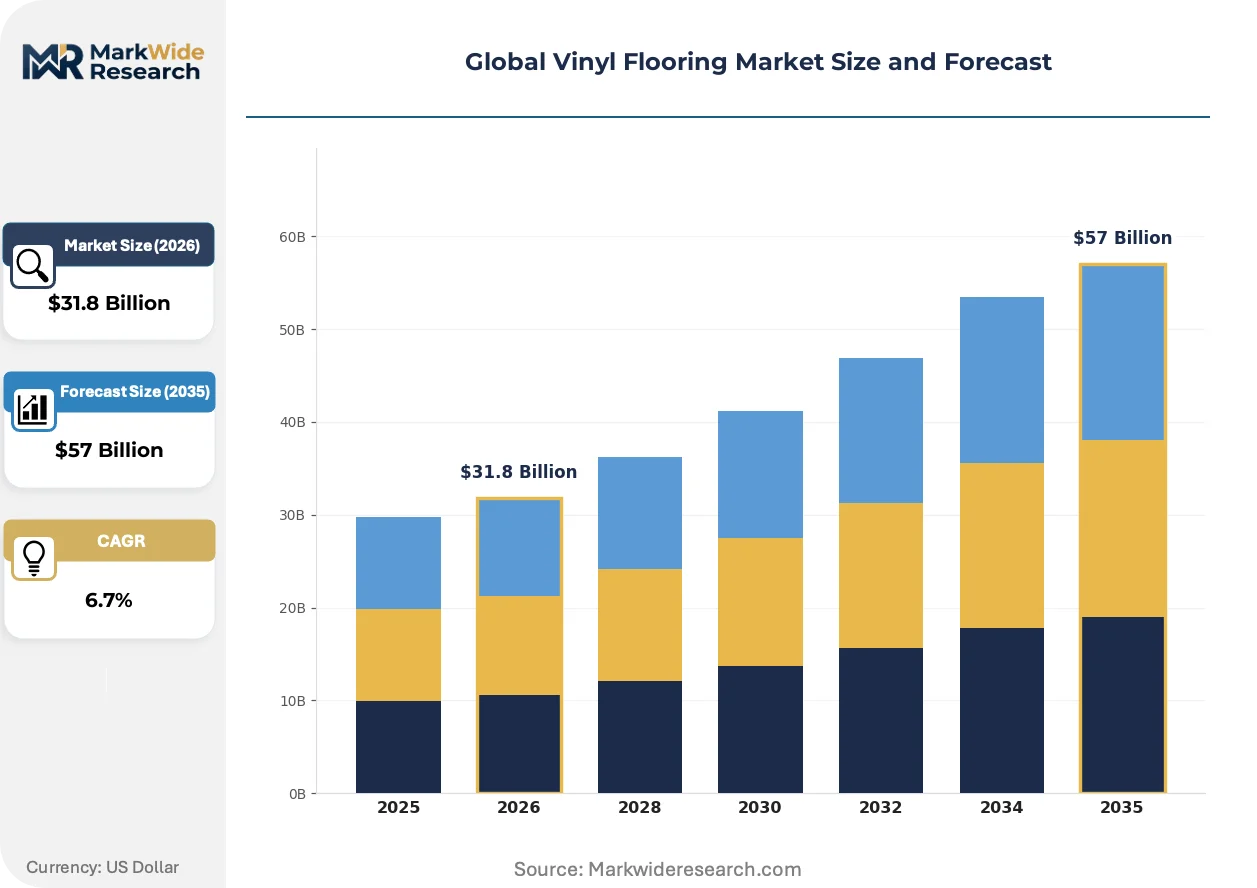
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tile, Sheet Vinyl, Vinyl Plank, Composite Vinyl Application: Commercial Spaces, Institutional Buildings, Hospitality Venues, Educational Facilities, Residential Complexes Installation Method: Glue-Down, Loose Lay, Click Lock, Self-Adhesive End User: Property Developers, Facility Managers, Interior Designers, Contractors, Retail Chain Operators |
| Companies Covered | Mohawk Industries, Shaw Industries Group, Tarkett, Armstrong Flooring, Mannington Mills, Gerflor Group, Forbo Holding, Interface, Congoleum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vinyl Flooring Market Shifts & Advancements
Digital decoration technology and rigid core construction are compressing the performance gap between synthetic and natural materials, while regulatory chemistry mandates are restructuring raw material procurement across all major supply basins.
Stone-plastic composite and wood-plastic composite rigid cores are rendering obsolete traditional flexible vinyl sheet and glue-down tile formats in residential replacement applications. Multifamily developers and hospitality renovators specify SPC exclusively for its dimensional stability over imperfect subfloors. The technology is rendering obsolete the skilled labor premium previously commanded by floating laminate and engineered hardwood installation.
REACH Annex XVII restrictions on ortho-phthalates are compelling systematic reformulation of plasticizer portfolios toward terephthalate, adipate, and bio-based alternatives. Compounders serving European markets must validate migration testing protocols and update safety data sheets across entire product ranges. Rigid core producers with backward integration into PVC resin production are responding fastest due to captive formulation control.
Specification decisions increasingly flow through consolidated national flooring distributors rather than fragmented independent retailers. Large commercial contractors in the United States and Germany now source directly from mill-direct programs with dedicated project management support. This channel consolidation is most visible in healthcare and education verticals where national account pricing and single-source accountability override local supplier relationships.
Global Vinyl Flooring Market Segmentation
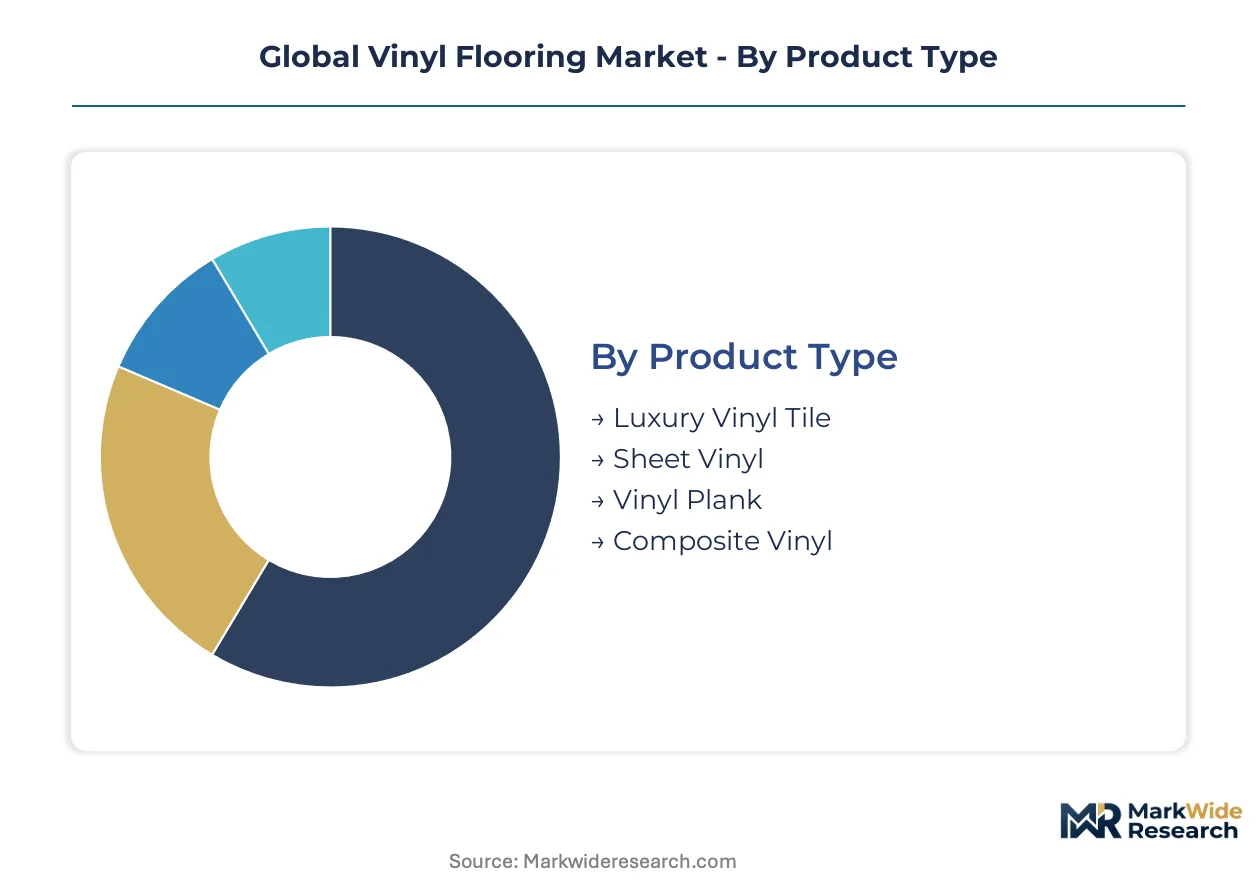
Vinyl flooring segmentation reveals divergent margin structures across product formats and installation complexity. Service intensity varies dramatically between floating click-lock systems and traditional glue-down specifications, reshaping distributor training investments and contractor loyalty programs.
Product Type:
After-sales service intensity escalates with product complexity, as rigid core formats demand specialized subfloor assessment and acclimation protocols that flexible sheet products rarely require.
- Luxury Vinyl Tile:Multi-layer construction fuses a high-definition printed film between transparent wear layer and vinyl core, achieving stone and wood realism at reduced installed cost. Demand concentrates in US residential renovation channels where homeowners prioritize moisture resistance for kitchens and bathrooms alongside rapid installation turnaround.
- Vinyl Plank:Elongated plank dimensions replicate hardwood aesthetics through embossed-in-register surface texture and beveled edges. US multifamily developers specify vinyl plank exclusively for unit turnovers, as click-lock floating systems eliminate adhesive curing delays and accelerate lease-up timelines.
- Sheet Vinyl:Continuous rolled format delivers seamless hygiene surfaces through heat-welded installation, dominating healthcare and food service specifications where infection control governs procurement.
- Composite Vinyl:Stone-plastic composite and wood-plastic composite cores provide dimensional stability over imperfect substrates, displacing traditional flexible vinyl in residential replacement applications.
Luxury vinyl tile holds the largest share; momentum sits with vinyl plank.
Application:
Cost tier differentiation separates specification-grade products with extended warranties from value-engineered alternatives, with procurement authority residing at distinct organizational levels across segment types.
- Commercial Spaces:Office lobbies and retail environments demand 20+ mil wear layers with acoustic underlayment integration to satisfy lease requirements and foot traffic durability. India's Bangalore and Hyderabad office corridors generate accelerating specification volume for premium formats.
- Residential Complexes:Single-family and multifamily housing replacement cycles drive volume concentration in North American renovation markets, with DIY-friendly installation systems capturing share from professional-only alternatives.
- Institutional Buildings:Government and municipal facilities prioritize lifecycle cost analysis and domestic content requirements over initial acquisition price, extending procurement cycles.
- Hospitality Venues:Hotel renovation schedules demand rapid installation with minimal operational disruption, favoring loose lay and floating systems over adhesive-dependent formats.
- Educational Facilities:K-12 and university construction balances budget constraints against durability requirements, with national account pricing consolidating purchasing authority among large district networks.
Commercial spaces command premium pricing; residential complexes are expanding most quickly.
Installation Method:
Customer type stratification separates professional contractors from DIY renovators, with installation complexity determining addressable audience and margin structure for each format.
- Click Lock:Mechanical interlocking edges enable floating installation without adhesive, subfloor preparation, or specialized tools. US big-box retailers and online channels concentrate demand among homeowner renovators seeking weekend project completion.
- Glue-Down:Full-spread adhesive application delivers permanent dimensional stability for commercial environments with heavy rolling loads and point-source pressure requirements.
- Loose Lay:Friction-backed systems rely on perimeter anchoring and weight distribution, serving hospitality renovation where rapid deployment and future access outweigh permanent fixation.
- Self-Adhesive:Pre-applied pressure-sensitive backing simplifies installation for small-scale residential applications, though temperature sensitivity limits climate applicability.
Click lock dominates residential volume; glue-down retains commercial specification preference.
End User:
Supply concentration among integrated manufacturers with captive resin production favors large-scale purchasers capable of committing to volume contracts and mill-direct programs.
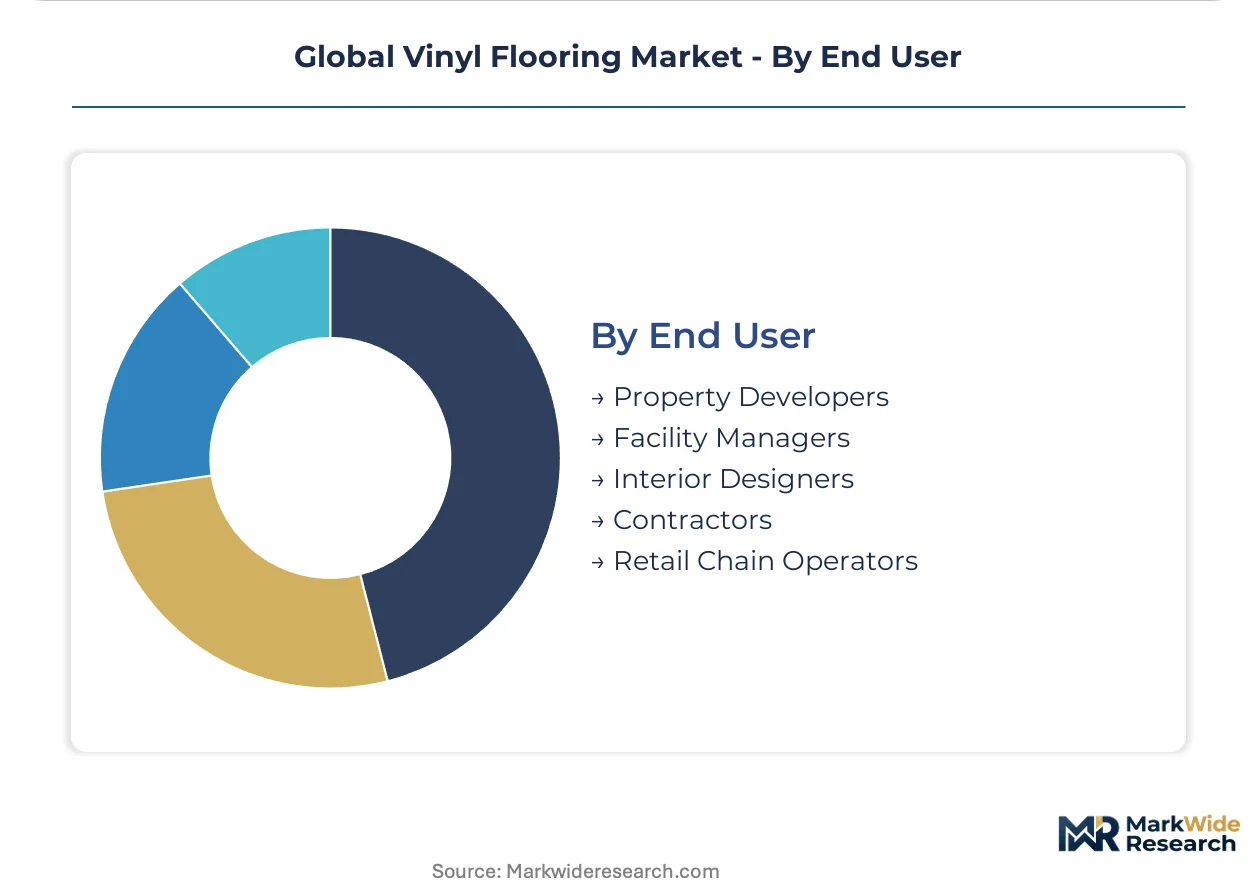
- Property Developers:Multifamily and mixed-use project pipelines in US Sun Belt metros specify vinyl flooring for cost certainty and installation speed, with national developers consolidating procurement through preferred supplier agreements.
- Contractors:Commercial flooring installation firms influence product selection through labor cost calculations, with click-lock systems reducing crew size and project duration versus traditional methods.
- Facility Managers:Corporate and healthcare real estate operations prioritize lifecycle maintenance protocols and replacement accessibility over initial material specifications.
- Interior Designers:Specification consultants bridge aesthetic requirements with performance standards, increasingly sourcing through consolidated national distributors with project management support.
- Retail Chain Operators:Rollout programs for store refresh cycles demand consistent national availability and dedicated account management, favoring suppliers with multi-facility manufacturing footprints.
Property developers represent the largest procurement volume; interior designers are gaining specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of phthalate restrictions under the Toxic Substances Control Act anchors United States regulatory pressure, while divergent compliance frameworks across Germany, China, India, and Vietnam reshape regional sourcing strategies and manufacturing location decisions.
United States
Residential renovation demand in Texas and Florida Sun Belt metros drives luxury vinyl plank specification for multifamily unit turnovers. EPA TSCA Section 6 restrictions on ortho-phthalates compound with California Proposition 65 litigation risk to accelerate bio-based plasticizer adoption. Southeast manufacturing clusters in Georgia and Tennessee concentrate rigid core production capacity serving big-box retail distribution.
Germany
Commercial real estate refurbishment in Frankfurt and Munich office corridors sustains specification-grade vinyl tile demand with 20+ mil wear layers. ECHA REACH Annex XVII enforcement mandates systematic DINP substitution, pushing compounders toward terephthalate and bio-attributed alternatives. The Ruhr industrial basin hosts closed-loop recycling infrastructure development aligned with EU Green Deal circularity targets.
China
Urban housing cluster development in Chengdu and Wuhan generates volume demand for cost-optimized SPC flooring formats. MEE emission controls on PVC resin production are consolidating supply toward integrated producers with captive VCM and plasticizer facilities. The Yangtze River Delta manufacturing belt is absorbing technology transfer for high-definition digital print decoration systems.
India
Commercial office construction in Bangalore, Hyderabad, and Pune corridors is creating specification pull for acoustic-underlayment-integrated vinyl systems. BIS certification requirements for flooring products are extending compliance timelines for imported formulations. Gujarat chemical manufacturing zones are attracting plasticizer compounders seeking proximity to PVC resin supply and export port access.
Vietnam
New extrusion capacity in Binh Duong and Dong Nai provinces is fragmenting Southeast Asian supply concentration previously centered on Thai producers. The country's national environmental regulator is tightening industrial emission standards for calendering operations. Ho Chi Minh City logistics hubs are enabling direct container export to US West Coast distribution channels.
Global Vinyl Flooring Market Competitive Landscape
Integrated resin producers and specialized flooring fabricators split the market between cost-engineered volume plays and specification-driven premium positioning. Consolidation favors multinationals with backward integration into PVC resin and captive plasticizer production, while regional extrusion specialists compete on lead-time flexibility for distributor private-label programs. Two archetypes dominate: vertically integrated chemical-flooring hybrids controlling formulation cost, and design-focused brand houses commanding specification premiums through digital print realism. Capacity expansion and M&A-driven geographic extension represent the dominant competitive vectors as players defend margin position against Southeast Asian cost competition.
Among North American integrated manufacturers, Mohawk Industries and Shaw Industries Group exemplify the chemical-flooring hybrid archetype through in-house resin and rigid core production. Tarkett occupies a position representing European sustainability-focused brand positioning with bio-attributed material sourcing and closed-loop collection infrastructure development.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries Group |
| Tarkett |
| Armstrong Flooring |
| Mannington Mills |
| Gerflor Group |
| Forbo Holding |
| Interface |
| Congoleum |
| Others |
Supply & Pricing Matrix
Overcapacity in Vietnam's extrusion corridor is compressing spot pricing for rigid core formats while simultaneously eroding the pricing power that integrated Thai producers previously commanded in Southeast Asian spot markets.
Pricing Analysis
Geographic price spreads between US-manufactured rigid core and Southeast Asian imports now exceed freight-adjusted differentials, reflecting quality-tier separation rather than pure cost arbitrage. Three-tier pricing structure across premium, standard, and economy levels stratifies by wear-layer thickness and certification grade, with FloorScore-certified products commanding sustained premiums. Pricing pressure stems from Vietnam-Thailand capacity fragmentation dispersing volume concentration that anchored supplier leverage. National flooring distributors exhibit lowest price sensitivity due to mill-direct volume commitments, while independent retailers face margin compression from big-box channel competition.
Supply Chain Analysis
Tariff exposure between Vietnam and the United States dominates supply chain risk calculations for Southeast Asian extrusion specialists serving North American distribution. Manufacturing gravity centers on China, Vietnam, and Thailand for calendering and extrusion operations, with Georgia and Tennessee anchoring US rigid core production. PVC resin and plasticizer feedstocks draw from integrated petrochemical complexes in the US Gulf Coast and China's Yangtze River Delta. Single-source vulnerability concentrates in digital print decoration equipment supply from Italian and German specialists. Distribution runs through consolidated national flooring distributors and big-box retail channels rather than fragmented independent networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII ortho-phthalate restrictions and EPA TSCA Section 6 enforcement are forcing simultaneous chemistry reformulation across all major production regions, creating first-mover advantages for bio-attributed material suppliers and compressing laggard margins.
For Market Incumbents: Pre-empt Southeast Asian cost competition by accelerating captive bio-plasticizer production in US Gulf Coast facilities, while consolidating specification-grade volume through exclusive distributor partnerships that lock out emerging Vietnamese extruders from premium commercial channels. For New Entrants and Emerging Players: Mid-market commercial buildings in India's Bangalore and Hyderabad corridors represent the most penetrable entry point, as acoustic-underlayment-integrated systems face limited domestic supply and BIS certification timelines disadvantage established importers; pursue mill-direct relationships with national developers bypassing distributor markups. For Investors and Strategic Acquirers: Capital is best deployed toward rigid core specialists with backward integration into PVC resin and captive plasticizer production, as formulation control accelerates regulatory compliance and sustains margin compression resistance; watch for MEE enforcement intensity in China as consolidation trigger signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Plasticizer Production | Captive supply of terephthalate alternatives accelerates REACH and EPA compliance while insulating margin from raw material premiums. |
| Closed-Loop Recycling Infrastructure Development | Ruhr basin collection networks align with EU Green Deal circularity mandates and CSRD reporting obligations for recycled content documentation. |
| Digital Print Decoration Technology Licensing | High-definition inkjet systems from Italian specialists narrow realism gaps with natural materials at reduced installed cost. |
| Mill-Direct National Account Programs | Consolidated distributor relationships with US multifamily developers secure volume commitment and accelerate lease-up timelines. |
| Acoustic Underlayment Integration | 20+ mil wear-layer products with sound-dampening cores capture specification demand in India's commercial office construction corridors. |
Research Methodology
The analysis maps rigid core, luxury vinyl tile, sheet vinyl, and composite vinyl segments, each validated through plant managers at integrated manufacturers, procurement leads at national flooring distributors, commercial contractor installation firms, and technical R&D directors at plasticizer compounders. Primary interview insights triangulate against customs and trade data, SEC 10-K filings, ECHA REACH registration databases, and industry association capacity surveys. Bottom-up volume builds from identified production facilities reconcile with top-down demand estimates derived from construction activity indices and renovation spending patterns.
Model assumptions hold fixed the regulatory compliance trajectory across REACH, EPA TSCA, and China's MEE enforcement intensity, while varying raw material cost scenarios and capacity utilization rates across the projection horizon. Segmentation dimensions include product format, installation method complexity, end-use application, and regional production hub classification. CAGRs derive from slope analysis of normalized volume trends adjusted for identified inflection points in substitution dynamics. Forecast inputs incorporate PVC resin capacity expansion timelines and digital print technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in residential renovation spending, commercial construction lending availability, or freight rate volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology transfer rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Bamboo Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market