
 United States Floor Covering Market | 2026-2036
United States Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
United States Floor Covering Market Analytics
Consolidation among national homebuilders and multifamily developers is repositioning procurement power toward volume-contract arrangements. Mohawk Industries leverages its integrated manufacturing footprint to serve these consolidated buyers with consistent spec-grade output. Shaw Industries anchors its position through captive carpet fiber production and direct-to-builder logistics networks. Floor & Decor Holdings competes by controlling the specialty retail channel and concentrating inventory depth in high-growth metropolitan areas.
Floor covering encompasses finished surfacing materials installed over structural subfloors, with products specified by wear-layer thickness, dimensional stability coefficients, and slip-resistance ratings for commercial applications. These materials provide thermal insulation, acoustic dampening, and aesthetic finish in built environments across residential and non-residential construction. Vinyl products lead volume due to water-resistant polymer composition and floating installation compatibility, while hardwood commands premium positioning through solid-sawn construction and refinishing longevity. Carpet maintains share in multifamily residential and hospitality segments where acoustic performance and first-cost economics dominate specification criteria.
The EPA regulates composite wood products under TSCA Title VI formaldehyde emission standards, directly limiting substrate options for laminate and engineered hardwood manufacturers. California Air Resources Board (CARB) Phase 2 requirements and OSHA workplace silica exposure rules during installation further constrain product formulation and contractor practices. Stakeholders must monitor evolving state-level extended producer responsibility legislation and low-VOC certification programs as these frameworks increasingly determine specification eligibility in public and institutional projects.
Market Dynamics
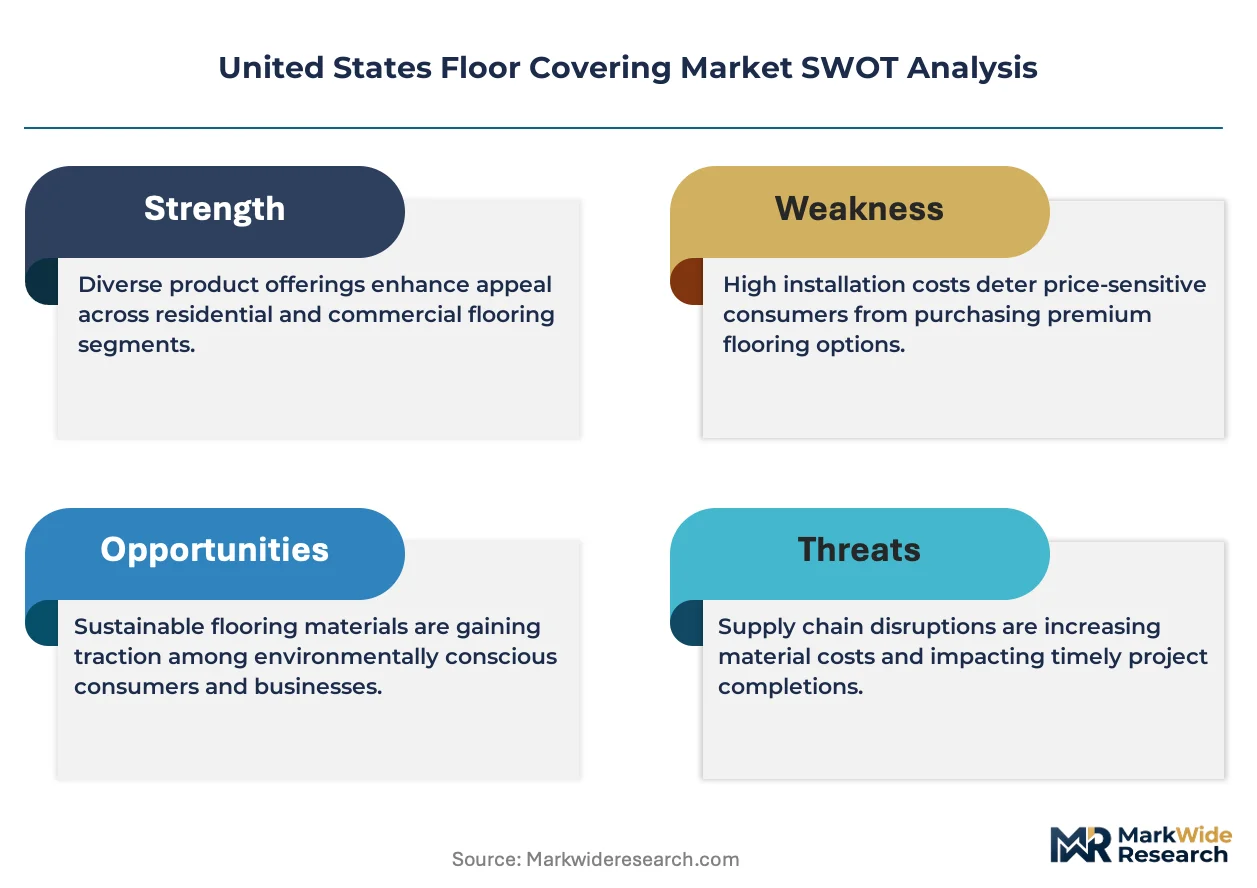
Consolidation among national homebuilders and multifamily developers is concentrating procurement power into volume-contract arrangements, forcing manufacturers to restructure distribution around direct-to-builder logistics and captive fiber production.
Growth Catalysts
- Sun Belt Housing Construction:New residential development in Texas and Florida outpaces national averages, generating sustained demand for spec-grade flooring materials in single-family and multifamily units.
- EPA TSCA Title VI Compliance:Stricter formaldehyde emission standards for composite wood products are accelerating substrate innovation in engineered hardwood and laminate categories.
- Luxury Vinyl Technology:Water-resistant polymer composition and floating installation compatibility are displacing traditional materials in residential renovation projects.
Market Restraints
- Petrochemical Feedstock Volatility:Vinyl flooring production depends on PVC resin pricing, which fluctuates with crude oil markets and chlor-alkali capacity constraints.
- Silica Exposure Regulation:OSHA workplace rules during tile and stone installation increase contractor compliance costs and liability exposure.
- Hardwood Substitution Pressure:Premium solid-sawn products face competition from engineered alternatives and ceramic tile in moisture-prone applications.
Strategic Opportunities
- Low-VOC Certification Programs:California's extended producer responsibility legislation and indoor air quality mandates are creating specification advantages for compliant manufacturers in public and institutional projects.
- Direct-to-Builder Channels:Bypassing traditional distribution through captive logistics networks captures margin and secures volume commitments from consolidated national homebuilders.
- Acoustic Performance Specialization:Carpet and underlayment systems targeting multifamily residential and hospitality segments address stricter sound transmission building codes.
Industry Challenges
- Installation Labor Shortage:Skilled flooring mechanics with expertise in floating and glue-down methods are scarce in high-growth metropolitan areas, extending project timelines.
- CARB Phase 2 Documentation:Chain-of-custody certification for composite wood substrates requires extensive supplier auditing and testing protocols.
- Legacy Inventory Systems:Specialty retailers struggle to synchronize SKU depth across high-velocity metropolitan markets with predictive demand signals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Floor Covering Market |
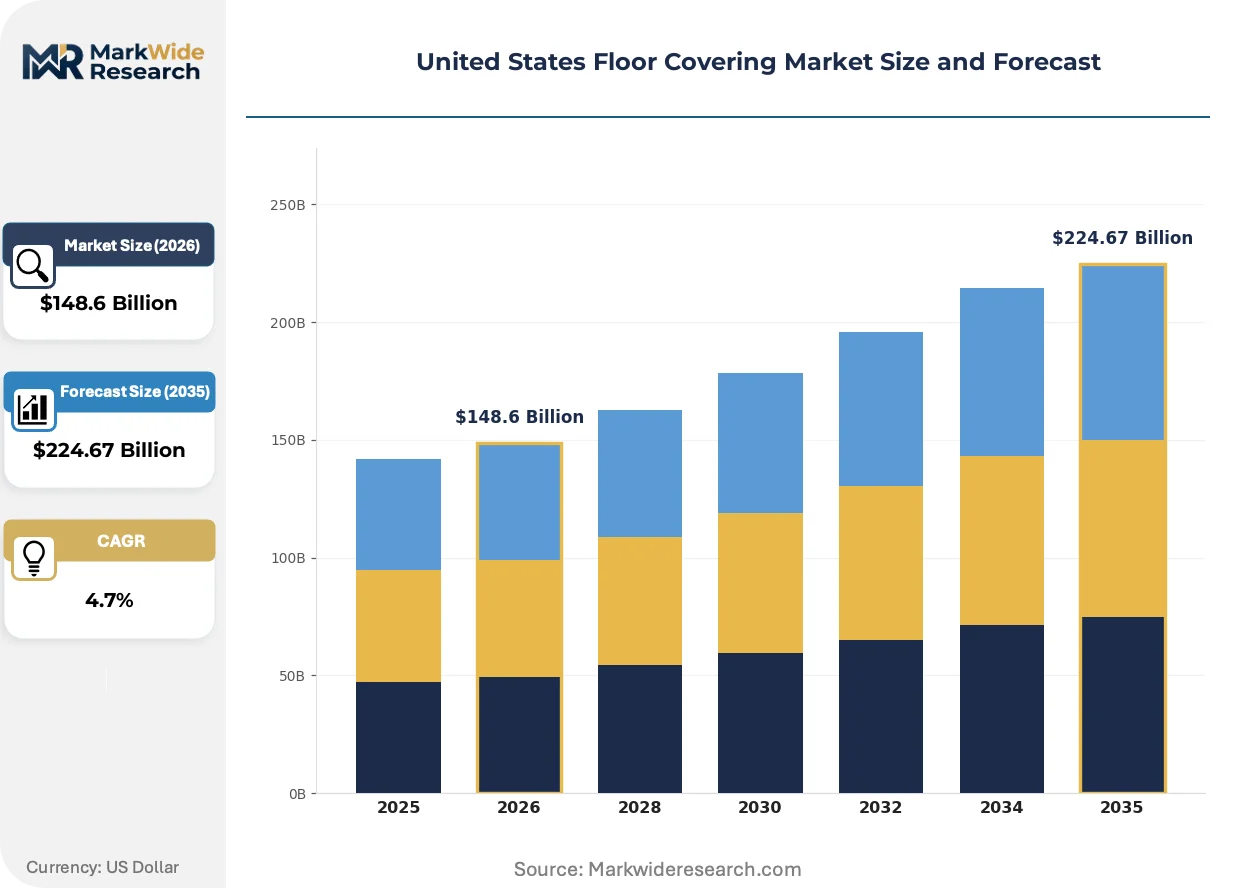
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $224.67 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Laminate, Vinyl, Hardwood Installation Type: Glue-down, Floating, Loose Lay, Nail-down End Use: Residential, Commercial, Industrial, Hospitality Material: Nylon, Polyester, Wood, Rubber |
| Companies Covered | Armstrong Flooring, Floor & Decor Holdings, Mohawk Industries, AFH Products, Mannington Mills, Shaw Industries, Interface, Pergo, Tarkett, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Floor Covering Market Evolving Landscape
Material science advances and regulatory pressure are compressing product development cycles while reshaping how manufacturers align formulation, certification, and channel strategy.
Waterproof core technology is unifying the performance characteristics of laminate and luxury vinyl into rigid composite constructions. National homebuilders specify these hybrid products for whole-house installations to reduce SKU complexity and installation labor. The technology is unifying previously distinct product categories into single-source procurement arrangements.
California's Title 24 building energy standards now incorporate embodied carbon considerations for interior finishes. Flooring manufacturers must document lifecycle emissions and thermal performance metrics to maintain specification eligibility in state-funded projects. Engineered hardwood and cork suppliers are investing in Environmental Product Declarations to satisfy these disclosure requirements.
Renovation-driven purchasing is compressing traditional replacement cycles as homeowners prioritize immediate property value enhancement over deferred maintenance. Big-box and specialty retail channels are expanding in-store visualization tools and sample-to-home programs to capture these discretionary projects. This pattern concentrates in coastal metropolitan areas where housing turnover and equity extraction remain elevated.
United States Floor Covering Market Segmentation
Floor covering procurement patterns diverge sharply across product categories, installation methods, and end-use specifications. Manufacturers structure production capacity and distribution networks around these segment boundaries, with compliance requirements and labor availability further fragmenting competitive positioning.
Product Type:
Supply concentration tilts toward polymer-based products where capital intensity and scale economies favor integrated producers.
- Vinyl:Polymer composition delivers water resistance and dimensional stability across residential and commercial substrates. Demand concentrates in Texas and Florida new construction, where floating installation compatibility reduces skilled labor requirements and accelerates project completion.
- Hardwood:Solid-sawn and engineered constructions command premium positioning through refinishing longevity and aesthetic warmth. California renovation activity and Title 24 compliance documentation are reshaping specification toward certified low-emission engineered alternatives.
- Carpet:Tufted constructions from nylon and polyester fiber systems dominate multifamily and hospitality acoustic specifications.
- Laminate:High-density fiberboard cores with decorative overlays compete on first-cost economics in residential replacement cycles.
Today's leader: Vinyl. Tomorrow's challenger: Engineered hardwood.
Installation Type:
Cost tier differentiation separates premium glue-down specifications from economy floating systems.
- Floating:Click-lock and loose-lay systems eliminate adhesive curing time and subfloor preparation costs. Residential renovation demand in Sun Belt metropolitan areas favors these methods for speed of completion and lower contractor qualification thresholds.
- Glue-down:Direct adhesive bonding delivers maximum dimensional stability and acoustic performance for commercial and high-traffic hospitality applications. OSHA silica exposure rules and volatile organic compound regulations constrain adhesive specification and installer certification requirements.
- Nail-down:Traditional solid hardwood attachment requires seasoned mechanics and seasoned subfloor conditions.
- Loose Lay:Friction-fit polymer systems target temporary and rental property installations.
Volume concentrates in floating methods. Margin concentrates in glue-down specifications.
End Use:
Application requirements dictate performance certification tiers and channel access.
- Residential:Single-family and multifamily new construction plus renovation activity generates the majority of volume. Sun Belt housing starts in Texas and Florida outpace national averages, with spec-grade products specified through national homebuilder volume contracts.
- Commercial:Office, retail, and institutional specifications demand slip-resistance ratings, wear-layer thickness documentation, and extended producer responsibility compliance for public project eligibility.
- Hospitality:Hotels and resorts prioritize acoustic dampening and rapid replacement cycles.
- Industrial:Manufacturing and warehouse facilities specify chemical resistance and static control properties.
Residential commands volume share. Commercial commands specification discipline.
Material:
Customer type and margin structure separate commodity feedstocks from performance-engineered inputs.
- Wood:Solid lumber and engineered substrates face EPA TSCA Title VI formaldehyde emission limits and CARB Phase 2 chain-of-custody documentation. Premium positioning depends on Forest Stewardship Council certification and refinishing cycle longevity.
- Nylon:Polyamide 6 and 6,6 fiber systems deliver superior resilience and stain resistance for commercial carpet specifications. Captive fiber production at major manufacturers secures margin control and consistent dye lot quality.
- Polyester:PET fiber from recycled content targets sustainability-positioned residential segments.
- Rubber:Natural and synthetic compositions serve fitness, healthcare, and industrial anti-fatigue applications.
Maturity favors wood. Steepest expansion trajectory: Nylon in commercial carpet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas generates construction volume that dwarfs most national markets, while California imposes regulatory stringency unmatched elsewhere. These contrasting dynamics produce divergent procurement patterns across American sub-regions.
Texas
Houston and Dallas-Fort Worth metropolitan areas sustain elevated single-family housing starts that outpace national averages. The Texas Department of Licensing and Regulation oversees contractor certification requirements for flooring installation. San Antonio and Austin construction corridors concentrate demand for spec-grade vinyl products in volume-contract arrangements with national homebuilders.
California
Los Angeles and San Francisco renovation activity drives premium hardwood and engineered product specifications. CARB Phase 2 formaldehyde emission standards and Title 24 building energy codes constrain substrate options for laminate manufacturers. San Diego and Sacramento metropolitan markets prioritize low-VOC certification and Environmental Product Declaration documentation for public project eligibility.
Florida
Miami and Tampa housing construction generates sustained demand for water-resistant flooring materials in multifamily developments. The Florida Building Code incorporates wind-load and moisture-resistance requirements that influence product specification. Orlando and Jacksonville retail corridors concentrate specialty flooring distribution capacity serving renovation-driven purchasing patterns.
Georgia
Atlanta anchors southeastern distribution networks with rail and interstate connectivity to Carolinas and Tennessee markets. Georgia Department of Community Affairs administers energy codes that reference federal EPA formaldehyde standards. Savannah and Augusta manufacturing clusters support carpet fiber production and resilient flooring fabrication for regional supply.
Illinois
Chicago metropolitan commercial construction demands slip-resistance documentation and wear-layer certification for office and institutional specifications. Illinois Environmental Protection Agency aligns with federal TSCA Title VI enforcement for composite wood products. Rockford and Peoria industrial corridors maintain legacy manufacturing capacity serving Midwest renovation and replacement cycles.
United States Floor Covering Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. National manufacturers with integrated fiber production and captive logistics networks hold procurement advantages with consolidated homebuilder accounts. Three archetypes dominate: vertically integrated giants controlling raw material through retail, specialty retailers concentrating inventory depth in high-velocity metros, and regional mills serving contractor-direct replacement channels. Competitive moves center on direct-to-builder channel development and waterproof core technology licensing.
Among integrated manufacturers, Mohawk Industries, Shaw Industries, and Armstrong Flooring exemplify scale-driven archetypes. Mohawk represents the vertically integrated model with manufacturing footprint spanning substrate through finished goods. Shaw anchors the captive fiber production approach with direct logistics networks serving national builder accounts. Armstrong occupies a position bridging commercial specification expertise with residential product development. These three entities collectively illustrate how manufacturing scale and channel control determine competitive positioning in volume-contract procurement environments.
| Leading Market Players |
|---|
| Armstrong Flooring |
| Floor & Decor Holdings |
| Mohawk Industries |
| AFH Products |
| Mannington Mills |
| Shaw Industries |
| Interface |
| Pergo |
| Tarkett |
| Others |
Value Network & Pricing Analysis
Waterproof core technology unification is compressing production economics while concentrating supply among integrated polymer compounders and rigid composite fabricators. This manufacturing transition simultaneously reduces per-unit substrate costs and elevates minimum efficient scale thresholds, marginalizing regional mills without captive resin supply or direct-to-builder logistics networks.
Pricing Analysis
Capacity additions in Texas and Georgia are reshaping price floors for spec-grade vinyl products as integrated manufacturers leverage scale economies to capture national homebuilder volume contracts. Three-tier pricing structure across premium, standard, and economy levels separates certified low-VOC engineered hardwood from commodity laminate and imported ceramic alternatives. Price differentiation hinges on wear-layer thickness documentation and CARB Phase 2 chain-of-custody certification. Cost compression in economy-tier laminate is intensifying because polyester fiber substitution and high-density fiberboard oversupply erode margin buffers. National homebuilders exhibit lowest price sensitivity due to volume-contract security, while independent specialty retailers face acute margin pressure from big-box inventory depth.
Supply Chain Analysis
Dual-sourcing requirements from consolidated national homebuilders are fragmenting procurement across domestic rigid composite fabricators and Asian decorative overlay suppliers. Geographic supply concentration centers on the United States for vinyl resin compounding and carpet fiber extrusion, China for laminate decorative papers and ceramic tile, and Canada for softwood lumber inputs. Raw material dependencies rest on PVC resin from Gulf Coast chlor-alkali complexes, nylon 6,6 polymer from integrated chemical producers, and tropical hardwood veneers subject to Lacey Act documentation. Supply chain risk manifests as tariff exposure on Chinese laminate substrates and ceramic imports. Distribution runs through captive direct-to-builder logistics networks for volume accounts, with specialty retailers serving renovation-driven replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor manufacturers with backward integration into resin supply and those capturing premium-tier shifts toward certified low-emission engineered products. Waterproof core technology licensing and direct-to-builder channel control represent the primary value-capture mechanisms.
For Market Incumbents: Lock in volume commitments from consolidated national homebuilders through captive logistics networks and spec-grade product standardization. Invest in Environmental Product Declaration documentation to secure California Title 24 eligibility and public project specification access. Defend against ceramic tile substitution in moisture-prone applications by accelerating rigid composite product development. Prioritize acoustic performance specialization for multifamily and hospitality segments where sound transmission codes tighten. For New Entrants and Emerging Players: Direct-to-builder digital procurement platforms offer lower customer acquisition costs than traditional distribution relationships for regional mill challengers. Target Sun Belt metropolitan renovation activity in Texas and Florida where floating installation compatibility reduces skilled labor barriers. Pursue white-space opportunities in low-VOC certified engineered hardwood for California's extended producer responsibility procurement mandates. Establish sample-to-home fulfillment capabilities to capture discretionary homeowner projects. For Investors and Strategic Acquirers: Roll-up economics work for regional carpet mills and specialty flooring distributors because fragmented contractor-direct channels lack scale efficiency and national homebuilder access. Five-to-ten year viability depends on securing waterproof core technology licenses and direct-to-builder logistics infrastructure. Acquisition target archetype: mid-cap manufacturers with EPA TSCA Title VI compliant substrate capabilities and Sun Belt distribution presence. Monitor CARB Phase 2 enforcement intensity and California low-VOC certification adoption rates as inflection indicators for specification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Waterproof Core Technology Licensing | Enables unified whole-house specifications and reduces national homebuilder SKU complexity. |
| Direct-to-Builder Logistics Network | Captures margin from consolidated procurement and secures volume-contract commitments. |
| Environmental Product Declaration Investment | Satisfies California Title 24 embodied carbon documentation for public project eligibility. |
| Acoustic Performance Specialization | Addresses multifamily sound transmission code tightening and hospitality rapid replacement cycles. |
| Low-VOC Certification Program Alignment | Meets extended producer responsibility legislation and indoor air quality mandate requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with flooring manufacturer executives, national homebuilder procurement directors, specialty retailer category managers, and contractor installation crews with secondary validation against EPA TSCA Title VI enforcement records, CARB Phase 2 certification databases, Census Bureau construction spending data, and SEC 10-K filings from publicly traded flooring companies. Bottom-up demand modeling across product type, installation method, end use, and material segments was triangulated against top-down market value reconciliation.
Comparable historical reference periods anchored the projection framework, with growth trajectories derived from regression analysis of housing starts, renovation spending, and regulatory compliance cost pass-through patterns across the modeling period. Segmentation dimensions modeled include product category, installation system, residential versus commercial application, and substrate material composition. Forecast inputs incorporated petrochemical feedstock price volatility assumptions and Sun Belt construction permit velocity indices.
The model assumes a particular technology adoption path; alternative pathways for waterproof core unification would alter the outlook if ceramic tile manufacturers accelerate large-format thin-set product development or if solid hardwood refinishing longevity recaptures specification share. Deviation in EPA formaldehyde enforcement intensity or California extended producer responsibility expansion timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
China Wood Flooring Market