
 Europe Resilient Floor Covering Market | 2026-2036
Europe Resilient Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Resilient Floor Covering Market Foresight
REACH compliance is pivoting the cost-of-entry calculus for imported raw materials across the Europe Resilient Floor Covering Market. Tarkett S.A. leverages vertically integrated polymer compounding to manage substance-of-very-high-concern liabilities. Forbo Flooring Systems anchors its position through linoleum manufacturing rooted in oxidized linseed oil chemistry. Gerflor SAS competes via specialized vinyl formulations engineered for healthcare and education environments.
Europe resilient floor covering encompasses flexible surfacing materials—vinyl, linoleum, rubber, and cork—typically manufactured in rolls, tiles, or planks between 2mm and 5mm thickness, installed through glue-down, loose lay, or click-lock methods to provide durable, water-resistant walking surfaces. These materials serve commercial, institutional, and residential buildings where foot traffic, moisture exposure, or acoustic control demands exceed rigid flooring performance thresholds. Vinyl dominates volume across the region due to cost scalability and design versatility, while linoleum retains structural relevance in sustainability-specified public procurement. Click-lock installation is displacing traditional glue-down methods in residential renovation as skilled labor scarcity elevates demand for faster, cleaner fitting systems.
EMA, ECHA, and the EU Green Deal collectively shape product formulation, chemical disclosure obligations, and embodied carbon thresholds for flooring specified in public buildings. ECHA's SVHC candidate list expansion is forcing reformulation of plasticizer systems in PVC-based products, while the EU Green Deal's building renovation wave redirects procurement toward lower-carbon alternatives. Stakeholders must monitor how the CSRD's scope-three reporting requirements alter specification behavior among large commercial real estate owners and institutional facility managers.
Market Dynamics
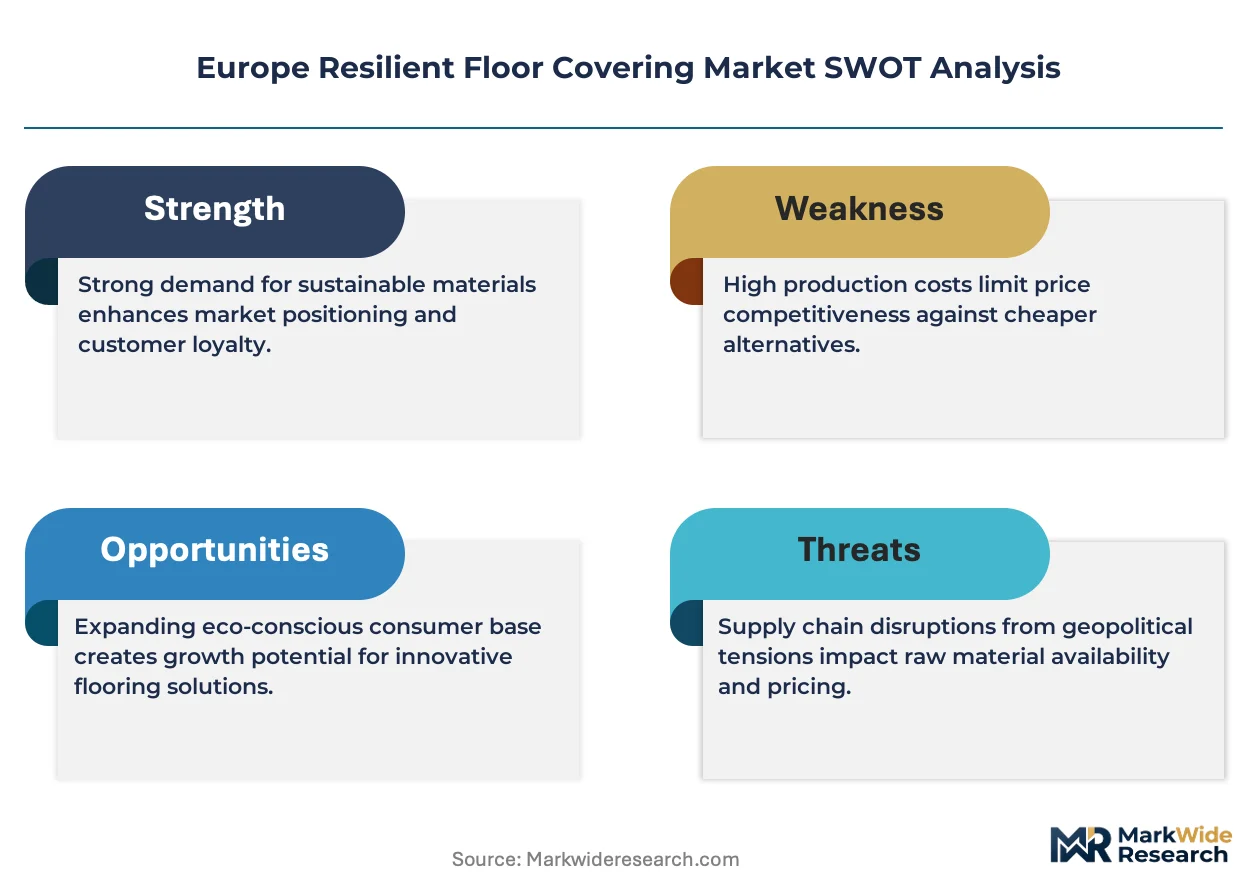
REACH substance-of-very-high-concern listings are forcing wholesale plasticizer reformulation across European vinyl flooring supply chains, compressing margins for importers while rewarding captive polymer compounders.
Growth Catalysts
- Healthcare construction:German, French, and Dutch hospital expansion programs specify hygienic, seam-welded vinyl surfaces for infection control corridors and operating theaters.
- EU Green Deal renovation wave:Member-state building retrofit mandates accelerate substitution from rigid ceramics toward lower-embodied-carbon resilient materials in public procurement.
- Click-lock mechanical fastening:Residential renovation demand for glue-free installation systems is automating fit-out timelines and reducing skilled labor dependency.
Market Restraints
- Plasticizer chemistry constraints:ECHA SVHC candidate list expansion restricts orthophthalate formulations, forcing costly migration to bio-based or non-phthalate alternatives.
- Raw material concentration:European PVC resin supply clusters around Rhine-Ruhr and Rotterdam-Antwerp chemical corridors, exposing buyers to regional logistics disruption.
- Linoleum feedstock volatility:Oxidized linseed oil production depends on agricultural harvest cycles in Argentina and Ukraine, creating input price instability.
Strategic Opportunities
- CSRD scope-three reporting:Large commercial real estate owners now require embodied carbon disclosure, creating specification pull for Environmental Product Declaration-certified surfaces.
- Eastern European renovation backlog:Poland, Czech Republic, and Romania hold underpenetrated residential stock ripe for moisture-resistant flooring upgrades.
- Bio-based polymer convergence:Blending recycled PVC with bio-attributed feedstocks offers compliance pathway for Green Public Procurement criteria in Nordic markets.
Industry Challenges
- Skilled installer scarcity:Traditional glue-down sheet vinyl application requires certified welding technicians, a trade with declining apprenticeship completion across Germany and France.
- Multi-standard certification lag:Products must simultaneously satisfy CE marking, national building codes, and voluntary ecolabels, extending time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Resilient Floor Covering Market |
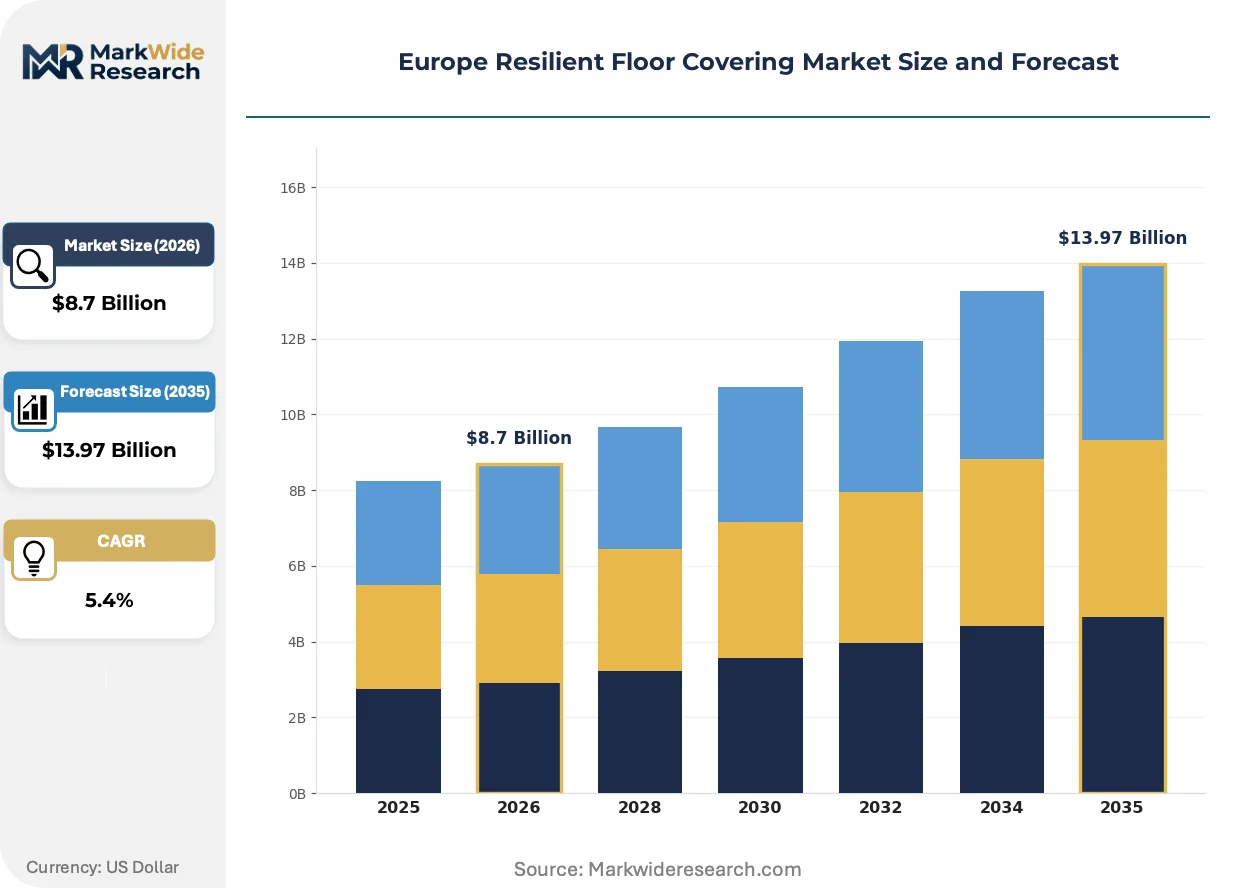
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Linoleum, Rubber, Cork End Use: Residential, Commercial, Industrial, Institutional Installation Type: Glue-down, Loose Lay, Interlocking, Click Lock Thickness: 2mm, 3mm, 4mm, 5mm |
| Companies Covered | Tarkett S.A., Forbo Flooring Systems, Gerflor SAS, Mohawk Industries, Interface Inc., Beaulieu International Group, Altro Limited, Armstrong Flooring, Shaw Industries Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Resilient Floor Covering Market Shifts & Advancements
Digital surface decoration and mechanical installation systems are compressing the traditional trade-off between design flexibility and fit-out speed across European commercial and residential segments.
Digital print transfer technology is automating wood-grain and mineral visual replication onto vinyl wear layers with sub-millimeter registration accuracy. Hospital and education facility buyers in the Netherlands and Belgium are specifying these surfaces for rapid corridor refurbishment without demolition. This capability is automating the displacement of traditional rotary-screen printing equipment and shortening production changeover cycles from days to hours.
ECHA's persistent organic pollutant restrictions and REACH authorization requirements are eliminating legacy stabilizer chemistries from PVC compounding. Flooring manufacturers with in-house polymer science capabilities are securing supply continuity through提前 reformulation, while smaller importers face stock obsolescence. Healthcare procurement departments in France and Germany now require full material disclosure to SVHC thresholds, filtering specification toward compliant domestic producers.
Facility management departments are consolidating flooring maintenance contracts into multi-year service agreements bundling installation, cleaning chemistry, and scheduled replacement. This displaces traditional spot-purchase procurement through distributors and direct manufacturer sales teams. The shift is most visible in German commercial real estate, where property management platforms specify total-cost-of-ownership metrics over upfront material pricing.
Europe Resilient Floor Covering Market Segmentation
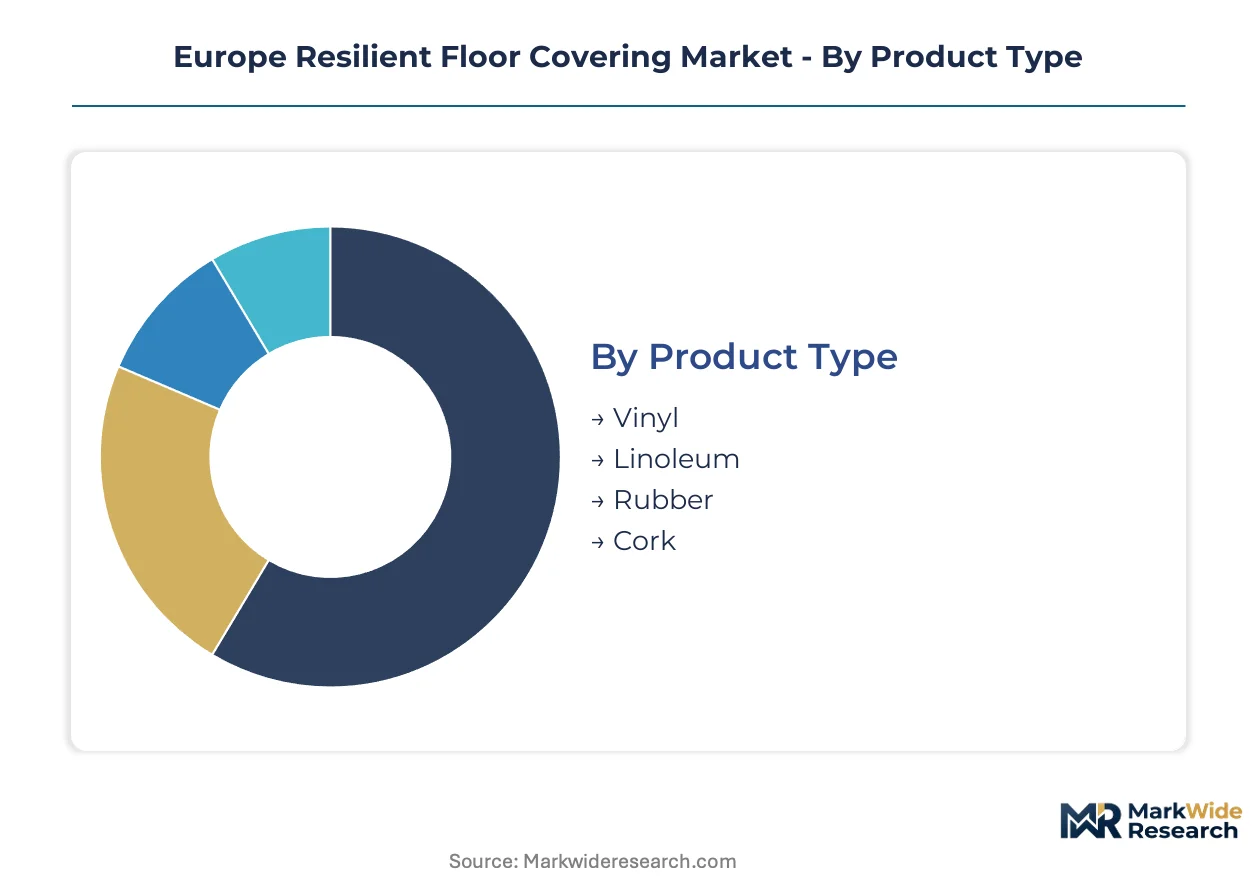
Segmentation in Europe's resilient flooring market reveals how capital deployment, regulatory exposure, and installation labor availability concentrate value capture across distinct product and application categories. Manufacturers align production assets against these dimensions to defend margin structure.
Product Type:
Vinyl and linoleum command the heaviest upfront capital requirements due to polymer compounding infrastructure and continuous oxidation line investments respectively.
- Vinyl:PVC-based formulations with calendered or extruded wear layers dominate volume across German and French commercial construction. REACH SVHC compliance costs are compressing importer margins while rewarding Rhine-Ruhr compounders with captive plasticizer reformulation capabilities.
- Linoleum:Oxidized linseed oil bonded to jute backing retains structural relevance in sustainability-specified public procurement, particularly Dutch healthcare and Nordic education facilities where Environmental Product Declaration certification is mandatory.
- Rubber:Vulcanized synthetic or natural rubber compounds serve high-impact athletic and industrial environments where slip resistance and acoustic dampening exceed vinyl performance thresholds.
- Cork:Granulated cork with polyurethane binders occupies premium residential niches in Portugal and Spain where thermal insulation and renewable content specifications drive specification.
Most installed capacity flows through vinyl. Expansion is steepest in linoleum as EU Green Deal procurement criteria harden.
End Use:
Application segments diverge sharply in specification authority, with institutional buyers wielding consolidated procurement power versus fragmented residential decision-making.
- Commercial:Office, retail, and hospitality fit-outs across Germany's Rhine-Ruhr corridor and Bavaria specify digitally printed vinyl for rapid refurbishment cycles. Facility management platforms are consolidating multi-year service contracts that bundle installation, maintenance chemistry, and scheduled replacement.
- Institutional:Hospitals, schools, and government buildings in the Netherlands, France, and Germany require seam-welded hygienic surfaces with full SVHC material disclosure, filtering specification toward domestic producers with in-house polymer science capabilities.
- Residential:Renovation demand concentrates in moisture-resistant flooring upgrades across Poland, Czech Republic, and Romania where click-lock installation is displacing glue-down methods due to skilled labor scarcity.
- Industrial:Manufacturing and logistics facilities prioritize chemical resistance and load-bearing capacity, typically specifying thicker rubber or fortified vinyl formulations.
Commercial captures the greatest specification volume. Institutional is gaining share fastest as healthcare construction accelerates.
Installation Type:
Mechanical fastening systems are redistributing value from skilled installers toward product-integrated locking geometries that compress fit-out timelines.
- Click Lock:Rigid core planks with angle-angle locking profiles enable glue-free floating installation, automating residential renovation timelines across Eastern European markets where certified welding technicians are scarce.
- Glue-down:Full-spread adhesive application remains mandatory for sheet vinyl in hospital corridors and operating theaters requiring seam welding for infection control, preserving demand for certified installer networks in Germany and France despite apprenticeship decline.
- Loose Lay:Friction-backed planks or tiles rely on dimensional stability and perimeter retention, suited to temporary commercial installations where future access to subflooring is anticipated.
- Interlocking:Square-edge tiles with gasket or puzzle-style connections serve modular replacement scenarios in education and retail environments.
Glue-down retains the largest installed base. Click-lock is climbing the fastest as labor constraints intensify.
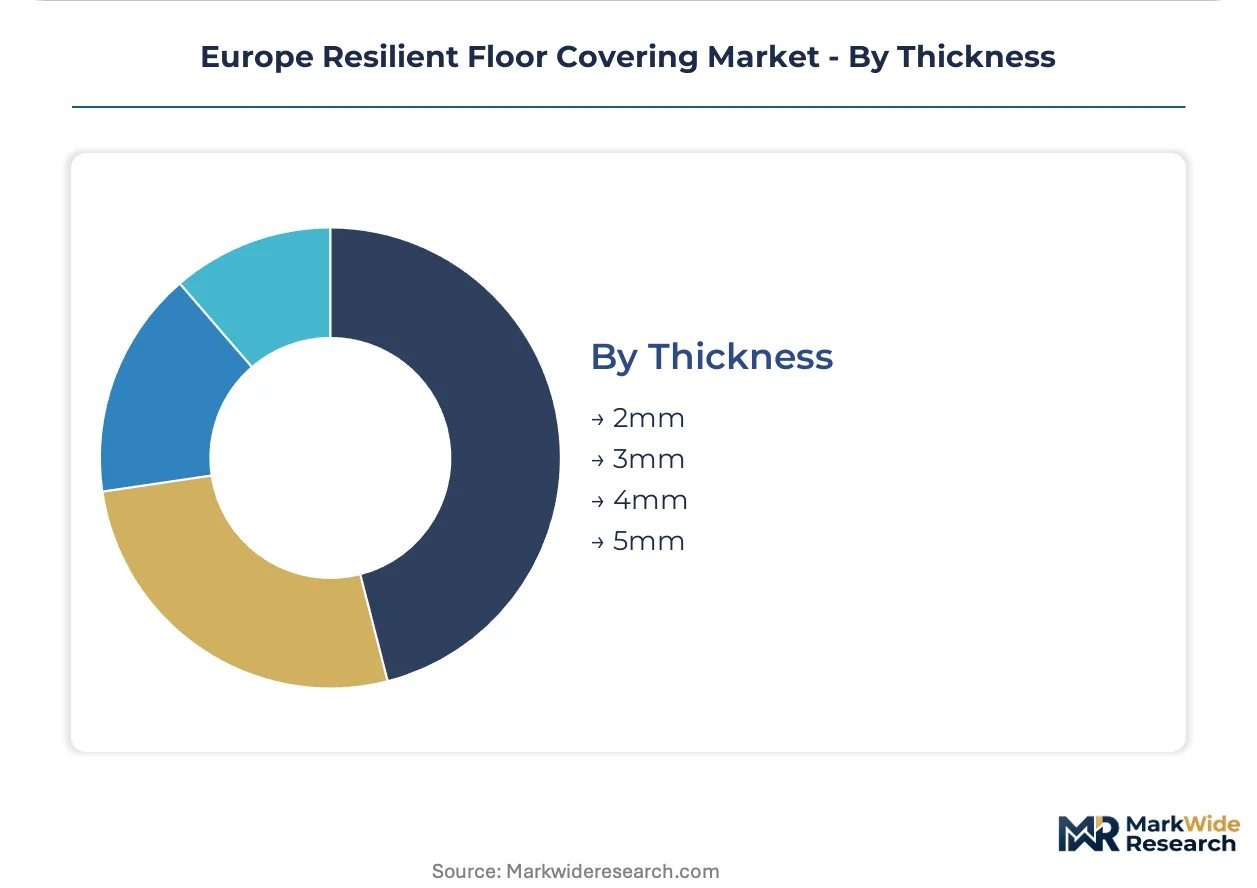
Thickness:
Gauge selection correlates directly with traffic load specification and subfloor condition tolerance, with thicker products commanding material premiums but reducing preparation labor.
- 2mm:Economy-grade sheet and tile formats serve light residential and commercial refurbishment where subfloor flatness is assured and replacement cycles are short.
- 3mm:Mid-range specification balances material cost with sufficient wear layer depth for standard commercial traffic across French office and retail environments.
- 4mm:Rigid core click-lock platforms with integrated underlayment dominate Eastern European residential renovation, accommodating moderate subfloor irregularity without additional preparation.
- 5mm:Heavy-duty commercial and industrial formulations provide maximum dimensional stability and acoustic performance for German healthcare and education facilities with demanding maintenance protocols.
3mm and 4mm gauges absorb the majority of current volume. 5mm is expanding most quickly in institutional specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welding technicians and polymer compounding chemists cluster along the Rhine-Ruhr chemical corridor, anchoring Europe's resilient flooring production capacity. This workforce concentration shapes regional competitive advantage across national markets.
Germany
Healthcare construction in Bavaria and the Rhine-Ruhr corridor drives specification for seam-welded hygienic vinyl surfaces. REACH SVHC compliance requirements filter procurement toward domestic producers with captive plasticizer reformulation capabilities. Cologne-Düsseldorf chemical plants supply modified PVC compounds to flooring manufacturers clustered in Solingen and Weinheim.
France
Hospital expansion programs in Île-de-France and Auvergne-Rhône-Alpes prioritize infection-control flooring with full material disclosure to ECHA thresholds. The EU Green Deal's building renovation targets accelerate substitution from ceramics toward lower-carbon resilient materials in public procurement. Lyon-based polymer scientists collaborate with flooring producers in Saint-Étienne on bio-based plasticizer development.
Netherlands
Dutch healthcare and education facilities mandate Environmental Product Declaration certification, sustaining linoleum demand from Forbo's Krommenie production site. ECHA's persistent organic pollutant restrictions eliminate legacy stabilizer chemistries from specified products. Rotterdam-Antwerp chemical corridors supply oxidized linseed oil feedstocks to domestic manufacturers.
Poland
Residential renovation backlog in Warsaw and Kraków concentrates demand for moisture-resistant click-lock flooring systems. Skilled installer scarcity elevates preference for glue-free mechanical fastening methods. Poznań distribution hubs channel German and Czech manufactured products into Eastern European retail networks.
Belgium
Digital print transfer technology adoption concentrates among Antwerp and Ghent surface decoration specialists serving rapid commercial refurbishment cycles. CE marking and national building code convergence extends product time-to-market, favoring established domestic regulatory affairs capabilities. Liège polymer research institutes collaborate with flooring producers on wear-layer formulation advances.
Europe Resilient Floor Covering Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's resilient flooring market. The vendor base stratifies into three tiers: multinational surface materials groups with polymer compounding integration, mid-cap flooring specialists with regional manufacturing footprints, and import-dependent distributors facing REACH compliance cost compression. Strategic moves center on backward integration into raw material supply and portfolio diversification toward bio-attributed feedstocks.
Within the integrated polymer compounding tier, Tarkett S.A. and Forbo Flooring Systems occupy positions anchored by in-house formulation capabilities. Gerflor SAS exemplifies the healthcare-specialist archetype. These French and Swiss-registered entities represent contrasting strategic postures: captive chemical production versus linoleum oxidation expertise versus vinyl formulation specialization for institutional specification.
| Leading Market Players |
|---|
| Tarkett S.A. |
| Forbo Flooring Systems |
| Gerflor SAS |
| Mohawk Industries |
| Interface Inc. |
| Beaulieu International Group |
| Altro Limited |
| Armstrong Flooring |
| Shaw Industries Group |
| Others |
Supply & Pricing Matrix
German facility management platforms bundling installation, maintenance chemistry, and scheduled replacement into multi-year service agreements command pricing power over spot-purchase procurement channels. This consolidation toward total-cost-of-ownership contracting compresses upfront material premiums while elevating after-sales service margins across the Rhine-Ruhr corridor.
Pricing Analysis
Bundled service contracts versus unbundled material-only transactions split the pricing landscape. Three-tier pricing structure across premium EPD-certified, standard CE-marked, and economy-grade unlabeled products differentiates by certification burden and disclosure depth. Cost compression in imported vinyl formulations intensifies as REACH SVHC compliance obligations force plasticizer reformulation. Residential renovation buyers in Poland and Romania exhibit highest price sensitivity; Dutch healthcare procurement departments demonstrate lowest sensitivity due to mandatory lifecycle costing protocols.
Supply Chain Analysis
Single-source vulnerability sits with oxidized linseed oil feedstock concentrated in Argentina and Ukraine harvest cycles. PVC resin production clusters in Germany, Belgium, and the Netherlands along Rhine-Ruhr and Rotterdam-Antwerp chemical corridors. Supply chains draw from petroleum-derived vinyl chloride monomer, agricultural linseed crops, and jute backing textiles from Bangladesh. Regulatory restriction through ECHA SVHC candidate list expansion threatens legacy stabilizer availability. Distribution runs through Poznań and Warsaw hubs channeling German-manufactured products into Eastern European retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in captive polymer compounding and EPD certification premiums as REACH compliance costs filter out import-dependent competitors. Bio-attributed feedstock blending offers a compliance pathway for Green Public Procurement criteria in Nordic markets.
For Market Incumbents: Extend backward integration into modified PVC compounding to capture plasticizer reformulation margins that REACH SVHC listings are compressing for importers. Consolidate certified welding technician networks in Germany and France before apprenticeship completion rates decline further. Anchor position through multi-year facility management service contracts that displace spot-purchase distributor channels. For New Entrants and Emerging Players: Distributor partnerships in Poland, Czech Republic, and Romania offer the most penetrable entry channel given Eastern European residential renovation backlog and skilled installer scarcity. Target click-lock rigid core platforms for moisture-resistant flooring upgrades where glue-free installation automates fit-out timelines. Compete on speed-to-install rather than material cost against established Rhine-Ruhr compounders. For Investors and Strategic Acquirers: Building materials conglomerates with existing polymer science capabilities are the most active acquirer in this space, seeking linoleum oxidation expertise and healthcare-specialized vinyl formulation assets. Mid-cap flooring specialists with captive EPD certification and Dutch or Nordic public procurement relationships represent the priority acquisition archetype. Watch CSRD scope-three reporting adoption rates among large commercial real estate owners as the signal for accelerated specification pull toward embodied carbon-disclosed surfaces.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive plasticizer reformulation secures REACH SVHC compliance continuity against importer stock obsolescence. |
| Environmental Product Declaration Certification | Dutch healthcare and Nordic education procurement mandates filter specification toward EPD-verified domestic producers. |
| Multi-Year Service Contract Bundling | German facility management platforms consolidate installation, maintenance chemistry, and replacement into recurring revenue streams. |
| Bio-Attributed Feedstock Blending | Recycled PVC combined with bio-based content satisfies EU Green Deal procurement criteria in sustainability-specified tenders. |
| Click-Lock Installation Platform Expansion | Glue-free mechanical fastening addresses skilled welder scarcity across Polish and Czech residential renovation markets. |
Research Methodology
Coverage spans Western Europe and Eastern Europe, with primary inputs from each regional cluster combining executive interviews with flooring manufacturer R&D directors, German and French facility management procurement leads, Polish distributor network heads, and Dutch healthcare estates managers. Secondary validation drew from ECHA SVHC candidate list publications, EU Green Deal building renovation target documentation, CE marking technical files, and customs trade data for PVC resin and linoleum feedstock flows. Bottom-up volume modeling triangulated against top-down construction sector expenditure estimates.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, segmenting by product type, end-use application, installation method, and thickness gauge. CAGRs derived from fitted trend extrapolation adjusted for regulatory inflection points including REACH authorization timelines and CSRD reporting phase-ins. Modeled inputs incorporated hospital construction pipeline data from Germany, France, and the Netherlands alongside residential renovation permit volumes from Poland, Czech Republic, and Romania.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA SVHC list expansion timing, agricultural harvest volatility in Argentina and Ukraine, and apprenticeship completion trends for certified vinyl welders. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market