
 Asia-Pacific Floor Covering Market | 2026-2036
Asia-Pacific Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Floor Covering Market Outlook
Digital printing on ceramic and resilient surfaces is tilting production economics toward shorter runs with customized visual layers. Mohawk Industries Inc. leverages its integrated fiber-to-tile manufacturing footprint to control cost curves across multiple substrate categories. Shaw Industries Group Inc. anchors its Asia-Pacific position through carpet tile specialization aimed at commercial workspace retrofits. Tarkett S.A. competes on bio-based PVC formulations that respond to specifier preferences for reduced petrochemical content.
Asia-Pacific floor covering encompasses finished surfacing materials installed over structural subfloors to provide wear resistance, acoustic control, and aesthetic finish in built environments; technical specifications span wear-layer thickness measured in millimeters, density ratings for carpet pile, and water absorption coefficients for glazed ceramic tile. The product type dimension shows vinyl and tile occupying the largest volume positions due to moisture tolerance and cleaning protocols favored in healthcare and food service settings, while laminate sustains share in residential applications where cost-per-square-meter drives selection. Material-grade PVC and polyester dominate commercial specification flows because of supply availability and colorfastness under UV exposure.
China's SAMR enforces GB standards for indoor air quality that directly constrain adhesive and substrate formulations sold into residential projects. India's BIS certification mandates for imported ceramic tile create procedural barriers that favor domestic manufacturing scale or pre-certified supplier relationships. Japan's JIS standards for slip resistance and fire performance shape product development priorities for hospitality and aged-care end uses. Stakeholders must monitor how divergent national compliance frameworks fragment procurement strategies across what remains a regionally interconnected supply base.
Market Dynamics
China's SAMR enforcement of tightening GB standards for formaldehyde emissions is compressing laminate supply chains while accelerating specification migration toward compliant resilient and ceramic alternatives across residential construction corridors.
Growth Catalysts
- Urban residential tower construction:India's metropolitan corridors are driving specification volumes for carpet and resilient flooring as commercial retrofit cycles accelerate alongside new-build activity.
- GB standards compliance pressure:China's tightening indoor air quality mandates are forcing substrate reformulation investments that favor domestic manufacturers with integrated testing capabilities.
- Digital printing adoption:Shorter production runs with customized visual layers are enabling hospitality developers across Southeast Asia to specify project-specific luxury vinyl plank and porcelain tile at reduced minimum order quantities.
Market Restraints
- Petrochemical input volatility:Material-grade PVC and polyester supply fluctuations create margin compression for commercial specification flows dependent on colorfastness under UV exposure.
- Import certification barriers:India's BIS mandates for ceramic tile create procedural friction that limits supplier diversification and extends procurement timelines for large-scale projects.
- Natural stone substitution:Engineered quartz and sintered stone surfaces are capturing premium specification share in hospitality and healthcare settings where moisture tolerance and cleaning protocols overlap.
Strategic Opportunities
- Tier-2 Indian urban expansion:Secondary cities beyond Mumbai, Delhi, and Bangalore present underpenetrated specification channels as residential construction migrates inland from coastal corridors.
- Bio-based formulation tailwinds:Reduced petrochemical content preferences among commercial specifiers are creating procurement advantages for suppliers with certified bio-based PVC and renewable binder systems.
- Healthcare-acoustics convergence:Integrated underlayment systems combining wear resistance with sound attenuation are opening specification pathways in Japan's aged-care facility expansion.
Industry Challenges
- Multi-jurisdiction compliance staffing:Divergent national frameworks across China, India, and Japan require dedicated regulatory affairs capacity that mid-scale suppliers struggle to maintain.
- Subfloor preparation standardization:Inconsistent substrate condition assessment protocols across project sites create installation quality variance and warranty claim exposure.
- Digital-to-physical color matching:Custom visual layer production demands precise calibration between screen-based specification tools and manufacturing output, stretching technical service resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Floor Covering Market |
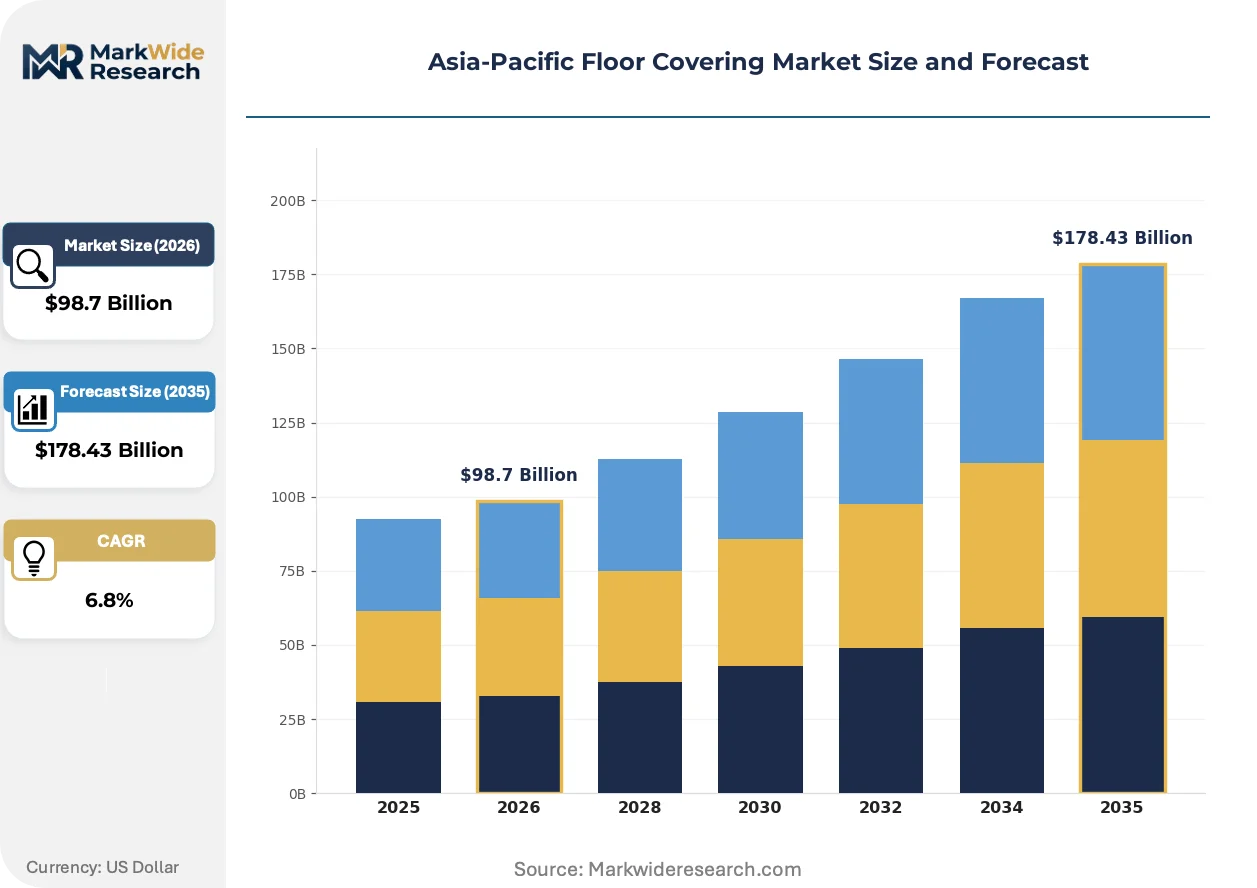
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpets, Laminate, Vinyl, Tiles Material: Wool, Nylon, Polyester, PVC End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online, Retail Stores, Distributors, Showrooms |
| Companies Covered | Mohawk Industries Inc., Shaw Industries Group Inc., Tarkett S.A., Interface Inc., Milliken & Company, TOLI Corporation, Forbo Flooring Systems, Gerflor Group, RAK Ceramics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Floor Covering Market Strategic Shifts
Specification workflows are compressing decision timelines while fragmenting procurement authority across project stakeholders, forcing material suppliers to reconfigure technical service and sampling infrastructure.
Water-based UV-curable coating systems are migrating from niche artisan applications to mainstream resilient flooring production. Hospitality developers in Thailand and Vietnam are specifying these finishes for high-traffic lobby and corridor installations. The technology is migrating from European import dependence to localized production partnerships that compress lead times from twelve weeks to under four.
Japan's METI has issued updated JIS standards for slip resistance and fire performance in commercial flooring. These regulations are accelerating product development cycles for hospitality and aged-care suppliers. Domestic manufacturers with existing JIS certification infrastructure are capturing specification share from importers facing retesting timelines.
Architects and interior designers are consolidating material libraries into centralized digital platforms that bypass traditional distributor showrooms. Commercial workspace retrofit projects across Singapore and Sydney are sourcing directly through these curated databases. This channel compression is most visible in corporate headquarters and co-working space rollouts where repeat specification patterns reduce the need for physical sampling.
Asia-Pacific Floor Covering Market Segmentation
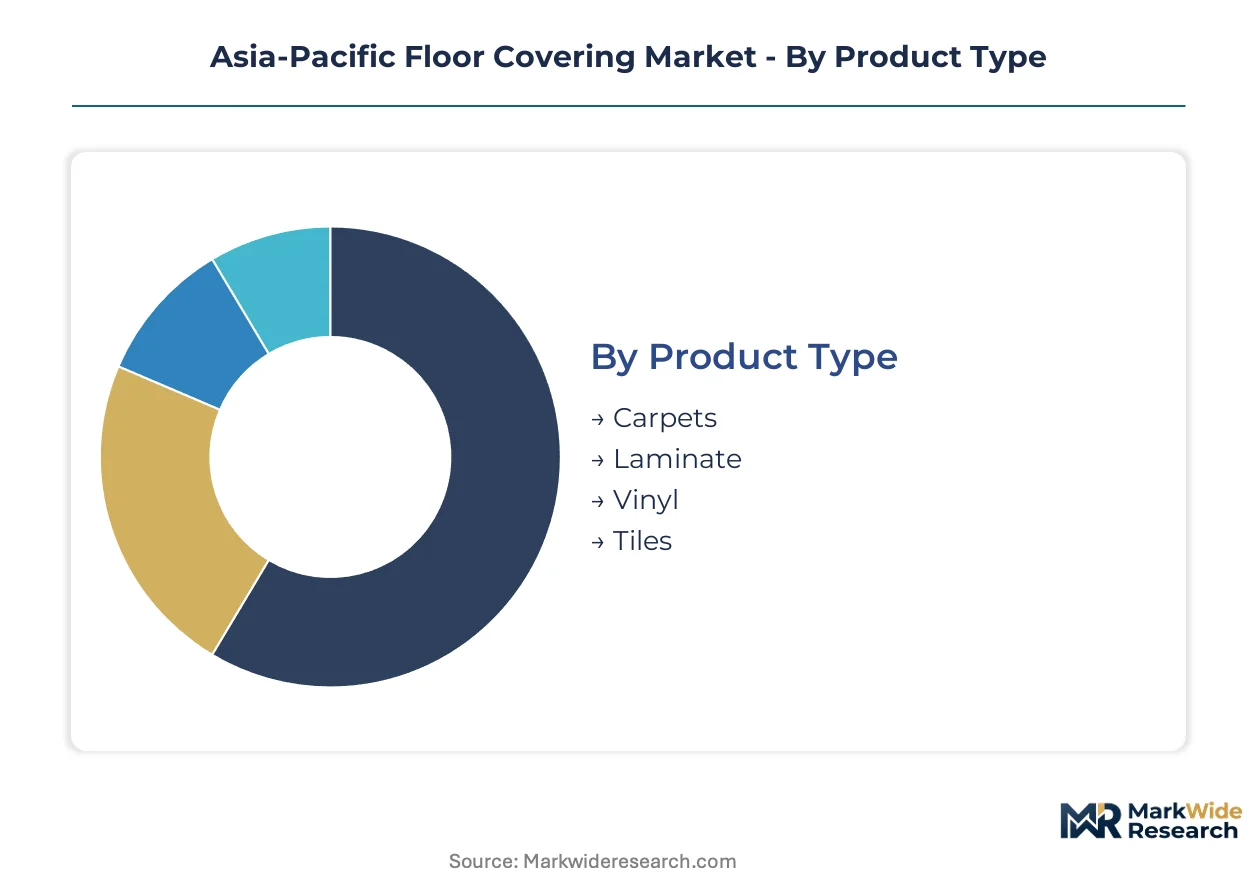
Specification patterns across Asia-Pacific diverge sharply by subfloor condition, moisture exposure, and compliance burden. Segmentation reveals where procurement authority concentrates and which material categories capture margin versus volume.
Product Type:
Mature categories dominate current specification flows while emerging formats reshape production economics through digital customization capabilities.
- Vinyl:Luxury vinyl plank and sheet goods combine calendered PVC wear layers with fiberglass reinforcement for dimensional stability. Hospitality developers across Thailand and Vietnam specify these surfaces for high-traffic corridors where moisture tolerance and rapid installation matter. Water-based UV-curable coating localization has compressed lead times from European import dependence to under four weeks.
- Tiles:Glazed ceramic and porcelain surfaces command healthcare and food service specification through water absorption coefficients below 0.5% and chemical resistance. India's BIS certification mandates for imported ceramic create procedural barriers that favor domestic manufacturing scale in Morbi and Gujarat clusters.
- Carpets:Broadloom and carpet tile systems deliver acoustic control through pile density ratings measured in ounces per square yard. Commercial workspace retrofits across Singapore and Sydney drive specification through digital material libraries that bypass traditional distributor showrooms.
- Laminate:High-density fiberboard cores with aluminum oxide wear layers sustain residential share where cost-per-square-meter drives selection. China's SAMR enforcement of tightening GB standards for formaldehyde emissions is compressing supply chains and accelerating migration toward compliant alternatives.
Vinyl retains volume leadership; tiles hold the steepest expansion curve through hospitality specification at scale.
Material:
Cost tier stratification separates premium natural fibers from petrochemical-derived volume categories, with bio-based formulations emerging as a procurement differentiator.
- PVC:Material-grade polyvinyl chloride dominates commercial specification through supply availability and colorfastness under UV exposure. Tarkett S.A. competes on bio-based PVC formulations that respond to specifier preferences for reduced petrochemical content in corporate workspace rollouts.
- Polyester:Solution-dyed PET fibers offer stain resistance and recycled content credentials for carpet tile backing and face yarn. India's urban corridors absorb volume as residential tower construction and commercial retrofit cycles accelerate.
- Nylon:Type 6 and Type 6,6 polymers deliver crush resistance and resilience for high-traffic commercial installations. Premium positioning concentrates in aged-care and hospitality segments where durability warranties extend to fifteen years.
- Wool:Natural protein fibers provide inherent flame resistance and moisture buffering for premium residential and boutique commercial environments. Limited supply and price volatility constrain specification to projects with sustainability certification requirements.
PVC commands the broadest specification base; bio-based formulations within this category are gaining share fastest among ESG-mandated procurement.
End User:
Application-driven performance requirements fragment procurement authority across project stakeholders with divergent technical priorities.
- Commercial:Corporate headquarters, co-working spaces, and retail environments prioritize carpet tile modularity and rapid replacement cycles. Digital platform consolidation enables direct sourcing through curated databases that compress decision timelines.
- Hospitality:Hotels, resorts, and food service operations demand slip resistance, acoustic control, and cleaning protocol compatibility. Southeast Asian developers specify project-specific visual layers through digital printing at reduced minimum order quantities.
- Residential:Urban tower construction across India's metropolitan corridors drives specification for laminate and resilient surfaces where cost-per-square-meter dominates selection criteria. China's tightening indoor air quality mandates force substrate reformulation investments.
- Industrial:Manufacturing and logistics facilities require static control, chemical resistance, and load-bearing capacity. Specification concentrates in heavy-traffic zones where wear-layer thickness exceeds 2.0 millimeters.
Commercial captures the largest specification volume; hospitality presents the steepest margin expansion opportunity through customized production runs.
Distribution Channel:
Customer type fragmentation separates specification influencers from procurement executors, reshaping technical service and sampling infrastructure requirements.
- Distributors:Regional stocking intermediaries maintain inventory depth for project-based procurement with compressed lead time requirements. Relationships with domestic manufacturers in China and India provide compliance documentation for GB and BIS standards.
- Showrooms:Physical specification environments support tactile evaluation and color matching for hospitality and premium residential projects. Bangkok and Jakarta clusters serve as regional hubs for Southeast Asian project development.
- Retail Stores:Big-box and specialty flooring retailers capture residential replacement demand through installed-sales programs. Staff training on subfloor preparation standardization varies across markets, creating installation quality variance.
- Online:Digital platforms aggregate product data and enable direct specification for repeat commercial workspace patterns. Architects and interior designers in Singapore and Sydney bypass traditional distributor relationships for standardized carpet tile programs.
Distributors retain volume leadership through project scale; online channels are expanding most quickly among specification professionals with established material preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports luxury vinyl plank and porcelain tile to hospitality developers across Thailand and Indonesia, establishing a manufacturing corridor that feeds Southeast Asian construction booms.
China
Residential tower construction in Chengdu and Wuhan drives specification volumes for compliant resilient surfaces. SAMR enforces tightening GB standards for formaldehyde emissions that compress laminate supply chains. Domestic manufacturers in the Yangtze River Delta capture share through integrated testing capabilities.
India
Metropolitan corridors around Mumbai and Delhi accelerate carpet and resilient flooring procurement for commercial retrofits. BIS certification mandates for imported ceramic tile create procedural barriers favoring domestic scale. Manufacturing clusters in Morbi and Gujarat supply glazed porcelain to healthcare and food service projects.
Japan
Aged-care facility expansion across Kansai and Chubu regions demands integrated underlayment systems with sound attenuation. METI updated JIS standards for slip resistance and fire performance in commercial flooring. Domestic suppliers with existing certification infrastructure capture specification share from importers facing retesting timelines.
Australia
Corporate workspace retrofits in Sydney and Melbourne source carpet tile through digital material libraries that bypass traditional distributor showrooms. Solution-dyed PET fibers with recycled content credentials attract ESG-mandated procurement. Technical service infrastructure concentrates in the Sydney-Canberra corridor.
South Korea
Seoul Capital Area developers specify water-based UV-curable coating systems for high-traffic hospitality installations. MFDS-aligned quality frameworks shape import acceptance protocols for resilient surfaces. Localized production partnerships compress lead times from European import dependence to under four weeks.
Asia-Pacific Floor Covering Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages separate volume leaders from niche positioning. The market shows moderate consolidation at the top tier with fragmented mid-scale competition beneath. Three archetypes dominate: integrated fiber-to-tile manufacturers, bio-based formulation specialists, and carpet tile modularization experts. Competitive moves concentrate on backward integration into raw material supply and geographic expansion through localized production partnerships.
Within the integrated manufacturing tier, Mohawk Industries Inc. and Shaw Industries Group Inc. exemplify scale-driven positioning through captive control across multiple substrate categories. Tarkett S.A. occupies a distinct position among bio-based formulation advocates, representing the specialist archetype that responds to reduced petrochemical content preferences in corporate procurement.
| Leading Market Players |
|---|
| Mohawk Industries Inc. |
| Shaw Industries Group Inc. |
| Tarkett S.A. |
| Interface Inc. |
| Milliken & Company |
| TOLI Corporation |
| Forbo Flooring Systems |
| Gerflor Group |
| RAK Ceramics |
| Others |
Value Chain & Pricing Dynamics
China's GB standards enforcement creates a regulatory chokepoint that compresses laminate margins while widening spreads between compliant and non-compliant product tiers across the region. This divergence forces procurement officers to segment suppliers by certification infrastructure, reshaping sourcing geography toward domestic manufacturers with integrated testing capabilities.
Pricing Analysis
Digital printing technology-generation pricing gaps separate legacy rotary-screen production from inkjet-enabled short runs across Southeast Asian hospitality specification. Three-tier pricing structure across premium JIS-certified, standard BIS-compliant, and economy non-certified levels reflects certification investment differentials. Cost compression in economy laminate tiers intensifies because China's SAMR enforcement accelerates supply exit. Commercial workspace retrofit buyers in Singapore and Sydney show lowest price sensitivity due to ESG-mandated procurement budgets.
Supply Chain Analysis
Upstream petrochemical feedstock flows from South Korea, Thailand, and Singapore anchor PVC resin supply for calendered wear-layer production. Material-grade PVC and plasticizer inputs draw from regional crackers with limited alternative sourcing. Single-source vulnerability concentrates in specialty coating additives for water-based UV-curable systems. Distribution runs through project-stocking distributors in Bangkok and Jakarta that maintain GB and BIS documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific floor covering market rewards suppliers with captive compliance infrastructure as regulatory fragmentation outpaces regulatory affairs staffing capacity across mid-scale competitors. Technical service density in secondary Indian cities and JIS certification depth represent the scarcest capabilities for capturing specification share.
For Market Incumbents: Insulate specification relationships by embedding technical service teams within architect and interior designer digital platforms before channel compression accelerates. Backward integration into water-based UV-curable coating production in Vietnam compresses lead times against European import dependence. Certification pre-positioning for India's BIS mandates and Japan's updated JIS standards creates procurement friction that locks out importers facing retesting timelines. For New Entrants and Emerging Players: Build out bio-based PVC formulation capabilities to capture corporate ESG-mandated procurement in Sydney and Melbourne workspace retrofits. Tier-2 Indian urban corridors beyond Mumbai and Delhi present the most penetrable geography as residential construction migrates inland. Direct specification through curated digital material libraries offers the cleanest go-to-market angle for standardized carpet tile programs. For Investors and Strategic Acquirers: The market sits at a compliance-divergence phase that favors integrated manufacturers with multi-jurisdiction certification infrastructure over import-dependent trading houses. Long-term viability centers on suppliers with captive testing capabilities and localized production partnerships that compress lead times. Watch for BIS certification timeline extensions as the signal indicating procurement friction intensification and domestic manufacturing premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Production | Localized water-based UV-curable manufacturing in Vietnam compresses hospitality specification lead times from European dependence. |
| Multi-Jurisdiction Certification Investment | Simultaneous GB, BIS, and JIS compliance infrastructure locks out importers facing retesting timelines in aged-care and healthcare segments. |
| Digital Platform Technical Service Embedding | Architect and interior designer platform integration in Singapore and Sydney captures specification before distributor showroom bypass accelerates. |
| Bio-Based Formulation Scale-Up | Certified renewable PVC and binder systems capture ESG-mandated corporate procurement with reduced petrochemical content credentials. |
| Tier-2 Distribution Network Expansion | Secondary city stocking points in India's inland corridors intercept residential tower construction as specification migrates from coastal metros. |
Study Parameters
The analysis maps vinyl, tile, carpet, and laminate sub-sectors, each validated through specification interviews with hospitality developers, commercial workspace procurement officers, and residential tower project managers. Primary fieldwork with distributor inventory planners and manufacturing plant managers combined with secondary validation through customs trade data, BIS certification registries, and METI JIS standard documentation. Bottom-up project pipeline tracking and top-down construction spend estimates triangulate volume outputs.
Fixed assumptions include continued SAMR enforcement intensity, sustained petrochemical input volatility, and stable digital printing adoption curves across the projection horizon. Segmentation dimensions modeled encompass product type, material chemistry, end-use application, and distribution channel structure. CAGRs derive from installation volume trajectories tied to urban residential tower permits and commercial retrofit cycle timing. Industry-specific inputs include hospitality development pipeline databases and aged-care facility expansion forecasts.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Chinese domestic manufacturers or accelerated bio-based formulation scale-up by European specialists would shift outcomes beyond modeled ranges. Cross-checking against construction sector PMI data and petrochemical feedstock price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Lightweight Acoustic Floor Systems Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market