
 Luxury Vinyl Plank (LVP) Market | 2026-2036
Luxury Vinyl Plank (LVP) Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Vinyl Plank (LVP) Market Intelligence
Asian manufacturing concentration is decoupling from North American and European brand ownership, creating complex supply chain dynamics. This shift pressures companies to secure reliable production partners or invest in regional manufacturing capabilities. Shaw Floors leverages its extensive distribution network to maintain market presence. Meanwhile, Mohawk Industries competes on manufacturing scale and brand recognition across multiple flooring categories.
Luxury vinyl plank is a multi-layered synthetic flooring composed of a PVC or composite core, a high-definition photorealistic print layer, and a protective wear layer. Its primary function is to replicate the appearance of natural materials like hardwood or stone while offering superior water resistance and durability. Rigid core products dominate new installations in the residential sector, valued for their stability and impact resistance. Flexible core LVP maintains a foothold in commercial settings where budget and roll-out speed are primary considerations.
Product compliance is governed by multiple frameworks, including the US EPA's standards for volatile organic compound (VOC) emissions, often verified through FloorScore certification. In Europe, the REACH regulation restricts specific chemical substances used in PVC production, while CE marking ensures products meet health and safety standards. The key decision for manufacturers now involves balancing investments in sustainable, low-VOC materials against maintaining competitive price points.
Market Dynamics
The LVP market's primary dynamic involves balancing consumer demand for hyper-realistic aesthetics against intensifying regulatory pressures for healthier, low-VOC materials. This tension drives innovation in core composition and print layer technology while complicating global supply chains.
Growth Catalysts
- Rigid Core Innovation:Innovations in rigid core construction, particularly Stone Plastic Composite (SPC), enhance product stability and impact resistance, making LVP a preferred choice for high-traffic residential remodeling projects.
- North American Renovation Demand:The United States residential sector, specifically single-family home renovation, provides a concentrated source of demand for LVP due to its performance and design flexibility.
- Advanced Photorealistic Printing:High-definition digital printing enables the creation of authentic wood and stone visuals, satisfying consumer aesthetic preferences for natural material replication without the associated maintenance.
Market Restraints
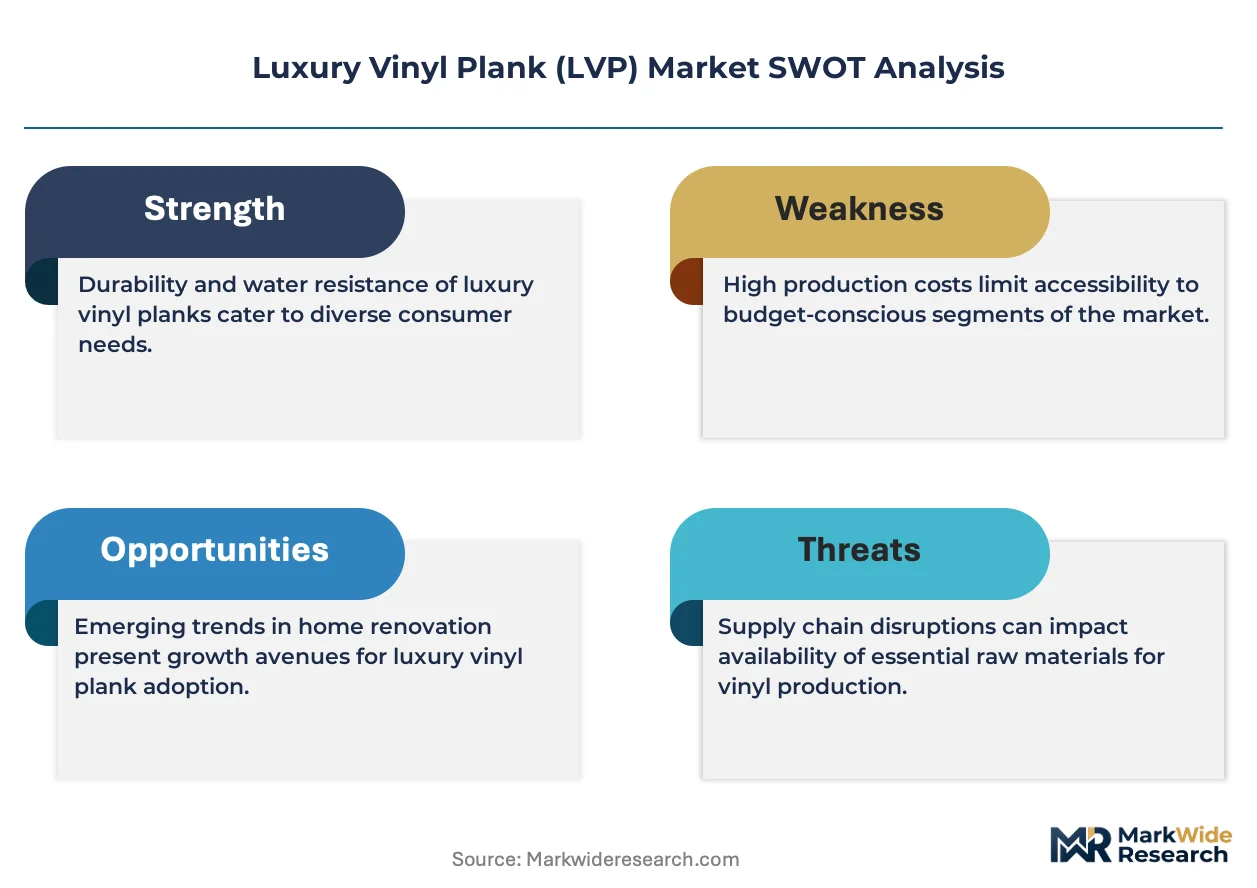
- Raw Material Volatility:The market is exposed to price fluctuations in key inputs, particularly PVC resin and plasticizers, which can compress manufacturer margins and impact final product cost.
- Substitution from Laminate:Next-generation laminate flooring with improved water resistance presents a significant substitution threat, competing directly on both performance and price points in key residential segments.
- Supply Chain Concentration:A heavy reliance on manufacturing in specific Asian countries creates vulnerability to geopolitical tensions, shipping disruptions, and tariff implementations that can affect supply continuity.
Strategic Opportunities
- Bio-Based PVC Development:Investing in the development and commercialization of bio-based or recycled PVC alternatives presents an opportunity to meet demand for sustainable building materials and gain a competitive edge.
- Light Commercial Sector Penetration:There is significant growth potential in light commercial applications, including boutique hospitality, retail, and healthcare clinics, which require a blend of durability, aesthetics, and easy maintenance.
- Expansion in Latin America:Markets such as Brazil and Mexico represent underpenetrated regions where rising construction activity creates a new frontier for LVP adoption beyond North America and Europe.
Industry Challenges
- Navigating Global Compliance:Manufacturers face the operational challenge of ensuring products simultaneously meet divergent regulatory standards, such as the US EPA's VOC limits and Europe's REACH chemical restrictions.
- Installation Skill Gap:A shortage of trained installers, especially for intricate patterns like herringbone, can lead to installation failures that negatively impact brand reputation and customer satisfaction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Vinyl Plank (LVP) Market |
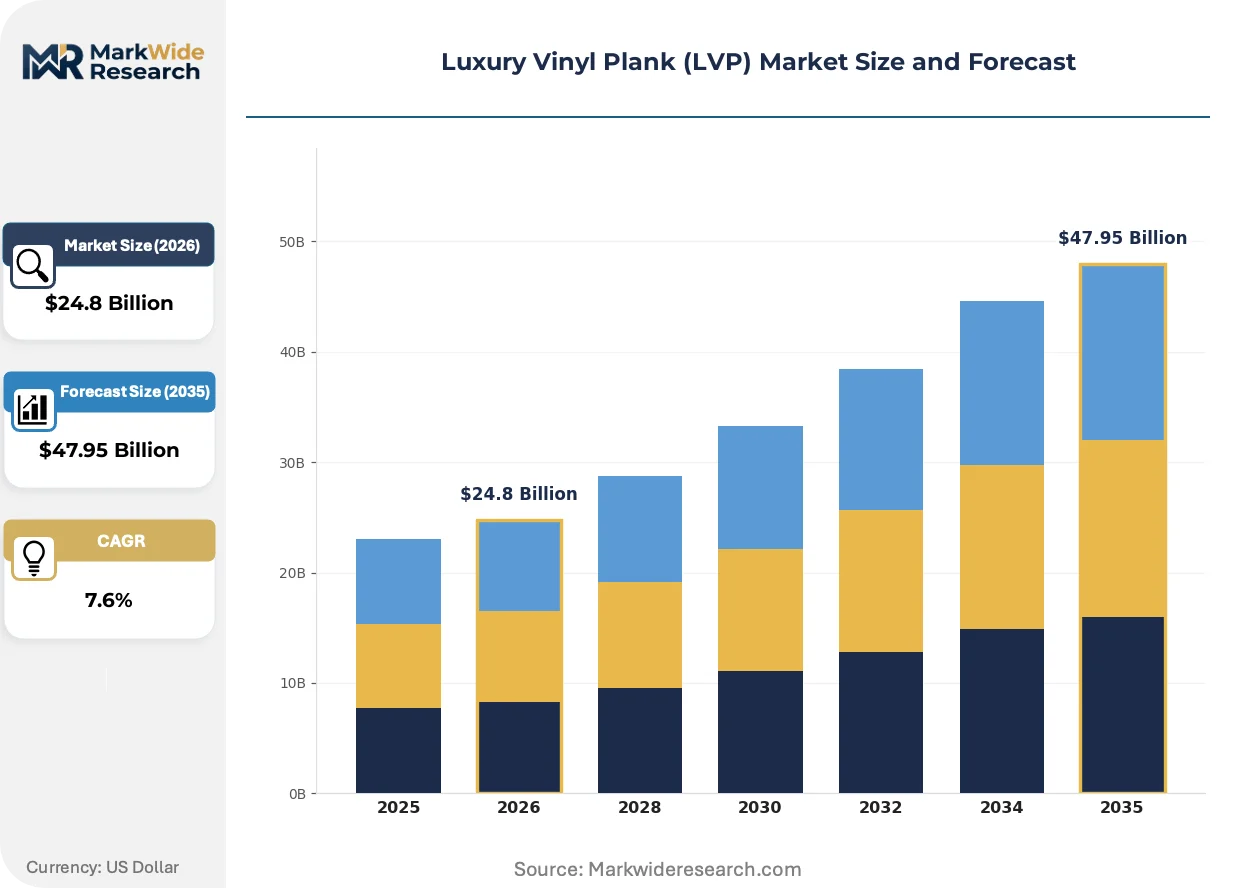
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $47.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Core, Flexible Core, Loose Lay, Click Lock End User: Residential, Commercial, Hospitality, Retail Thickness: 5mm, 6mm, 7mm, 8mm Surface Texture: Smooth, Embossed, Hand-Scraped, Textured |
| Companies Covered | Karndean, Mannington Mills, Shaw Floors, NuCore, LifeProof Flooring, Mohawk Industries, Armstrong Flooring, Pergo, COREtec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Vinyl Plank (LVP) Market Strategic Shifts & Innovations
Material science advancements are converging with circular economy principles, fundamentally altering product lifecycles. This shift compels manufacturers to rethink everything from raw material sourcing to end-of-life product management, pushing the industry toward more sustainable solutions.
Stone Plastic Composite (SPC) core technology provides exceptional dimensional stability and rigidity. Residential and light commercial sectors are rapidly adopting SPC for its durability and waterproof properties. This technology is expanding into areas once held by ceramic tile, including full bathrooms and basements, due to its superior performance in high-moisture environments.
Europe's REACH regulation tightens restrictions on certain phthalates in PVC products. This directive necessitates rigorous supply chain auditing and formulation adjustments for manufacturers selling into the European Union. Consequently, product lines are bifurcating, with specific EU-compliant formulations developed for that market while other versions serve less-regulated regions.
A behavioral change is the increasing reliance of architects and designers on digital specification tools and Building Information Modeling (BIM) libraries. This trend sidelines traditional physical sampling, giving an advantage to producers who offer data-rich digital assets and Environmental Product Declarations (EPDs). The shift is most pronounced within commercial design communities in North America and Western Europe.
Luxury Vinyl Plank (LVP) Market Segmentation
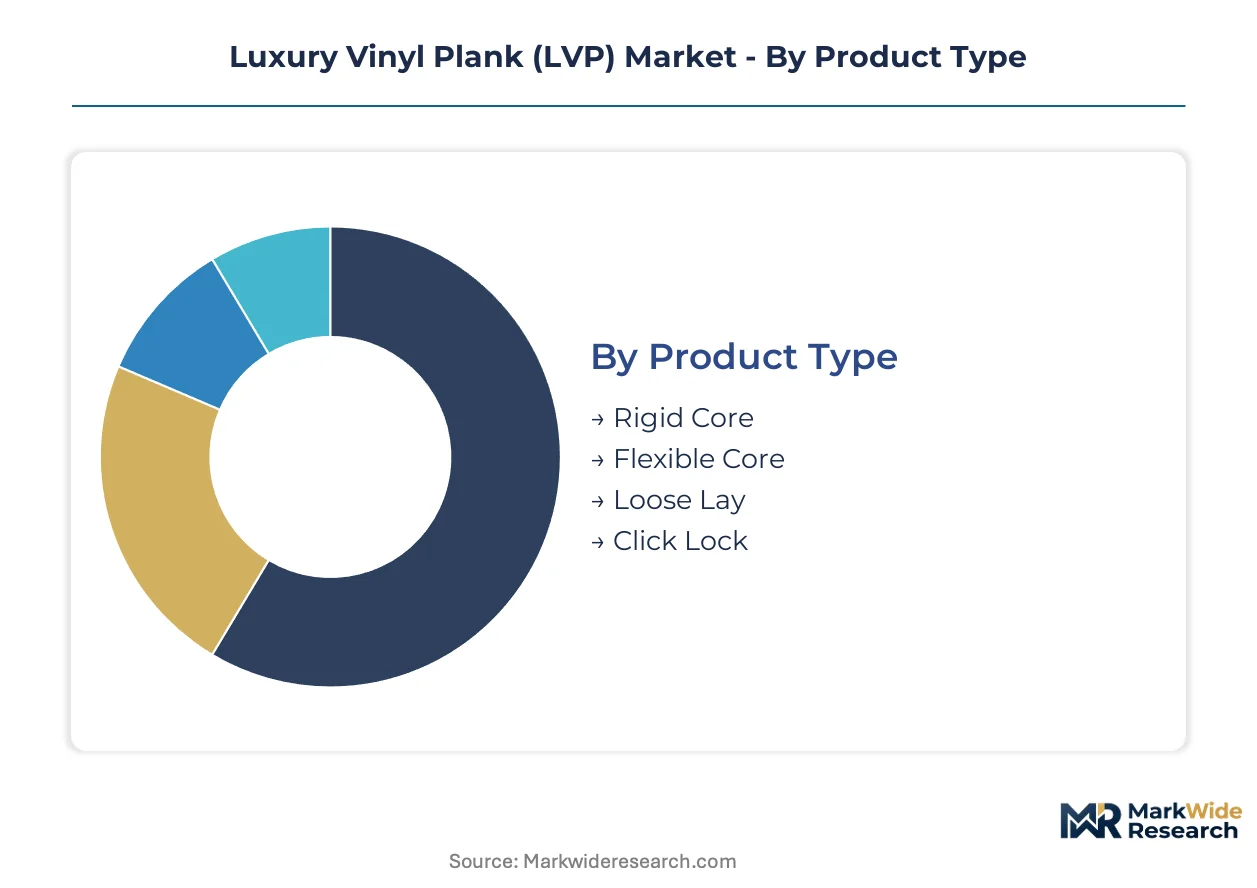
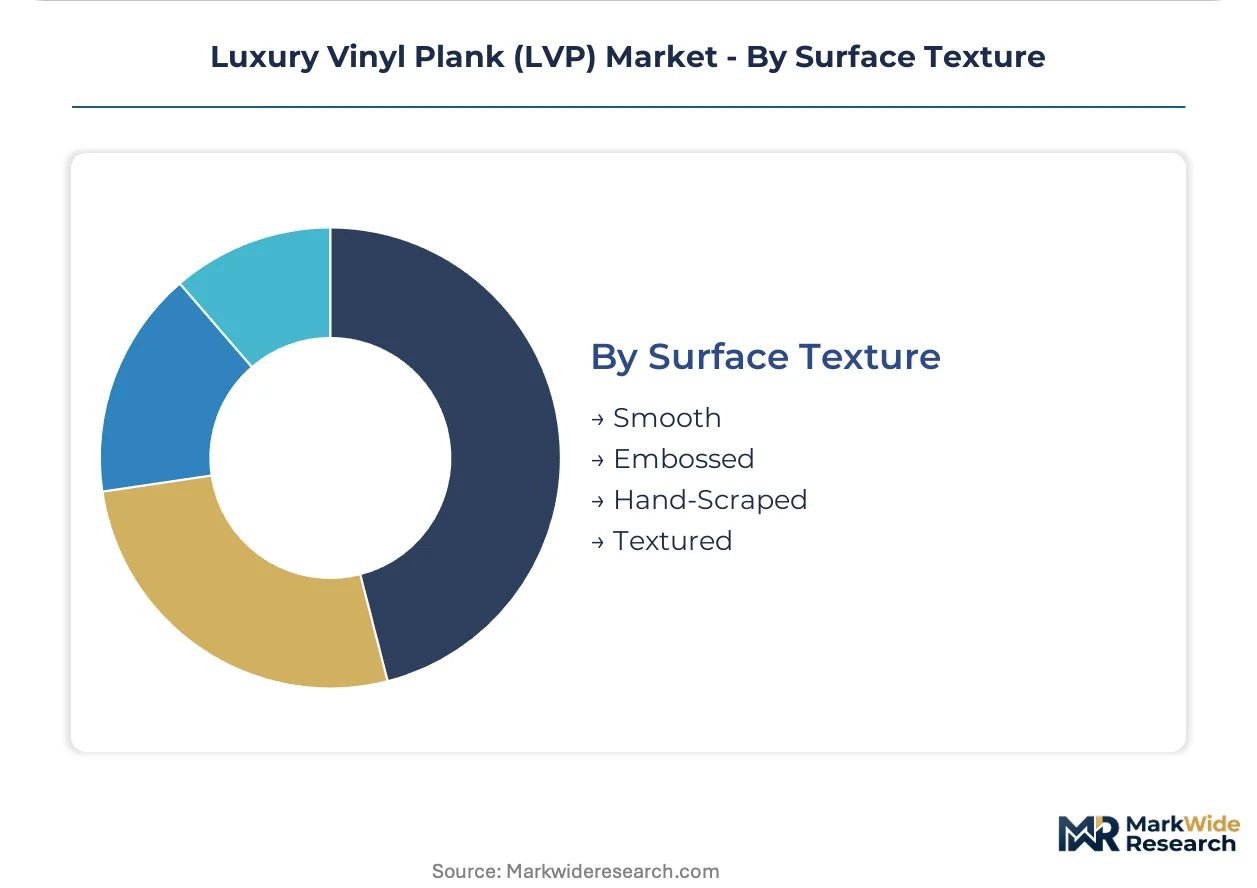
The Luxury Vinyl Plank (LVP) market's segmentation provides a detailed framework for understanding product differentiation and demand drivers. Analyzing these categories reveals how specific material compositions, end-user applications, and aesthetic attributes shape competitive strategies and market expansion. This granular view enables stakeholders to identify high-growth niches and tailor product development efforts effectively.
Product Type:
LVP product types differentiate based on core construction and installation methodology, directly influencing performance characteristics and suitability for various applications.
- Rigid Core:Rigid core LVP, such as Stone Plastic Composite (SPC), features a dense, stable core providing superior dimensional stability and impact resistance. Demand concentrates in residential renovation projects, particularly in North America, driven by its waterproof properties and ease of installation over imperfect subfloors.
- Flexible Core:Flexible core LVP typically utilizes a softer PVC core, offering greater pliability and often a lower profile for easier handling and cutting. Commercial settings, especially in Europe, favor flexible core options for large-scale roll-out projects due to budget considerations and faster installation times.
- Loose Lay:Loose lay LVP relies on friction and weight for installation, making it ideal for temporary applications or spaces requiring frequent access to the subfloor.
- Click Lock:Click lock LVP features an interlocking edge system, enabling glueless floating installations that are popular for DIY residential projects.
Rigid Core leads on scale; Click Lock leads on momentum.
End User:
LVP adoption varies significantly across different end-user segments, each driven by distinct performance requirements and aesthetic preferences.
- Residential:The residential sector encompasses single-family homes and multi-family dwellings, where LVP is valued for its durability, water resistance, and design versatility. Demand is concentrated in the United States, particularly for renovation projects, where homeowners seek authentic wood and stone aesthetics without high maintenance.
- Commercial:Commercial end-users include offices, educational institutions, and healthcare facilities, prioritizing LVP for its high wear resistance and ease of cleaning. European markets show strong demand for commercial LVP, driven by stringent health and safety standards requiring low-VOC materials and long-term performance.
- Hospitality:Hospitality applications, such as hotels and resorts, specify LVP for its aesthetic appeal, acoustic properties, and ability to withstand heavy foot traffic.
- Retail:Retail environments utilize LVP for its visual impact, quick installation, and resilience against spills and frequent cleaning in high-traffic areas.
The residential segment accounts for the largest volume, while the commercial sector exhibits the steepest expansion trajectory.
Thickness:
LVP thickness directly correlates with product durability, stability, and acoustic performance, influencing its suitability for various traffic levels and installation environments.
- 8mm:8mm LVP represents a premium offering, providing enhanced rigidity, superior impact absorption, and a more substantial feel underfoot. This thickness is increasingly specified in high-traffic residential areas and light commercial settings in North America, where long-term performance is paramount.
- 6mm:6mm LVP offers a balanced combination of durability and cost-effectiveness, making it a popular choice for a wide range of applications. It finds significant adoption in mid-range residential renovations and certain commercial spaces across Europe, balancing performance with budget constraints.
- 7mm:7mm LVP provides an intermediate option, delivering improved stability over thinner planks while remaining cost-competitive for various residential and light commercial uses.
- 5mm:5mm LVP is typically chosen for budget-conscious projects or areas with lighter traffic, offering basic durability and ease of handling.
Thicker LVP variants capture higher value per square foot, while mid-range options drive the largest installation volumes.
Surface Texture:
Surface texture in LVP profoundly influences the aesthetic appeal and tactile experience, allowing manufacturers to replicate natural materials with increasing realism.
- Embossed:Embossed LVP features a textured surface that aligns with the photographic print layer, enhancing the realism of wood grain or stone patterns. This texture is highly sought after in residential markets globally, as consumers prioritize authentic visual and tactile replication of natural flooring.
- Hand-Scraped:Hand-scraped textures mimic the appearance of aged, handcrafted wood floors, characterized by irregular grooves and subtle undulations. Premium residential segments in the United States increasingly favor hand-scraped LVP for its unique rustic aesthetic and perceived artisanal quality.
- Smooth:Smooth LVP offers a clean, contemporary look, often chosen for modern design schemes where minimalist aesthetics are preferred.
- Textured:Textured LVP provides a non-specific tactile surface, enhancing slip resistance and adding a subtle dimension beyond a completely smooth finish.
Embossed and hand-scraped textures command a premium price point, while smooth and general textured finishes cater to broader market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage shapes global LVP manufacturing, as producers seek regions with lower compliance costs for certain chemicals and VOC emissions. This dynamic influences investment in new facilities and supply chain restructuring. Demand centers in North America and Europe drive innovation while Asian countries lead production scale.
United States
Demand for LVP in the United States concentrates in single-family home renovation projects, driven by performance and aesthetic versatility. The US EPA's standards for volatile organic compound (VOC) emissions influence product formulation and certification requirements. Major distribution hubs in states like Georgia facilitate efficient supply to construction and retail channels.
Germany
Residential and commercial sectors in Germany specify LVP for its durability and compliance with strict environmental standards. The REACH regulation and CE marking ensure products meet health and safety criteria for chemical substances. Manufacturers in regions like North Rhine-Westphalia focus on developing low-VOC and sustainable LVP solutions.
China
Manufacturing of LVP in China remains a global production hub, benefiting from scale and established supply chains for PVC and related materials. Dual carbon goals and evolving GB standards are pushing local manufacturers towards more sustainable production practices. Industrial clusters in provinces like Jiangsu specialize in rigid core LVP exports to international markets.
Brazil
Rising construction activity and a growing middle class in Brazil fuel demand for cost-effective and durable LVP flooring solutions. National building codes increasingly emphasize material quality and safety in new residential and commercial developments. São Paulo serves as a major distribution and innovation center for LVP products across Latin America.
France
Renovation projects and commercial developments in France prioritize LVP for its aesthetic appeal and adherence to European health standards. Compliance with the REACH regulation and CE marking is essential for market entry and product acceptance. Major ports like Le Havre streamline the import and distribution of LVP materials across the country.
Luxury Vinyl Plank (LVP) Market Key Industry Players
North American producers anchor one tier, focusing on brand recognition and extensive distribution networks for residential markets. Asian specialists hold another tier, emphasizing large-scale manufacturing and cost efficiencies for global supply. The market structure exhibits a tiered consolidation, with a few large integrated players and numerous smaller, regional fabricators. Strategic archetypes include vertically integrated manufacturers, design-focused brands, and private-label suppliers. Companies pursue capacity expansion and strategic partnerships to secure raw material access and broaden market reach.
Within the established brand tier, Shaw Floors exemplifies a company leveraging an extensive distribution network to maintain market presence across North America and beyond, particularly in the residential renovation sector. Mohawk Industries occupies a position as a scale-driven entity, competing on manufacturing scale and brand recognition across multiple flooring categories, including LVP, serving both residential and commercial segments. Armstrong Flooring represents a legacy player adapting its portfolio to rigid core LVP innovations and evolving consumer preferences for durable, aesthetically versatile flooring solutions. These entities collectively shape product development and market trends through their significant investments in R&D, broad market penetration, and influence on design standards.
| Leading Market Players |
|---|
| Karndean |
| Mannington Mills |
| Shaw Floors |
| NuCore |
| LifeProof Flooring |
| Mohawk Industries |
| Armstrong Flooring |
| Pergo |
| COREtec |
| Others |
Cost & Logistics Intelligence
Large-scale commercial project developers often negotiate contract-based pricing directly with manufacturers, influencing the overall market's price stability. This concentration of buying power among major purchasers dictates specific pricing tiers and volume discounts within the LVP industry.
Pricing Analysis
Retailer markups significantly influence consumer-facing LVP prices, particularly for residential renovation projects. Per-unit transactional pricing dominates the retail segment, while project-based contracts are common for commercial installations. Brand premium and specific FloorScore certification levels drive price differentiation. Pricing softness reflects intensifying competition from next-generation laminate flooring, particularly in mid-range residential segments. Budget-conscious consumers represent the most price-sensitive segment, while commercial clients prioritizing long-term performance show less sensitivity.
Supply Chain Analysis
Reverse logistics for LVP products primarily involve waste management and recycling initiatives, driven by increasing sustainability mandates. Geographic supply concentration remains high in China and Vietnam, which serve as major production hubs. The industry relies heavily on PVC resin, plasticizers, and high-definition print films. Geopolitical tensions and shipping disruptions present a significant structural risk. Downstream distribution runs through a mix of wholesale channels, direct-to-retail partnerships, and project-specific procurement for large commercial builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LVP market presents a margin-expansion story, driven by consumer willingness to pay for SPC innovations and material science advancements.
For Market Incumbents:
Hedge against raw material volatility by diversifying sourcing agreements and exploring long-term contracts for PVC resin. Invest in regional manufacturing capabilities, especially in North America and Europe, to mitigate supply chain risks and comply with local regulations like REACH. Control key distribution channels to maintain market presence against emerging competitors. Focus R&D on bio-based PVC alternatives to meet sustainability demands and differentiate product lines.
For New Entrants and Emerging Players:
Launch via targeted digital specification tools to penetrate the commercial design community, offering data-rich BIM assets. Focus on the light commercial sector in underpenetrated regions like Latin America, where demand for durable, aesthetic flooring is rising. Emphasize sustainable, low-VOC product lines to gain a competitive edge in environmentally conscious markets. Partner with local installers to overcome the installation skill gap and ensure quality outcomes.
For Investors and Strategic Acquirers:
Private equity firms are the most active acquirers in this space, seeking established brands with strong distribution. The LVP market offers long-term viability, underpinned by sustained residential renovation demand and expanding commercial applications. Target specialized rigid core manufacturers or innovators in sustainable material science. The adoption rate of bio-based PVC and the expansion of FloorScore-certified products are key signals to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in North America | Reduces lead times and mitigates tariff risks for a key demand region. |
| Green Manufacturing Transition | Addresses regulatory pressures and consumer demand for sustainable building materials. |
| Product Launch: Next-Gen SPC | Captures premium segments seeking enhanced durability and aesthetic realism. |
| Distribution Channel Expansion into Light Commercial | Unlocks new revenue streams beyond the saturated residential market. |
| Strategic Partnership for Digital Specification Tools | Enhances engagement with architects and designers in commercial projects. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and trade statistics — were reconciled to construct a comprehensive market view. We engaged with LVP R&D directors, procurement leads, sales managers, and installation specialists to gather qualitative insights. Secondary data sources included industry association reports, government regulatory documents from EPA and ECHA, company financial filings, and trade publications. Bottom-up and top-down triangulation validated market sizing and growth projections.
Historical market performance was cross-referenced with expert panel input to establish the forecast framework. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, end-user, thickness, surface texture, and regional compliance. Compound annual growth rates were derived from historical performance and projected demand drivers. Key forecast inputs included global construction activity forecasts and evolving regulatory compliance costs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme raw material price volatility or unforeseen regulatory shifts. Forecasts reflect assumptions documented regarding macroeconomic stability and technological advancements. Practitioners should monitor new regulatory mandates and significant shifts in construction spending for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market