
 Turkey Carpet and Rugs Market | 2026-2036
Turkey Carpet and Rugs Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Carpet and Rugs Market Analytics
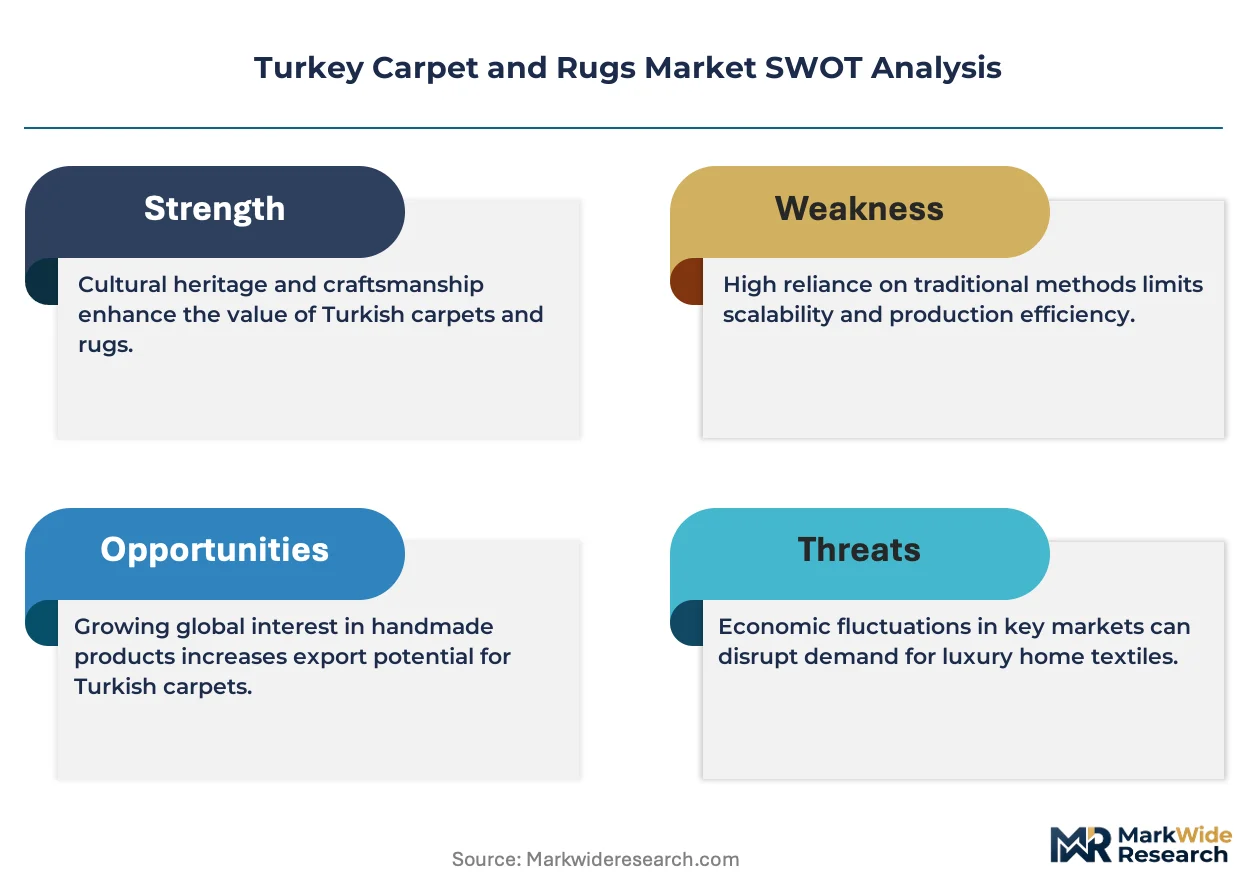
OEKO-TEX Standard 100 certification is redrawing competitive boundaries among Turkish carpet manufacturers. Merinos leverages integrated spinning and dyeing operations to sustain cost discipline across broadloom and area rug lines. Dinarsu anchors its position through dedicated hospitality sector programs targeting hotel refurbishment cycles. Royal Halı competes via design-led contemporary collections distributed through European retail partnerships.
Turkey carpets and rugs comprise textile floor coverings manufactured through hand-knotting, tufting, or weaving processes using pile heights typically ranging from 5mm to 15mm, serving decorative, acoustic, and thermal insulation functions in residential and commercial interiors. Handmade rugs command premium positioning within traditional and tribal design styles, where Anatolian motifs sustain collector and heritage buyer interest. Machine-made carpets dominate volume throughput in synthetic fiber constructions, with polypropylene and polyester blends capturing standard residential and commercial replacement demand. Carpet tiles are gaining specification in corporate and institutional end-user segments, where modular installation reduces lifecycle maintenance costs.
Turkish Ministry of Trade export certification requirements and BIS-equivalent TSE quality standards govern product labeling, flammability performance, and chemical content disclosure for domestic and export-bound production. The country's alignment with EU REACH substance restrictions shapes dye and finishing chemical selections across Gaziantep and Istanbul manufacturing clusters. Stakeholders must monitor evolving EU Deforestation Regulation traceability mandates that could reshape wool and natural fiber sourcing verification requirements.
Market Dynamics
Machine-made carpet production in Turkey is decomposing traditional hand-knotting capacity as Istanbul and Ankara hotel developments accelerate procurement cycles. The shift compresses artisan employment pools while redirecting capital toward automated tufting lines capable of polypropylene broadloom output at scale.
Growth Catalysts
- EU Deforestation Regulation traceability mandates:Wool sourcing verification requirements are creating compliance-ready supplier premiums for Anatolian herding cooperatives that can document chain-of-custody.
- Hospitality sector refurbishment cycles:Istanbul's hotel pipeline demands fire-rated carpet tiles with modular replacement capabilities, pulling specification toward Gaziantep manufacturing clusters.
- TSE quality mark alignment:Domestic certification equivalence with EU REACH substance restrictions is unlocking re-export channels through Rotterdam and Hamburg distribution hubs.
Market Restraints
- Wool price volatility:Anatolian pastureland constraints and Australian wool auction fluctuations compress margin predictability for hand-knotted premium lines.
- Dye chemical import dependency:REACH-compliant reactive dyes concentrate among German and Swiss specialty chemical suppliers, creating input bottleneck risk.
- Hard surface flooring substitution:Luxury vinyl tile and engineered wood specifications are displacing residential broadloom in Marmara region new construction.
Strategic Opportunities
- Central Anatolia underpenetration:Konya and Kayseri provinces exhibit carpet consumption gaps relative to per-capita income growth, supporting distributor network expansion.
- Carpet tile specification in healthcare:Antimicrobial-treated modular systems address infection control protocols in Ankara hospital construction.
- Digital printing convergence with tufting:Piezo inkjet patterning on synthetic substrates enables short-run customization for boutique hotel chains.
Industry Challenges
- Master weaver attrition:Anatolian hand-knotting knowledge transfer faces generational discontinuity as younger labor migrates to industrial zones.
- Dual certification timeline compression:Simultaneous TSE domestic and OEKO-TEX export testing extends product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Carpet and Rugs Market |
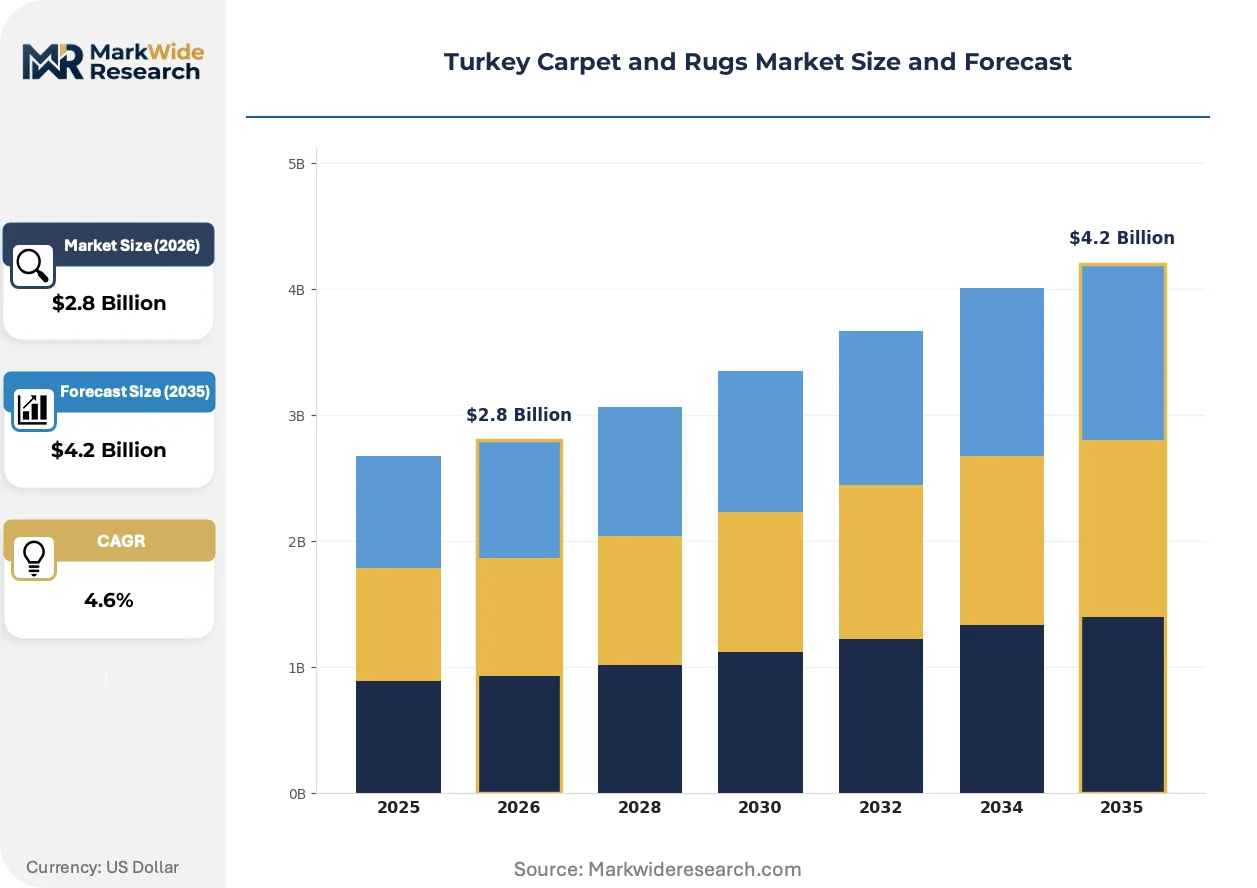
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handmade Rugs, Machine-Made Carpets, Carpet Tiles, Dhurries Material: Wool, Cotton, Synthetic Fibers, Silk Design Style: Traditional, Contemporary, Modern, Tribal End User: Residential, Commercial, Hospitality, Institution |
| Companies Covered | Merinos, Dinarsu, Royal Halı, Kaşmir Halı, Melikhan Carpets, Saray Hali, Milat Carpet, Kartal Hali, Festival Carpet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Carpet and Rugs Market Evolving Landscape
Digital design-to-loom workflows are compressing pattern development cycles while EU chemical restrictions reshape material selection. These forces intersect with changing buyer procurement behaviors across Turkey's domestic and re-export channels.
Recycled polyethylene terephthalate fiber integration is decomposing virgin polyester demand in machine-made residential broadloom. Istanbul-based distributors specify rPET content for corporate sustainability reporting compliance. The technology is decomposing price premiums previously attached to synthetic fiber carpets, compressing differentiation toward design and service attributes.
EU REACH substance restrictions now govern azo dye and heavy metal content across all export-bound production from Gaziantep and Istanbul clusters. Turkish manufacturers reformulate finishing chemistries to maintain Rotterdam and Hamburg market access. Hand-knotted wool lines face elevated testing costs relative to synthetic broadloom, shifting investment toward consolidated dyehouse compliance.
Hotel procurement teams now specify lifecycle cost models replacing upfront square-meter pricing for carpet tile installations. Ankara and Istanbul hospitality developers bundle maintenance contracts with initial material supply, compressing traditional distributor margins. This behavior concentrates specification authority among technical facilities management consultancies serving the Marmara construction pipeline.
Turkey Carpet and Rugs Market Segmentation
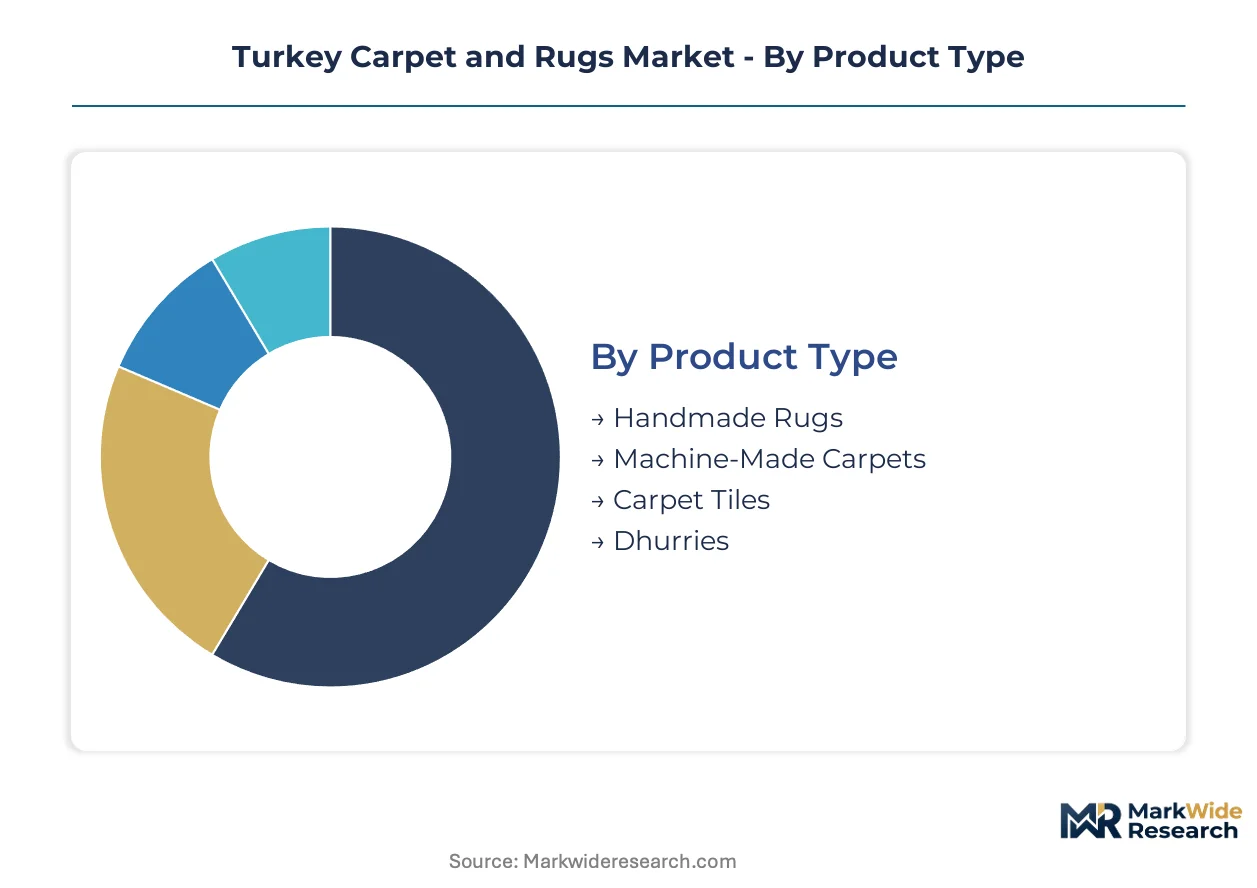
Turkey's carpet and rugs market fragments across four distinct classification axes, each mapping to divergent margin structures and procurement channels. Understanding these segment boundaries clarifies where synthetic substitution threatens legacy formats and where artisan positioning sustains premium extraction.
Product Type:
Luxury vinyl tile and engineered wood flooring are eroding broadloom penetration in Marmara region residential construction, compressing volume share for traditional woven formats while elevating modular alternatives.
- Machine-Made Carpets:Automated tufting lines process polypropylene and polyester blends into broadloom and area rug formats at scale. Istanbul and Ankara hotel developments concentrate procurement for fire-rated synthetic constructions, pulling specification toward Gaziantep manufacturing clusters with TSE certification equivalence.
- Carpet Tiles:Modular polypropylene or nylon systems with bitumen or PVC backing enable zonal replacement and reduced lifecycle maintenance. Ankara hospital construction and corporate office fit-outs in Istanbul specify antimicrobial-treated variants for infection control and acoustic management protocols.
- Handmade Rugs:Anatolian hand-knotting traditions produce wool pile constructions with 5mm to 15mm heights featuring tribal and heritage motifs. Konya and Kayseri collector markets sustain artisan employment pools despite generational knowledge transfer discontinuity.
- Dhurries:Flat-woven cotton or wool constructions without pile serve transitional and summer-season residential applications across Central Anatolia.
Machine-made carpets anchor the volume base while carpet tiles gain share at the steepest rate.
Material:
Raw material selection determines compliance burden and margin volatility, with natural fiber sourcing facing emerging traceability mandates against synthetic alternatives.
- Synthetic Fibers:Polypropylene and polyester blends dominate machine-made throughput, with recycled PET integration decomposing virgin polymer premiums. Istanbul distributors specify rPET content for corporate sustainability reporting compliance.
- Wool:Anatolian pastureland constraints and Australian auction volatility compress margin predictability. EU Deforestation Regulation chain-of-custody documentation creates compliance-ready supplier premiums for documented herding cooperatives.
- Cotton:Flat-weave dhurrie foundations and warp threads for hand-knotted constructions concentrate procurement through Izmir textile trading channels.
- Silk:Hereke and Kayseri ateliers produce ultra-premium collector pieces with knot densities exceeding 1,000 per square inch for Gulf and East Asian export markets.
Synthetic fibers carry the volume base while wool commands the highest unit margins despite regulatory compression.
Design Style:
Design positioning stratifies across heritage authenticity and contemporary minimalism, with distribution channel selection reinforcing price tier boundaries.
- Traditional:Oushak, Hereke, and Konya motifs with medallion and floral patterns serve heritage collector demand and diplomatic gifting protocols through Istanbul's Grand Bazaar and Nisantasi galleries.
- Contemporary:Abstract and transitional patterns bridge residential and hospitality specification, distributed through European retail partnerships with shortened development cycles enabled by digital design-to-loom workflows.
- Modern:Minimalist geometries and solid fields align with Scandinavian and Japanese interior influences in Istanbul's Bebek and Etiler districts.
- Tribal:Kurdish and Yoruk nomadic patterns with geometric medallions sustain ethnographic collector interest through Ankara and Gaziantep auction houses.
Traditional designs anchor heritage export premiums while contemporary formats expand most quickly through hospitality channel specification.
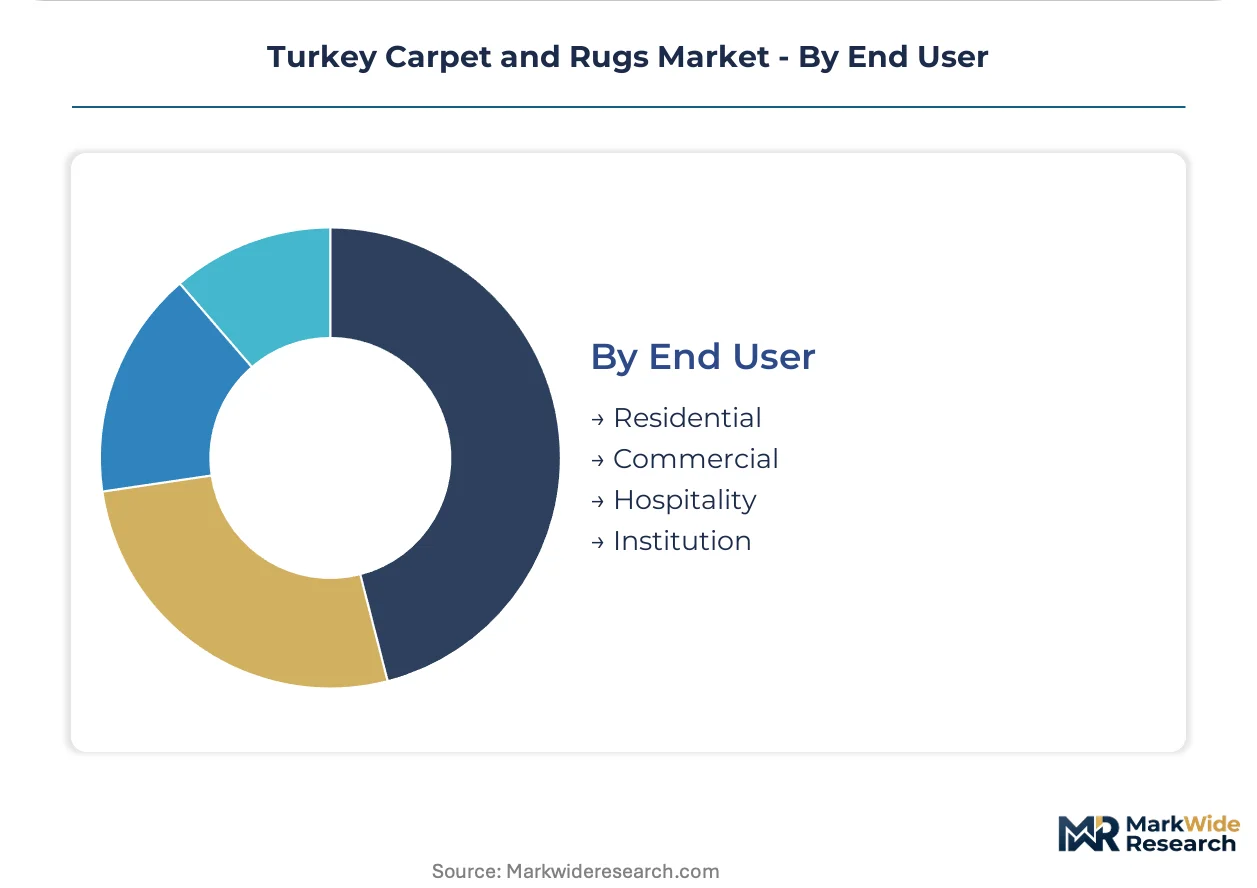
End User:
Procurement authority concentrates among technical facilities management consultancies as lifecycle cost models displace upfront square-meter pricing.
- Hospitality:Istanbul's hotel pipeline demands fire-rated carpet tiles with modular replacement capabilities, bundling maintenance contracts with initial material supply and compressing traditional distributor margins.
- Residential:Marmara region new construction exhibits displacement toward hard surface flooring, though Central Anatoria provinces show consumption gaps relative to per-capita income growth.
- Commercial:Corporate office fit-outs specify acoustic and ergonomic performance with rapid zonal replacement for churn management.
- Institution:Ankara hospital construction and educational facilities prioritize antimicrobial treatments and slip-resistant backing for regulatory compliance.
Residential channels maintain volume throughput while hospitality specification drives the steepest value-per-square-meter expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates among hospitality developers and facilities management consultancies across Turkey's manufacturing belt, with specification decisions increasingly bundling lifecycle maintenance contracts into initial material supply agreements.
Marmara Region
Istanbul's hotel pipeline and corporate office fit-outs drive fire-rated carpet tile demand through distributors serving domestic and re-export channels. TSE quality mark requirements align domestic production with EU REACH substance restrictions. Gaziantep manufacturing clusters supply synthetic broadloom to Rotterdam and Hamburg distribution hubs.
Central Anatolia
Konya and Kayseri provinces exhibit carpet consumption gaps relative to per-capita income growth, supporting distributor network expansion into underserved residential markets. The Ministry of Trade export incentive frameworks steer manufacturer compliance investments toward documented wool sourcing. Anatolian herding cooperatives face EU Deforestation Regulation chain-of-custody documentation requirements.
Aegean Region
Izmir textile trading channels concentrate cotton procurement for flat-weave dhurrie foundations and hand-knotted warp threads. REACH-compliant reactive dye imports from German and Swiss specialty chemical suppliers create input dependencies. Hereke ateliers produce ultra-premium silk collector pieces for Gulf and East Asian export markets.
Mediterranean Region
Antalya's tourism infrastructure sustains hospitality carpet replacement cycles alongside seasonal residential demand. BIS-equivalent TSE quality standards govern product labeling and flammability performance for domestic-bound production. Regional distributors face margin compression from lifecycle cost procurement models displacing upfront square-meter pricing.
Black Sea Region
Trabzon and Samsun port cities anchor re-export logistics for machine-made carpet shipments to Central Asian and Caucasus markets. Turkish Ministry of Trade certification requirements shape export-bound production compliance. Local manufacturing remains limited relative to Marmara and Gaziantep industrial concentrations.
Turkey Carpet and Rugs Market Competitive Landscape
Player mix skews toward vertically integrated domestic specialists with captive spinning and dyeing operations. Mid-scale manufacturers compete through design-led contemporary collections and hospitality sector program targeting. Three archetypes dominate: integrated producers controlling fiber-to-finished-goods workflows, design houses partnering European retail channels, and hospitality specialists bundling maintenance contracts. Competitive moves concentrate on automated tufting line expansion and consolidated dyehouse compliance investments.
Within the integrated production tier, Merinos leverages captive spinning and dyeing operations to sustain cost discipline across broadloom lines. Dinarsu anchors its market position through dedicated hospitality sector programs. Royal Halı competes via design-led contemporary collections distributed through European retail partnerships. These three exemplify the strategic divergence between scale-driven synthetic production and design-premium positioning.
| Leading Market Players |
|---|
| Merinos |
| Dinarsu |
| Royal Halı |
| Kaşmir Halı |
| Melikhan Carpets |
| Saray Hali |
| Milat Carpet |
| Kartal Hali |
| Festival Carpet |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with Australian wool auction indexation lock in raw material access for hand-knotted premium lines while exposing margins to pastureland volatility. These arrangements concentrate pricing power among Gaziantep and Istanbul manufacturers with documented TSE certification, compressing spot-market flexibility for smaller dyehouse operators serving the Marmara hospitality pipeline.
Pricing Analysis
Cost-plus contracts with Australian Wool Exchange indexation dominate hand-knotted wool procurement, while machine-made synthetic lines trade on volume-scaled per-square-meter baselines. Price differentiation hinges on OEKO-TEX certification tier and fire-rated performance grade. Cost compression in standard residential broadloom intensifies as recycled PET integration erodes virgin polyester premiums. Hospitality procurement teams exhibit lowest price sensitivity due to lifecycle cost bundling, whereas Central Anatolia residential buyers drive hardest bargain pressure.
Supply Chain Analysis
Inventory cycles stretch eight to fourteen weeks for REACH-compliant reactive dyes sourced from German and Swiss specialty chemical suppliers. Manufacturing concentrates in Turkey's Gaziantep and Istanbul clusters, with raw wool drawing from Australian auctions and Anatolian herding cooperatives. Single-source vulnerability sits with concentrated dye chemical import channels. Distribution runs through Rotterdam and Hamburg re-export hubs for EU-bound machine-made carpet shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among technical facilities management consultancies bundling lifecycle maintenance contracts, fragmenting traditional distributor influence across Istanbul's hospitality pipeline.
For Market Incumbents: Consolidate dyehouse compliance investments to capture dual TSE and OEKO-TEX certification premiums before EU Deforestation Regulation traceability mandates reshape wool sourcing verification. Lock in backward integration into captive spinning operations to defend margin position against recycled PET price erosion. Channel control through direct hospitality sector program targeting offers the strongest defensive lever.
For New Entrants and Emerging Players: Differentiate on digital printing convergence with tufting technology to serve boutique hotel chain short-run customization demand. White-space concentration sits in Central Anatolia's Konya and Kayseri provinces where carpet consumption gaps relative to per-capita income growth support distributor network expansion. Antimicrobial-treated carpet tile specification for Ankara hospital construction offers the most penetrable institutional entry point.
For Investors and Strategic Acquirers: Hospitality-specialized manufacturers with bundled maintenance contract capabilities represent the most defensible acquisition archetype for long-term positioning across the five-to-ten year window. Master weaver attrition and generational knowledge transfer discontinuity in Anatolian hand-knotting traditions signal structural supply constraint for premium wool lines. Watch for EU Deforestation Regulation implementation timeline acceleration as the key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Consolidated Dyehouse Compliance Investment | Dual TSE and OEKO-TEX certification unlocks Rotterdam and Hamburg re-export channel access. |
| Backward Integration into Captive Spinning | In-house polypropylene and polyester fiber production sustains cost discipline against rPET price erosion. |
| Digital Printing-Tufting Convergence | Piezo inkjet patterning enables short-run customization for Istanbul boutique hotel procurement teams. |
| Antimicrobial Carpet Tile Development | Infection control protocols in Ankara hospital construction pull specification toward modular systems. |
| Central Anatolia Distributor Expansion | Konya and Kayseri network buildout captures consumption gaps relative to per-capita income growth. |
Research Methodology
Initial hypotheses were tested against primary input from carpet manufacturing plant managers, hospitality procurement directors, dyehouse technical leads, and Istanbul distributor principals and refined through secondary validation against Turkish Ministry of Trade export statistics, TSE certification databases, EU REACH substance restriction filings, and customs trade data. Bottom-up production capacity modeling triangulated against top-down hospitality construction pipeline tracking.
Variance decomposition across product type, material fiber, design style, and end-user segment dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume and value build-ups incorporating synthetic fiber substitution rates, wool price auction volatility, and hospitality refurbishment cycle timing. Forecast inputs included Gaziantep manufacturing cluster capacity utilization and Rotterdam re-export channel throughput.
Material uncertainties — EU Deforestation Regulation implementation scope, Australian wool auction volatility, and hard surface flooring substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market