
 Hearth Market | 2026-2036
Hearth Market Size, Share, and Industry Trends Forecast 2026-2036
Hearth Market Intelligence
The US Environmental Protection Agency's New Source Performance Standards for residential wood heaters is pivoting consumer preference toward cleaner fuel sources. This regulatory pressure creates opportunities for manufacturers focused on high-efficiency gas and electric units. Hearth & Home Technologies leverages its extensive brand portfolio to offer a diverse product mix. Napoleon Group specializes in advanced gas fireplace technology, while HNI Corporation competes through its strong North American distribution network.
A hearth is an appliance designed for residential or commercial heating and ambiance, encompassing fireplaces, stoves, and inserts. These systems are characterized by their fuel type, heat output measured in British Thermal Units (BTUs), and construction materials like cast iron or steel. Electric fireplaces show significant adoption due to their ease of installation and minimal maintenance requirements. While residential heating remains the primary application, the use of hearths for commercial ambiance in hotels and restaurants is expanding.
Product design and market access are shaped by stringent environmental regulations. The EU's Ecodesign Directive and the EPA's standards in the United States mandate specific efficiency levels and particulate emission limits for solid fuel appliances. Compliance with standards from bodies like CSA Group in Canada is also critical for market entry. Future success depends on developing products that balance high-performance heating, aesthetic appeal, and adherence to evolving emissions regulations.
Market Dynamics
The hearth market's evolution is governed by the structural shift towards cleaner fuel sources, driven by stringent environmental regulations. This force creates a fundamental tension between the traditional demand for wood-burning ambiance and the modern imperative for energy efficiency and minimal emissions.
Growth Catalysts
- Ecodesign Directive:The EU's Ecodesign framework mandates higher efficiency and lower emissions for solid fuel appliances, compelling a transition towards compliant gas, electric, and advanced wood-burning technologies across member states.
- Hospitality Sector Demand:Hotels, restaurants, and resorts increasingly install hearth products, particularly gas and electric models, to create a welcoming ambiance and enhance customer experience without the maintenance of traditional wood fireplaces.
- Electric Fireplace Simplicity:The ease of installation and zero-clearance requirements for electric fireplaces allow for their adoption in a wider range of residential settings, including apartments and condominiums where venting is not feasible.
Market Restraints
- High Upfront Costs:Advanced, high-efficiency gas and certified low-emission wood-burning units carry a significant price premium over traditional models, limiting adoption among price-sensitive consumers.
- Regulatory Compliance Burden:Navigating and certifying products for multiple distinct regulatory regimes, such as the EPA standards in the United States and CE marking in Europe, adds significant cost and complexity.
- Substitution by HVAC Systems:High-efficiency central heating and cooling systems represent a primary substitute for hearths as a primary heat source, competing on utility and energy cost rather than ambiance.
Strategic Opportunities
- Smart Home Integration:Incorporating IoT connectivity and voice control into gas and electric fireplaces creates opportunities for integration with home automation systems, appealing to tech-savvy consumers seeking convenience.
- Outdoor Living Spaces:The expansion of outdoor living areas like patios and decks in residential construction presents a significant growth market for durable, weather-resistant outdoor fireplaces and fire pits.
- Retrofit and Renovation Market:Developing easy-to-install inserts that can upgrade inefficient, old masonry fireplaces to meet modern emission standards offers access to a large, established housing stock in North America and Europe.
Industry Challenges
- Installation Skill Gap:The increasing technical complexity of modern gas and smart electric hearths requires a specialized installer base, and shortages of qualified technicians can create installation backlogs and service issues.
- Supply Chain Volatility:Sourcing critical components, including specialized glass, high-grade steel, and electronic control modules, is subject to price fluctuations and disruptions that can impact production schedules and margins.
- Certification Timelines:The lengthy and rigorous testing and certification processes required by bodies like the CSA Group and for EPA compliance can delay new product introductions and market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearth Market |
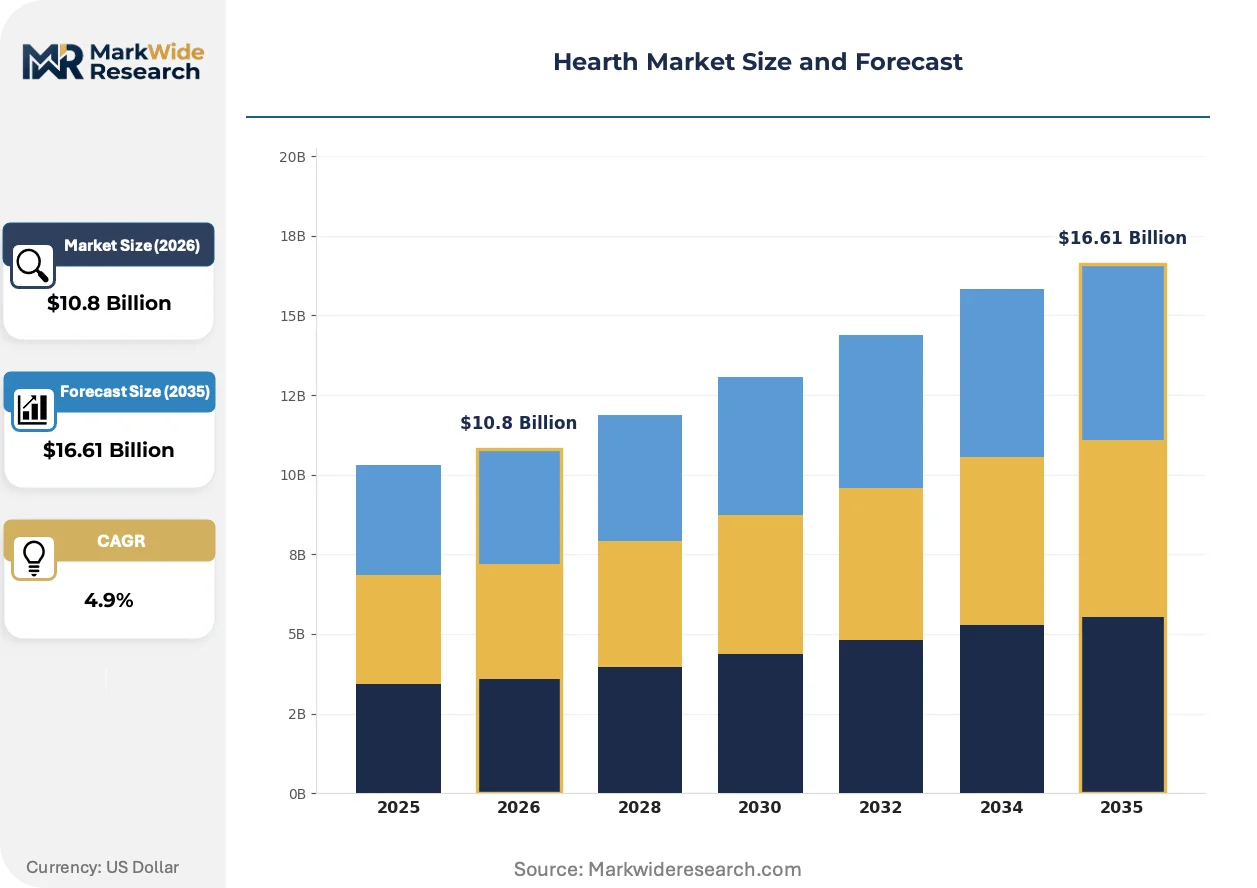
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $16.61 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Burning Stoves, Gas Fireplaces, Electric Fireplaces, Pellet Stoves, Ethanol Fireplaces Fuel Type: Wood Pellets, Natural Gas, Propane, Electricity, Bioethanol Application: Residential Heating, Commercial Ambiance, Outdoor Heating, Cabin Warmers, Recreational Areas End User: Homeowners, Property Managers, Hospitality Venues, Vacation Rentals, Specialty Retailers |
| Companies Covered | Hearth & Home Technologies, Empire Comfort Systems Inc., HNI Corporation, FPI Fireplace Products International Ltd., Innovative Hearth Products, Napoleon Group, Glen Dimplex, HPC Fire Inspired, Travis Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearth Market Strategic Shifts & Innovations
Product innovation in the hearth market is defined by the dual pursuit of enhanced aesthetic realism and adherence to tightening environmental standards. This drives development away from traditional combustion and toward controlled, clean, and connected thermal appliances.
Smart control technology provides digital management of flame height, heat output, and lighting effects via remote or mobile applications. Residential customers in new builds and major renovations are the primary adopters, seeking convenience and precise customization. This advanced user interface is converging with whole-home automation platforms, transforming the hearth from a standalone appliance into an integrated component of the connected living environment.
Regulatory frameworks like the U.S. Environmental Protection Agency's New Source Performance Standards (NSPS) are fundamentally altering product portfolios. These standards impose strict particulate emission limits on new residential wood heaters, rendering many older designs obsolete. The U.S. market is most affected, with manufacturers pivoting research and development resources toward compliant pellet stoves and high-efficiency gas and electric alternatives.
A notable behavioral shift is the prioritization of linear, minimalist aesthetics in product selection, especially in the premium segment. This design-centric purchasing trend is displacing the market for traditional, bulky masonry-style fireplaces with sleek, integrated gas and electric units. The preference for clean lines and flush-wall installations is most visible within the architectural and interior design communities specifying products for luxury homes and commercial spaces in Europe and North America.
Hearth Market Segmentation
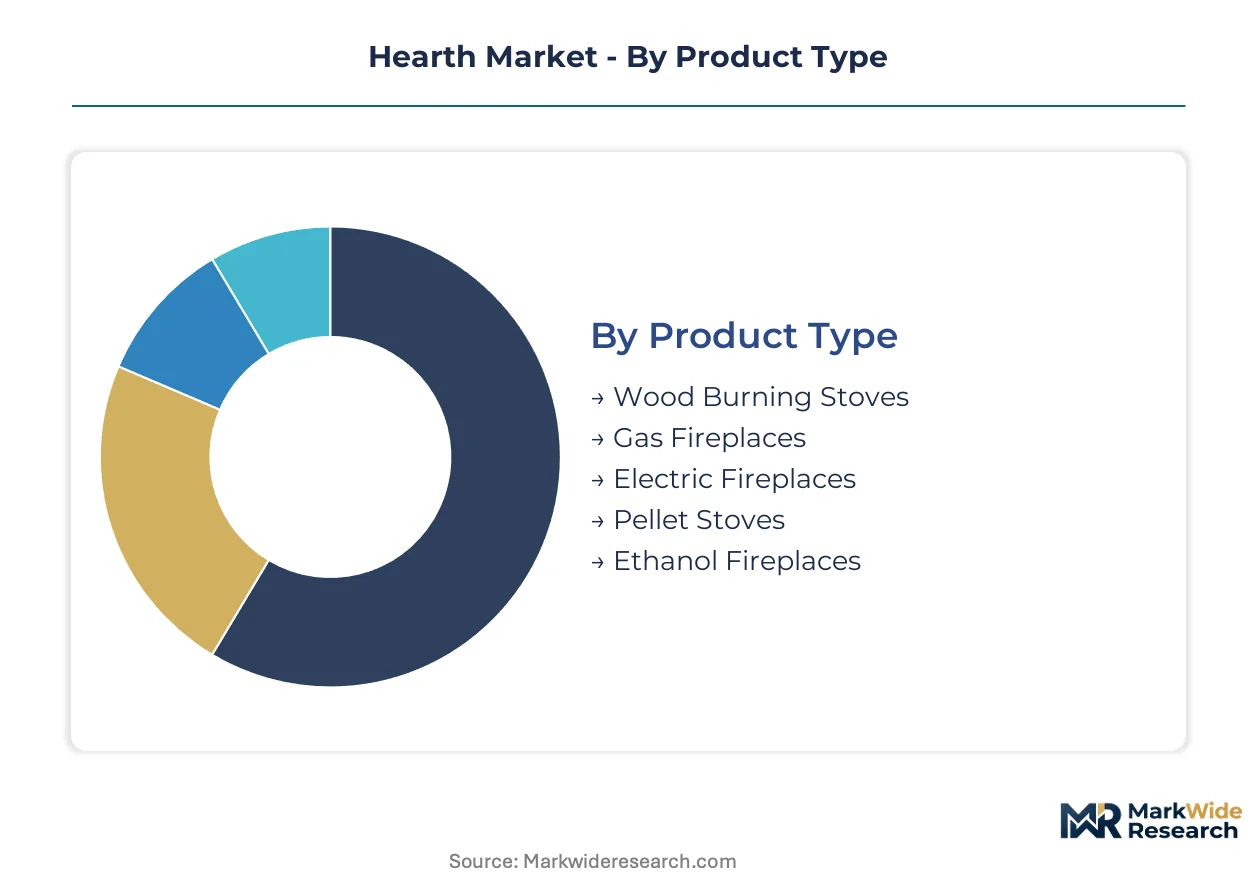
Market segmentation provides a granular view of the hearth industry, highlighting the distinct product offerings, fuel sources, applications, and end-user demands that collectively shape its structure. Understanding these divisions is crucial for manufacturers to tailor product development and for distributors to optimize market access strategies.
Product Type:
The customization-versus-standardization spectrum significantly influences product type offerings in the hearth market, ranging from bespoke installations to mass-produced units.
- Electric Fireplaces:These units operate by heating coils and often use LED technology to simulate flames, requiring no venting. Demand concentrates in urban residential settings and apartments, driven by ease of installation and minimal maintenance requirements.
- Gas Fireplaces:These appliances burn natural gas or propane, providing consistent heat and realistic flame effects, often with remote control options. North American homeowners increasingly prefer these for their convenience and cleaner burn compared to traditional wood.
- Wood Burning Stoves:These traditional heating units burn seasoned firewood, typically constructed from cast iron or steel for radiant heat.
- Pellet Stoves:These stoves combust compressed wood pellets, offering efficient, automated heating with lower emissions than traditional wood stoves.
- Ethanol Fireplaces:These ventless units burn bioethanol fuel, offering decorative flames without the need for chimneys or gas lines.
Leading the category by volume: Wood Burning Stoves. Growing fastest: Electric Fireplaces.
Fuel Type:
Cost tiering and availability shape the fuel type landscape, dictating consumer choices based on upfront investment and ongoing operational expenses.
- Electricity:This fuel type powers electric fireplaces and inserts, offering instant heat and flame effects without combustion. Homeowners in regions with accessible electrical grids prioritize this for its zero emissions at the point of use and simple operation.
- Natural Gas:Delivered via pipeline, natural gas fuels efficient gas fireplaces and stoves, offering a clean-burning and readily available energy source. Its widespread infrastructure in developed markets like the United States makes it a preferred option for convenience and lower operating costs.
- Wood Pellets:These compacted biomass fuels provide a renewable and efficient energy source for specialized pellet stoves.
- Propane:Stored in tanks, propane offers a versatile fuel option for gas hearths in areas without natural gas lines.
- Bioethanol:This alcohol-based fuel offers a clean-burning, ventless solution for decorative fireplaces.
The segment with the highest penetration is Natural Gas, while Electricity demonstrates the most rapid expansion.
Application:
The application focus varies significantly, from essential primary heating to purely aesthetic enhancements across diverse environments.
- Residential Heating:Hearth products provide supplemental or primary heating for homes, improving comfort and reducing reliance on central HVAC systems. Homeowners in colder climates utilize these for efficient zone heating and ambiance, particularly with high-efficiency gas and pellet stoves.
- Commercial Ambiance:Businesses such as hotels, restaurants, and retail spaces install hearths to create welcoming environments and enhance customer experience. Hospitality venues in Europe and North America increasingly adopt electric and gas models for their low maintenance and consistent aesthetic appeal.
- Outdoor Heating:Hearth products like fire pits and outdoor fireplaces extend the usability of patios and decks in residential and commercial settings.
- Cabin Warmers:Compact and robust hearths provide essential heating for remote cabins and vacation homes, often using wood or propane.
- Recreational Areas:Public and private recreational facilities integrate hearths for gathering spaces and warmth in common areas.
Primary demand originates from Residential Heating, with Commercial Ambiance exhibiting the strongest upward trend.
End User:
Customer type dictates product features and service requirements, ranging from individual consumer needs to large-scale commercial procurement.
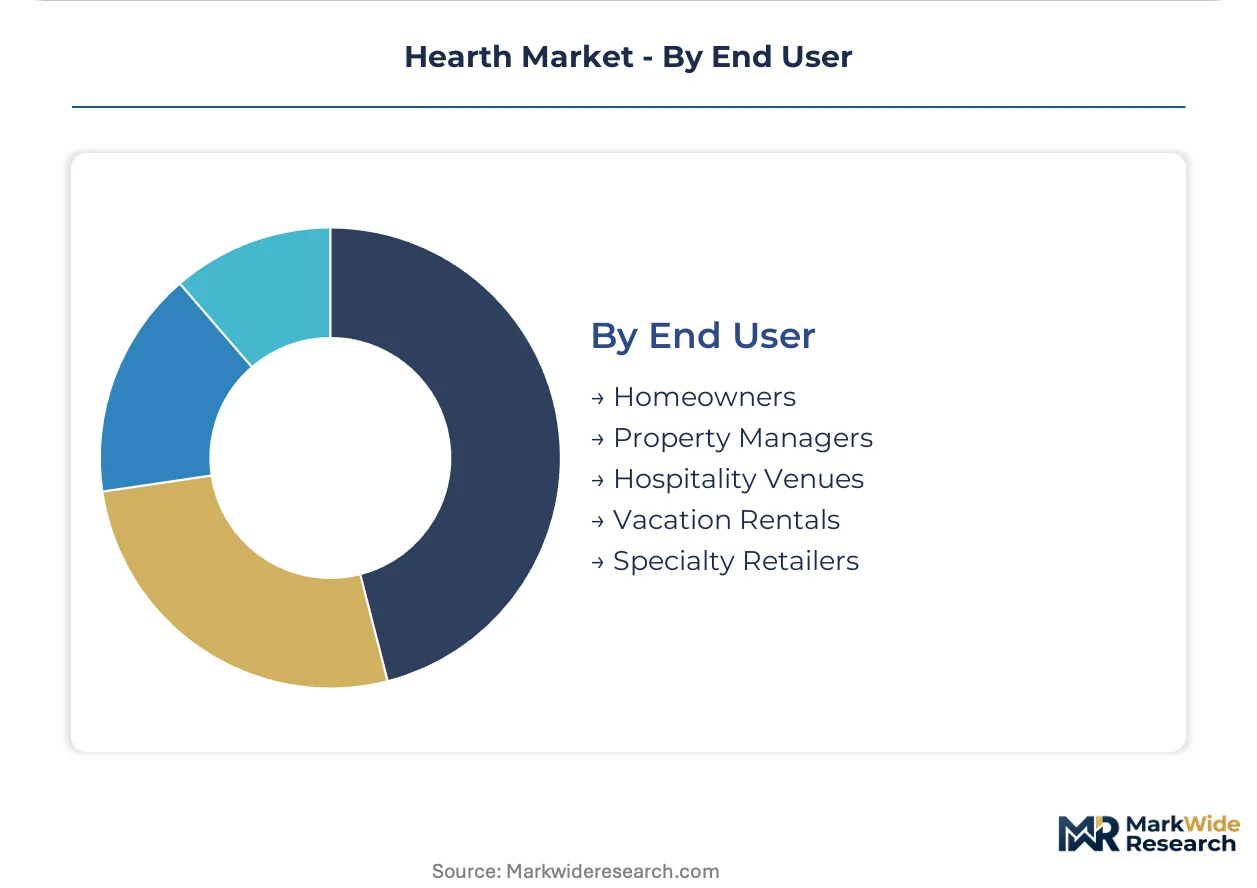
- Homeowners:Individual residents purchase hearth products for personal residences, prioritizing aesthetic appeal, heating efficiency, and ease of use. The retrofit and renovation market in North America represents a significant opportunity for upgrading existing fireplaces.
- Hospitality Venues:Hotels, resorts, and restaurants procure hearth solutions to enhance guest experience and interior design. These establishments often select electric or gas units for their minimal maintenance and ability to meet strict safety standards.
- Property Managers:These professionals oversee multi-unit residential or commercial buildings, often specifying hearths for common areas or rental units.
- Vacation Rentals:Owners of rental properties install hearths to increase property appeal and provide amenities for guests.
- Specialty Retailers:These businesses distribute hearth products, often providing installation services and expert advice to a diverse customer base.
The largest consumer base resides within Homeowners, as Hospitality Venues capture significant new market opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Midwest manufacturing belt in the United States forms a critical cluster for hearth product innovation and production. This region's manufacturers respond to evolving consumer preferences and stringent environmental regulations. Demand for cleaner burning and aesthetically pleasing heating solutions influences product development across global markets.
United States
Demand for cleaner burning gas and electric fireplaces is strong among homeowners in the United States. The EPA's New Source Performance Standards for residential wood heaters mandate lower emissions. Manufacturers in Minneapolis, Minnesota, focus on developing high-efficiency gas and electric units for the North American market.
Germany
German consumers prioritize energy efficiency and aesthetic integration in their hearth product selections. The EU's Ecodesign Directive compels manufacturers to develop highly efficient and low-emission appliances. Production facilities near Stuttgart, Germany, concentrate on advanced gas and electric fireplace technologies for the European market.
Canada
Canadian homeowners seek reliable heating solutions for diverse climates, driving demand for both traditional and modern hearths. Compliance with CSA Group standards is essential for all heating appliances sold across Canada. Companies in Quebec, Canada, specialize in robust wood-burning stoves and high-efficiency pellet stoves for colder regions.
China
Beijing and other major Chinese cities exhibit rising demand for electric and gas fireplaces in new residential developments. China's dual carbon goals and environmental protection policies influence the adoption of cleaner heating technologies. Manufacturing hubs in Guangdong province, China, produce a wide range of electric and bioethanol fireplaces for domestic and export markets.
United Kingdom
British homeowners are increasingly choosing electric and gas hearths for convenience and modern design aesthetics. The UK's adherence to Ecodesign principles, similar to the EU, promotes efficient and low-emission heating solutions. London's architectural and interior design community specifies sleek, integrated electric and gas units for luxury homes and commercial spaces.
Hearth Market Key Industry Players
Premium-margin players sit above commodity-margin players across the spectrum of product complexity and regulatory compliance. The hearth market exhibits a tiered structure, with specialized manufacturers focusing on high-efficiency, design-centric, and smart-enabled units. Archetypes include traditional wood stove manufacturers, advanced gas fireplace specialists, and electric hearth innovators emphasizing ease of installation. Portfolio diversification into cleaner fuel types and strategic partnerships for distribution network expansion are dominant competitive moves among these firms.
On the premium-tier vector, Hearth & Home Technologies, an Inc.-structured entity, represents a diversified portfolio approach across various hearth product categories. Napoleon Group, a Canada-based firm, exemplifies specialization in advanced gas fireplace technology and innovative design solutions. HNI Corporation, another Inc.-structured company, occupies a strong position within the North American market, leveraging its extensive distribution network for a broad product mix. These players anchor the market's evolution towards cleaner, more connected, and aesthetically refined heating solutions, influencing industry standards and consumer expectations.
| Leading Market Players |
|---|
| Hearth & Home Technologies |
| Empire Comfort Systems Inc. |
| HNI Corporation |
| FPI Fireplace Products International Ltd. |
| Innovative Hearth Products |
| Napoleon Group |
| Glen Dimplex |
| HPC Fire Inspired |
| Travis Industries Inc. |
| Others |
Cost & Logistics Intelligence
Vertical integration into specialized component manufacturing anchors supply stability for premium hearth manufacturers, enabling them to exert greater control over pricing and quality differentiation.
Pricing Analysis
Value-based pricing for hearth products ties directly to the ambiance generated and the heating efficiency provided. The dominant pricing structure is per-unit transactional, influenced by product type and fuel source. Price differentiation stems from aesthetic design complexity and compliance with stringent environmental certifications like EPA standards and CE marking. Pricing softness reflects competition from central HVAC systems, with homeowners for traditional wood stoves exhibiting the most price sensitivity compared to hospitality venues seeking premium features.
Supply Chain Analysis
Domestic-content mandates for appliances in regions like North America reshape sourcing strategies for hearth manufacturers. Geographic supply concentration for critical components like specialized glass and high-grade steel centers on China, Germany, and the United States. A structural risk involves commodity price volatility for metals. Distribution runs through a network of specialty retailers and home improvement chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hearth market presents a supply-constrained opportunity, particularly for advanced, compliant units. Specialized glass and electronic control module manufacturing capacity bottlenecks currently prop up pricing for high-efficiency models.
For Market Incumbents: To counter the threat of stringent environmental regulations and rising raw material costs, incumbents should deepen vertical integration into specialized component manufacturing. Expanding R&D efforts into advanced gas and electric fireplace technologies, particularly for smart home integration, can differentiate product portfolios. Investing in installer training programs will also mitigate the installation skill gap and reinforce brand reputation.
For New Entrants and Emerging Players: Capture the retrofit and renovation market by offering easy-to-install electric inserts for existing masonry fireplaces. The underpenetrated apartment and condominium segment, particularly in urban European and North American centers, represents a viable white-space target. A direct-to-consumer online sales model, coupled with local installation partnerships, can accelerate market entry.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized manufacturers of high-efficiency gas and electric units with strong intellectual property. The market demonstrates long-term viability, driven by regulatory tailwinds and consumer preference for ambiance. An attractive acquisition target archetype is a mid-cap firm with robust distribution networks in North America or Europe. The signal to watch is accelerating adoption of smart home integrated hearth products.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Expansion | Develop advanced electric models with enhanced aesthetic realism. |
| Certification Investment | Secure CE marking and EPA compliance for new solid fuel appliances. |
| Smart Home Integration | Embed IoT connectivity for remote control of gas fireplaces. |
| Channel Partnership | Establish alliances with residential construction developers in the US. |
| Supply Chain Diversification | Source specialized glass and steel from multiple global regions. |
Research Approach
Independent corroboration across industry association reports, regulatory body publications like EPA and EU Ecodesign documents, and company financial disclosures underwrites the qualitative findings. Primary research involved interviews with hearth product manufacturers, distributors, architectural designers, and residential contractors. This approach combined insights from key industry stakeholders with secondary validation, employing both bottom-up and top-down triangulation.
Rate-of-change decomposition modeled market expansion by product type, fuel source, application, and end-user segments across the analysis window. This framework incorporated regulatory impacts from the EPA and EU Ecodesign Directive. Compound Annual Growth Rates were derived from historical trends and projected technological shifts, with inputs including housing starts and commercial construction spending.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving environmental regulations and fluctuating energy prices. Forecasts reflect documented assumptions regarding technological advancements and consumer behavior shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Christmas Tree Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Wall Art Market
Homecare and Decor
Europe Decorative Laminates Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Home Decor Market