
 Ethyl Chloride Market | 2026-2036
Ethyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Chloride Market Foresight
Buyer concentration in the hospital procurement segment is broadening as group purchasing organizations consolidate anesthesia supply contracts while independent surgical centers fragment purchasing across regional distributors. The Dow Chemical Company leverages integrated chlor-alkali infrastructure to sustain cost-competitive feedstock positions. Lanxess anchors European supply through specialized pharmaceutical-grade purification capabilities. BASF SE competes on backward integration into ethylene oxide derivatives, securing captive ethyl chloride for downstream specialties.
Ethyl chloride is a volatile chloroethane compound (C₂H₅Cl) manufactured via hydrochlorination of ethylene or catalytic addition of hydrogen chloride to ethylene, with a boiling point of 12.3°C that enables rapid vaporization for topical anesthetic and refrigerant applications. Its primary industrial purpose spans medical spray formulations, solvent extraction in pharmaceutical synthesis, and intermediate production for tetraethyl lead alternatives and cellulose derivatives. The aerosol product type dominates current revenue as topical anesthetic sprays command premium pricing in emergency medicine and dermatology. Solvent applications represent the fastest-growing structural segment, driven by demand from research institutions performing nucleophilic substitution reactions and extraction protocols. Liquid charcoal formulations remain a mature niche with stable but limited volume in veterinary and historical medical contexts.
The United States Environmental Protection Agency regulates ethyl chloride under the Clean Air Act as a volatile organic compound, while the Food and Drug Administration governs pharmaceutical aerosol purity and labeling standards for human anesthetic use. In Europe, the European Chemicals Agency classifies chloroethane under REACH substance evaluation protocols, with the European Medicines Agency setting impurity thresholds for medical-grade material. Stakeholders must monitor evolving refrigerant phase-down schedules under the F-Gas Regulation and corresponding state-level restrictions, as these frameworks will redirect industrial ethyl chloride volumes toward medical and laboratory end uses.
Market Dynamics
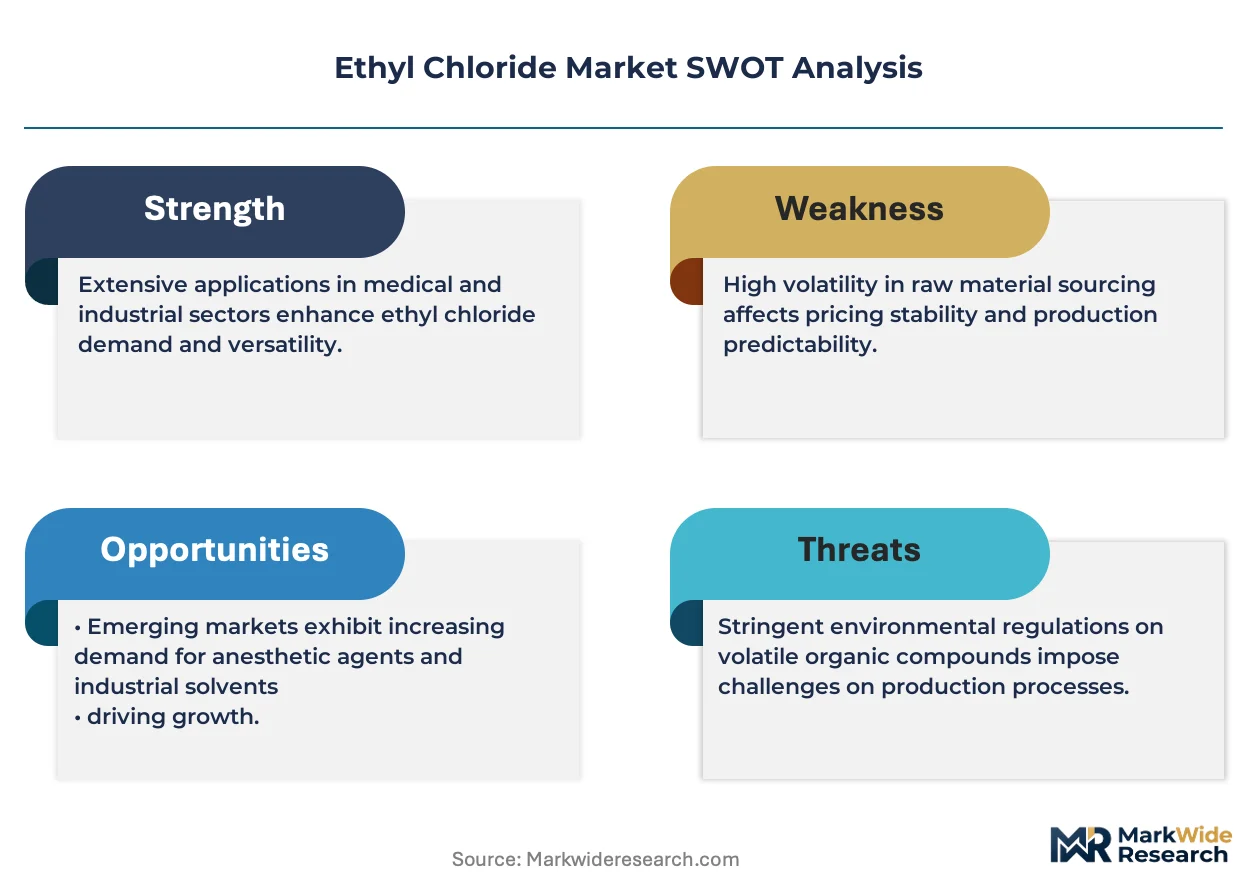
REACH substance evaluation protocols and EPA emissions guidelines are tightening purity thresholds for pharmaceutical-grade ethyl chloride, forcing purification technology upgrades across integrated chlor-alkali producers and specialized refiners.
Growth Catalysts
- Topical anesthetic protocols:Hospital networks and outpatient surgical centers are expanding spray-based pain management applications for emergency medicine and dermatology procedures.
- F-Gas Regulation phase-down:The European Union's refrigerant restrictions are redirecting industrial chloroethane volumes toward medical aerosol and laboratory solvent end uses.
- Research institution demand:Nucleophilic substitution protocols in pharmaceutical synthesis are driving solvent consumption across university and contract research organization laboratories.
Market Restraints
- Ethylene feedstock volatility:Hydrochlorination economics depend on ethylene pricing from naphtha cracking and shale gas derivatives, creating margin compression for non-integrated producers.
- Chinese supply concentration:Domestic chloroethane capacity in China feeds both refrigerant intermediate and medical aerosol supply chains, creating geographic single-point vulnerability.
- Refrigerant substitution:Hydrofluoroolefin and natural refrigerant technologies are displacing chloroethane-based systems in industrial cooling applications.
Strategic Opportunities
- Veterinary liquid charcoal formulations:Stable-volume niche applications in animal care represent underexploited demand outside human pharmaceutical channels.
- Cellulose derivative intermediates:Ethyl cellulose production for controlled-release drug coatings offers captive demand expansion for pharmaceutical-grade material.
- Contract manufacturing channels:Regional distributors serving independent surgical centers are consolidating anesthesia supply relationships outside group purchasing organization dominance.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA aerosol purity standards and EMA impurity threshold compliance require extended validation cycles for new production facilities.
- Specialized purification talent:Chloroethane refining expertise for medical-grade specifications remains concentrated among legacy European and North American operators.
- Clean Air Act VOC compliance:EPA volatile organic compound regulations mandate emissions control investments that strain smaller batch producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Chloride Market |
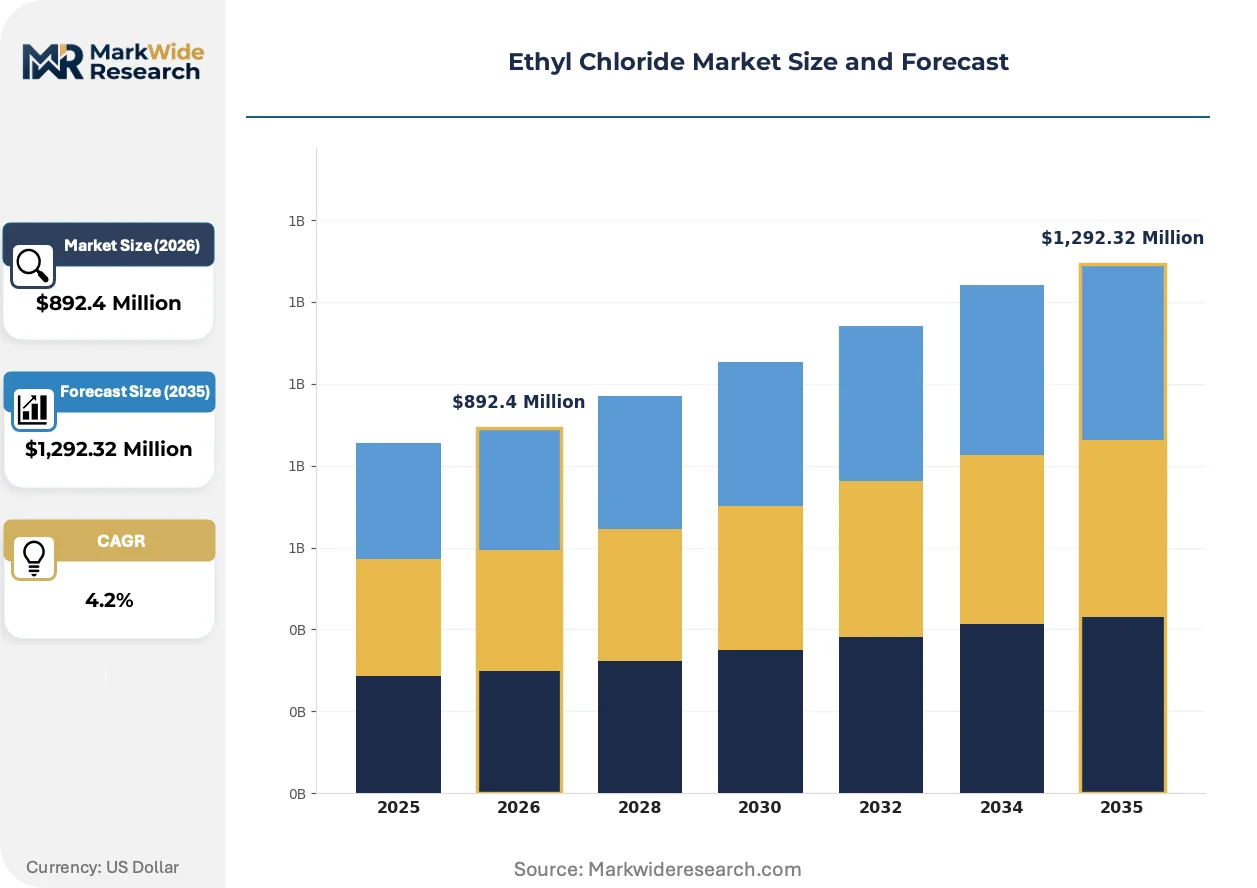
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,292.32 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosols, Solvents, Liquid Charcoal, Anesthetics Application: Medical, Industrial Cleaning, Laboratory Use, Refrigeration End User: Pharmaceuticals, Research Institutions, Manufacturing Plants, Hospitals Delivery Mode: Liquid, Gas, Compressed, Syringe |
| Companies Covered | The Dow Chemical Company, Chloritech Industries, Lanxess, BASF SE, Sumitomo Chemical, Westlake Corporation, Jiangsu Yinzhu Chemical, The Linde Group, Hebei Jianxin Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Chloride Market Shifts & Advancements
Membrane-based purification systems and continuous hydrochlorination reactor designs are compressing cost structures for pharmaceutical-grade material while regulatory phase-downs redirect technical chloroethane toward specialized medical and laboratory channels.
Continuous flow hydrochlorination reactor technology is rewriting production economics for pharmaceutical-grade ethyl chloride. Integrated chlor-alkali operators in Germany and the United States are retrofitting batch facilities with continuous systems to reduce energy intensity and impurity carryover. This technology is compressing the cost gap between industrial-grade and medical-grade material, enabling mid-scale producers to enter pharmaceutical aerosol supply chains previously reserved for specialized refiners.
The European Union F-Gas Regulation and corresponding state-level restrictions in California and Massachusetts are accelerating refrigerant application decline. Industrial chloroethane volumes are rotating toward solvent extraction and intermediate production as cooling system manufacturers abandon ozone-depleting and high-global-warming-potential substances. Medical aerosol and laboratory end uses are absorbing displaced capacity, though purification upgrade investments lag the regulatory timeline by eighteen to thirty-six months.
Group purchasing organizations are consolidating anesthesia supply contracts across hospital networks while independent surgical centers fragment purchasing across regional distributors. This bifurcation is creating parallel procurement channels with divergent service expectations: integrated health systems demand inventory management and compliance documentation, while standalone facilities prioritize just-in-time delivery flexibility. The United States exhibits the most pronounced channel stratification, with distributor specialization deepening between health-system-focused and ambulatory-surgery-center-focused intermediaries.
Ethyl Chloride Market Segmentation
Ethyl chloride segmentation reveals how purification standards and delivery specifications fragment supply chains across medical and industrial channels. Each dimension carries distinct regulatory burdens and margin structures that reshape procurement patterns for integrated producers and specialized refiners.
Product Type:
Upgrade cycles for pharmaceutical-grade purification systems are compressing the cost gap between industrial and medical specifications, enabling mid-scale producers to cross into aerosol supply chains previously reserved for specialized operators.
- Aerosols:Pressurized spray formulations containing pharmaceutical-grade chloroethane deliver rapid vaporization for topical anesthesia in emergency medicine and dermatology. Hospital networks in the United States and outpatient surgical centers in Germany are expanding spray-based pain management protocols, tightening purity documentation requirements.
- Solvents:High-purity liquid chloroethane serves nucleophilic substitution reactions and extraction protocols in pharmaceutical synthesis. Research institutions across Massachusetts and California are driving consumption as laboratory demand absorbs capacity displaced from refrigerant phase-downs.
- Liquid Charcoal:Veterinary and historical medical formulations maintain stable but limited volume.
- Anesthetics:Human-grade injectable and inhalation preparations require EMA and FDA certification cycles.
Aerosols sit at the top of the volume ranking, with solvents climbing the fastest as refrigerant restrictions redirect industrial capacity toward laboratory end uses.
Application:
Cost tier differentiation separates premium pharmaceutical aerosols from commodity industrial cleaning formulations, with certification grade determining price multiples rather than raw material input costs.
- Medical:Topical anesthetic sprays and surgical preparations command the highest purity thresholds under FDA aerosol standards and EMA impurity protocols. Emergency departments in Texas and dermatology clinics in France are expanding spray-based pain management, consolidating procurement through group purchasing organizations.
- Industrial Cleaning:Degreasing and precision cleaning applications face EPA volatile organic compound compliance burdens and refrigerant substitution pressures.
- Laboratory Use:Extraction solvents for nucleophilic substitution reactions are expanding most quickly across university and contract research organization facilities.
- Refrigeration:Cooling system applications are contracting under F-Gas Regulation phase-downs and state-level restrictions in California.
Medical applications command the highest margin tier, with laboratory use expanding most quickly as research institutions absorb redirected chloroethane capacity.
End User:
Customer type fragmentation splits procurement between consolidated health systems demanding compliance documentation and independent facilities prioritizing delivery flexibility.
- Pharmaceuticals:Controlled-release drug coating manufacturers consume ethyl chloride for ethyl cellulose intermediate production, requiring captive supply arrangements with integrated chlor-alkali operators.
- Research Institutions:University laboratories and contract research organizations in Massachusetts and Baden-Württemberg are expanding nucleophilic substitution protocol volumes.
- Manufacturing Plants:Industrial cellulose derivative and refrigerant intermediate producers face feedstock volatility from ethylene pricing swings.
- Hospitals:Integrated health systems in the United States consolidate anesthesia supply contracts through group purchasing organizations while independent surgical centers fragment purchasing across regional distributors.
Hospitals generate the largest absolute demand, with research institutions gaining share fastest as laboratory applications absorb displaced refrigerant volumes.
Delivery Mode:
Supply concentration in compressed and gas formats favors integrated producers with captive chlor-alkali infrastructure, while liquid and syringe formats enable specialized refiners to compete on purification expertise.
- Liquid:Bulk pharmaceutical-grade and industrial-grade chloroethane in pressurized containers serves manufacturing plants and research institutions requiring metered dispensing for synthesis protocols.
- Gas:Vapor-phase delivery systems for industrial cleaning and specialized laboratory applications require emissions control investments for Clean Air Act compliance.
- Compressed:Aerosol propellant systems dominate medical spray formulations, with FDA purity standards and labeling requirements extending validation timelines for new production facilities.
- Syringe:Pre-filled single-use units for veterinary and niche human anesthetic applications represent a stable-volume specialty channel.
Compressed delivery sits at the top of the volume ranking, with liquid formats climbing the fastest as batch producers retrofit continuous hydrochlorination systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest production footprint while the United States maintains the most stringent pharmaceutical-grade certification requirements, creating divergent competitive dynamics across major supply basins.
United States
Hospital networks in Texas and California are consolidating anesthesia procurement through group purchasing organizations, expanding spray-based pain management protocols. The EPA regulates chloroethane under Clean Air Act volatile organic compound standards, mandating emissions control investments for producers. The Gulf Coast petrochemical corridor anchors integrated chlor-alkali operations feeding both domestic medical aerosol and export refrigerant intermediate demand.
Germany
Research institutions in Baden-Württemberg and North Rhine-Westphalia are driving solvent consumption for nucleophilic substitution protocols in pharmaceutical synthesis. The F-Gas Regulation redirects industrial chloroethane volumes toward medical and laboratory end uses, tightening supply availability. Lanxess maintains specialized pharmaceutical-grade purification capabilities in the Cologne-Leverkusen chemical cluster, serving EMA-certified aerosol formulations.
China
Domestic chloroethane capacity in Jiangsu and Shandong provinces feeds both refrigerant intermediate and medical aerosol supply chains, creating geographic concentration risk. The Ministry of Ecology and Environment enforces dual carbon goals that constrain energy-intensive hydrochlorination expansion. The Yangtze River Delta industrial corridor hosts integrated producers supplying regional pharmaceutical manufacturers and export markets.
Japan
PMDA certification timelines for pharmaceutical-grade material favor established producers with validated quality systems. METI industrial policy supports solvent applications in precision chemical manufacturing over declining refrigerant uses. The Osaka-Kobe chemical cluster maintains specialized refining expertise for medical-grade chloroethane serving domestic pharmaceutical aerosol demand.
India
CDSCO regulatory pathways for imported pharmaceutical-grade ethyl chloride are lengthening validation cycles for new supply relationships. The country's national pharmaceutical regulator emphasizes impurity documentation for topical anesthetic registrations. Maharashtra and Gujarat chemical zones are developing chlor-alkali integration to reduce dependence on Chinese material for cellulose derivative intermediates.
Ethyl Chloride Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a bifurcated structure where integrated chlor-alkali operators hold feedstock cost advantages while specialized refiners command pharmaceutical-grade premiums. The vendor base clusters around three strategic archetypes: multinational chemical conglomerates with backward integration into ethylene derivatives, regional specialists with purification expertise for medical specifications, and Chinese producers leveraging domestic scale for industrial-grade material. Competitive moves concentrate on continuous hydrochlorination technology licensing and purification capacity expansion to capture rotating demand from refrigerant phase-downs.
Within the multinational tier, The Dow Chemical Company and BASF SE exemplify integrated operators with captive ethylene positions, while Lanxess occupies a specialized refining position for European pharmaceutical-grade supply. Jiangsu Yinzhu Chemical and Hebei Jianxin Chemical represent Chinese producers serving regional industrial and export medical demand.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Chloritech Industries |
| Lanxess |
| BASF SE |
| Sumitomo Chemical |
| Westlake Corporation |
| Jiangsu Yinzhu Chemical |
| The Linde Group |
| Hebei Jianxin Chemical |
| Others |
Supply & Pricing Matrix
Continuous hydrochlorination reactor retrofits across integrated chlor-alkali facilities in Germany and the United States are compressing production economics while concentrating pharmaceutical-grade supply among operators with capital-scale advantages. This technology transition simultaneously lowers unit costs for medical aerosol material and raises barriers for batch producers, reshaping competitive positioning across purification tiers.
Pricing Analysis
Capacity additions in China are reshaping price floors for industrial-grade chloroethane while pharmaceutical-grade premiums widen. Three-tier pricing structure across pharmaceutical, laboratory, and industrial certification levels anchors the market, with FDA and EMA compliance tiers commanding substantial markups over technical specifications. Price differentiation hinges on impurity documentation and validation timeline guarantees. Cost compression in industrial grades is intensifying because Chinese domestic capacity expansion outpaces refrigerant demand contraction. Independent surgical centers exhibit highest price sensitivity; integrated hospital systems prioritize compliance assurance over unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, North Rhine-Westphalia, and Jiangsu province operate hub-and-spoke patterns for compressed aerosol and liquid bulk formats. Supply concentrates in China, Germany, and the United States, with Chinese producers feeding both domestic pharmaceutical manufacturers and export refrigerant intermediate markets. Feedstock economics draw from ethylene availability, hydrogen chloride supply contracts, and chlor-alkali integration depth. Single-source vulnerability runs through Chinese purification capacity for medical-grade export volumes. Distribution runs through specialized chemical distributors serving GPO-consolidated hospital networks alongside independent regional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethyl chloride market functions as a regulatory compounder where F-Gas Regulation phase-downs redirect industrial volumes toward medical and laboratory channels, amplifying demand for certified pharmaceutical-grade material.
For Market Incumbents: Deepen backward integration into captive ethylene oxide derivatives to defend margin position against feedstock volatility from naphtha cracking economics. Prioritize continuous hydrochlorination licensing to mid-scale batch producers seeking pharmaceutical-grade entry, converting technology advantage into royalty streams while limiting direct capacity competition. For New Entrants and Emerging Players: Enter via veterinary liquid charcoal formulations and regional distributor relationships serving independent surgical centers outside GPO dominance. The ambulatory surgery center channel in the United States offers lowest certification barriers for aerosol entrants, with just-in-time delivery flexibility valued over inventory management systems. For Investors and Strategic Acquirers: Valuations sit cheapest among European specialized refiners with EMA-certified purification capabilities and underutilized laboratory solvent distribution infrastructure. Long-term viability centers on refrigerant phase-down absorption capacity and research institution demand growth. Monitor F-Gas Regulation enforcement intensity as the signal indicating laboratory solvent volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Hydrochlorination Licensing | Technology transfer agreements enable mid-scale producers to enter pharmaceutical aerosol supply chains previously reserved for specialized refiners. |
| Pharmaceutical-Grade Purification Expansion | EMA and FDA certification investments capture rotating demand from refrigerant phase-downs into medical aerosol channels. |
| Regional Distribution Consolidation | Specialized intermediaries serving independent surgical centers gain procurement share outside GPO-dominated hospital networks. |
| Veterinary Formulation Development | Animal care liquid charcoal applications represent stable-volume niche demand with limited incumbent competition. |
| Research Institution Partnership Programs | University laboratory solvent agreements in Massachusetts and Baden-Württemberg absorb displaced industrial chloroethane capacity. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with plant managers at integrated chlor-alkali operators, procurement leads at downstream pharmaceutical manufacturers, distribution channel partners, and technical R&D directors informed supply-side and demand-side perspectives. Secondary sources included customs and trade data, Cefic and ACC industry reports, SEC 10-K filings, and EMA regulatory submission databases. Bottom-up volume modeling and top-down value triangulation cross-validated segmentation outputs.
Rate-of-change decomposition across product type, application, end user, and delivery mode dimensions structured the analytical framework. Grade tier, end-use industry, and regional production hub segmentation anchored volume projections. CAGRs were derived from regression analysis against ethylene feedstock pricing, regulatory phase-down schedules, and hospital procurement consolidation indices. Forecast inputs incorporated F-Gas Regulation enforcement trajectories, continuous hydrochlorination adoption curves, and group purchasing organization contract renewal patterns.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time Chinese domestic production capacity data introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented assumptions about refrigerant substitution velocity and pharmaceutical aerosol protocol expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Phenothiazine Market
Chemicals
China Inorganic Iodide Market
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
Ammonia Market
Chemicals
Benzhydrol Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Europe Biguanide Market
Chemicals
Piroctone Olamine Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Immunochemicals Market
Chemicals
Valeryl Chloride Market
Chemicals
Isopropanolamine Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Ferric Phosphate Market