
 Global Non-Halogenated Flame Retardants Market | 2026-2036
Global Non-Halogenated Flame Retardants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Halogenated Flame Retardants Market Foresight
Chinese phosphorus-based chemical producers is repositioning capacity toward intumescent and silicone-based grades to serve EV battery and charging infrastructure clients. Albemarle Corporation leverages its bromine-to-phosphorus technology pivot to sustain North American supply relationships with construction firms and appliance makers. Lanxess anchors European demand through tailored nitrogen-based solutions that comply with evolving EU fire safety codes for electrical housings.
Non-halogenated flame retardants are chemical additives formulated without chlorine, bromine, or fluorine, typically employing phosphorus, nitrogen, aluminum, or magnesium compounds to interrupt combustion through char formation, endothermic cooling, or radical scavenging at temperatures exceeding 300°C. Their primary purpose is to reduce flammability and smoke toxicity in polymers used across construction, transportation, and consumer electronics. Phosphorus-based formulations dominate current volume due to versatility across thermoset and thermoplastic matrices, while intumescent systems command premium positioning in architectural steel coatings where extended fire resistance ratings are mandatory. Inorganic grades, particularly aluminum and magnesium hydroxides, occupy cost-sensitive segments such as wire and cable jacketing where high loadings are technically feasible.
The EPA and OSHA in the United States enforce workplace exposure limits and product safety standards that restrict legacy halogenated additives in building materials and electrical components. REACH and the EU F-Gas Regulation in Europe impose substance restrictions and disclosure obligations that redirect formulation choices toward nitrogen-based and metal hydrate alternatives. Stakeholders must monitor pending amendments to fire safety standards in automotive and energy storage applications, as these will determine which chemistries qualify for next-generation material specifications.
Market Dynamics
REACH and RoHS frameworks in Europe are accelerating substitution away from brominated compounds, forcing reformulation across electrical housings and construction materials. This regulatory compression is reshaping supplier portfolios and procurement criteria simultaneously.
Growth Catalysts
- EV battery enclosure standards:China's tightening flammability requirements for electric vehicle battery housings are pulling phosphorus-based formulations into high-volume automotive supply chains. Domestic appliance production expansion in the same geography compounds this demand.
- REACH substance restrictions:The European Union's disclosure obligations and substance bans are redirecting formulation choices toward nitrogen-based and metal hydrate alternatives in building materials and electrical components.
- Intumescent coating specifications:Architectural steel applications are mandating extended fire resistance ratings that only advanced intumescent systems can satisfy, creating specification lock-in for premium grades.
Market Restraints
- Red phosphorus supply concentration:Critical raw material processing capacity clusters in China, exposing non-integrated formulators to export control volatility and freight cost spikes.
- High loadings requirement:Aluminum and magnesium hydroxide grades require 50-65% polymer loading to achieve equivalent performance, compressing mechanical properties and limiting application scope.
- Technical limitation in thermoplastics:Phosphorus-based additives face thermal stability ceilings below 320°C, excluding them from high-temperature engineering polymer matrices used in under-hood automotive applications.
Strategic Opportunities
- Charging infrastructure buildout:India's expanding EV charging station deployment under central government schemes is creating first-mover positioning for silicone-based grades in connector housings and cable management systems.
- EU F-Gas Regulation alignment:The European Union's fluorinated gas phase-down is opening specification windows for nitrogen-based alternatives in HVAC and refrigeration insulation foams previously served by halogenated chemistry.
- Silicone-phosphorus hybrid technology:Convergence of silicone backbone durability with phosphorus char-forming efficiency is enabling single-additive solutions for wire and cable jacketing in mass transit applications.
Industry Challenges
- Fire safety certification timelines:UL 94 and EN 13501-1 testing protocols require 12-18 month validation cycles, delaying product launches and freezing formulation decisions early in development pipelines.
- Polymer processing expertise gap:Compounders lack technical specialists capable of optimizing dispersion and thermal stability for high-loading metal hydrate systems, constraining regional manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Halogenated Flame Retardants Market |
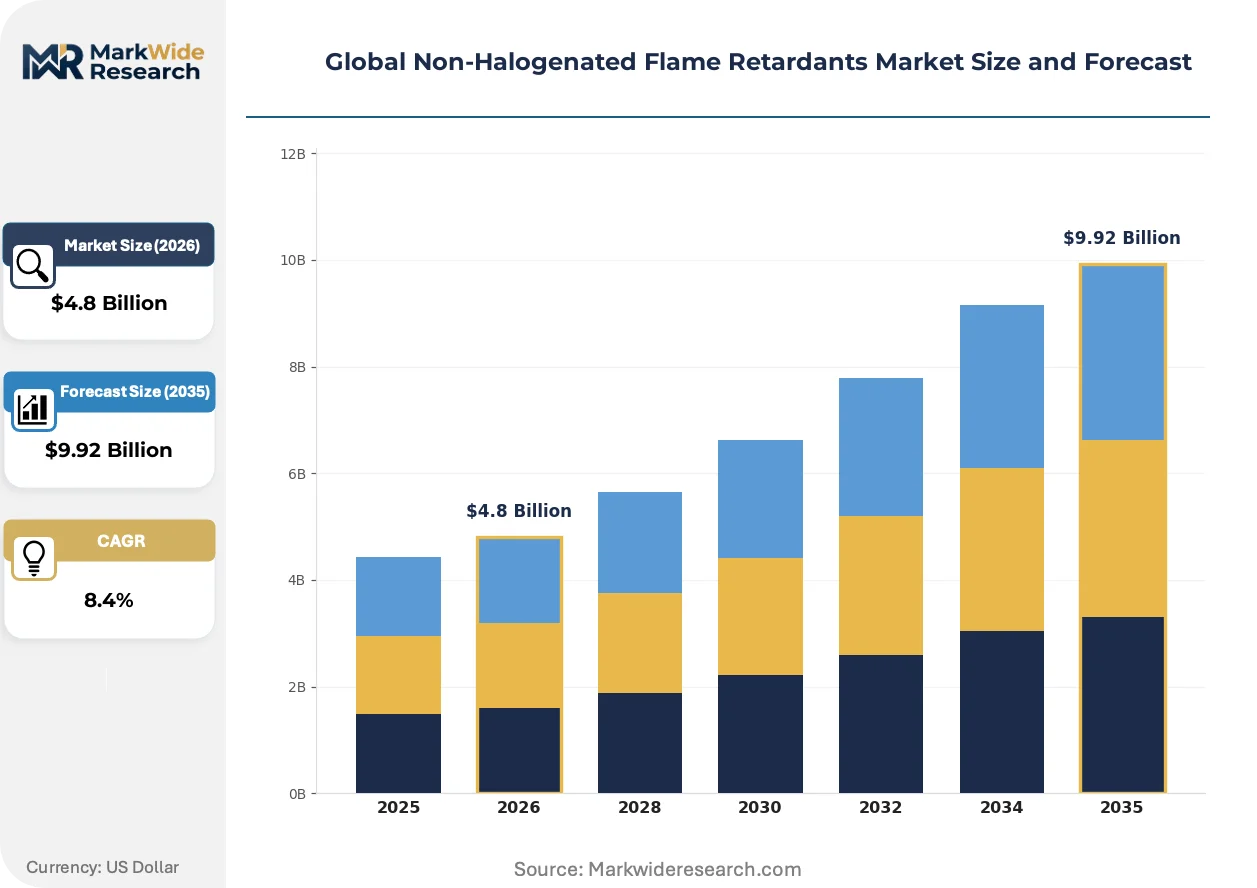
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphorus-Based, Nitrogen-Based, Inorganic, Intumescent, Silicone-Based Application: Building & Construction, Electrical & Electronics, Transportation Components, Textiles, Adhesives & Coatings End User Industry: Consumer Goods Manufacturers, Electronics OEMs, Aerospace Suppliers, Appliance Makers, Construction Firms Form: Powder, Granules, Pellets, Liquid, Resin |
| Companies Covered | Clariant, Lanxess, Albemarle Corporation, ICL, BASF SE, Nabaltec AG, Huber Engineered Materials, Italmatch Chemicals S.p.A, ADEKA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Halogenated Flame Retardants Market Shifts & Advancements
Formulation chemistry is pivoting toward reactive and polymeric flame retardant architectures that bond permanently into polymer matrices. This shift promises to resolve migration and leaching failures that have limited non-halogenated adoption in demanding applications.
Reactive phosphorus oligomers are converging with thermoplastic polyurethane and polyamide supply chains as Tier 1 automotive suppliers seek to eliminate additive bloom in interior components. BMW and Volkswagen procurement specifications now require covalently bound flame retardant chemistry for seat foam and dashboard substrates. The technology is compressing competitive differentiation around migration resistance rather than raw cost.
EPA enforcement of workplace exposure limits under TSCA Section 6 is restricting legacy halogenated additives in US building materials and electrical components. The industrial consequence is a forced reformulation timeline for construction firms and appliance makers serving federal procurement contracts. Wire and cable manufacturers in the Midwest and Southeast are responding fastest, driven by infrastructure stimulus project specifications.
Japanese electronics OEMs are consolidating supplier relationships around compounders capable of delivering pre-certified polymer grades rather than discrete additive packages. This procurement compression is displacing independent flame retardant distributors in favor of integrated polymer compounders with in-house regulatory affairs capabilities. The shift is most visible in consumer electronics supply chains serving Sony and Panasonic television and laptop programs.
Global Non-Halogenated Flame Retardants Market Segmentation
Non-halogenated flame retardant procurement varies sharply by certification burden. UL 94 V-0 ratings dominate electronics sourcing, while EN 13501-1 classifications govern European construction tenders. Formulators must map additive selection to the specific approval pathway each downstream application demands.
Product Type:
Phosphorus-based and intumescent grades carry the heaviest certification loads, requiring combined UL 94 and ASTM E84 clearance for North American construction and electronics applications. Nitrogen-based and silicone alternatives face lighter testing protocols in textiles and consumer goods, though automotive specifications under SAE J369 impose additional thermal cycling validation.
- Phosphorus-Based:These formulations employ organic and inorganic phosphorus compounds to catalyze char formation at combustion temperatures. Demand concentrates in China's EV battery enclosure supply chains, where GB/T 31485 flammability standards are tightening and domestic producers are expanding capacity for red phosphorus derivatives.
- Intumescent:Multicomponent systems that expand under heat to form insulating char layers, typically combining ammonium polyphosphate with carbon sources and blowing agents. Architectural steel coating specifications in Germany and France mandate extended fire resistance ratings that only these grades satisfy, creating specification lock-in for premium suppliers.
- Nitrogen-Based:Melamine derivatives and guanidine compounds that release inert gases during decomposition, interrupting combustion through dilution effects. Common in polyurethane foams for furniture and bedding applications.
- Inorganic:Aluminum and magnesium hydroxides that decompose endothermically, absorbing heat and releasing water vapor. Predominantly used in wire and cable jacketing where high loadings are technically feasible.
- Silicone-Based:Organosilicon compounds forming ceramic-like protective layers at elevated temperatures. Gaining traction in EV charging infrastructure connector housings under India's CEA technical standards.
Leading the category by volume: Phosphorus-Based. Growing fastest: Intumescent.
Application:
Cost tier differentiation separates specification-grade segments from commodity positioning. Building and construction commands premium pricing for certified intumescent systems, while textile treatments operate at thinner margins with less regulatory overhead.
- Building & Construction:Structural steel coatings, insulation boards, and interior finish materials requiring multi-hour fire resistance ratings. German construction firms under KBA-adjacent state building codes are specifying phosphorus-intumescent hybrids for high-rise projects.
- Electrical & Electronics:Circuit board laminates, connector housings, and cable assemblies demanding thin-wall flame retardancy without halogen content. Japanese electronics OEMs are consolidating procurement around pre-certified polymer compounds rather than discrete additives.
- Transportation Components:Aircraft interiors, rail seating, and automotive under-hood applications where smoke toxicity regulations apply. Phosphorus-based additives face thermal stability ceilings below 320°C that exclude them from certain engineering polymer matrices.
- Textiles:Upholstery, curtains, and protective clothing requiring durable flame retardant finishes. Nitrogen-based treatments dominate this cost-sensitive segment.
- Adhesives & Coatings:Bonding agents and surface treatments for composite materials in mass transit and industrial equipment.
Commanding premium pricing: Building & Construction. Expanding most quickly: Electrical & Electronics.
End User Industry:
Customer type determines formulation complexity and service intensity. Electronics OEMs demand technical partnership and regulatory documentation, while construction firms prioritize supply security and batch consistency.
- Electronics OEMs:Tier 1 suppliers to Sony, Panasonic, and similar programs require covalently bound flame retardant chemistry with migration resistance guarantees. These buyers are displacing independent additive distributors in favor of integrated compounders with in-house regulatory affairs capabilities.
- Construction Firms:Mid-Atlantic and Southeastern US contractors responding to EPA TSCA Section 6 enforcement are reformulating wire and cable specifications fastest, driven by federal infrastructure stimulus project requirements.
- Consumer Goods Manufacturers:Furniture and bedding producers sourcing nitrogen-based treatments for polyurethane foams under CPSC flammability standards.
- Aerospace Suppliers:Aircraft interior component manufacturers subject to FAA fire safety regulations and OEM-specific material qualifications.
- Appliance Makers:Domestic appliance producers in China and North America specifying phosphorus-based formulations for housings and internal components.
Generating highest service revenue: Electronics OEMs. Driving volume growth: Appliance Makers.
Form:
Supply concentration shapes regional availability and freight economics. Powder and granule production clusters near phosphorus processing facilities in China, while liquid and resin forms require compounding capabilities closer to end-use markets.
- Powder:Fine particulate grades requiring dust control and dispersion expertise during polymer processing. Aluminum hydroxide powders dominate cost-sensitive wire and cable applications.
- Granules:Agglomerated forms improving handling characteristics and reducing dust exposure. Preferred by mid-sized compounders lacking advanced powder handling systems.
- Pellets:Pre-compounded masterbatch formats enabling direct feeding into extrusion and molding equipment. BMW and Volkswagen specifications for automotive interior components favor pelletized reactive phosphorus oligomers.
- Liquid:Dispersions and solutions for coating, adhesive, and textile finishing applications where uniform surface treatment is critical.
- Resin:Reactive flame retardants permanently incorporated into polymer backbones during synthesis, eliminating migration and leaching failures.
Highest volume format: Powder. Steepest expansion trajectory: Resin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Red phosphorus processing capacity clusters in Yunnan and Guizhou provinces, anchoring raw-material supply for phosphorus-based formulations serving EV battery and electronics supply chains across Asia.
China
GB/T 31485 flammability standards for EV battery enclosures are tightening procurement specifications for domestic automakers and tier suppliers. MIIT enforcement of new energy vehicle safety codes is accelerating reformulation away from legacy additives. Appliance production expansion in Guangdong and Jiangsu provinces compounds demand for phosphorus-based grades in housing and internal components.
Germany
KBA-adjacent state building codes mandate extended fire resistance ratings for high-rise structural steel, locking in demand for intumescent coating systems. REACH substance restrictions and disclosure obligations redirect formulation choices toward nitrogen-based alternatives in electrical housings. Chemical production clusters in North Rhine-Westphalia and Bavaria are reconfiguring compounding lines to serve construction and automotive export markets.
United States
EPA TSCA Section 6 enforcement restricts legacy halogenated additives in building materials and electrical components serving federal procurement contracts. OSHA workplace exposure limits compress allowable thresholds for brominated compounds in manufacturing environments. Wire and cable manufacturers in the Midwest and Southeast are responding fastest, driven by infrastructure stimulus project specifications requiring halogen-free jacketing.
India
CEA technical standards for EV charging infrastructure are creating specification windows for silicone-based grades in connector housings and cable management systems. Central government schemes under the Faster Adoption and Manufacturing of Electric Vehicles program are expanding charging station deployment. Manufacturing investment is concentrating in Gujarat and Tamil Nadu, where compounders are building technical capability to serve domestic automotive programs.
Japan
METI guidance on sustainable materials procurement is pressuring electronics OEMs to consolidate supplier relationships around pre-certified polymer compounds. JIS standards for consumer electronics flammability are migrating toward covalently bound flame retardant chemistry to eliminate additive bloom. Industrial concentration in the Kanto and Kansai regions supports integrated compounders with in-house regulatory affairs capabilities serving Sony and Panasonic supply chains.
Global Non-Halogenated Flame Retardants Market Competitive Landscape
Global majors compete with regional champions across certification depth and regulatory affairs bandwidth. The vendor base separates into three tiers: integrated chemical conglomerates with captive phosphorus supply, specialized flame retardant formulators with polymer processing expertise, and regional compounders serving cost-sensitive wire and cable segments. Strategic moves center on technology licensing partnerships for reactive phosphorus oligomers and backward integration into red phosphorus processing to secure feedstock positions.
Among Swiss and German chemical specialists, Clariant and Lanxess exemplify the integrated formulator archetype with deep regulatory documentation capabilities. Albemarle Corporation occupies a position bridging bromine heritage and phosphorus pivot strategies. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning in a market where certification timelines and polymer processing expertise determine customer access.
| Leading Market Players |
|---|
| Clariant |
| Lanxess |
| Albemarle Corporation |
| ICL |
| BASF SE |
| Nabaltec AG |
| Huber Engineered Materials |
| Italmatch Chemicals S.p.A |
| ADEKA Corporation |
| Others |
Supply & Pricing Matrix
Polymer processing specialists concentrated in Germany's North Rhine-Westphalia chemical belt command wage premiums that widen spreads between certified premium grades and commodity metal hydrate alternatives. Labor-cost differentials between European compounding facilities and Chinese powder processing plants feed directly into three-tier pricing stratification across phosphorus-based formulations.
Pricing Analysis
Warranty-backed regulatory documentation bundles separate premium phosphorus-based grades from unbundled commodity metal hydrates. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and polymer processing complexity. Price differentiation hinges on UL 94 V-0 pre-certification status and reactive oligomer thermal stability guarantees. Cost compression in economy-grade aluminum hydroxide wire and cable segments is intensifying because Chinese export capacity expansions outpace formulation expertise growth. Electronics OEMs exhibit lowest price sensitivity due to specification lock-in, while mid-sized construction distributors face acute margin pressure from freight cost volatility.
Supply Chain Analysis
Ocean freight rate spikes between Yunnan province and European compounding hubs compress margins on red phosphorus derivatives. Raw material supply draws from China's Guizhou processing clusters, German nitrogen-based chemical production, and US Gulf Coast magnesium hydroxide extraction. Critical dependencies include red phosphorus metallurgical-grade feedstock, ammonium polyphosphate technical-grade supply, and organosilicon precursor chemicals. Single-source vulnerability concentrates in Chinese red phosphorus export licensing. Distribution runs through integrated compounders with captive regulatory affairs capabilities serving Japanese electronics OEMs and German automotive Tier 1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Red phosphorus processing capacity bottlenecks in Yunnan and Guizhou provinces prop pricing power for integrated producers, constraining supply elasticity across phosphorus-based formulation tiers.
For Market Incumbents: Extend backward integration into red phosphorus metallurgical processing to secure captive feedstock positions against Chinese export control volatility. Expand compounding capacity in India's Gujarat and Tamil Nadu industrial corridors to capture EV charging infrastructure demand under CEA technical standards. Certification investment in pre-validated UL 94 V-0 polymer masterbatches defends margin position against Japanese electronics OEM procurement consolidation toward integrated compounders. For New Entrants and Emerging Players: Silicone-phosphorus hybrid reactive oligomer technology offers entry positioning into wire and cable jacketing specifications for mass transit applications. India's EV charging connector housing segment under central government Faster Adoption schemes presents the most penetrable white-space target. Go-to-market execution should anchor on CEA pre-certification partnerships with Gujarat-based compounders lacking advanced thermal stability formulation expertise. For Investors and Strategic Acquirers: The window for entry favors German and Swiss specialty chemical formulators with established REACH documentation bandwidth and automotive OEM qualification relationships. Long-term viability over the next decade rests on regulatory affairs depth rather than raw production scale. Acquisition screening should prioritize targets with reactive phosphorus oligomer patent estates and existing BMW or Volkswagen program approvals. The signal to watch is MIIT enforcement acceleration of GB/T 31485 battery enclosure standards, which would trigger step-change demand pull for qualified phosphorus-based suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Red Phosphorus Processing | Captive Yunnan feedstock supply insulates formulators from Chinese export licensing volatility. |
| Reactive Oligomer Patent Estate Acquisition | BMW and Volkswagen covalent chemistry specifications lock in premium tier positioning. |
| CEA Pre-Certification Partnership | India's EV charging infrastructure buildout creates first-mover specification windows. |
| UL 94 V-0 Masterbatch Validation Investment | Sony and Panasonic procurement consolidation favors pre-certified polymer compounds. |
| Gujarat Compounding Facility Joint Venture | Regional technical capability gaps constrain domestic supply response to automotive demand. |
Research Methodology
Multi-period observation of GB/T 31485 enforcement patterns, REACH substance restriction amendments, and UL 94 certification timeline compression anchored the trend analysis, supplemented by interviews with polymer compounding plant managers, flame retardant procurement leads at electronics OEMs, distribution channel partners in wire and cable segments, and technical R&D directors at specialty chemical formulators. Secondary validation drew from ECHA restriction proposal databases, USITC trade flow records, MIIT new energy vehicle safety code filings, and SEC 10-K disclosures from listed chemical producers. Bottom-up demand modeling across end-use applications triangulated against top-down supply capacity assessments.
Input-output matrices mapped phosphorus derivative production volumes through formulation tiers to end-use consumption across the analysis window. Segmentation dimensions modeled include chemistry family, certification grade, polymer matrix compatibility, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating EV battery enclosure content-per-vehicle trajectories and construction fire code amendment schedules. Forecast inputs incorporated red phosphorus export license issuance patterns and intumescent coating specification adoption curves in German high-rise construction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH substance ban acceleration or Chinese environmental enforcement shutdowns of Guizhou processing facilities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Polyimide Varnish Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Europe Sugarcane Wax Market