
 Calcium Methoxide Market | 2026-2036
Calcium Methoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Methoxide Market Insights
Specialty chemical distribution channels is reconfiguring as regional buyers consolidate procurement around certified suppliers with backward integration into lime feedstock. BASF leverages its integrated methanol-calcium chemistry network to secure cost positions across European pharma accounts. Evonik Industries sustains technical service density in North American catalyst applications. Solvay SA anchors volume contracts with multinational pharmaceutical manufacturers seeking pharmaceutical grade consistency.
Calcium methoxide functions as a calcium alkoxide salt produced through controlled reaction of calcium metal or calcium hydroxide with methanol, yielding a white crystalline powder with strong basicity and hygroscopic properties valued in transesterification and condensation reactions. Industrial grade material dominates current shipment volumes tied to biodiesel catalyst demand, while pharmaceutical grade commands premium positioning due to stringent impurity thresholds enforced by FDA and EMA filings. Research grade volume remains comparatively thin but exhibits the fastest trajectory as academic labs expand mechanistic studies in green synthesis pathways.
REACH registration requirements in Europe, FDA pharmaceutical excipient standards in the United States, and China's GB chemical purity specifications collectively elevate compliance costs for non-specialist producers. EMA guidelines on residual solvent limits directly shape pharmaceutical grade manufacturing protocols and testing expenditure. Stakeholders must monitor evolving green chemistry procurement mandates from multinational chemical manufacturers and assess feedstock lime sourcing security before committing capacity expansion decisions.
Market Dynamics
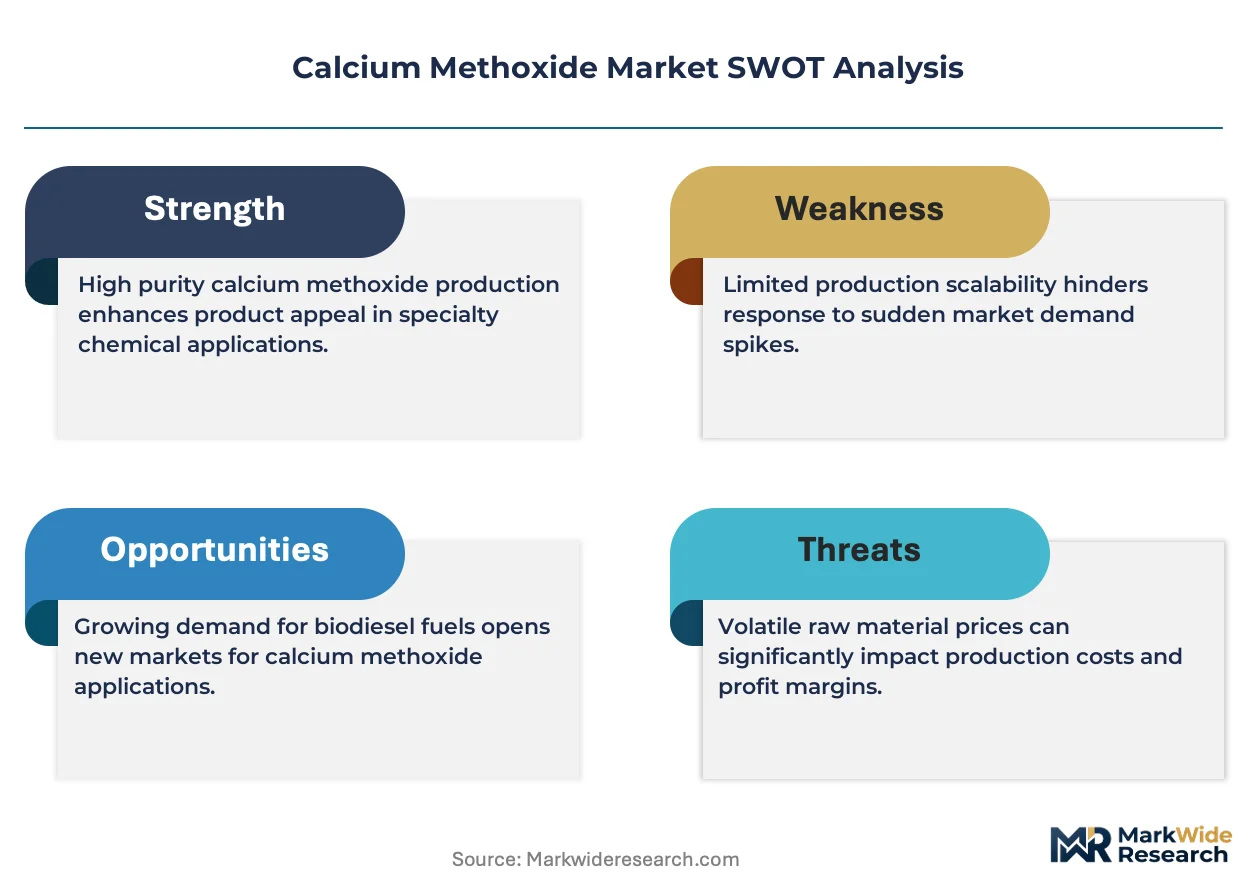
Pharmaceutical grade certification requirements under FDA and EMA guidelines are compressing supplier margins while concentrating procurement around backward-integrated lime producers with captive methanol supply. This regulatory tightening is forcing specialty chemical distributors to consolidate sourcing relationships.
Growth Catalysts
- REACH registration mandates:EU Green Deal procurement rules are compelling multinational pharmaceutical manufacturers to source calcium methoxide from certified suppliers with verified carbon footprints.
- Biodiesel catalyst demand:Transesterification applications in renewable diesel production are pulling industrial grade volumes as refineries seek strong basicity catalysts.
- Academic mechanistic research:Green synthesis pathway studies at research institutions are expanding consumption of high-purity research grade material.
Market Restraints
- Feedstock lime volatility:Calcium hydroxide and calcium metal prices fluctuate with construction sector demand cycles and energy-intensive kiln operations.
- Chinese GB standard compliance costs:Non-specialist producers face elevated testing expenditure to meet China's chemical purity specifications for export qualification.
- Sodium methoxide substitution:Lower-cost alkoxide alternatives threaten calcium methoxide in price-sensitive biodiesel catalyst applications where calcium specificity is not required.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO filing requirements are creating demand for pharmaceutical grade material as domestic API production expands under PLI scheme incentives.
- Continuous flow reactor integration:Convergence of process intensification technology with solid catalyst handling systems is opening new equipment specification channels.
- Direct procurement platforms:Specialty chemical marketplaces are disintermediating traditional distributors for standardized industrial grade shipments.
Industry Challenges
- Residual solvent testing capacity:EMA guidelines on methanol limits require investment in gas chromatography infrastructure that smaller producers lack.
- Hygroscopic material handling:Moisture-sensitive powder logistics demand climate-controlled storage and specialized packaging that complicates distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Methoxide Market |
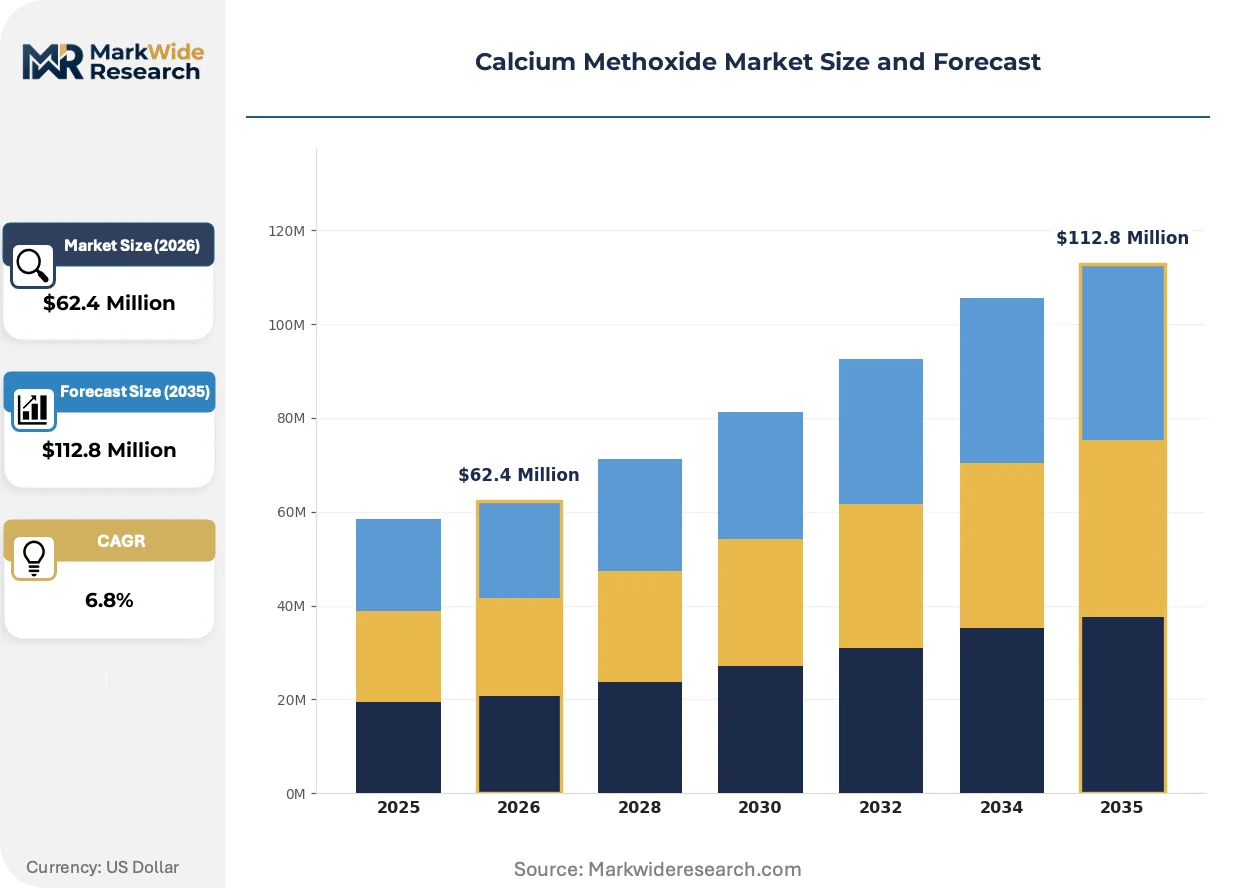
| Market Size in 2026 | $62.4 Million |
| Market Size in 2035 | $112.8 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Reagent Grade, Research Grade Application: Organic Synthesis, Pharmaceutical Intermediates, Catalysts, Biochemistry End User: Chemical Manufacturers, Pharmaceutical Companies, Research Institutions, Academic Labs Packaging Type: Drum, Bag, Bottle, Bulk |
| Companies Covered | BASF, Evonik Industries, Solvay SA, Carmeuse, Lhoist Group, Omya AG, American Elements, AkzoNobel N.V., Sigma-Aldrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Methoxide Market Trends and Innovations
Digital process control systems are compressing batch-to-batch variability in alkoxide production. This precision shift is enabling tighter impurity profiles that pharmaceutical formulators demand for regulatory filings.
Computational modeling of calcium alkoxide reaction kinetics is virtualizing traditional empirical scale-up protocols. Catalyst manufacturers in Germany and the United States are deploying these simulation tools to reduce pilot plant iterations. The technology is compressing development timelines for custom grade specifications.
EMA residual solvent guideline revisions are tightening methanol detection thresholds in pharmaceutical excipients. Manufacturers must retest legacy inventory and revalidate analytical methods. European contract manufacturers are responding by qualifying secondary suppliers with redundant testing capabilities.
Consolidated procurement desks at multinational chemical buyers are unbundling technical service from material supply. North American pharmaceutical accounts now source calcium methoxide through centralized contracts while purchasing application support separately. This bifurcation is visible most acutely in catalyst selection for condensation reactions.
Calcium Methoxide Market Segmentation
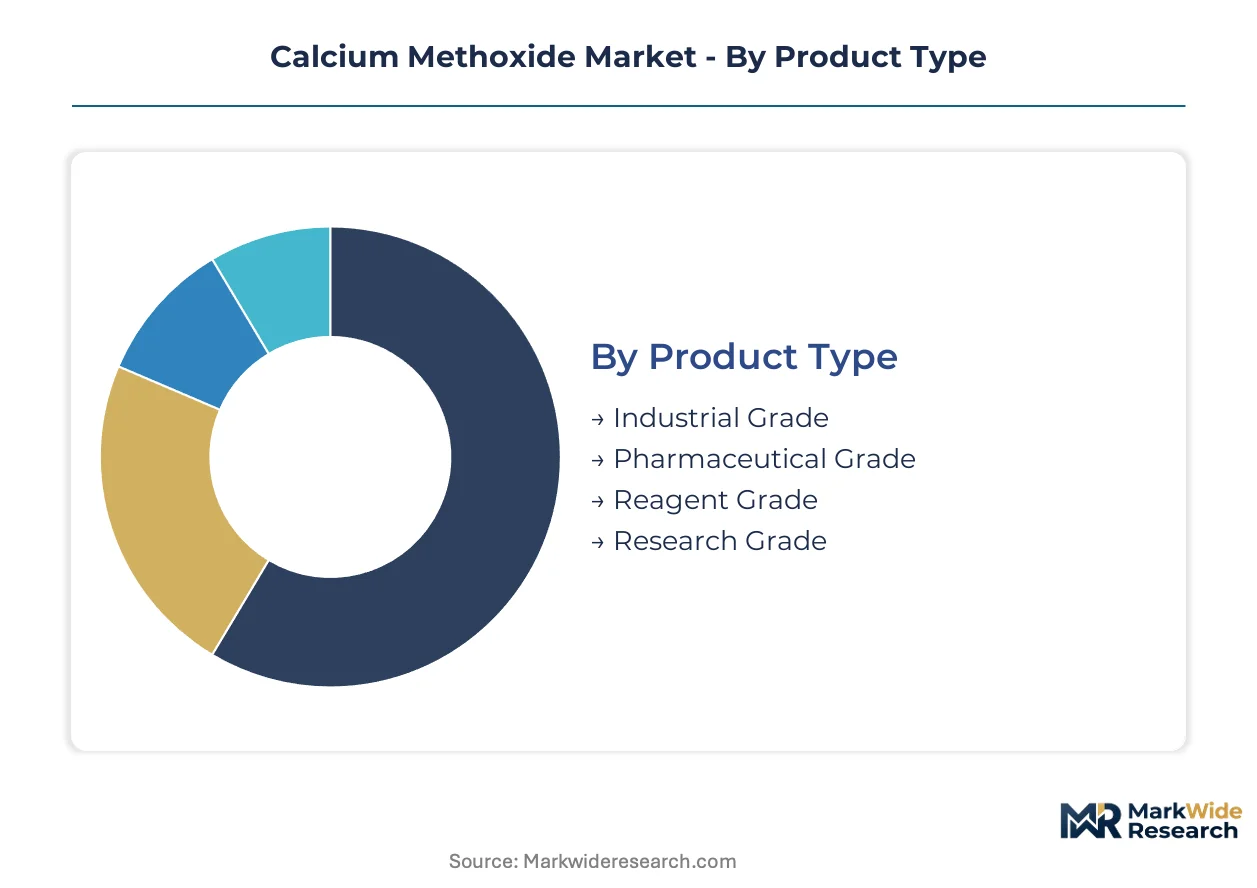
Segmentation in calcium methoxide markets separates volume-driven commodity flows from premium-certified pharmaceutical supply chains. Grade purity thresholds and end-user regulatory exposure create distinct pricing corridors that suppliers must navigate simultaneously.
Product Type:
Cost tier determines procurement behavior across buyer categories, with certification requirements widening spreads between commodity and specialty grades.
- Industrial Grade:Material with moderate purity specifications serves transesterification catalyst demand from renewable diesel refineries. BASF and Solvay SA anchor European supply contracts for biodiesel producers seeking strong basicity at scale.
- Pharmaceutical Grade:Stringent impurity thresholds enforced by FDA and EMA filings command premium positioning. German and United States manufacturers dominate procurement desks at multinational pharmaceutical companies requiring excipient consistency for regulatory submissions.
- Reagent Grade:Standardized purity for analytical applications supports quality control laboratories across chemical manufacturing facilities.
- Research Grade:High-purity material for mechanistic studies in green synthesis pathways. Academic institutions in Germany and China are expanding consumption for alkoxide reaction kinetics research.
Industrial Grade holds installed capacity. Research Grade is rotating up the share rankings.
Application:
End-use function separates process chemistry volume from high-value pharmaceutical synthesis where regulatory filing costs dominate material economics.
- Organic Synthesis:Condensation and alkylation reactions in fine chemical production consume drum-quantities from contract manufacturers. Evonik Industries sustains technical service density for North American catalyst selection in these applications.
- Pharmaceutical Intermediates:Calcium methoxide serves as a base in API synthesis where residual solvent limits under EMA guidelines shape manufacturing protocols. CDSCO filing requirements in India are expanding demand as domestic production scales under PLI scheme incentives.
- Catalysts:Transesterification applications in biodiesel production pull industrial grade volumes from refineries seeking renewable diesel compliance with EU Green Deal mandates.
- Biochemistry:Enzymatic reaction support and protein modification applications require specialized handling protocols for hygroscopic material logistics.
Organic Synthesis maintains volume leadership. Pharmaceutical Intermediates is gaining share fastest.
End User:
Customer type segmentation captures procurement sophistication divergence between centralized chemical buyers and distributed research purchasers.
- Chemical Manufacturers:Integrated producers with backward integration into lime feedstock secure cost positions across European and Chinese supply bases. REACH registration requirements favor certified suppliers with verified carbon footprints.
- Pharmaceutical Companies:Multinational manufacturers source through consolidated procurement desks that unbundle technical service from material supply. EMA residual solvent guidelines directly shape supplier qualification protocols.
- Research Institutions:Mechanistic studies in green chemistry pathways drive high-purity research grade demand from German and United States academic centers.
- Academic Labs:Small-volume purchasers rely on specialty chemical distributors with climate-controlled storage capabilities for moisture-sensitive powder handling.
Chemical Manufacturers hold installed capacity. Pharmaceutical Companies is rotating up the share rankings.
Packaging Type:
Logistics configuration separates bulk commodity flows from precision-dispensed laboratory quantities with divergent handling cost structures.
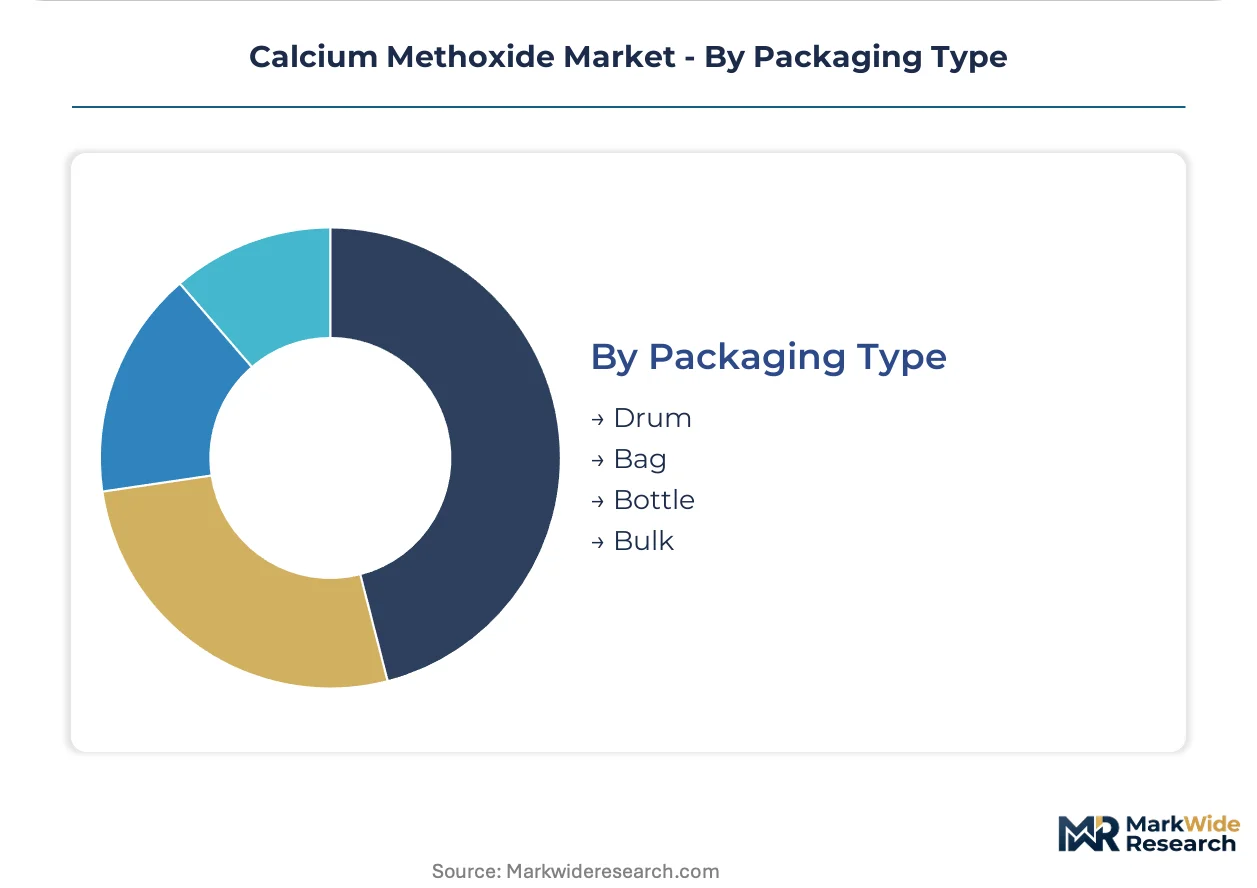
- Drum:Standard 200-liter steel containers serve chemical manufacturers with moderate volume requirements and established material handling infrastructure.
- Bag:Multi-layer moisture-barrier packaging addresses hygroscopicity concerns for industrial grade shipments to biodiesel catalyst users.
- Bottle:Amber glass with desiccant seals protects research grade material for pharmaceutical intermediate synthesis in quality-controlled environments.
- Bulk:Tanker and silo delivery supports highest-volume transesterification catalyst consumers with dedicated storage and nitrogen-blanketing systems.
Bulk holds installed capacity. Bottle is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German pharmaceutical-grade supply chains while Chinese industrial-grade producers compete on volume metrics. This asymmetry shapes procurement desk behavior across multinational chemical buyers.
United States
FDA pharmaceutical excipient standards and renewable diesel tax credits drive divergent demand streams. The EPA's renewable fuel standard compliance deadlines accelerate biodiesel catalyst procurement from Gulf Coast refineries. Houston-area chemical manufacturers anchor industrial-grade volume contracts with integrated lime-methanol supply chains.
Germany
REACH registration mandates and EU Green Deal procurement rules tighten supplier qualification protocols. EMA residual solvent guidelines directly shape pharmaceutical-grade manufacturing investment in the Rhine-Ruhr chemical corridor. Ludwigshafen and Leverkusen clusters host backward-integrated producers with captive methanol infrastructure.
China
Dual carbon goals and GB chemical purity specifications elevate compliance costs for export-oriented producers. NMPA alignment efforts with ICH standards reshape pharmaceutical-grade capacity planning. Yangtze River Delta chemical parks concentrate industrial-grade output serving domestic biodiesel expansion.
India
CDSCO filing requirements and PLI scheme incentives expand domestic API production capacity. BIS certification protocols for chemical imports create entry barriers for non-specialist exporters. Maharashtra and Gujarat pharmaceutical clusters drive pharmaceutical-grade procurement consolidation.
Japan
METI green chemistry procurement guidelines and PMDA pharmaceutical standards enforce stringent impurity thresholds. JIS industrial standards shape catalyst specification channels for domestic refineries. Osaka-Kobe chemical manufacturing belt maintains specialized handling infrastructure for hygroscopic alkoxide logistics.
Calcium Methoxide Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with feedstock leverage. Market structure tilts toward consolidated procurement relationships around certified suppliers with lime-methanol integration. Three archetypes dominate: backward-integrated chemical conglomerates, specialty alkoxide producers with pharmaceutical-grade certification, and regional lime processors diversifying into derivative chemistry. Competitive moves concentrate on capacity expansion in high-purity grades and strategic partnerships with biodiesel catalyst distributors.
Among European chemical conglomerates, BASF and Evonik Industries occupy positions reflecting integrated methanol-calcium chemistry networks. Solvay SA exemplifies the pharmaceutical-grade certification tier with volume contract anchoring. These three names represent distinct strategic postures: feedstock control, technical service density, and regulatory filing support respectively.
| Leading Market Players |
|---|
| BASF |
| Evonik Industries |
| Solvay SA |
| Carmeuse |
| Lhoist Group |
| Omya AG |
| American Elements |
| AkzoNobel N.V. |
| Sigma-Aldrich |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp chemical corridor freight costs compress margins for non-integrated calcium methoxide suppliers while amplifying price differentiation between pharmaceutical-grade certified producers and commodity biodiesel catalyst shippers. This logistics chokepoint concentrates procurement power among Rhine-Ruhr producers with captive methanol infrastructure and direct barge access to European pharmaceutical accounts.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade material commanding certification-linked pricing from standardized industrial-grade contracts indexed to methanol commodity benchmarks. Price differentiation hinges on EMA residual solvent compliance thresholds and backward integration into lime feedstock. Cost compression in industrial-grade biodiesel catalyst tiers intensifies as sodium methoxide substitution accelerates in price-sensitive renewable diesel applications. Research institutions exhibit lowest price sensitivity due to grant-funded procurement and small-volume precision requirements.
Supply Chain Analysis
Upstream lime calcination and methanol synthesis capacity concentrates supply concentration in Germany, China, and the United States. Calcium methoxide production draws from calcium hydroxide or calcium metal feedstock, methanol reagent, and specialized gas chromatography testing infrastructure for residual solvent validation. Single-source vulnerability runs through Yangtze River Delta industrial-grade clusters exposed to dual carbon policy enforcement and export qualification delays. Distribution runs through specialty chemical distributors with climate-controlled warehousing for hygroscopic material handling, supplemented by direct procurement platforms disintermediating standardized industrial shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium methoxide procurement is restructuring around technical service bundling, with EMA-compliant testing and regulatory filing support expanding faster than commodity chemical supply. This service-attach dynamic favors suppliers with analytical method validation capabilities and pharmaceutical-grade certification infrastructure.
For Market Incumbents: Harden backward integration into lime feedstock and captive methanol supply to defend margin position against sodium methoxide substitution in biodiesel catalyst tiers. Consolidate procurement relationships with multinational pharmaceutical manufacturers by qualifying redundant EMA residual solvent testing capabilities. Capacity expansion in pharmaceutical-grade production at Rhine-Ruhr sites anchors volume contracts requiring regulatory filing consistency. For New Entrants and Emerging Players: Build out CDSCO-compliant pharmaceutical-grade capacity serving Maharashtra and Gujarat API clusters under India's PLI scheme incentives. Target research-grade white space in German and United States academic mechanistic studies where green synthesis pathway funding accelerates alkoxide consumption. Qualify through specialty chemical marketplaces with climate-controlled logistics partnerships to bypass traditional distributor margin capture. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-grade certification specialists with EMA/FDA dual filing capabilities over commodity industrial-grade volume players. Long-term viability rests on regulatory compliance infrastructure rather than scale economics in biodiesel catalyst substitution scenarios. The signal to watch is CDSCO alignment with ICH standards accelerating domestic Indian pharmaceutical-grade capacity buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lime Feedstock | Captive calcium hydroxide supply secures cost position against construction sector demand cycles. |
| Pharmaceutical-Grade Certification Investment | EMA residual solvent compliance opens multinational API manufacturer procurement desks. |
| Continuous Flow Reactor Partnership | Process intensification integration creates equipment specification channels with catalyst manufacturers. |
| Direct Procurement Platform Qualification | Specialty chemical marketplace presence disintermediates distributor margin capture in industrial-grade tiers. |
| Indian CDSCO Filing Support Infrastructure | Regulatory affairs capability captures PLI scheme-driven API production expansion in domestic market. |
Research Methodology
Desk research of customs/trade databases, SEC 10-K filings, and ECHA REACH registration records preceded structured interviews with plant managers at calcium alkoxide producers, procurement leads at multinational pharmaceutical manufacturers, distribution channel partners, and technical R&D directors. Bottom-up volume estimates triangulated against top-down market sizing derived from lime feedstock consumption patterns and methanol derivative demand analysis.
Assumptions held regulatory filing timelines and EMA residual solvent guideline enforcement within observed patterns while varying biodiesel catalyst substitution rates and Indian PLI scheme capacity expansion scenarios across the analysis window. Segmentation modeling incorporated grade tier, end-use application, packaging format, and regional production hub dimensions. CAGRs derived from regression analysis of historical shipment volumes against pharmaceutical intermediate and renewable diesel catalyst demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese industrial-grade specialists or accelerated sodium methoxide substitution would shift outcomes. Cross-checking against ECHA registration database updates and CDSCO filing publication rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Methanol Market
Chemicals
Chromium Trioxide Market
Chemicals
Potassium Alum Market
Chemicals
Caustic Soda Market
Chemicals
Deicing Fluid Market
Chemicals
Chemical As a Service Market
Chemicals
Hexachloroethane Market
Chemicals
Morpholine Market
Chemicals
Spirodiclofen Market
Chemicals
Coal Tar Market
Chemicals
Japan Methanol Market
Chemicals
Potassium Zirconium Fluoride Market
Chemicals
Fireworks Market
Chemicals
Zinc Chemicals Market
Chemicals
Heptaldehyde Market
Chemicals
Detergent Alcohols Market