

Industrial Odor Management Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Odor Management Market Insights
The EU Green Deal's industrial emissions targets is restructuring procurement priorities across European odor control infrastructure. Ecolab leverages its integrated water and air treatment portfolio to capture bundled facility contracts. Veolia sustains dominant positions in municipal waste treatment through long-term service agreements. Dürr Group anchors its competitive stance with specialized oxidation systems for automotive coating applications.
Industrial odor management encompasses engineered systems that capture, neutralize, or destroy malodorous compounds—primarily hydrogen sulfide, ammonia, and volatile organic compounds—through physical, chemical, or biological processes, typically achieving removal efficiencies above 90% depending on contaminant load and residence time. These systems serve the essential commercial purpose of enabling industrial facilities to maintain operational permits, protect worker health, and sustain community relations in densely populated manufacturing zones. Activated carbon systems occupy mature, high-margin positions in intermittent-load chemical processing environments where predictable replacement cycles generate recurring revenue. Biofilters represent the fastest-expanding technology segment as food manufacturers and municipal composting operators seek lower-energy alternatives to thermal oxidation. Chemical scrubbers retain structural importance in pulp and paper applications where high sulfur compound concentrations demand reliable continuous treatment.
The EPA enforces Maximum Achievable Control Technology standards that compel US facilities to upgrade legacy odor control infrastructure, while REACH and the EU F-Gas Regulation restrict certain chemical neutralizing agents and fluorinated compounds used in advanced oxidation equipment. China's MEE implements increasingly stringent odor emission limits for petrochemical and pharmaceutical manufacturing clusters, directly shaping product certification requirements for equipment suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substances restrictions across multiple jurisdictions, as these compound classes appear in proprietary scrubber formulations and membrane materials that suppliers will need to reformulate or replace.
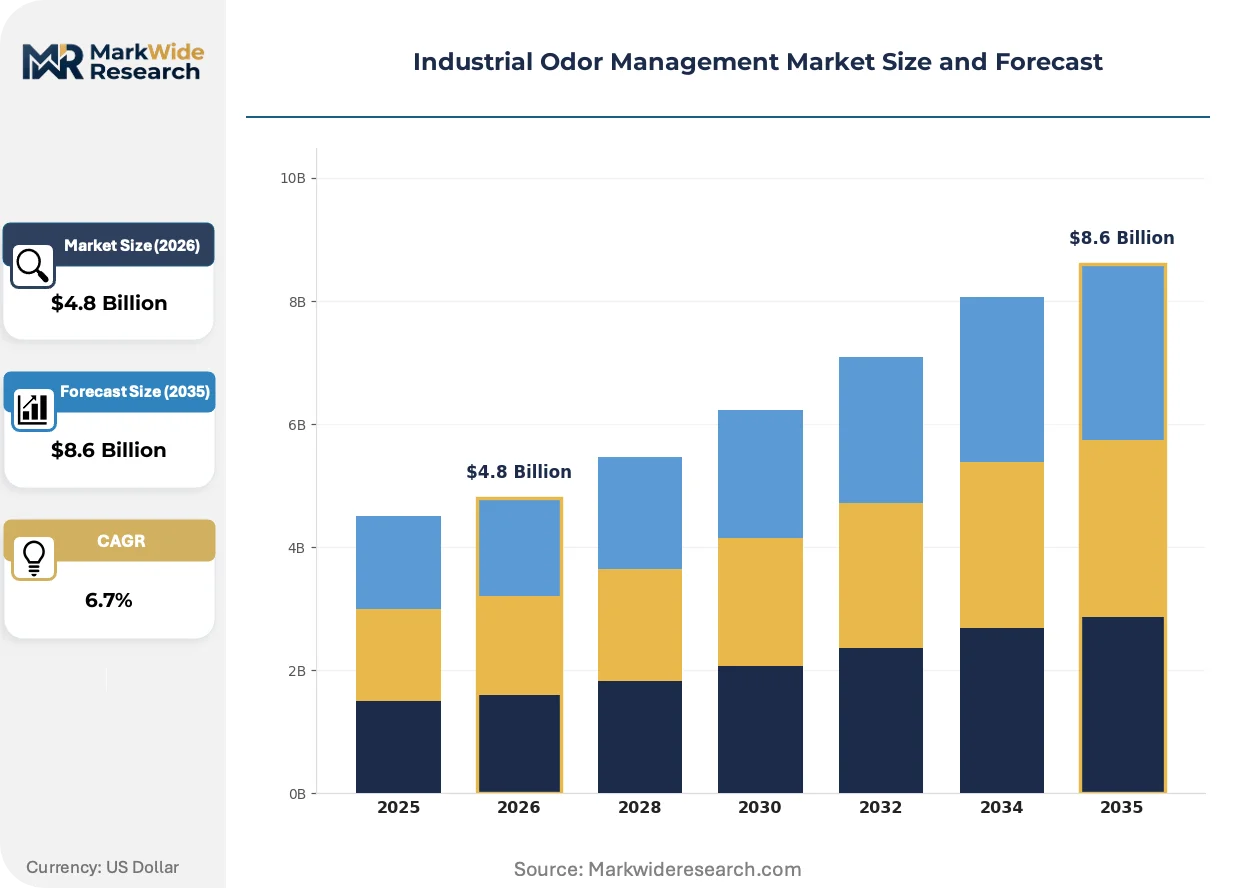
Market Dynamics
The EU Green Deal's tightening industrial emissions framework is forcing accelerated replacement cycles across European odor control infrastructure, while China's MEE odor limits for Yangtze River Delta chemical clusters are compressing supplier certification timelines.
Growth Catalysts
- REACH and F-Gas Regulation:The EU's restrictions on fluorinated compounds in oxidation equipment are compelling facilities to upgrade to compliant biofilter and scrubber systems.
- Municipal wastewater expansion:Germany, the United States, and India are expanding biofilter installations to meet stricter ambient air quality directives.
- Lower-energy biological processes:Food manufacturers and composting operators are migrating from thermal oxidation to biofilters to reduce operational expenditure.
Market Restraints
- Activated carbon supply concentration:Coconut shell and coal-based carbon sourcing clusters in Southeast Asia and South Asia create input cost volatility and delivery risk.
- Per- and polyfluoroalkyl substances restrictions:Multiple jurisdictions are banning PFAS compounds found in proprietary scrubber formulations and membrane materials, forcing urgent reformulation.
- High sulfur compound technical limitations:Biofilters struggle with consistent performance above threshold hydrogen sulfide concentrations, preserving chemical scrubber lock-in for pulp and paper applications.
Strategic Opportunities
- China's pharmaceutical manufacturing corridor:MEE odor emission limits for petrochemical and pharmaceutical clusters are creating certified equipment demand that domestic suppliers currently underserve.
- EPA MACT standards:Maximum Achievable Control Technology enforcement compels US facilities to replace legacy infrastructure, opening upgrade contracts for integrated water-air treatment providers.
- Biofilter-UV hybrid convergence:Combining biological degradation with photocatalytic oxidation addresses variable contaminant loads in food processing environments.
Industry Challenges
- Cross-functional engineering scarcity:Facilities require personnel fluent in both air quality engineering and biological process optimization, a combination rarely found in single candidates.
- Legacy system integration friction:Retrofitting biofilters into existing chemical scrubber infrastructure demands custom ductwork and control system reconciliation.
- PFAS reformulation timeline compression:Suppliers must replace membrane materials and scrubber chemistries before phased bans take effect, straining R&D bandwidth.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Odor Management Market Trends and Innovations
Biofiltration is displacing incumbent thermal oxidation across energy-sensitive applications, while regulatory chemical bans are rewriting material specifications for scrubber and membrane suppliers.
Biological odor control is overtaking thermal oxidation in food manufacturing and municipal composting operations. These facilities prioritize energy reduction over absolute destruction efficiency. The shift is compressing demand for natural gas-fired oxidizers and expanding biofilter vessel fabrication capacity.
REACH and the EU F-Gas Regulation are restricting fluorinated compounds used in advanced oxidation equipment and scrubber formulations. Equipment suppliers must reformulate proprietary chemistries and source alternative membrane materials. Automotive coating applications in Germany face compressed compliance timelines for replacing oxidation systems.
Long-term service agreements are displacing equipment-only transactions in municipal waste treatment. Veolia and Ecolab structure bundled water-air contracts spanning 10-15 years. Germany's municipal sector shows the most pronounced shift toward operational expenditure models.
Industrial Odor Management Market Segmentation
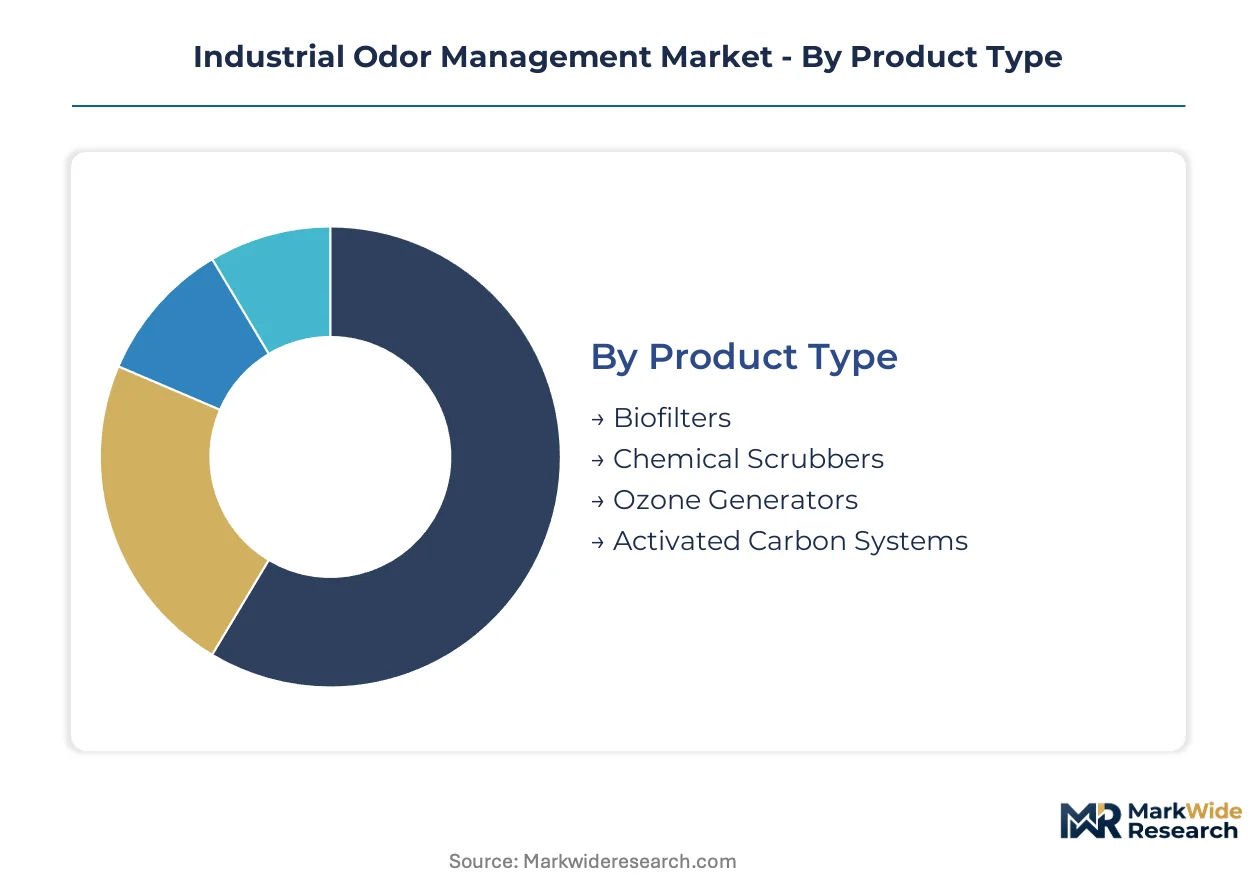
Technology selection in odor management follows facility-specific contaminant profiles and energy constraints. Procurement decisions increasingly bundle air and water treatment under unified service contracts rather than discrete equipment purchases.
Product Type:
Upgrade cycles across European and Chinese industrial corridors are accelerating replacement demand for legacy scrubber and carbon systems with lower-energy biological alternatives.
- Biofilters:Engineered packed-bed systems use microbial colonies to degrade hydrogen sulfide and volatile organic compounds through aerobic respiration. Municipal composting operators in Germany and food processors across the Yangtze River Delta are prioritizing biofilter installations to meet MEE and EU Green Deal emission ceilings while cutting natural gas consumption.
- Chemical Scrubbers:Packed-tower or spray-chamber designs deploy proprietary caustic or oxidizing chemistries to neutralize acid gases and reduced sulfur compounds. Pulp and paper mills in the United States retain scrubber dominance where EPA MACT standards enforce continuous treatment of high-concentration hydrogen sulfide streams that overwhelm biological systems.
- Ozone Generators:Corona discharge or UV-based systems produce ozone for oxidative destruction of odor molecules in low-humidity environments.
- Activated Carbon Systems:Fixed-bed or canister configurations adsorb contaminants onto coconut shell or coal-based carbon media, generating recurring replacement revenue in intermittent-load chemical processing.
Biofilters sit at the top of the volume ranking, with chemical scrubbers climbing the fastest in high-sulfur industrial applications.
Technology:
Process selection hinges on contaminant destruction efficiency targets versus operational expenditure constraints across municipal and private facility portfolios.
- Adsorption:Physical binding of odor molecules onto high-surface-area media, primarily activated carbon or zeolites, achieves removal without chemical transformation. REACH and F-Gas Regulation restrictions on fluorinated compounds are compressing supplier certification timelines for carbon regeneration services in EU member states.
- Absorption:Mass transfer of gases into liquid scrubbing solutions enables continuous treatment of high-flow, high-concentration streams. Chemical scrubber absorption dominates pulp and paper applications where sulfur compound loads exceed biological system tolerance thresholds.
- Oxidation:Thermal or photochemical destruction converts odor compounds to carbon dioxide, water, and inorganic byproducts. Food manufacturers are migrating from thermal oxidation to biological oxidation to reduce energy expenditure and carbon footprint reporting burdens.
- Neutralization:Acid-base or redox reactions in wet scrubbing systems chemically transform malodorous species into non-volatile salts or less offensive compounds.
Absorption commands the largest installed base, though oxidation is expanding most quickly in energy-sensitive food processing environments.
Application:
Facility type dictates contaminant complexity, regulatory scrutiny intensity, and acceptable technology capital expenditure ranges.
- Waste Treatment Plants:Municipal anaerobic digesters and composting facilities generate concentrated hydrogen sulfide, ammonia, and mercaptan emissions requiring robust biological or chemical treatment. Germany, the United States, and India are expanding biofilter installations to comply with tightening ambient air quality directives.
- Food Processing Units:Rendering, fermentation, and cooking operations produce variable organic sulfur and nitrogen compound loads. These facilities prioritize biofiltration over thermal oxidation to reduce operational expenditure and natural gas price exposure.
- Pulp and Paper Mills:Kraft pulping and recovery boiler operations emit high-concentration reduced sulfur compounds that demand reliable continuous chemical scrubbing.
- Textile Manufacturing:Dyeing, finishing, and coating processes release volatile organic compounds and formaldehyde requiring adsorption or oxidation treatment.
Waste treatment plants anchor the application volume ranking, with food processing units gaining share fastest on energy transition priorities.
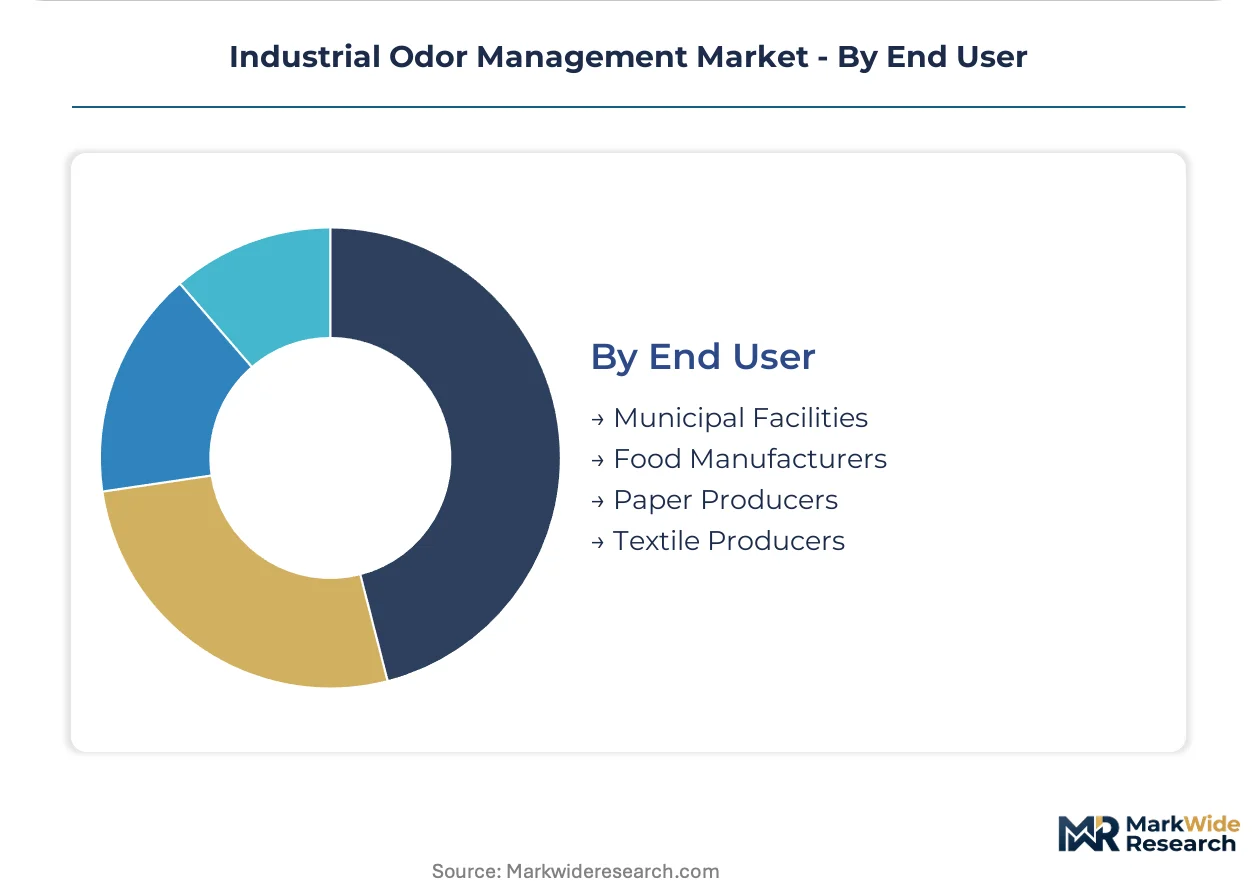
End User:
Ownership structure shapes procurement modality, with municipal entities favoring long-term service contracts and industrial operators retaining equipment purchase authority.
- Municipal Facilities:Public wastewater treatment and solid waste composting operations operate under political accountability for community odor complaints and regulatory compliance. Germany's municipal sector shows pronounced migration toward 10-15 year operational expenditure models bundling water and air treatment.
- Food Manufacturers:Private sector processors balance brand protection, worker safety, and energy cost management in technology selection. These end users are driving biofilter demand expansion as they seek lower-energy alternatives to thermal oxidizers.
- Paper Producers:Integrated pulp and paper mills maintain captive chemical scrubber infrastructure for high-sulfur process streams.
- Textile Producers:Dyeing and finishing houses face increasing MEE odor emission limits in China's manufacturing clusters, creating certified equipment demand.
Municipal facilities occupy the top volume position, while food manufacturers are expanding most quickly on energy cost reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Environmental engineers and air quality specialists cluster in Germany, the United States, and China's Yangtze River Delta, anchoring the industry's geographic talent concentration.
United States
Pulp and paper mills along the Gulf Coast and municipal wastewater facilities in the Midwest drive scrubber and biofilter procurement. EPA MACT standards compel continuous treatment upgrades for high-sulfur process streams. Houston's petrochemical corridor sustains demand for chemical scrubber installations meeting federal emission ceilings.
Germany
Municipal composting operators and automotive coating facilities anchor biofilter and oxidation system demand. EU Green Deal emissions targets compress replacement cycles for legacy infrastructure. Bavaria's municipal sector leads migration toward 10-15 year bundled service contracts covering water and air treatment.
China
Pharmaceutical manufacturers and chemical processors in the Yangtze River Delta generate certified equipment demand. MEE odor emission limits for manufacturing clusters reshape supplier certification timelines. Shanghai's chemical corridor sees accelerated biofilter adoption as facilities seek lower-energy alternatives to thermal oxidation.
India
Municipal wastewater expansion in Delhi-NCR and industrial zones around Mumbai drives biofilter installations. Stricter ambient air quality directives compel treatment upgrades at anaerobic digesters. Gujarat's specialty chemical belt attracts scrubber system deployments for high-concentration sulfur compound streams.
Japan
Food processing facilities in the Kansai region and electronics manufacturers in Chubu prioritize energy-efficient biological treatment. METI industrial emissions guidelines influence technology selection for odor control infrastructure. Osaka's fermentation and rendering operations exemplify migration from thermal oxidizers to biofiltration systems.
Industrial Odor Management Market Competitive Landscape
Capital-heavy equipment fabricators compete with asset-light technology licensors across the odor management value chain. The vendor base separates between integrated environmental service conglomerates and specialized oxidation system manufacturers. Three archetypes dominate: diversified water-air treatment providers, dedicated air pollution control specialists, and regional fabrication houses serving local certification requirements. Competitive positioning hinges on long-term service contract capture and geographic certification breadth rather than equipment differentiation alone.
Among diversified environmental service providers, Ecolab and Veolia occupy positions bundling water and air treatment under unified operational expenditure models. Dürr Group anchors the specialized oxidation tier with focused expertise in industrial coating applications. These three entities exemplify contrasting strategic postures: integrated portfolio breadth versus deep vertical specialization in high-performance destruction systems.
| Leading Market Players |
|---|
| Ecolab |
| Veolia |
| DuPont |
| Dürr Group |
| Xylem |
| Anguil Environmental Systems |
| Catalytic Products International |
| Tholander Ablufttechnik |
| OMI Industries |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between MEE-compliant systems and legacy equipment manifests in both pricing premiums and supplier qualification timelines. Municipal buyers in Germany absorb higher lifecycle costs through 10-15 year bundled service contracts, while industrial operators in China's Yangtze River Delta face compressed procurement cycles that favor standardized biofilter configurations over customized oxidation systems.
Pricing Analysis
Bundled water-air treatment contracts command premium positioning against unbundled equipment-only transactions. Project-based pricing dominates municipal procurement in Germany and the United States, where 10-15 year operational expenditure models separate Ecolab and Veolia from fabrication-only competitors. Price differentiation hinges on certification breadth—MEE compliance for Chinese pharmaceutical clusters and EU Green Deal alignment for automotive coating applications—and geographic delivery cost differentials from Southeast Asian carbon media suppliers. Cost compression in standard biofilter vessels is intensifying because domestic Chinese fabricators are expanding vessel production capacity. Municipal wastewater operators show highest price sensitivity due to political budget constraints, while pharmaceutical manufacturers in Shanghai's chemical corridor prioritize certification speed over capital expenditure minimization.
Supply Chain Analysis
Direct-to-municipal channels handle hyperscale biofilter demand from Germany's composting operators and India's Delhi-NCR wastewater expansion. Coconut shell activated carbon production clusters in Indonesia, Sri Lanka, and the Philippines create input cost volatility for intermittent-load chemical processing applications. Raw material dependencies center on specialized packing media for biofiltration, proprietary caustic formulations for chemical scrubbers, and fluorinated membrane materials facing REACH and F-Gas Regulation restrictions. Single-source vulnerability concentrates in coconut shell carbon regeneration services, where EU supplier certification timelines have compressed following regulatory chemical bans. Distribution runs through integrated environmental service conglomerates for municipal accounts and regional fabrication houses for industrial retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
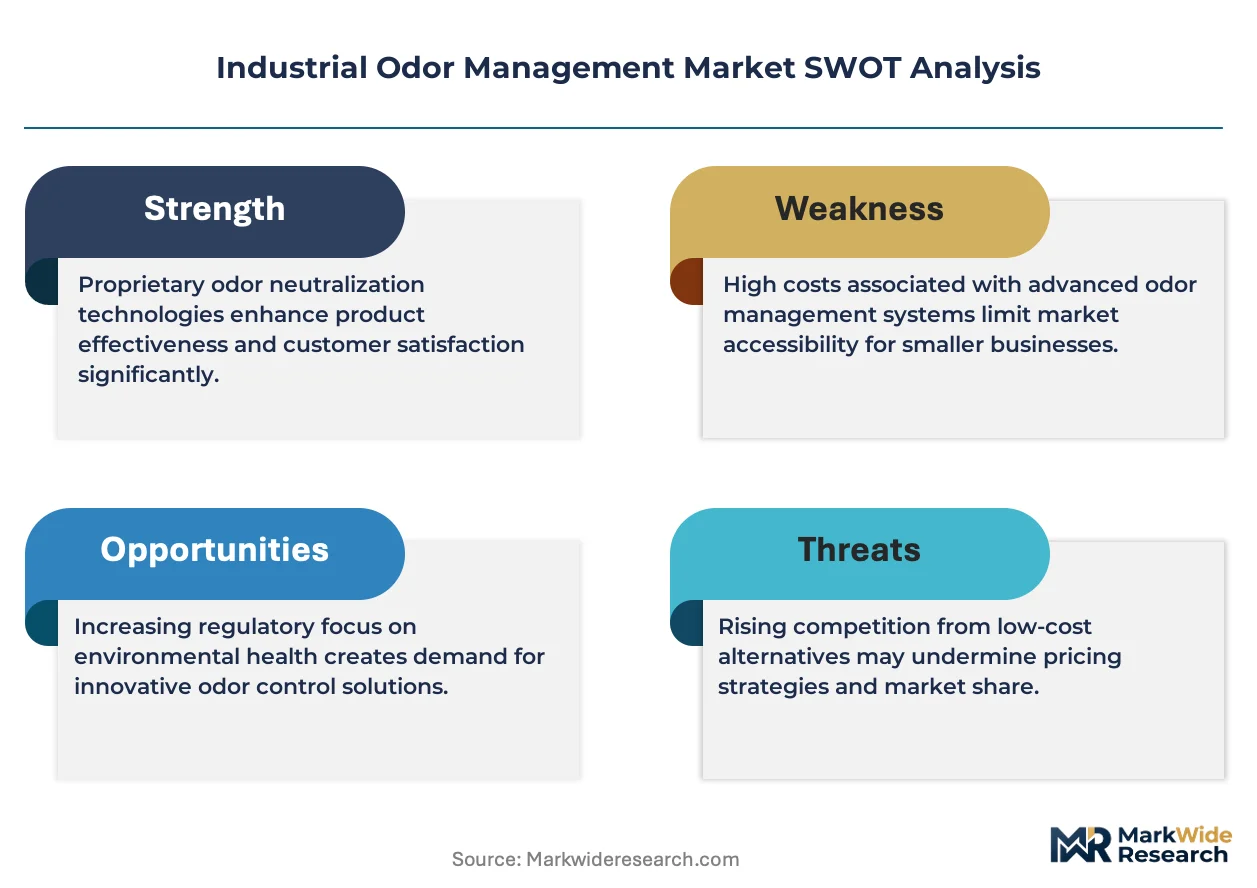
This market reads as a late-cycle quality story, with procurement gravity shifting toward certified equipment suppliers capable of navigating MEE odor emission limits and EU Green Deal compliance timelines. Premium specifications now dominate buyer evaluation criteria over pure capital expenditure minimization.
For Market Incumbents: Deepen vertical integration into coconut shell carbon regeneration capacity to defend margin position against Southeast Asian supply volatility. Expand MEE certification services for pharmaceutical manufacturing corridors in China's Yangtze River Delta, where domestic suppliers currently underserve certified equipment demand. Prioritize R&D bandwidth for PFAS-free scrubber formulation reformulation ahead of phased regulatory bans. For New Entrants and Emerging Players: Small-scale food processors in Japan's Kansai region represent an underserved buyer archetype seeking lower-energy biofiltration alternatives without thermal oxidation infrastructure. Target municipal composting operators in India's Gujarat specialty chemical belt with standardized biofilter configurations that compress installation timelines versus custom oxidation systems. Pursue technology licensing partnerships with established packing media suppliers to bypass captive distribution channels controlled by integrated service providers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized oxidation system manufacturers possessing automotive coating application expertise and EU Green Deal compliance track records. Long-term viability over a 5-10 year window favors asset-light technology licensors over capital-heavy vessel fabricators exposed to Chinese domestic competition. Watch for inflection in EPA MACT enforcement intensity along the US Gulf Coast pulp and paper corridor, where upgrade contract velocity signals regulatory compliance urgency.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Reformulation | REACH and F-Gas Regulation restrictions force urgent chemistry replacement in scrubber and membrane applications. |
| MEE Certification Expansion | Shanghai's pharmaceutical corridor generates certified equipment demand that domestic Chinese suppliers currently underserve. |
| Biofilter-UV Hybrid Development | Combining biological degradation with photocatalytic oxidation addresses variable contaminant loads in food processing environments. |
| Long-Term Service Agreement Capture | Germany's municipal sector shows pronounced migration toward 10-15 year operational expenditure models bundling water and air treatment. |
| Coconut Shell Carbon Regeneration Investment | Southeast Asian supply concentration creates input cost volatility for activated carbon systems in intermittent-load chemical processing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing and growth trajectory assumptions. Primary fieldwork engaged plant engineers at municipal wastewater facilities, procurement leads at pulp and paper mills, technical R&D directors at biofilter packing media suppliers, and aftermarket service heads at integrated environmental service providers. Secondary validation drew from EPA MACT enforcement records, EU ETS emissions disclosure databases, China MEE odor emission limit notifications, and customs data tracking activated carbon import flows. Bottom-up vessel fabrication capacity estimates were cross-checked against top-down municipal procurement budget allocations.
Segment-weighting approaches modeled technology type, application vertical, and end-user ownership structure across the projection horizon. The analytical framework incorporated contaminant destruction efficiency thresholds, energy expenditure constraints, and regulatory compliance timeline compression. CAGRs were derived from facility-level upgrade cycle analysis and supplier order backlog trajectories. Industry-specific forecast inputs included natural gas price exposure for thermal oxidation displacement trends and coconut shell carbon spot price volatility indices.
Underlying measurement precision varies by segment; municipal wastewater application data carries tighter precision than emerging pharmaceutical manufacturing corridor estimates. Forecasts reflect assumptions regarding EPA enforcement continuity, EU Green Deal implementation pace, and MEE certification timeline stability. Periodic stress-testing of base assumptions is recommended given regulatory restriction acceleration for PFAS compounds and fluorinated materials.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.